
 Male Hypogonadism Market | 2026-2036
Male Hypogonadism Market Size, Share, and Industry Trends Forecast 2026-2036
Male Hypogonadism Market Outlook
North American manufacturing capacity for testosterone APIs and finished dosage forms is fragmenting as compounders and specialty manufacturers enter the space. AbbVie leverages its established AndroGel brand equity and physician relationships to sustain high prescription loyalty. Bayer AG anchors European supply through its Berlin-based hormone production network. Eli Lilly and Company competes via differentiated delivery science and urology-focused commercial teams.
Male hypogonadism denotes a clinical syndrome resulting from testicular failure to produce adequate testosterone, typically confirmed when morning serum total testosterone falls below 300 ng/dL on two separate measurements, with symptoms spanning fatigue, reduced libido, and decreased bone mineral density. Injectable testosterone formulations occupy the largest volume share due to decades of clinical familiarity and lower per-dose cost, while transdermal gels command premium positioning through convenience-driven adherence advantages among working-age patients. Specialty pharmacies represent the fastest-growing distribution channel as manufacturers route high-touch therapies through limited networks that manage prior authorization and patient monitoring.
FDA risk evaluation and mitigation strategies govern testosterone labeling, post-market surveillance, and prescriber certification requirements, directly constraining market access and promotional claims. The Drug Enforcement Administration's Schedule III classification of testosterone imposes dispensing limits, storage standards, and transaction reporting that shape channel economics and inventory planning. Stakeholders must monitor evolving cardiovascular outcome data and corresponding label revisions that could abruptly recalibrate risk-benefit conversations with prescribers and payers.
Market Dynamics
FDA cardiovascular safety monitoring and DEA Schedule III controls are compressing prescriber autonomy while specialty pharmacy networks capture margin from traditional retail channels. These intersecting forces are restructuring how testosterone therapies reach patients and how manufacturers defend formulary access.
Growth Catalysts
- Aging Demographics:The US Census Bureau projects sustained expansion of men aged 45-64, the primary diagnostic cohort for late-onset hypogonadism. This demographic tailwind sustains addressable patient pools regardless of treatment modality shifts.
- Specialty Pharmacy Networks:Limited distribution channels manage prior authorization complexity and adverse event reporting. These networks improve adherence metrics that manufacturers leverage in payer negotiations.
- Bone Health Awareness:Endocrinology guidelines increasingly link testosterone deficiency to osteoporosis and fracture risk. This indication expansion broadens prescriber base beyond urology into metabolic medicine.
Market Restraints
- DEA Schedule III Classification:Storage, dispensing limits, and transaction reporting impose inventory carrying costs and audit exposure on pharmacies. These compliance burdens constrain channel expansion into general retail.
- Cardiovascular Outcome Uncertainty:Inconclusive heart attack and stroke data from observational studies chill prescriber enthusiasm. FDA-mandated label warnings amplify liability concerns in primary care settings.
- Injectable Cost Compression:Generic testosterone cypionate and enanthate formulations commoditize the highest-volume delivery route. Reimbursement pressure on these products drags pricing across the category.
Strategic Opportunities
- Subcutaneous Autoinjector Formats:Self-administration devices reduce clinic dependency and expand addressable geography to rural and underserved areas. These formats command premium pricing through convenience differentiation.
- Telemedicine Protocols:Remote testosterone monitoring and prescription renewal models bypass traditional urology clinic bottlenecks. Regulatory clarity on telehealth prescribing creates channel expansion headroom.
- Oral Testosterone Undecanoate:Non-invasive delivery eliminates transference risk and application site reactions that limit transdermal adoption. Hepatic safety profiles and food-effect requirements define competitive positioning.
Industry Challenges
- REMS Compliance Architecture:FDA risk evaluation mandates require real-world evidence collection and prescriber certification systems. These infrastructure investments strain mid-scale manufacturers without established pharmacovigilance operations.
- Reimbursement Prior Authorization:Payers increasingly demand documented morning testosterone levels below threshold on two separate dates. Claims denial rates and appeals processing consume specialty pharmacy operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Male Hypogonadism Market |
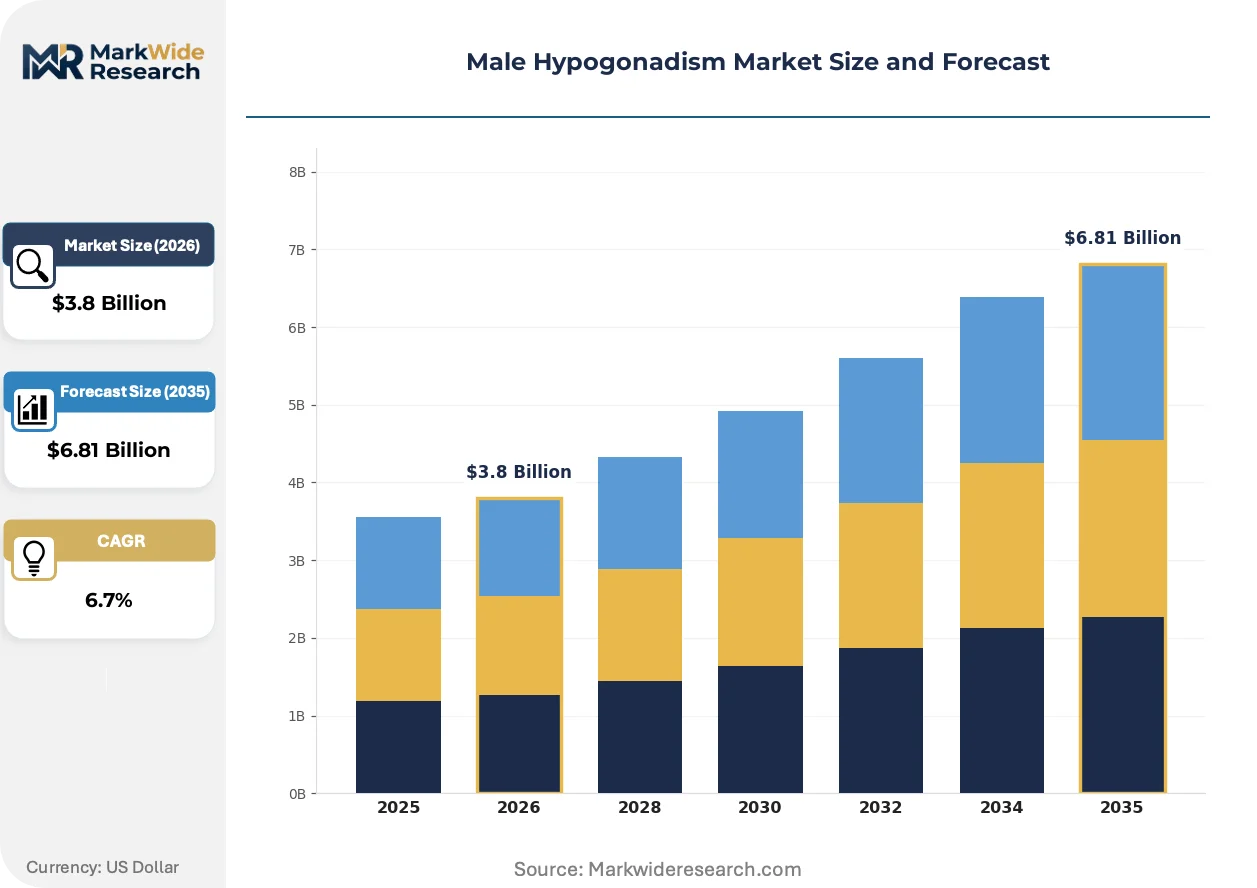
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Testosterone, Transdermal Patches, Gels, Pellets End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Therapy Area: Andrology, Urology, Primary Care, Hormone Replacement Distribution Channel: Retail Pharmacy, Online Pharmacy, Institutional Pharmacy, Wholesalers |
| Companies Covered | Merck, AbbVie, Besins Healthcare, Teva Pharmaceutical Industries, Eli Lilly and Company, Bayer AG, Endo Pharmaceuticals, Ferring, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Male Hypogonadism Market Strategic Shifts
Delivery science convergence and regulatory data requirements are forcing manufacturers to integrate digital adherence tools with physical product formats. These developments compress development timelines while expanding post-market surveillance obligations.
Long-acting testosterone undecanoate intramuscular injections extend dosing intervals to ten weeks, reducing clinic visit burden for working patients. Urology practices with high-volume testosterone protocols are adopting these formulations to improve scheduling efficiency. The technology is hybridizing convenience expectations across injectable and transdermal categories, pressuring gel manufacturers to demonstrate adherence advantages beyond application simplicity.
FDA's evolving cardiovascular safety communication framework requires manufacturers to maintain active surveillance databases and prescriber education modules. This regulatory architecture elevates compliance costs for market entrants without established risk management infrastructure. Established manufacturers with dedicated REMS teams are consolidating prescriber relationships through certified education programs that smaller competitors cannot replicate.
Patient self-advocacy through direct-to-consumer laboratory testing is shortening diagnostic pathways and bypassing traditional primary care gatekeeping. Men with symptomatic complaints are presenting to specialists with prior testosterone results, compressing the evaluation timeline. This behavioral shift concentrates demand in states with permissive direct-access testing regulations and established specialty pharmacy density.
Male Hypogonadism Market Segmentation
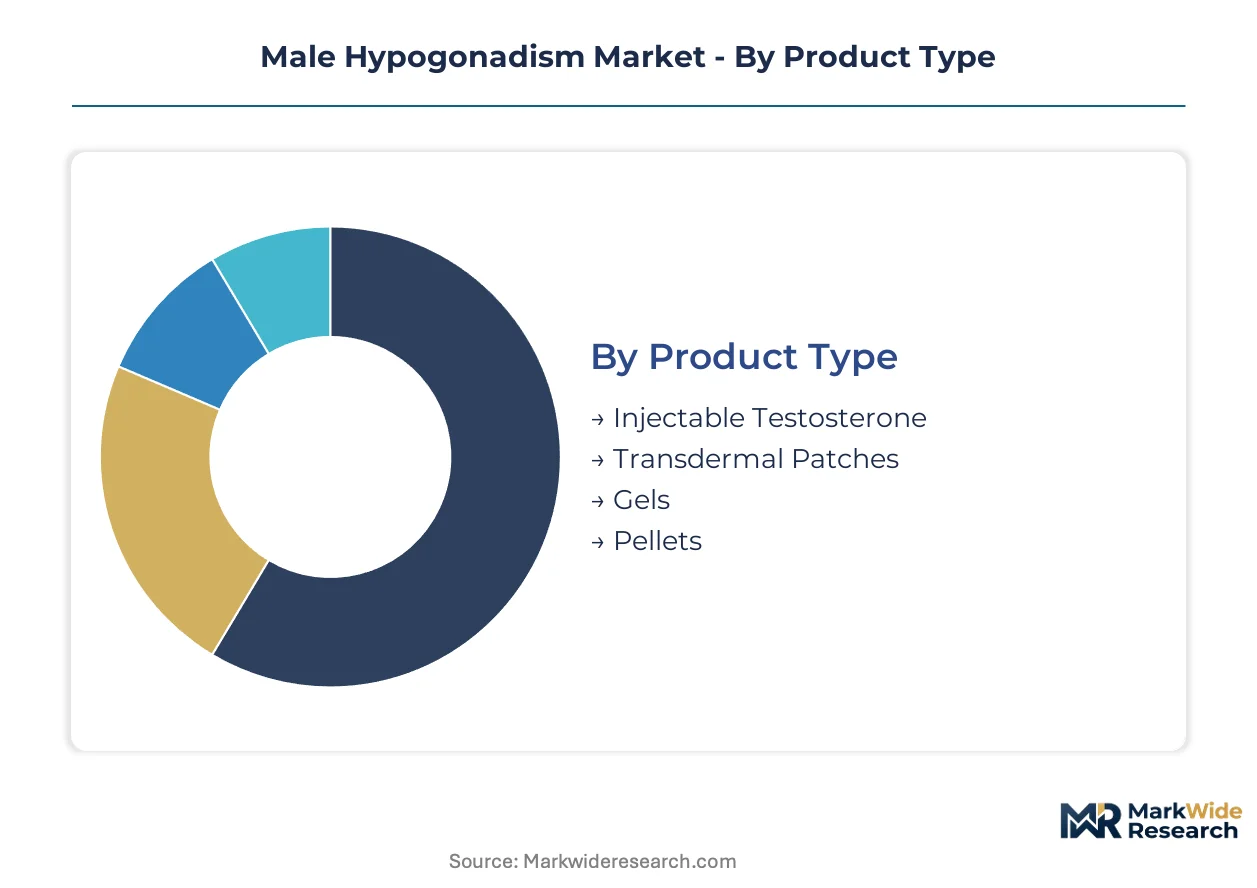
Segmentation in the male hypogonadism market reveals how delivery science, prescriber specialization, and channel economics partition patient access. Manufacturers configure commercial strategies around these fault lines to defend formulary position and capture adherence premiums.
Product Type:
After-sales intensity varies sharply across delivery formats, with injectable formulations demanding clinical administration support while transdermal options require patient education on application protocols and transference avoidance.
- Injectable Testosterone:Intramuscular testosterone cypionate and enanthate formulations dominate prescription volumes through established reimbursement pathways and lower per-dose acquisition costs. Demand concentrates in urology and endocrinology practices managing high-volume testosterone protocols, though clinic dependency limits rural access.
- Transdermal Patches:Reservoir and matrix patch designs deliver steady-state testosterone absorption with 24-hour wear cycles. Adoption clusters among working-age patients in the United States prioritizing convenience over cost, with FDA label warnings on skin irritation constraining first-line positioning.
- Gels:Hydroalcoholic testosterone gels enable rapid drying and minimal residue, commanding premium pricing through AbbVie's AndroGel brand equity.
- Pellets:Subcutaneous testosterone implants provide three-to-six-month dosing intervals, appealing to patients averse to frequent injections or daily applications.
Injectable testosterone holds the largest share; momentum sits with transdermal gels as convenience premiums justify reimbursement negotiations.
End User:
Cost tier stratification separates institutional settings with bundled reimbursement from retail channels where prior authorization complexity determines access.
- Hospitals:Academic medical centers and community hospitals manage complex hypogonadism cases with comorbid cardiovascular risk, requiring multidisciplinary endocrinology-cardiology coordination. Demand concentrates in tertiary referral networks with established testosterone monitoring protocols.
- Clinics:Urology and men's health clinics drive diagnostic volumes through targeted screening programs and direct-to-consumer marketing partnerships.
- Homecare Settings:Self-administration of subcutaneous testosterone autoinjectors expands addressable geography beyond clinic catchment areas.
- Specialty Pharmacies:Limited distribution networks manage REMS compliance, adverse event reporting, and prior authorization processing for branded therapies.
Specialty pharmacies are gaining share fastest; hospitals retain the highest absolute prescription volumes through integrated care pathways.
Therapy Area:
Application focus determines prescriber training requirements and label indication breadth, with andrology and urology maintaining tighter testosterone protocol standardization than primary care.
- Andrology:Male reproductive medicine specialists manage hypogonadism within fertility preservation contexts, emphasizing spermatogenesis preservation alongside testosterone restoration.
- Urology:Urologists dominate testosterone prescribing through prostate health monitoring integration and established relationships with specialty pharmacy networks.
- Primary Care:General practitioners screen symptomatic men but increasingly defer initiation to specialists amid cardiovascular liability concerns.
- Hormone Replacement:Endocrinologists coordinate testosterone therapy within broader metabolic syndrome management, linking deficiency to bone density and glycemic control outcomes.
Urology holds the largest share; momentum sits with hormone replacement as metabolic comorbidity linkages broaden the prescriber base.
Distribution Channel:
Channel margin structures reflect inventory carrying costs for Schedule III controlled substances and the operational burden of REMS documentation requirements.
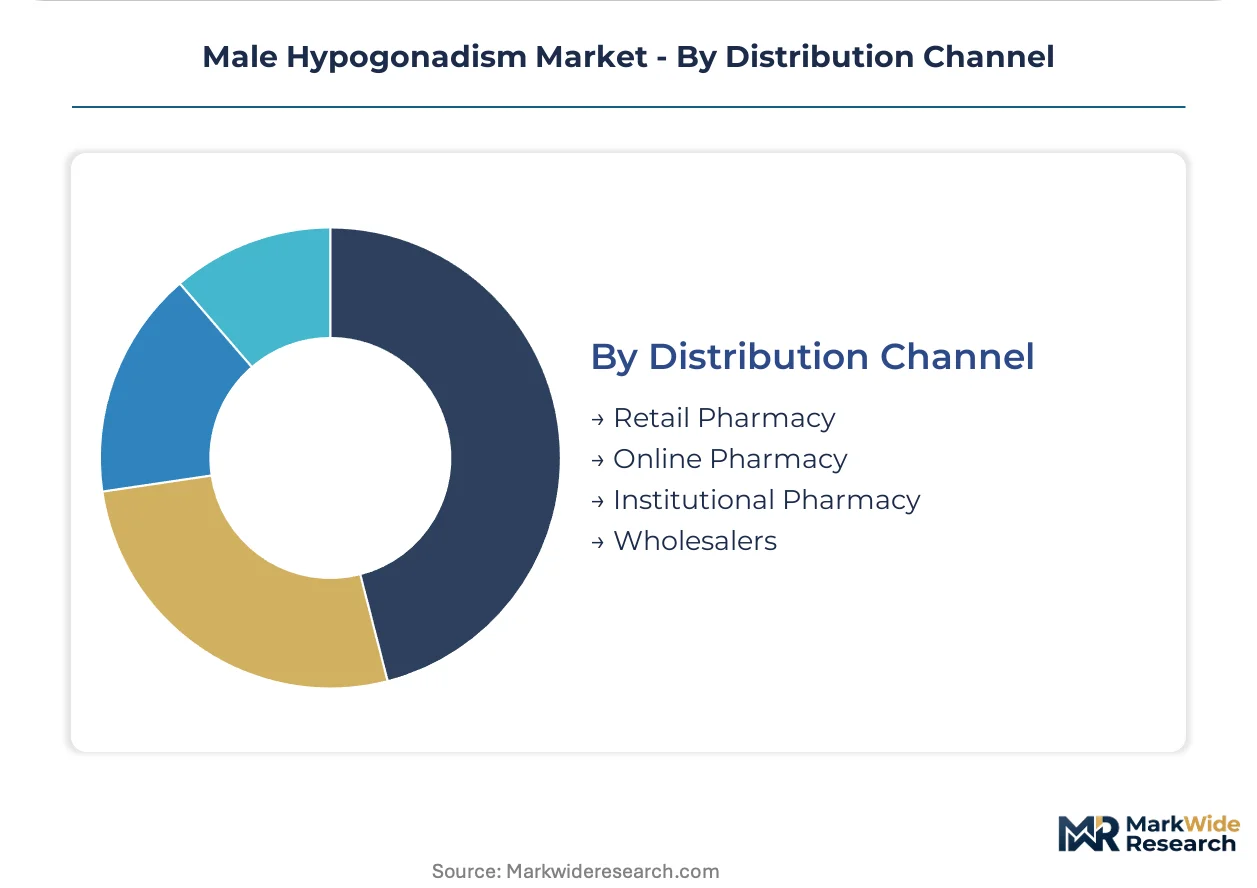
- Retail Pharmacy:Chain and independent pharmacies dispense generic testosterone cypionate with limited patient support services, competing primarily on co-pay differentials.
- Online Pharmacy:Telehealth-integrated platforms enable remote testosterone monitoring and prescription renewal, expanding fastest in states with permissive direct-access testing regulations.
- Institutional Pharmacy:Hospital-owned pharmacies manage inpatient testosterone initiation and discharge coordination for complex cases.
- Wholesalers:Cardinal Health, McKesson, and AmerisourceBergen distribute testosterone APIs and finished dosage forms under DEA quota and transaction reporting requirements.
Retail pharmacy holds the largest share; online pharmacy is climbing the fastest as telemedicine protocols mature and regulatory clarity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA protocols govern the dominant geography where diagnostic rates and specialty pharmacy density concentrate treatment volumes. Regulatory divergence across developed markets fragments commercial strategies for testosterone replacement therapies.
United States
Aging male demographics and direct-to-consumer laboratory testing sustain diagnostic volume expansion. FDA risk evaluation and mitigation strategies constrain promotional claims and mandate prescriber certification systems. Specialty pharmacy networks in Florida, Texas, and California manage prior authorization complexity for branded therapies.
Germany
Endocrinology guideline integration with metabolic syndrome management broadens prescriber participation beyond urology. EMA centralized procedures govern testosterone product approvals while national reimbursement negotiations determine access tiers. Berlin anchors European hormone API production through Bayer AG's established manufacturing infrastructure.
United Kingdom
National Health Service testosterone prescribing protocols emphasize documented morning serum thresholds and cardiovascular risk stratification. MHRA post-market surveillance requirements align with EMA cardiovascular safety communications. London and Manchester academic medical centers coordinate multidisciplinary hypogonadism management pathways.
Japan
PMDA regulatory frameworks impose distinct efficacy endpoints and dosing regimen requirements for testosterone approvals. Aging demographics and workplace productivity concerns sustain employer-sponsored screening programs. Tokyo and Osaka metropolitan areas concentrate urology specialist density and specialty pharmacy distribution.
Australia
TGA scheduling controls and importation restrictions shape testosterone product availability and pricing structures. PBS reimbursement listing processes demand robust cardiovascular safety evidence packages. Sydney and Melbourne clinical networks drive diagnostic protocol standardization and prescriber education initiatives.
Male Hypogonadism Market Competitive Environment
Capability concentration sits with established pharmaceutical manufacturers possessing dedicated REMS infrastructure; scale advantage sits with diversified healthcare conglomerates leveraging broad therapeutic portfolios. The market structure tiers between legacy hormone specialists with prescriber relationship depth and diversified players with payer negotiation leverage. Three archetypes dominate: vertically integrated API-to-finished-dose manufacturers, specialty therapeutics divisions of major pharma, and regional hormone-focused licensees. Competitive moves center on specialty pharmacy network exclusivity arrangements and cardiovascular outcomes data generation for label differentiation.
Among the established hormone therapeutics specialists, AbbVie, Bayer AG, and Eli Lilly and Company occupy positions defined by delivery format diversification and prescriber certification program ownership. AbbVie represents the transdermal gel archetype with brand equity accumulated through sustained physician engagement. Bayer AG anchors European supply chain reliability through captive API production. Eli Lilly and Company exemplifies urology-focused commercial infrastructure with differentiated administration science portfolios.
| Leading Market Players |
|---|
| Merck |
| AbbVie |
| Besins Healthcare |
| Teva Pharmaceutical Industries |
| Eli Lilly and Company |
| Bayer AG |
| Endo Pharmaceuticals |
| Ferring |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Air freight corridors linking Frankfurt and Chicago impose differential cost burdens that amplify price spreads between European-sourced testosterone APIs and finished formulations distributed through US specialty pharmacy networks. These logistics premiums compound with DEA Schedule III compliance costs to stratify pricing across branded transdermal gels, generic injectables, and compounded alternatives.
Pricing Analysis
Geographic price spreads between North American and European markets exceed those within either region, reflecting divergent reimbursement frameworks and regulatory compliance burdens. The market operates on a three-tier pricing structure across premium branded gels, standard generic injectables, and economy compounded formulations. Price differentiation rests on delivery convenience, prescriber certification requirements, and adverse event monitoring bundling. Cost compression in generic testosterone cypionate is intensifying because of formulary tiering and mail-order pharmacy substitution. Primary care prescribers exhibit highest price sensitivity due to reimbursement pressure and liability concerns, while urology specialists prioritize adherence metrics over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Catalent, Patheon, and Siegfried Holding for testosterone API synthesis and finished dose production. Active pharmaceutical ingredient supply concentrates in Germany, Switzerland, and the United States, with Italian and Spanish facilities handling secondary packaging for European distribution. Raw material dependencies include soy-derived sterol precursors, organic solvents for extraction, and specialized excipients for transdermal matrix formulations. Single-source vulnerability characterizes long-acting testosterone undecanoate production, where proprietary esterification technology limits qualified supplier pools. Distribution runs through DEA-registered wholesale distributors with Schedule III quota allocation, then into limited specialty pharmacy networks managing REMS documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as prescriber specialization splinters demand across urology, endocrinology, and emerging telemedicine channels. Direct-to-consumer diagnostic testing is creating addressable niches for differentiated delivery formats and remote monitoring services.
For Market Incumbents: Harden prescriber certification program ownership against emerging oral testosterone undecanoate entrants by embedding digital adherence tools within existing gel and autoinjector portfolios. Deepen captive API supply through backward integration into sterol precursor sourcing, insulating margin position from commodity feedstock volatility. Consolidate specialty pharmacy network exclusivity arrangements before telemedicine platforms achieve regulatory clarity on interstate prescribing.
For New Entrants and Emerging Players: Rural and underserved metropolitan corridors in the United States Southeast and Mountain West represent the most penetrable geography, where urology specialist density lags diagnostic demand. Target subcutaneous autoinjector formats for these regions, leveraging self-administration to bypass clinic dependency. Pursue direct-to-consumer laboratory testing partnerships as the primary go-to-market angle, compressing diagnostic pathways and capturing patients before traditional gatekeeping channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized hormone manufacturing infrastructure and dormant prescriber relationships. Long-term viability across the analysis window hinges on cardiovascular outcomes data generation capabilities and REMS compliance architecture ownership. Monitor FDA label revision timelines as the critical inflection signal, with corresponding prescriber sentiment shifts determining category growth trajectories. Quarterly review of formulary exclusion lists and prior authorization denial rate trends is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | Establishes compliance moats that smaller competitors cannot replicate under FDA-mandated surveillance requirements. |
| Specialty Pharmacy Network Exclusivity | Captures margin from traditional retail through limited distribution arrangements managing prior authorization complexity. |
| Subcutaneous Autoinjector Development | Expands addressable geography to rural populations while commanding premium pricing through convenience differentiation. |
| Cardiovascular Outcomes Data Generation | Supports label differentiation and liability defense amid evolving FDA safety communication frameworks. |
| Telemedicine Protocol Integration | Bypasses traditional urology clinic bottlenecks in states with permissive direct-access testing regulations. |
Study Parameters
Initial hypotheses were tested against primary input from urology practice administrators, specialty pharmacy operations directors, endocrinology clinic directors, and payer formulary managers, then refined through secondary validation. FDA filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and DEA quota allocation records anchored quantitative demand modeling. Bottom-up prescription volume triangulation against top-down manufacturer revenue disclosures ensured segmentation integrity across delivery formats and prescriber specialties.
Demand-supply-balance framing governed the analytical approach, with patient flow modeling from diagnosis through therapy initiation and persistence tracking across the projection horizon. Segmentation dimensions included administration route, prescriber specialty, distribution channel type, and regional regulatory cluster. CAGRs derived from patient population expansion, treatment rate assumptions, and pricing trajectory modeling. Testosterone monitoring protocol adoption curves and specialty pharmacy network penetration rates served as key forecast inputs.
Practitioners should monitor cardiovascular safety study readouts, DEA scheduling reclassification proposals, and state-level telemedicine prescribing legislation for early signals requiring forecast revision. Regulatory label changes, generic entry events, and reimbursement tier adjustments constitute specific risk factors that could materially alter trajectory assumptions. Quarterly review of FDA advisory committee calendars and CMS national coverage determination pipelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market