
 OTC Topical Drugs Market | 2026-2036
OTC Topical Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Topical Drugs Market Outlook
Pharmacist expertise in dermatological counseling is collapsing across community pharmacy networks, constraining consumer guidance for proper product selection. Johnson & Johnson leverages its heritage in skin science to sustain brand trust in analgesic and antifungal topicals. Bayer AG anchors its competitive stance through R&D intensity in hydrocortisone and anti-itch formulations. GSK plc differentiates via pharmacy-led distribution control across European and North American markets.
OTC topical drugs are non-prescription formulations applied to body surfaces, typically containing active pharmaceutical ingredients at concentrations between 0.5% and 5% in semisolid bases such as petrolatum or aqueous gels, designed for localized therapeutic action without systemic absorption. Their primary commercial purpose centers on enabling consumer-directed management of pain, pruritus, and superficial infections. Analgesic creams and gels command the largest revenue pool due to chronic musculoskeletal conditions in aging populations, while antifungal ointments represent the fastest-expanding category driven by rising athlete's foot and ringworm incidence in humid climates. Spray formulations capture disproportionate growth in convenience-oriented channels, though tubes retain dominant pharmacy shelf presence.
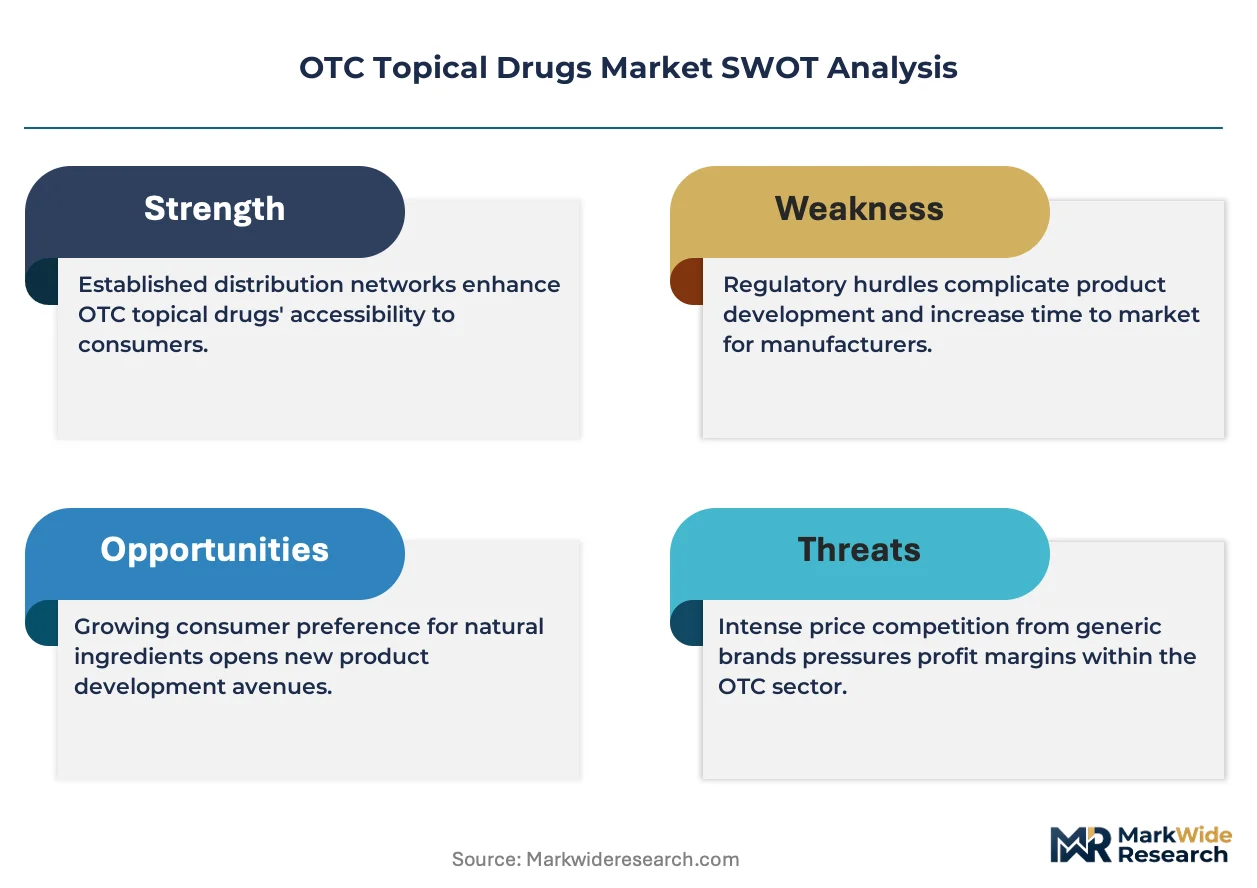
The FDA's OTC monograph reform program is accelerating ingredient safety reviews, forcing reformulations of longstanding topical actives. EMA's MDR framework imposes stricter clinical evidence thresholds for borderline cosmetic-therapeutic products entering European markets. China's NMPA has streamlined approval pathways for low-risk topical generics, reshaping competitive entry dynamics. Stakeholders must monitor regulatory divergence across FDA, EMA, and NMPA jurisdictions to anticipate reformulation costs and market access timelines.
Market Dynamics
The FDA's OTC monograph reform is forcing systematic reformulations of legacy active ingredients, compressing product development timelines while elevating compliance costs across formulation pipelines. This regulatory recalibration is restructuring competitive positioning between established incumbents and agile generics manufacturers.
Growth Catalysts
- Direct-to-consumer health spending:United States households allocate disproportionate budgets to self-managed dermatology, expanding addressable volume for analgesic and antifungal topicals without prescription gatekeeping.
- MDR framework harmonization:EMA's clinical evidence thresholds for borderline cosmetic-therapeutic products are clarifying market access rules, reducing regulatory uncertainty for compliant entrants.
- Pharmacy shelf expansion:Retail pharmacy chains are dedicating incremental linear footage to self-care dermatology sections, creating physical distribution advantages for stocked SKUs.
Market Restraints
- API concentration risk:Hydrocortisone and clotrimazole active pharmaceutical ingredients concentrate among Chinese and Indian bulk manufacturers, exposing formulators to supply disruption.
- Petrolatum price volatility:Semisolid base materials track crude oil derivatives, compressing margin stability for cream and ointment producers during energy price spikes.
- Substitution by cosmeceuticals:Unregulated cosmetic topicals with similar positioning claims capture price-sensitive consumers seeking skin condition management without pharmacy markup.
Strategic Opportunities
- Spray formulation whitespace:Convenience-oriented channels in Germany and France show underpenetration for metered-dose topical delivery versus tube-saturated pharmacy segments.
- NMPA streamlining:China's accelerated approval pathways for low-risk topical generics are shortening market entry timelines for compliant international applicants.
- Telehealth integration:Digital pharmacy platforms are creating new recommendation touchpoints where algorithmic skin assessment drives product selection.
Industry Challenges
- Pharmacist counseling erosion:Community pharmacy networks are reducing dermatological training investment, degrading consumer guidance quality at point of sale.
- Monograph compliance timelines:FDA's safety review acceleration demands simultaneous toxicology updates across multiple active ingredients, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Topical Drugs Market |
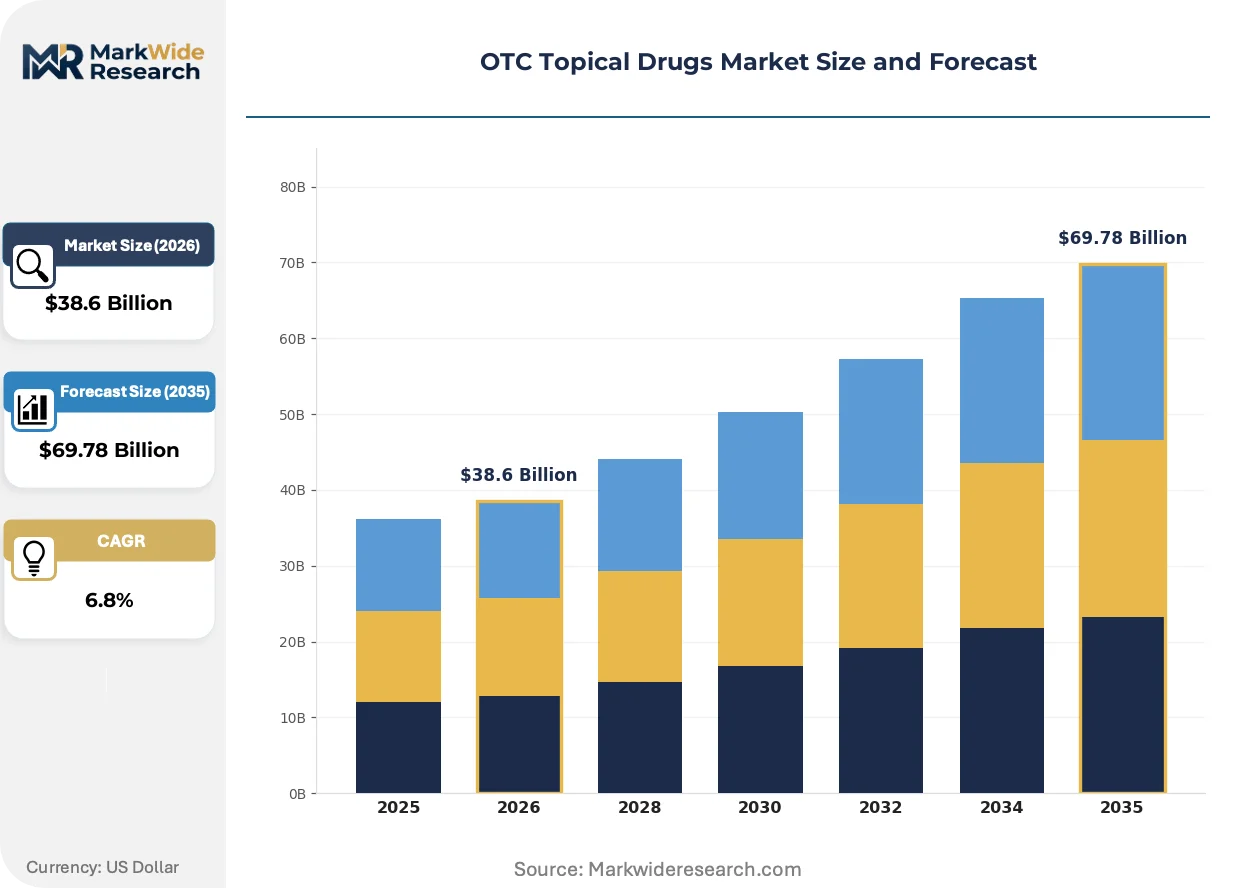
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antihistamines, Antibacterial, Antifungal Application: Pain Relief, Allergy Treatment, Skin Infection, Skin Irritation Formulation: Gels, Creams, Ointments, Sprays Packaging Type: Tubes, Bottles, Sachets, Jars |
| Companies Covered | Johnson & Johnson, Bayer AG, GSK plc, Bausch Health Companies Inc., Galderma, Novartis AG, Perrigo Company plc, Cipla, Hisamitsu Pharmaceuticals Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Topical Drugs Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation. Active ingredient delivery mechanisms are evolving toward enhanced skin penetration, while regulatory frameworks and purchasing behaviors are compressing traditional commercial pathways.
Microemulsion and nanostructured lipid carrier systems are supplanting conventional petrolatum-based matrices in premium topical development. Dermatology-focused contract manufacturers in Switzerland and South Korea are adopting these platforms at accelerating rates. The technology is supplanting legacy formulation approaches by enabling lower active concentrations with equivalent efficacy, reducing API costs and regulatory exposure simultaneously.
REACH authorization requirements for novel preservative systems are extending formulation development cycles by twelve to eighteen months. ECHA's stricter hazard classification protocols are forcing substitution of longstanding excipients in European-market products. Antifungal ointments with updated preservative suites are experiencing delayed launches in Germany, France, and the Netherlands as toxicology dossiers undergo extended review.
Subscription-based replenishment models are capturing chronic-condition users who previously purchased through episodic pharmacy visits. Digital-native topical brands are disintermediating traditional wholesale-pharmacy relationships through direct fulfillment. This behavioral pivot is most visible in United States urban markets where same-day delivery infrastructure supports just-in-time inventory for musculoskeletal pain management products.
OTC Topical Drugs Market Segmentation
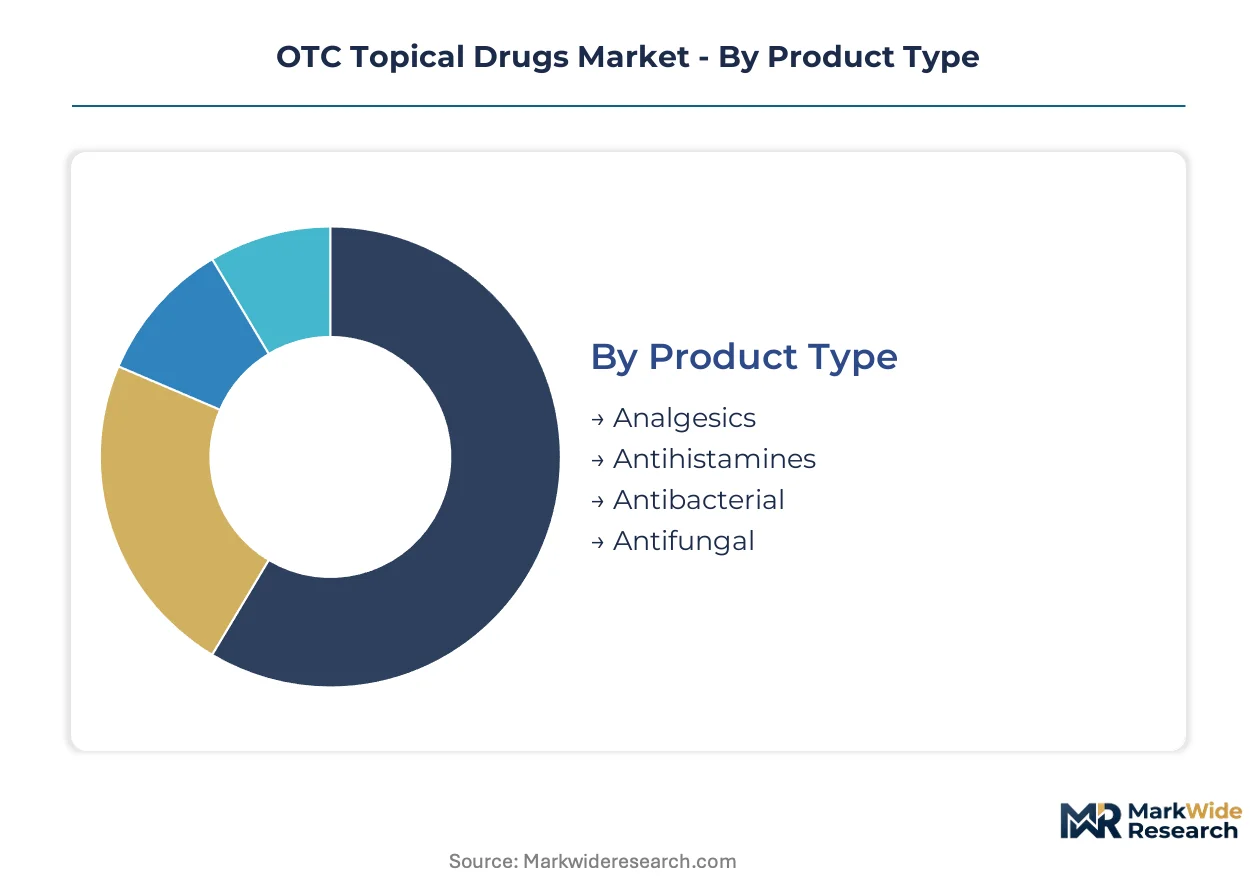
OTC topical drug manufacturers navigate distinct substitution pressures across product architectures, where cosmeceutical alternatives and prescription-to-OTC switches fragment demand pools. Segmentation discipline separates volume-stable categories from those facing margin compression through channel commoditization.
Product Type:
Substitution pressure intensifies most acutely in antihistamine and antibacterial segments, where unregulated cosmetic topicals with anti-itch or antimicrobial positioning capture price-sensitive consumers bypassing pharmacy markups.
- Analgesics:Formulations containing menthol, capsaicin, or salicylate esters in concentrations between 2% and 10%, designed for counterirritant and mild anti-inflammatory action. United States households with chronic musculoskeletal conditions drive disproportionate volume through retail pharmacy and mass-market channels, though telehealth-integrated digital platforms are capturing replenishment loyalty from episodic purchasers.
- Antifungal:Azole and allylamine-based actives such as clotrimazole and terbinafine in 1% concentrations, targeting dermatophyte infections. Humid climate zones in the southeastern United States and Gulf Coast metropolitan areas concentrate incidence-driven demand, with athlete's foot and ringworm prevalence expanding addressable volume faster than population growth alone would predict.
- Antihistamines:Topical diphenhydramine and doxylamine formulations for pruritus relief. Unregulated cosmetic alternatives with colloidal oatmeal or pramoxine positioning erode pharmacy channel preference among younger demographics seeking immediate retail access.
- Antibacterial:Bacitracin, neomycin, and polymyxin B combinations in petroleum-based carriers. First-aid kit bundling and private-label commoditization compress branded margin structures in mass retail.
Analgesics retain volume leadership; antifungal holds the steepest expansion curve.
Application:
Cost tier stratification separates acute episodic purchasers from chronic-condition subscribers, with pain relief commanding premium positioning while skin irritation management faces downward price pressure from cosmetic substitutes.
- Pain Relief:Musculoskeletal and neuropathic pain management through counterirritant and mild analgesic mechanisms. Aging demographic concentration in Florida, Arizona, and retirement corridor states sustains per-capita consumption above national averages, with pharmacy chains dedicating expanded linear footage to topical analgesic sections.
- Skin Infection:Bacterial and fungal superficial infection management requiring antimicrobial actives. Community pharmacy networks in Texas and California report elevated incidence consultation volumes, though pharmacist counseling erosion degrades proper product selection guidance at point of sale.
- Allergy Treatment:Contact dermatitis and urticaria symptom management. Seasonal pollen corridors through the Ohio River Valley and mid-Atlantic states drive geographic concentration of demand spikes.
- Skin Irritation:Minor burns, insect bites, and non-specific dermatitis. Mass-market retailers and convenience channels capture volume through lower-unit-price formats, constraining pharmacy-exclusive premium positioning.
Pain relief dominates revenue contribution; skin infection management climbs fastest on antimicrobial resistance awareness.
Formulation:
Volume concentration favors semisolid formats in established pharmacy channels, while spray architectures show underpenetration whitespace in convenience-oriented European markets.
- Creams:Oil-in-water emulsions with 15-40% lipid content, offering cosmetic elegance and rapid absorption. United States retail pharmacy chains stock creams as default formulations across analgesic and antifungal categories, with petrolatum price volatility compressing margin stability during energy market disruption.
- Gels:Aqueous or hydroalcoholic matrices with carbomer or cellulose thickeners, preferred for hair-bearing application sites. Sports medicine and fitness-oriented consumers in California and Colorado metropolitan markets drive disproportionate gel format preference for exercise-related pain management.
- Ointments:Water-in-oil emulsions with 60-80% occlusive petrolatum content, maximizing skin hydration and active retention. Chronic dry skin conditions in northern tier states sustain ointment volume despite cosmetic elegance limitations.
- Sprays:Metered-dose or continuous-spray delivery systems for difficult-to-reach anatomical sites. Germany and France pharmacy segments show underpenetration versus tube-saturated markets, creating whitespace for convenience-oriented channel expansion.
Creams retain shelf dominance; sprays gain share fastest on accessibility advantages.
Packaging Type:
Supply concentration in Chinese and Indian tube and bottle manufacturers exposes formulators to API and packaging material disruption risk simultaneously.
- Tubes:Collapsible aluminum or laminated plastic containers in 15-100 gram capacities, dominant across pharmacy and mass retail. Tube manufacturing capacity concentrates in Zhejiang province and Mumbai industrial corridors, with freight cost volatility affecting landed cost structures.
- Bottles:HDPE or PET containers for liquid and semi-liquid formulations, prevalent in spray and pump-delivery products. Blow-molding operations track regional petrochemical feedstock pricing, with Gulf Coast petrochemical complex disruptions propagating through packaging cost structures.
- Sachets:Single-use foil or polymer laminate pouches, capturing trial and travel-oriented purchasing. Airport retail and hospitality amenity channels in Dubai and Singapore drive format innovation for portability positioning.
- Jars:Wide-mouth polypropylene or glass containers for ointment and cream bulk formats. Institutional and professional channel preference sustains jar volume despite consumer convenience disadvantages.
Tubes command unit volume leadership; sachets expand most quickly on portability and trial-driven purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's OTC monograph reform anchors regulatory dynamics in the United States, the market's dominant geography. Direct-to-consumer health spending on dermatology concentrates demand across specific national markets with varying regulatory postures.
United States
Chronic musculoskeletal conditions in aging populations drive analgesic topical consumption above global per-capita averages. The FDA's accelerated safety reviews for legacy active ingredients force simultaneous reformulations across multiple product lines. Pharmacy chains in Florida and Arizona dedicate expanded shelf space to self-care dermatology sections.
Germany
Community pharmacy networks maintain stronger counseling infrastructure than Anglo-American counterparts, sustaining guided product selection at point of sale. EMA's MDR framework imposes stricter clinical evidence thresholds for borderline cosmetic-therapeutic products entering German markets. Metered-dose spray formulations show underpenetration versus tube-saturated pharmacy segments in Berlin and Munich metropolitan corridors.
China
Rising athlete's foot and ringworm incidence in humid southern provinces expands antifungal addressable volume faster than population growth. NMPA streamlined approval pathways for low-risk topical generics shorten market entry timelines for compliant international applicants. Manufacturing clusters in Zhejiang province concentrate tube and packaging material supply, exposing formulators to freight cost volatility.
Japan
Aging demographics sustain premium positioning for cosmetic-elegant formulations in urban markets. PMDA maintains distinct regulatory pathways for quasi-drugs that blur cosmetic-therapeutic boundaries. Dermatology-focused contract manufacturers in Osaka and Tokyo accelerate adoption of microemulsion delivery systems.
United Kingdom
Telehealth-integrated digital pharmacy platforms capture replenishment loyalty from episodic purchasers in London and Southeast England. MHRA post-Brexit regulatory divergence from EMA creates parallel compliance requirements for topical drug entrants. Boots and Lloyds pharmacy networks reduce dermatological training investment, degrading consumer guidance quality.
OTC Topical Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the OTC topical drugs landscape. The market structure consolidates around heritage consumer health conglomerates with established brand equity, while agile generics manufacturers exploit regulatory streamlining in emerging markets. Three archetypes dominate: science-backed heritage brands, scale-driven private-label suppliers, and dermatology-specialist innovators. Competitive moves concentrate on portfolio diversification into convenience-oriented formats and backward integration into active pharmaceutical ingredient supply.
Among heritage science-backed conglomerates, Johnson & Johnson and Bayer AG occupy positions sustained by decades of skin science credibility. GSK plc exemplifies the pharmacy-led distribution control archetype across European and North American markets. These three anchors represent distinct competitive vectors—Johnson & Johnson leveraging consumer trust in analgesic and antifungal segments, Bayer AG concentrating R&D intensity in hydrocortisone formulations, and GSK plc optimizing channel relationships rather than formulation innovation alone.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bayer AG |
| GSK plc |
| Bausch Health Companies Inc. |
| Galderma |
| Novartis AG |
| Perrigo Company plc |
| Cipla |
| Hisamitsu Pharmaceuticals Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for hydrocortisone and clotrimazole APIs lock in supply access and price visibility for formulators facing FDA monograph reform timelines. These contracts tether procurement stability to Chinese and Indian bulk manufacturers while insulating margin structures from spot-market volatility in semisolid base materials.
Pricing Analysis
United States pharmacy channels command 15-25% premiums over German and French equivalents for identical analgesic formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand heritage, with Johnson & Johnson and Bayer AG capturing top-tier positioning through skin science credibility. Cost compression in private-label antifungal segments is intensifying because mass retailers are expanding shelf-space allocations for store brands. Price-sensitive consumers in humid climate zones show highest elasticity, while chronic-condition subscribers in retirement corridor states exhibit lowest sensitivity due to replenishment loyalty.
Supply Chain Analysis
Inventory buffers for petrolatum-derived semisolid bases have compressed to six-to-eight week cycles as energy price volatility propagates through formulation pipelines. Active pharmaceutical ingredient supply concentrates in Zhejiang province and Mumbai industrial corridors, with excipient sourcing drawing from South Korean microemulsion specialists and Swiss contract manufacturers. Single-source vulnerability in Chinese tube and packaging material supply exposes formulators to freight cost spikes and customs processing delays. Distribution runs through wholesale-pharmacy relationships in established markets, while digital-native brands disintermediate through direct-to-consumer fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OTC topical drugs represent an early-cycle expansion story as telehealth-integrated digital platforms convert episodic purchasers into recurring-revenue subscribers. Spray formulation whitespace in European convenience channels accelerates penetration velocity beyond traditional pharmacy saturation curves.
For Market Incumbents: Compound brand equity in analgesic and antifungal segments through microemulsion delivery system licensing from Swiss and South Korean contract manufacturers. Backward integration into hydrocortisone API supply hedges against Chinese manufacturer concentration risk. FDA monograph compliance timelines demand simultaneous toxicology updates across multiple actives, straining regulatory affairs bandwidth and favoring incumbents with dedicated compliance infrastructure. For New Entrants and Emerging Players: Differentiate on metered-dose spray convenience in Germany and France pharmacy segments where tube formats dominate shelf space. Target underpenetrated humid climate metropolitan areas in the southeastern United States with athlete's foot incidence exceeding national averages. Pursue NMPA streamlined approval pathways for low-risk topical generics to capture China's antifungal expansion curve. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native topical brands with subscription-based replenishment models in United States urban markets. Long-term viability over the five-to-ten year window favors acquirers of dermatology-specialist innovators with microemulsion platform capabilities. Monitor pharmacist counseling erosion rates as an inflection indicator for guided product selection degradation and subsequent private-label share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Microemulsion Platform Licensing | Enables lower active concentrations with equivalent efficacy, reducing API costs for Johnson & Johnson and Bayer AG pipelines. |
| Spray Formulation Expansion | Captures whitespace in German and French convenience channels where metered-dose delivery remains underpenetrated versus tube saturation. |
| Subscription Replenishment Model | Converts chronic-condition users from episodic pharmacy visits to recurring digital-native brand loyalty in United States urban markets. |
| API Backward Integration | Hedges hydrocortisone and clotrimazole supply concentration risk in Zhejiang province and Mumbai industrial corridors. |
| NMPA Pathway Utilization | Shortens market entry timelines for compliant international applicants targeting China's rising antifungal incidence in humid southern provinces. |
Study Parameters
A standing panel of pharmacy chain category managers, dermatology-focused contract manufacturing executives, regulatory affairs leads at heritage consumer health conglomerates, and telehealth platform product directors provided ongoing calibration across the study duration. Primary interview findings combined with secondary validation from FDA OTC monograph filings, EMA MDR submission databases, NMPA approval registries, and Nielsen retail audit data for self-care dermatology sections. Bottom-up SKU-level volume aggregation and top-down market sizing triangulation anchored quantitative outputs.
Consistency checks validated projection outputs against external benchmarks including customs trade data for petrolatum-derived excipients and pharmaceutical API import records. The analytical framework modeled segmentation dimensions spanning product type, formulation architecture, packaging format, and regional regulatory cluster across the analysis window. CAGRs were derived from patient population epidemiology, channel shift elasticity coefficients, and pricing tier migration patterns. Forecast inputs incorporated chronic musculoskeletal condition prevalence curves and humid climate dermatophyte incidence projections.
The analysis sits within stated boundaries; outcomes outside FDA monograph reform acceleration or EMA MDR enforcement intensity assumptions would require recalibration. Forecasts reflect documented assumptions regarding pharmacist counseling infrastructure degradation rates and digital pharmacy platform penetration velocity. Specific risk factors including REACH authorization delays for novel preservative systems and Gulf Coast petrochemical complex disruptions could revise trajectory estimates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Desloratadine Market