
 Oligonucleotide Therapeutics Market | 2026-2036
Oligonucleotide Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Oligonucleotide Therapeutics Market Outlook
Platform licensing revenue is rewriting how oligonucleotide developers monetize intellectual property beyond direct drug sales. Ionis Pharmaceuticals anchors its position through extensive antisense patent estates and partnership structures with larger pharmaceutical firms. Alnylam Pharmaceuticals differentiates via proprietary GalNAc conjugate delivery technology that enables liver-targeted siRNA administration. Biogen competes in neuromuscular indications with established commercial infrastructure for rare disease patient identification and reimbursement navigation.
Oligonucleotide therapeutics are synthetic, single-stranded or double-stranded nucleic acid polymers, typically 8–50 bases in length, manufactured through solid-phase phosphoramidite synthesis with subsequent purification and analytical validation. These molecules function by sequence-specific binding to target RNA transcripts, modulating gene expression through degradation, translational blockade, or splice correction mechanisms. Among product type segments, antisense oligonucleotides occupy the largest current revenue pool given mature approved products in spinal muscular atrophy and hereditary transthyretin amyloidosis, while siRNA represents the fastest-expanding category driven by liver-targeted delivery advances. By therapy area, genetic disorders command premium pricing and orphan drug incentives, though oncology pipelines are broadening as tumor-specific antigen targeting improves.
FDA oversees oligonucleotide drug approval through its Center for Drug Evaluation and Research, with specialized guidance for gene therapy products and nucleic acid chemistry manufacturing controls. EMA's Committee for Medicinal Products for Human Use evaluates RNA-targeted therapies under its advanced therapy medicinal products framework, while ISO 13485 standards govern contract manufacturing quality systems. Stakeholders must monitor how evolving pharmacovigilance requirements for long-acting genetic medicines reshape post-market commitment burdens and lifecycle management strategies.
Market Dynamics
The oligonucleotide therapeutics market is compressing development timelines through FDA accelerated approval pathways and EMA adaptive licensing frameworks that reward biomarker-driven efficacy demonstrations. These regulatory innovations are redrawing competitive positioning around speed-to-clinic capabilities rather than manufacturing scale alone.
Growth Catalysts
- Orphan drug incentives:Genetic disorder indications command premium pricing and extended exclusivity periods under FDA and EMA frameworks, attracting development investment toward ultra-rare populations.
- Liver-targeted delivery advances:GalNAc conjugate chemistry enables subcutaneous siRNA administration with durable pharmacology, expanding addressable patient pools beyond infusion-dependent modalities.
- Academic medical center expansion:Neurology departments in Boston and San Diego biotechnology clusters are building dedicated antisense prescribing programs with specialized nursing infrastructure.
Market Restraints
- Phosphoramidite supply concentration:Solid-phase synthesis raw materials depend on a limited supplier base in Asia-Pacific, creating vulnerability to logistics disruptions and input cost volatility.
- Immunogenicity screening burden:Preclinical safety packages require extensive complement activation and cytokine release profiling, extending IND-enabling timelines and consuming analytical capacity.
- Small molecule competition:Oral transthyretin stabilizers and gene editing approaches threaten pricing power in established amyloidosis and neuromuscular franchises.
Strategic Opportunities
- Central nervous system penetration:Intrathecal delivery programs for Huntington's disease and ALS represent white space with limited competition and high unmet need.
- ISO 13485 contract manufacturing expansion:Quality-certified CDMO capacity in Switzerland and Singapore remains underdeveloped relative to sponsor pipeline growth.
- Tumor microenvironment targeting:siRNA conjugates directed against immunosuppressive stromal signals could unlock oncology applications beyond liver-localized mechanisms.
Industry Challenges
- Nucleic acid chemistry expertise scarcity:Phosphorothioate stereochemistry control and analytical method development require specialized training pipelines that academic programs have not scaled to match industry demand.
- Post-market pharmacovigilance complexity:Long-acting genetic medicines require extended patient follow-up commitments that strain safety database infrastructure and regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oligonucleotide Therapeutics Market |
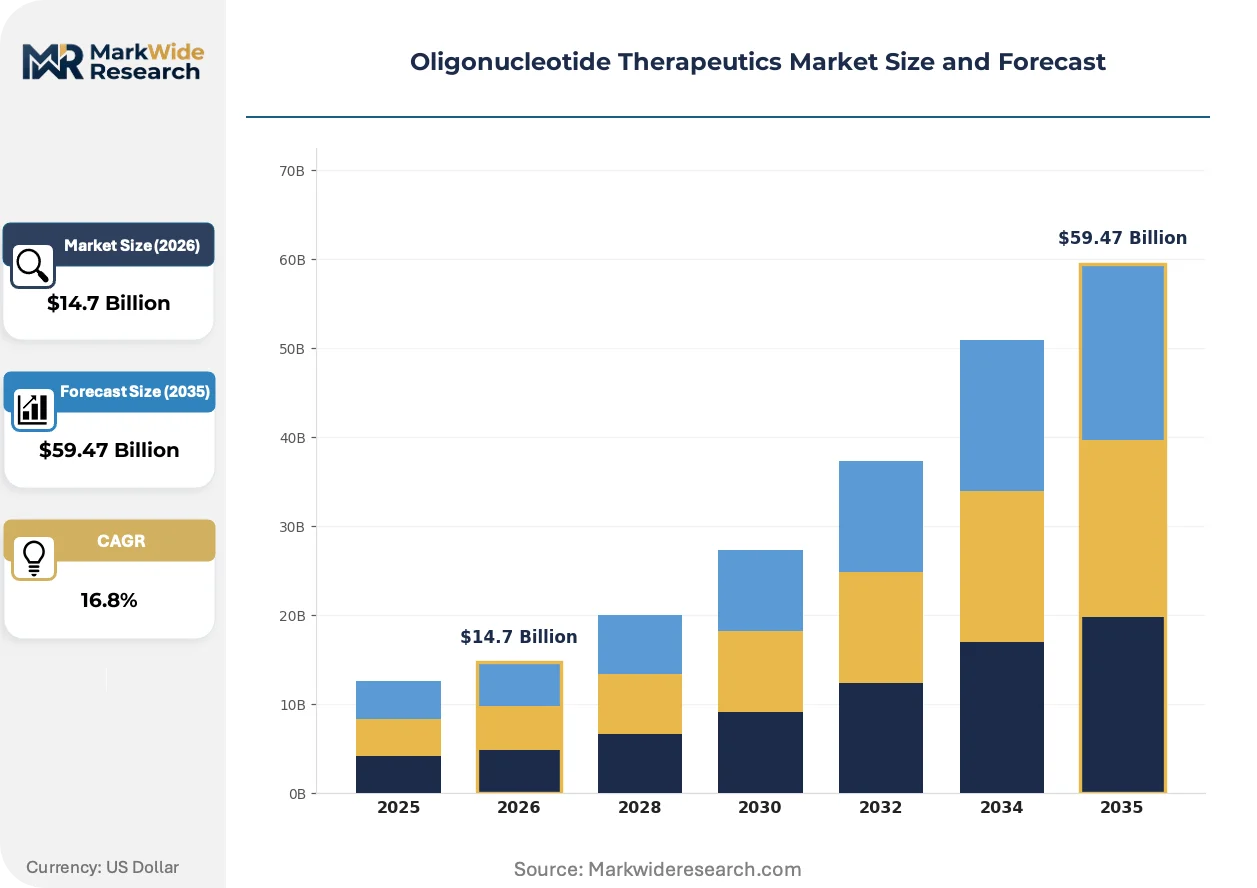
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $59.47 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antisense Oligonucleotides, siRNA, RNA Aptamers, Gene Editing Oligonucleotides Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation Therapy Area: Oncology, Genetic Disorders, Infectious Diseases, Cardiovascular Diseases End User: Hospitals, Research Institutions, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Ionis Pharmaceuticals, Alnylam Pharmaceuticals, Biogen, Regulus Therapeutics, Sarepta Therapeutics, Gilead Sciences, Novartis, Arrowhead Pharmaceuticals, Stoke Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oligonucleotide Therapeutics Market Strategic Shifts
RNA-targeted modalities are converging with advanced delivery chemistry and computational target identification to restructure how developers prioritize pipeline candidates. The competitive frontier is shifting toward tissue-specific biodistribution and duration-of-action engineering.
GalNAc-siRNA conjugate technology is collapsing the dosing frequency gap between nucleic acid therapeutics and small molecule standards. Hepatocyte-targeted uptake enables quarterly or biannual subcutaneous administration, displacing weekly infusion regimens in patient preference surveys. Specialty pharmacy networks are reconfiguring distribution infrastructure around this injection-to-infusion substitution pattern.
EMA's advanced therapy medicinal products framework is streamlining scientific advice procedures for RNA-targeted modalities with companion diagnostic requirements. The Committee for Medicinal Products for Human Use has issued three positive opinions for oligonucleotide therapies in the past eighteen months, establishing precedent for extrapolated efficacy claims in ultra-rare populations. Sponsors are front-loading health technology assessment engagement to preempt reimbursement delays in Germany and France.
Patient advocacy organizations are consolidating purchasing influence through managed access program negotiations and real-world evidence generation partnerships. Neuromuscular disease foundations in the United States are contracting directly with developers for expanded access protocols, bypassing traditional hospital formulary committees. This channel disintermediation is most visible in spinal muscular atrophy and hereditary transthyretin amyloidosis, where caregiver networks maintain direct communication with prescriber specialists.
Oligonucleotide Therapeutics Market Segmentation
Oligonucleotide therapeutics fragment across multiple technical and commercial dimensions that determine manufacturing requirements, regulatory pathways, and reimbursement negotiations. Each segmentation axis reveals distinct competitive dynamics between platform technology owners, delivery specialists, and indication-focused developers.
Product Type:
Technology maturity separates segments with established clinical validation from emerging modalities still establishing manufacturing scalability and pharmacokinetic profiles.
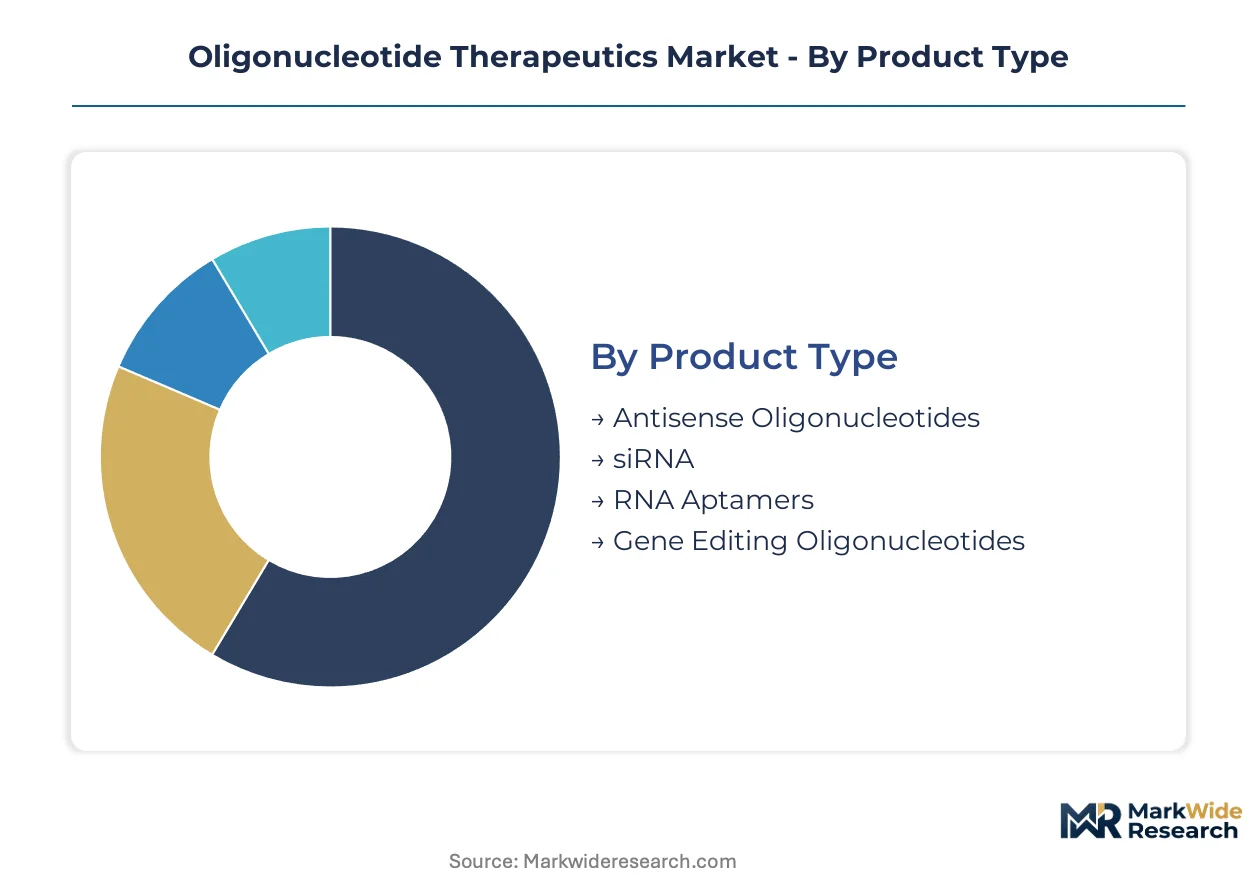
- Antisense Oligonucleotides:Single-stranded synthetic DNA analogs, typically 15–25 nucleotides with phosphorothioate backbone modifications, bind target mRNA to trigger RNase H-mediated degradation. Demand concentrates in spinal muscular atrophy and hereditary transthyretin amyloidosis programs at academic medical centers in Boston and San Diego, where specialized nursing infrastructure supports intrathecal administration protocols.
- siRNA:Double-stranded RNA molecules 21–25 base pairs in length leverage RNA interference machinery for post-transcriptional gene silencing. Hepatocyte-targeted GalNAc conjugate chemistry enables subcutaneous dosing at quarterly intervals, displacing infusion-dependent modalities in patient preference surveys across United States specialty pharmacy networks.
- RNA Aptamers:Structured single-stranded oligonucleotides fold into three-dimensional conformations that bind protein targets with antibody-like specificity.
- Gene Editing Oligonucleotides:Synthetic nucleic acids guide CRISPR-Cas systems or mediate single-base editing through engineered deaminase conjugates.
Antisense oligonucleotides hold installed capacity. siRNA is rotating up the share rankings.
Delivery Mode:
Route of administration determines formulation complexity, cold chain requirements, and prescriber training investments across development portfolios.
- Subcutaneous:GalNAc-conjugated siRNA formulations enable self-administration with quarterly dosing frequency, collapsing the convenience gap against oral small molecules. United States specialty pharmacies are reconfiguring distribution infrastructure around this injection-to-infusion substitution pattern.
- Intravenous:Lipid nanoparticle encapsulation remains necessary for extrahepatic tissue targeting and oncological applications, requiring infusion center capacity and extended observation protocols.
- Oral:Gastrointestinal stability challenges and epithelial permeability limitations constrain bioavailability for naked oligonucleotides.
- Inhalation:Pulmonary deposition patterns and mucociliary clearance mechanisms complicate local delivery to airway epithelium.
Subcutaneous administration captures the steepest expansion trajectory as liver-targeted chemistry matures. Intravenous maintains dominance in oncology pipelines.
Therapy Area:
Indication selection governs pricing power, trial design complexity, and post-market surveillance obligations through distinct regulatory precedents.
- Genetic Disorders:Ultra-rare monogenic diseases command orphan drug incentives with premium pricing and extended exclusivity under FDA and EMA frameworks. Patient advocacy organizations in the United States are consolidating purchasing influence through managed access program negotiations.
- Oncology:Tumor-specific antigen targeting and immunosuppressive stromal signal modulation represent white space with limited competition, though solid tumor penetration remains unresolved.
- Infectious Diseases:Viral RNA targeting faces competition from direct-acting antivirals and vaccine platforms.
- Cardiovascular Diseases:Lipid metabolism and inflammatory pathway modulation show promise but require large outcome trials.
Genetic disorders anchor current revenue concentration. Oncology is climbing the fastest as tumor microenvironment targeting improves.
End User:
Customer type dictates procurement scale, technical support requirements, and contractual risk allocation in supply agreements.
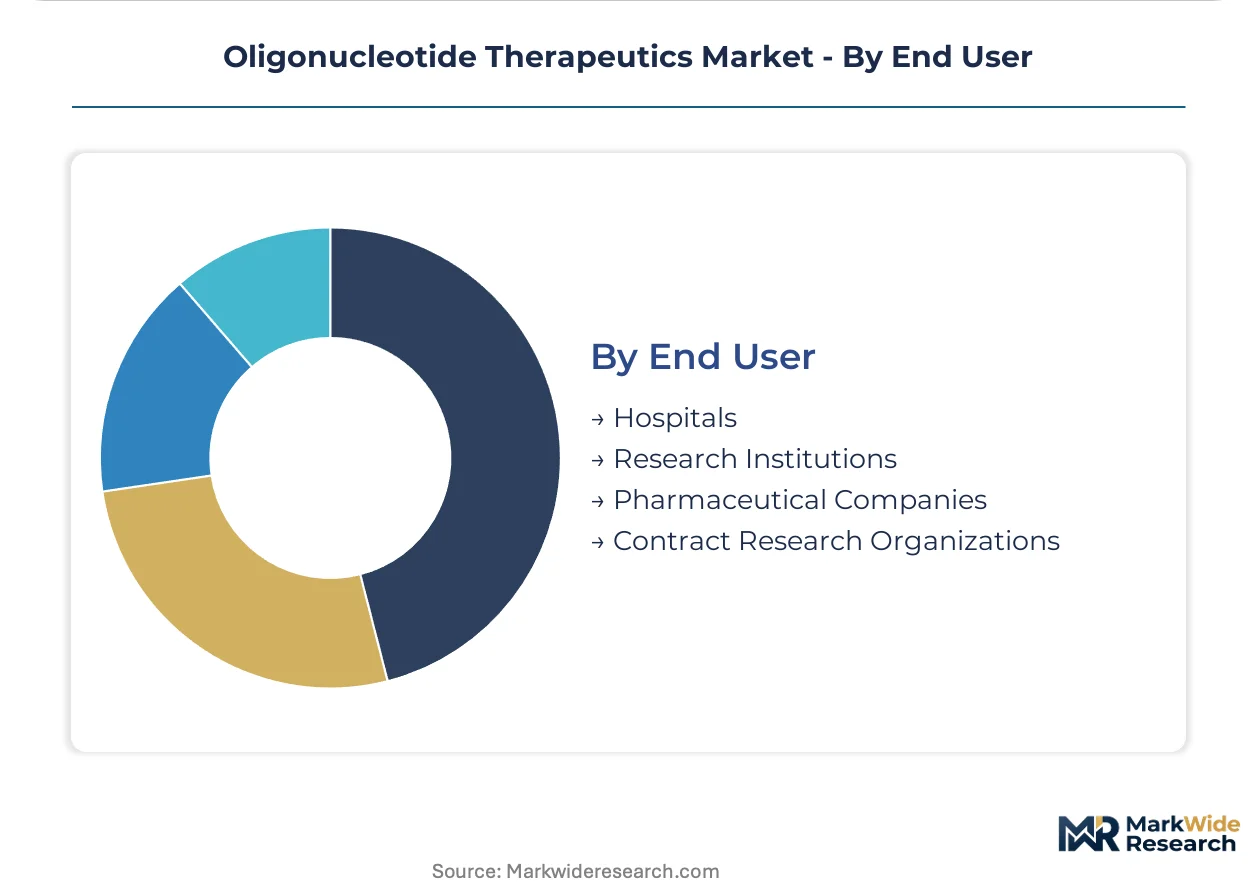
- Pharmaceutical Companies:Platform licensing revenue streams and partnership structures with larger firms monetize intellectual property beyond direct drug sales, with Ionis Pharmaceuticals and Alnylam Pharmaceuticals anchoring positions through patent estates and proprietary delivery technology.
- Hospitals:Academic medical centers in Boston and San Diego biotechnology clusters are building dedicated antisense prescribing programs with specialized nursing infrastructure for intrathecal administration.
- Research Institutions:Preclinical target validation and mechanism-of-study studies consume analytical-grade material.
- Contract Research Organizations:ISO 13485-certified manufacturing quality systems support IND-enabling toxicology and pharmacokinetic studies.
Pharmaceutical companies command the largest procurement volumes. Hospitals are gaining share fastest as commercial infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States buyers absorb premium pricing for orphan indications with minimal resistance. European procurement authorities extract substantial discounts through health technology assessment leverage.
United States
Specialty pharmacy networks concentrate demand in Boston and San Diego biotechnology clusters where academic medical centers expand intrathecal administration programs. FDA accelerated approval pathways compress development timelines for RNA-targeted modalities. Neurology departments in Massachusetts General Hospital and UC San Diego Health build dedicated antisense prescribing infrastructure with specialized nursing protocols.
Germany
Pharmaceutical procurement through G-BA health technology assessment demands robust cost-effectiveness evidence for premium-priced genetic medicines. EMA adaptive licensing frameworks enable early patient access while real-world evidence collection continues. Heidelberg and Munich research hospitals coordinate managed access programs for ultra-rare disease therapies under national reimbursement negotiations.
Switzerland
Swissmedic maintains streamlined evaluation procedures for advanced therapy medicinal products with companion diagnostic requirements. Basel and Zurich host contract manufacturing organizations seeking ISO 13485 certification expansion to match sponsor pipeline growth. The country's precision medicine ecosystem attracts platform licensing negotiations between developers and larger pharmaceutical partners.
Japan
PMDA's regenerative medicine and gene therapy review framework accommodates oligonucleotide modalities with biomarker-driven efficacy demonstrations. Tokyo and Osaka academic hospitals participate in multinational clinical trials for spinal muscular atrophy and hereditary transthyretin amyloidosis. METI industrial policy supports domestic manufacturing capacity for phosphoramidite synthesis intermediates.
United Kingdom
NICE appraisal processes scrutinize value-for-money claims in genetic disorder indications with small eligible populations. MHRA post-Brexit regulatory autonomy enables rapid approval decisions for innovative RNA-targeted therapies. London and Cambridge life science clusters attract early-stage pipeline assets through specialized venture financing structures.
Oligonucleotide Therapeutics Market Competitive Environment
Capability concentration sits with platform technology specialists; scale advantage sits with established pharmaceutical firms with commercial infrastructure. The market structure shows moderate consolidation around antisense patent estates and proprietary delivery chemistry. Two strategic archetypes dominate: technology originators monetizing intellectual property through licensing structures, and integrated developers combining manufacturing scale with rare disease commercial expertise. Competitive moves center on partnership formations with larger pharmaceutical firms and geographic expansion of ISO 13485-certified manufacturing capacity.
Within the platform technology tier, Ionis Pharmaceuticals and Alnylam Pharmaceuticals exemplify contrasting approaches to market positioning. Ionis anchors its presence through extensive antisense patent estates that enable partnership structures with larger pharmaceutical firms seeking RNA-targeted pipeline assets. Alnylam occupies a position defined by proprietary GalNAc conjugate delivery technology that enables liver-targeted siRNA administration with quarterly dosing frequency. Biogen represents the integrated commercial archetype, combining neuromuscular indication focus with established infrastructure for rare disease patient identification and reimbursement navigation.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals |
| Alnylam Pharmaceuticals |
| Biogen |
| Regulus Therapeutics |
| Sarepta Therapeutics |
| Gilead Sciences |
| Novartis |
| Arrowhead Pharmaceuticals |
| Stoke Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Phosphoramidite synthesis capacity in Asia-Pacific feeds directly into margin capture by integrated developers with captive manufacturing. Platform licensors extract royalty streams that decouple revenue from production volume, while contract manufacturers compete on analytical validation speed.
Pricing Analysis
After-sales revenue from patient support programs and adherence monitoring drives lifetime value for approved oligonucleotide therapies. The dominant structure combines per-dose transactional pricing with outcomes-based contracting for large payers. Price differentiation rests on orphan drug exclusivity status and intrathecal versus subcutaneous administration complexity. Cost compression in the infusion-dependent segment is intensifying because GalNAc-conjugate chemistry collapses nursing infrastructure requirements. Hospital procurement committees show highest price sensitivity; specialty pharmacy networks absorb premiums with minimal resistance.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for solid-phase synthesis equipment and phosphoramidite monomers. Manufacturing gravity centers on Switzerland, Singapore, and selected United States biotechnology clusters for ISO 13485-certified capacity. Raw material dependencies include phosphoramidite reagents, controlled-pore glass solid supports, and high-purity solvents. Single-source vulnerability persists for stereochemically pure phosphorothioate building blocks. Distribution runs through cold-chain specialty pharmacy networks with direct-to-patient last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA-targeted modalities constitute high-growth therapeutic disruption justified by FDA accelerated approval pathway compression and EMA adaptive licensing precedent for biomarker-driven submissions.
For Market Incumbents: Harden antisense patent estates through continuation filings and territorial expansion into Japan and Switzerland. Secure backward integration into phosphoramidite manufacturing to neutralize Asia-Pacific supply concentration. Defend against siRNA displacement by emphasizing intrathecal delivery expertise in neuromuscular indications where blood-brain barrier penetration remains unresolved.
For New Entrants and Emerging Players: Build out central nervous system penetration capabilities for Huntington's disease and ALS as white-space targets with limited competition. Target academic medical centers in Boston and San Diego for early prescriber relationship formation. Pursue platform licensing structures with larger pharmaceutical partners lacking RNA-targeted internal expertise.
For Investors and Strategic Acquirers: Capital is best deployed toward delivery technology specialists with demonstrated GalNAc conjugate chemistry or proprietary intrathecal formulation intellectual property. Long-term viability favors developers with diversified modality pipelines spanning antisense, siRNA, and gene editing oligonucleotides. Watch FDA breakthrough therapy designation frequency as inflection indicator for regulatory risk appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc Delivery Technology Licensing | Enables liver-targeted siRNA administration with quarterly dosing frequency. |
| Intrathecal Administration Program Expansion | Builds specialized nursing infrastructure at academic medical centers. |
| ISO 13485 Manufacturing Certification | Qualifies contract manufacturing for FDA and EMA regulatory submissions. |
| Orphan Drug Designation Pursuit | Secures extended exclusivity and premium pricing under FDA framework. |
| Real-World Evidence Partnership | Generates post-market data for health technology assessment negotiations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market sizing. Cross-referencing across these sources identified consensus assumptions for penetration rates and pricing trajectories.
Forecast inputs span product type, delivery mode, therapy area, and regional regulatory cluster segmentation across the projection horizon. CAGRs derive from patient population epidemiology, approval probability-weighted pipeline valuation, and analog product launch curve analysis. Industry-specific inputs include phosphoramidite supply capacity expansion timelines and academic medical center infrastructure buildout rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene editing platform developers or oral small molecule competitors would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Hard Gelatin Capsules Market