
 United Kingdom OTC Drugs Market | 2026-2036
United Kingdom OTC Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom OTC Drugs Market Analytics
The capital-intensity divergence between multinational pharmaceutical conglomerates and domestic OTC specialists is collapsing as shelf-space competition intensifies across UK retail channels. Haleon Group of Companies leverages its demerged consumer health infrastructure to dominate pharmacy and supermarket distribution. GSK plc sustains brand equity in cold and allergy medicines through decades of UK market presence. Perrigo Company plc anchors private-label supply contracts with major supermarket chains, competing on volume rather than innovation.
Over-the-counter drugs encompass non-prescription medicinal products formulated with active pharmaceutical ingredients below prescription-strength thresholds, manufactured through standard tableting, encapsulation, or liquid-fill processes, and distributed for self-diagnosed conditions without clinician oversight. The primary commercial purpose centers on enabling consumer-directed symptom management while reducing National Health Service primary care burdens. Pain relievers occupy the largest revenue pool within product type segments, reflecting persistent demand for ibuprofen and paracetamol-based formulations. Online retail represents the fastest-growing distribution channel, though pharmacies retain the highest margin capture through professional consultation attachments. Blister packs lead packaging type preferences due to compliance-prompting unit-dose formats and child-resistant safety requirements.
The Medicines and Healthcare products Regulatory Agency governs OTC reclassification pathways, while the General Pharmaceutical Council oversees pharmacy-level dispensing standards, and the Competition and Markets Authority monitors pricing practices across retail channels. MHRA switch protocols from prescription to OTC status directly expand addressable product portfolios for manufacturers and retailers alike. Stakeholders must monitor MHRA reclassification timetables and pharmacy workforce capacity constraints to anticipate category expansion windows and distribution bottlenecks.
Market Dynamics
The MHRA's reclassification protocols are compressing prescription-to-OTC transition timelines, forcing manufacturers to accelerate formulation development while retailers scramble for shelf-space allocation in England's consolidated pharmacy networks.
Growth Catalysts
- MHRA Switch Protocols:The agency's streamlined assessment pathways for prescription-to-OTC transitions are expanding accessible product portfolios. Category managers at major retailers now plan around anticipated reclassification timetables.
- Aging Self-Medication:Adults over 65 in England's urban centers are driving sustained demand for digestive aids and nutritional supplements without clinician consultation.
- Supermarket Channel Expansion:Tesco, Sainsbury's and Asda are dedicating expanded aisle space to OTC categories, competing directly with pharmacy networks on convenience and price.
Market Restraints
- API Supply Concentration:Paracetamol and ibuprofen active pharmaceutical ingredients depend heavily on Indian and Chinese bulk manufacturers, exposing formulators to input cost volatility and geopolitical friction.
- Pharmacy Workforce Constraints:The General Pharmaceutical Council's training bottlenecks limit dispensing capacity in England's NHS-contracted community pharmacies, creating distribution bottlenecks for newly reclassified products.
- Digital Therapeutic Substitution:NHS-endorsed symptom-checker apps and telehealth triage services are diverting mild-condition patients from OTC purchase occasions entirely.
Strategic Opportunities
- Scotland and Wales Underpenetration:Rural pharmacy networks in these regions carry narrower OTC assortments than England's urban centers, presenting first-mover expansion potential for digestive and respiratory categories.
- Online Pharmacy Integration:Pharmacy2U and Boots' digital platforms are merging prescription fulfillment with OTC cross-selling, creating new high-margin consultation touchpoints.
- Nutraceutical Convergence:Probiotic and vitamin formulations with medicinal claims are blurring category boundaries, opening shelf-space in supermarket health-and-wellness aisles previously closed to drug-format products.
Industry Challenges
- Qualified Person Shortage:MHRA-mandated responsible pharmacists for OTC manufacturing sites are in acute supply, delaying product launches and facility certifications.
- Blister-Pack Sustainability Compliance:Transitioning from PVC to recyclable alternatives while maintaining child-resistant standards requires capital-intensive line reconfiguration at contract packaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom OTC Drugs Market |
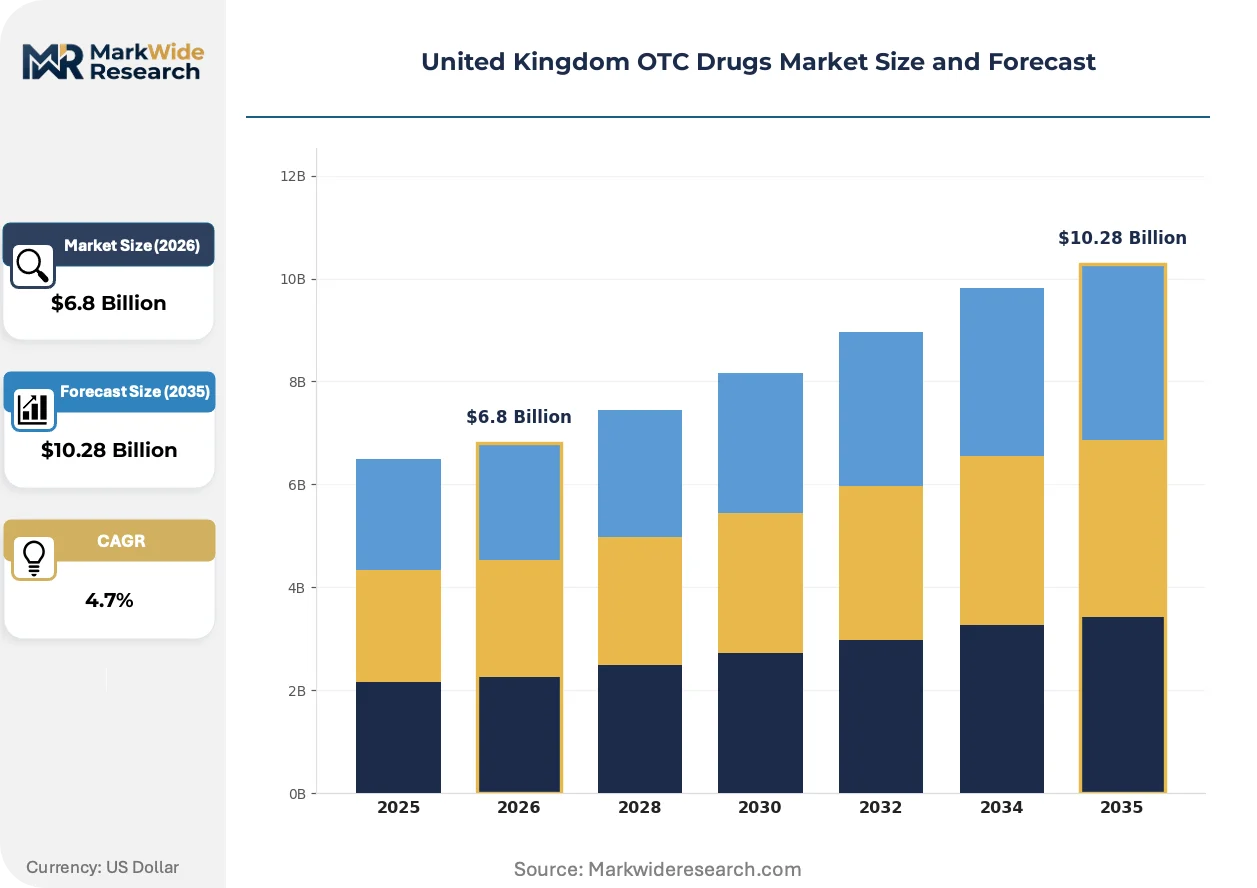
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cold & Allergy Medicines, Digestive Aids, Nutritional Supplements Distribution Channel: Pharmacies, Supermarkets, Online Retail, Health Stores Packaging Type: Blister Packs, Bottles, Sachets, Tubs Customer Type: Adults, Children, Seniors, Healthcare Professionals |
| Companies Covered | Pfizer Inc, Bayer AG, Johnson & Johnson, Haleon Group of Companies, Perrigo Company plc, Reckitt Benckiser Group PLC, Sanofi, Novo Nordisk A/S, GSK plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom OTC Drugs Market Evolving Landscape
Digital health integration and sustainable packaging mandates are forcing simultaneous transformation across formulation, manufacturing and distribution layers of the UK OTC value chain.
Smart blister packaging with embedded NFC tags is displacing conventional compliance packaging in premium analgesic and chronic-condition categories. Pharmacy chains in Greater London and Manchester are piloting these formats for medication adherence programs. The technology is displacing unit-dose cartons as the standard for NHS-contracted smoking cessation and statin adjunct products.
The MHRA's updated guidance on Real World Evidence for OTC switches is compressing clinical trial requirements for reclassification applicants. Manufacturers can now submit patient survey data and pharmacy dispensing records in lieu of prospective studies for certain low-risk switches. This regulatory shift most benefits respiratory and topical analgesic categories where decades of prescription safety data already exist.
Subscription-based replenishment models are capturing chronic-condition households previously served by episodic supermarket purchases. Pharmacy2U and LloydsPharmacy have built dedicated OTC subscription tiers alongside prescription services. This pattern concentrates in England's Southeast commuter belt where convenience premiums outweigh price sensitivity for allergy and vitamin D maintenance regimens.
United Kingdom OTC Drugs Market Segmentation
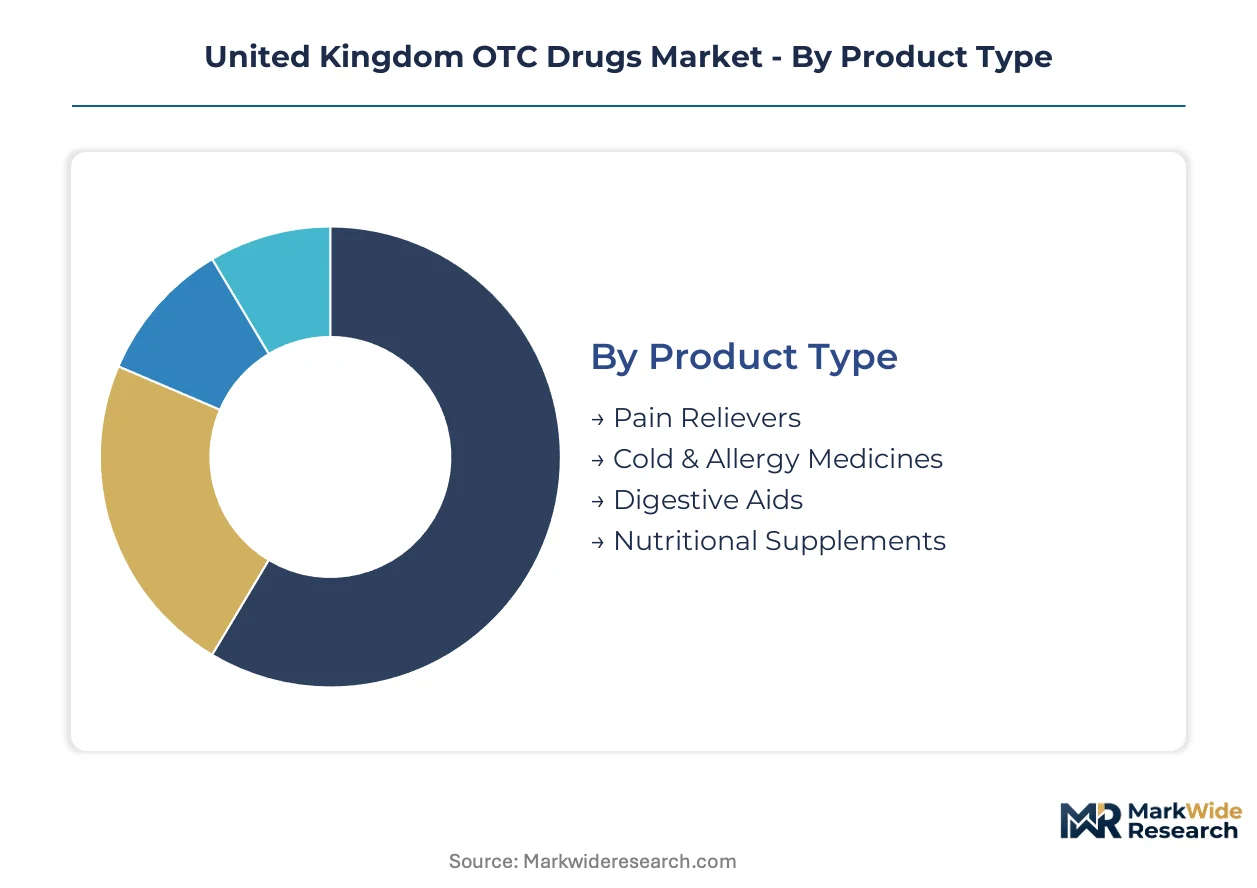
Segmentation in the United Kingdom OTC Drugs Market reveals how MHRA reclassification protocols and channel consolidation reshape competitive boundaries. Manufacturers must align formulation development with distinct packaging, distribution, and customer requirements across England's urban pharmacy networks versus supermarket retail channels.
Product Type:
Substitution pressure varies sharply across therapeutic categories, with digital health apps and NHS telehealth services diverting mild-condition patients from traditional analgesic purchases while chronic-condition segments prove stickier.
- Pain Relievers:Ibuprofen and paracetamol-based formulations dominate shelf space across Tesco, Sainsbury's, and Asda outlets. Demand concentrates in England's urban centers where aging populations self-medicate recurring musculoskeletal complaints without GP appointments.
- Cold & Allergy Medicines:Antihistamine and decongestant combinations face seasonal volatility but retain pharmacy loyalty through professional consultation attachments. Hay fever preparations spike in the Southeast commuter belt where Pharmacy2U subscription models capture recurring households.
- Digestive Aids:Antacids and proton pump inhibitors compete with prescription alternatives in supermarket health aisles.
- Nutritional Supplements:Vitamin D and probiotic formulations blur into wellness categories with medicinal claim restrictions.
Pain Relievers retain volume leadership; Nutritional Supplements hold the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates premium-margin pharmacy consultations from high-volume supermarket transactions, with online platforms now bridging both models.
- Pharmacies:NHS-contracted community pharmacies in England capture the highest margin through professional consultation attachments and smoking cessation program tie-ins. The General Pharmaceutical Council's dispensing standards create regulatory moats that supermarkets cannot replicate.
- Supermarkets:Tesco, Sainsbury's, and Asda compete on convenience and price, dedicating expanded aisle space to OTC categories previously pharmacy-exclusive. Volume concentrates in paracetamol and ibuprofen private-label contracts where Perrigo anchors supply.
- Online Retail:Pharmacy2U and Boots digital platforms merge prescription fulfillment with OTC cross-selling.
- Health Stores:Holland & Barrett and independent retailers focus on nutraceutical convergence products with blurred medicinal boundaries.
Pharmacies retain margin leadership; Online Retail climbs the fastest.
Packaging Type:
Application requirements drive format selection, with child-resistant mandates and compliance-prompting features determining premium versus economy positioning.
- Blister Packs:Unit-dose formats with child-resistant safety requirements dominate analgesic and chronic-condition categories. Smart blister packaging with embedded NFC tags is displacing conventional formats in NHS-contracted smoking cessation programs across Greater London and Manchester.
- Bottles:Liquid-fill processes serve pediatric and geriatric segments where swallowing difficulties concentrate demand. Scotland's rural pharmacy networks rely heavily on bottle formats for broader demographic reach.
- Sachets:Single-dose powder formats target travel and on-the-go consumption occasions.
- Tubs:Bulk containers serve healthcare professional and institutional procurement channels.
Blister Packs retain format leadership; Smart blister variants gain share fastest.
Customer Type:
Volume concentration aligns with demographic weighting, though healthcare professional procurement creates distinct B2B dynamics separate from consumer self-selection.
- Adults:Working-age consumers in England's Southeast commuter belt drive subscription-based replenishment for allergy and vitamin D maintenance regimens through Pharmacy2U and LloydsPharmacy platforms.
- Seniors:Adults over 65 in urban centers sustain demand for digestive aids without clinician consultation, though digital therapeutic substitution poses emerging threat to episodic purchase patterns.
- Children:Pediatric formulations face stricter MHRA dosing regulations and packaging mandates.
- Healthcare Professionals:Practice nurses and pharmacists procure smoking cessation and statin adjunct products through NHS supply chains.
Adults retain purchase frequency leadership; Seniors present the steepest expansion trajectory amid aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across UK regions, with supermarket-driven England showing highest sensitivity to private-label competition while pharmacy-dependent Scotland and Wales retain margin resilience through consultation attachments.
London and the Southeast
Subscription-based replenishment models capture chronic-condition households in the commuter belt, where Pharmacy2U and LloydsPharmacy platforms merge prescription fulfillment with OTC cross-selling. The MHRA's proximity to Westminster accelerates reclassification awareness among category managers. Smart blister packaging pilots concentrate in Greater London pharmacy chains for NHS-contracted smoking cessation programs.
Midlands
Manufacturing sites for contract packaging and formulation development cluster in Birmingham and Leicester, where MHRA-mandated Qualified Person shortages delay facility certifications. The region's aging industrial workforce sustains demand for musculoskeletal analgesics through Tesco and Asda superstores. Boots' distribution hub in Nottingham anchors pharmacy network replenishment.
North England
Consolidated pharmacy networks in Manchester and Liverpool face workforce constraints from General Pharmaceutical Council training bottlenecks. Rural Cumbria and Northumberland rely on bottle-format liquid medicines for broader demographic reach. The region's NHS-contracted community pharmacies capture smoking cessation program margins unavailable to supermarket competitors.
Scotland
Rural pharmacy networks carry narrower OTC assortments than England's urban centers, presenting first-mover expansion potential for digestive and respiratory categories. The Scottish Government's pharmacy-first minor ailments scheme diverts GP consultations toward pharmacist-managed OTC recommendations. Edinburgh and Glasgow concentrate demand for antihistamine combinations through professional consultation channels.
Wales
Valleys communities exhibit lower supermarket OTC penetration, preserving pharmacy channel dominance for pain relievers and cold medicines. The Welsh Government's free prescription policy reduces price sensitivity for reclassified products. Cardiff anchors distribution while rural networks depend on bottle formats for pediatric and geriatric segments.
United Kingdom OTC Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with demerged consumer health infrastructure competing against legacy pharmaceutical conglomerates for shelf-space allocation. The capital-intensity gap between multinational formulators and domestic OTC specialists is narrowing as blister-pack sustainability mandates force capital-intensive line reconfiguration. Three archetypes dominate: pharmacy-network integrators leveraging professional consultation attachments; supermarket private-label suppliers competing on volume; and nutraceutical convergence players blurring wellness-medicine boundaries. Competitive moves center on MHRA reclassification timing acceleration and subscription platform integration.
Within the pharmacy-network tier, Haleon Group of Companies and GSK plc exemplify divergent post-demerger strategies, with the former leveraging standalone consumer health infrastructure and the latter sustaining brand equity through decades of UK market presence. Perrigo Company plc anchors the private-label supply archetype, competing on volume rather than innovation through major supermarket chain contracts. These three occupy positions across the integrated-to-specialist spectrum, representing the competitive tension between margin-capture pharmacy models and price-driven retail formats.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bayer AG |
| Johnson & Johnson |
| Haleon Group of Companies |
| Perrigo Company plc |
| Reckitt Benckiser Group PLC |
| Sanofi |
| Novo Nordisk A/S |
| GSK plc |
| Others |
Value Network & Pricing Analysis
Paracetamol and ibuprofen API substitution from Indian bulk manufacturers to alternative sourcing strategies simultaneously redraws supply geography toward Southeast Asian chemical hubs and compresses formulation economics for UK packagers. This input displacement forces domestic manufacturers to absorb margin erosion or pass through cost volatility to supermarket private-label contracts and pharmacy network tenders.
Pricing Analysis
After-sales consultation revenue through NHS-contracted pharmacy smoking cessation programs and chronic-condition management attachments drives lifetime value capture beyond unit-dose transactions. Three-tier pricing structure across premium pharmacy consultation bundles, standard supermarket shelf formats, and economy private-label contracts stratifies the market. Cost compression in economy tiers is intensifying because Perrigo's volume-anchored supermarket supply contracts exert downward pressure on branded alternatives. Price sensitivity concentrates among supermarket shoppers in England's urban centers, while pharmacy-dependent seniors in Wales and Scotland accept consultation premiums.
Supply Chain Analysis
Strait of Hormuz transit exposure for API shipments from Indian bulk manufacturers to European formulation sites concentrates geopolitical risk in a single maritime chokepoint. Active pharmaceutical ingredient supply draws from India, China, and select Eastern European chemical producers. Paracetamol powder, ibuprofen crystals, and excipient blends constitute the core input dependencies. Single-source vulnerability from concentrated Indian API manufacturing exposes UK formulators to tariff friction and currency volatility. Distribution runs through Boots' Nottingham hub and Tesco's central replenishment network for downstream pharmacy and supermarket allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MHRA's compressed reclassification timelines for prescription-to-OTC switches constitute a regulatory inflection that accelerates product portfolio turnover and rewards agile formulation development.
For Market Incumbents: Compound pharmacy network loyalty through exclusive consultation-anchored distribution agreements that supermarket competitors cannot replicate. Deepen backward integration into sustainable blister-pack manufacturing to preempt PVC-to-recyclable transition capital requirements. Haleon and GSK must defend against Perrigo's volume-driven private-label expansion by locking shelf-space commitments ahead of MHRA reclassification waves. For New Entrants and Emerging Players: Subscription-layer service gaps in chronic-condition replenishment for allergy and vitamin D regimens expose incumbent underinvestment in digital adherence platforms. Pharmacy2U's integration model reveals penetrable white space in Scotland and Wales where rural pharmacy networks carry narrower assortments. Target first-mover expansion into digestive and respiratory categories through direct-to-patient subscription launches. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated OTC specialists with captive API relationships and MHRA-approved manufacturing footprints. Long-term viability hinges on regulatory navigation capability rather than pure brand equity. Acquisition candidates should demonstrate Qualified Person staffing depth and sustainable packaging line readiness. Monitor MHRA reclassification timetables as the primary inflection signal for category expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Switch Protocol Acceleration | Expands addressable product portfolios for manufacturers ahead of competitor launches. |
| Subscription Platform Integration | Pharmacy2U and LloydsPharmacy merge prescription fulfillment with high-margin OTC cross-selling. |
| Sustainable Packaging Line Reconfiguration | PVC-to-recyclable blister transitions require capital-intensive contract packaging facility upgrades. |
| Scotland and Wales Geographic Expansion | Rural pharmacy underpenetration presents first-mover capture potential for digestive categories. |
| Smart Blister Packaging Pilot Deployment | NFC-enabled compliance formats displace unit-dose cartons in NHS smoking cessation programs. |
Research Methodology
A standing panel of pharmacy procurement managers, MHRA regulatory affairs specialists, supermarket category buyers, and NHS formulary directors provided ongoing calibration throughout the study period. Primary interviews with contract packaging facility operators and API sourcing executives combined with secondary validation from MHRA reclassification databases, NHS dispensing records, and supermarket private-label contract filings. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions covered product type, distribution channel, packaging format, and customer demographic, with regional regulatory cluster as an additional modeled layer. CAGRs derived from historical trajectory analysis and forward-looking reclassification pipeline assessment incorporated MHRA switch probability weightings and pharmacy workforce capacity constraints.
Underlying assumptions cover sustained MHRA reclassification velocity, stable API trade flows from Indian bulk manufacturers, and NHS pharmacy-first policy continuity, with deviation risk concentrated in geopolitical friction affecting paracetamol and ibuprofen input costs. Practitioners should keep alternative scenarios live as MHRA staffing levels and EU-UK regulatory divergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market