
 Middle East and Africa Patient Monitoring Market | 2026-2036
Middle East and Africa Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Patient Monitoring Market Outlook
MDR compliance timelines for CE-marked devices is rebalancing the cost-of-entry calculus for manufacturers exporting into North African markets. GE Healthcare leverages its established imaging-service infrastructure to bundle monitoring hardware with long-term maintenance contracts. Koninklijke Philips NV anchors its competitive position through intensive R&D allocation toward wearable cardiac form factors suited to hot-climate durability requirements. Medtronic competes by extending its diabetes monitoring portfolio into broader metabolic tracking platforms for hospital networks.
Patient monitoring encompasses continuous or intermittent physiological measurement systems—incorporating sensors, signal processors, and data transmission modules—that capture vital signs including electrocardiography, pulse oximetry, capnography, and invasive pressure readings for clinical decision support. These systems employ analog-to-digital conversion at sampling rates exceeding 250 Hz for cardiac applications, with Bluetooth Low Energy and medical-grade telemetry enabling ward-to-cloud data pipelines. Remote patient monitoring solutions lead structural expansion as Gulf health systems deploy post-acute surveillance to reduce readmission penalties, while bedside monitors sustain margin pools in tertiary critical care installations where multi-parameter integration commands premium positioning. Wearable devices represent the fastest-growing product category, though implantable devices occupy the highest per-unit value tier due to biocompatibility certification burdens and sterile manufacturing protocols.
South Africa's SAHPRA, Saudi Arabia's SFDA, and the UAE's MOHAP collectively enforce electromagnetic compatibility and cybersecurity standards that determine market access for wireless-enabled devices. These regulators now mandate software bill of materials disclosure and post-market surveillance reporting, elevating compliance investment for new entrants. Stakeholders must monitor harmonization gaps between Gulf national requirements and broader African Medicines Regulatory Harmonization initiative standards to avoid fragmented certification pathways.
Market Dynamics
Gulf health ministries are consolidating procurement through centralized tenders that favor multi-parameter monitoring suites with embedded telemetry, compressing vendor margins while expanding installed base volumes across Saudi Arabia and UAE hospital networks.
Growth Catalysts
- SFDA Remote Monitoring Guidelines:Saudi Arabia's regulatory framework mandates post-acute surveillance for cardiac patients, creating institutional demand for ward-to-cloud telemetry infrastructure in tertiary hospitals.
- Chronic Disease Surveillance:Diabetes and cardiovascular monitoring programs across Gulf Cooperation Council states are scaling connected glucose and ECG platforms into primary care networks.
- Bluetooth Low Energy Integration:Medical-grade BLE modules are enabling ambulatory monitoring with 30-day battery life, supporting hot-climate wearable deployments in UAE and Qatar.
Market Restraints
- Biocompatibility Certification Burden:Implantable device manufacturers face 18-24 month SAHPRA sterile manufacturing audits, elevating working capital requirements for South African market entry.
- Semiconductor Component Concentration:Analog-to-digital converters and MEMS sensors concentrate in East Asian foundries, exposing African distributors to 12-week lead time volatility.
- Electromagnetic Compatibility Testing:Gulf regulators enforce IEC 60601-1-2 radiated immunity standards that disqualify consumer-grade wearables from hospital procurement lists.
Strategic Opportunities
- Nigeria's National Health Insurance Expansion:Federal coverage mandates for rural primary care are opening tender channels for low-cost pulse oximetry and temperature monitoring devices.
- AI-Enabled Arrhythmia Detection:Edge computing algorithms embedded in bedside monitors are reducing false alarm rates, creating upgrade cycles in Saudi critical care units.
- Pharmacy Retail Distribution:South African retail pharmacy chains are establishing direct-to-patient rental models for home sleep apnea monitoring, bypassing hospital procurement bottlenecks.
Industry Challenges
- Embedded Systems Engineering Talent:Firmware development for 250 Hz cardiac sampling with real-time artifact rejection remains scarce across Middle East engineering labor pools.
- Legacy Hospital IT Integration:HL7 FHIR interoperability with 1990s-era patient data management systems requires custom middleware development, extending deployment timelines in Egyptian public hospitals.
- Software Bill of Materials Disclosure:Gulf cybersecurity mandates expose third-party library vulnerabilities, forcing vendors to re-architect codebases for regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Patient Monitoring Market |
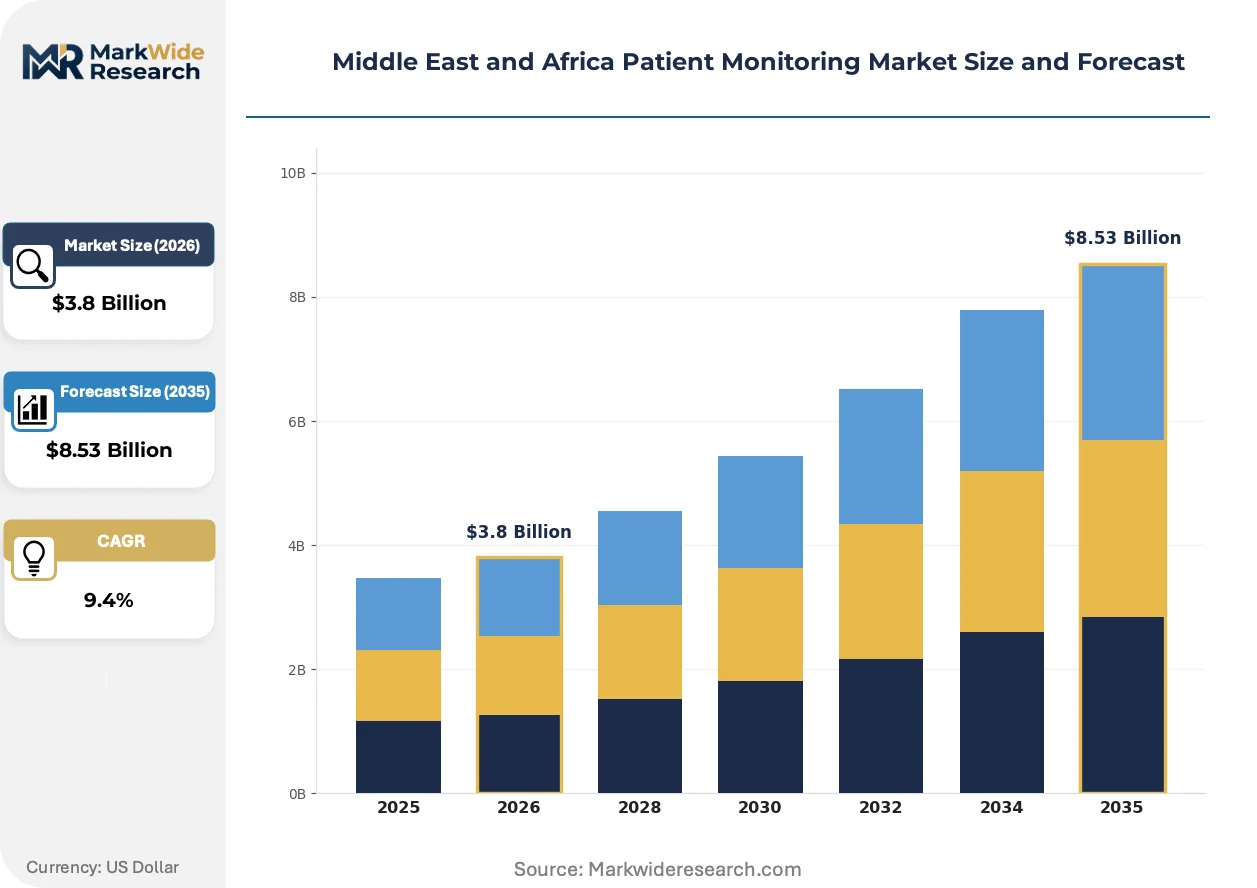
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Remote Patient Monitoring Solutions, Bedside Monitors Technology: Wireless Technology, Bluetooth, Telemetry, Cloud Computing End User: Hospitals, Home Care Settings, Clinics, Long-term Care Facilities Application: Cardiac Monitoring, Respiratory Monitoring, Fetal Monitoring, Neurological Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips NV, Medtronic, Abbott Laboratories, Boston Scientific Corporation, Becton Dickinson and Company, Siemens Healthcare GmbH, OMRON Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Patient Monitoring Market Strategic Shifts
Patient monitoring architecture is pivoting from bedside-centric installations toward distributed sensor networks that capture physiological data across ambulatory, home, and acute settings through unified cloud platforms.
Capnography modules with solid-state infrared sensing are absorbing traditional sidestream gas analyzer market share in Saudi Arabian intensive care units. King Faisal Specialist Hospital and Research Centre has standardized these devices across its Riyadh cardiac surgery wards. The technology is absorbing maintenance revenue from legacy electrochemical sensor replacement cycles while reducing calibration downtime.
MDR compliance timelines for CE-marked devices are compressing North African market access windows as Egyptian and Moroccan regulators adopt European technical documentation requirements. Manufacturers must now submit clinical evaluation reports and post-market surveillance protocols to national competent authorities. Cardiac implantable electronic device segments face the steepest re-certification burdens, with several vendors withdrawing economy-tier product lines rather than absorbing compliance costs.
Hospital procurement departments across Dubai Health Authority networks are unbundling hardware acquisition from long-term service contracts, creating transparent lifecycle cost comparisons between vendors. This separation enables multi-brand monitoring ecosystems where Philips wearable cardiac patches integrate with GE bedside displays through standardized data protocols. The shift is most visible in UAE's public-private partnership hospitals, where finance departments now mandate 10-year total cost of ownership analyses for capital committee approvals.
Middle East and Africa Patient Monitoring Market Segmentation
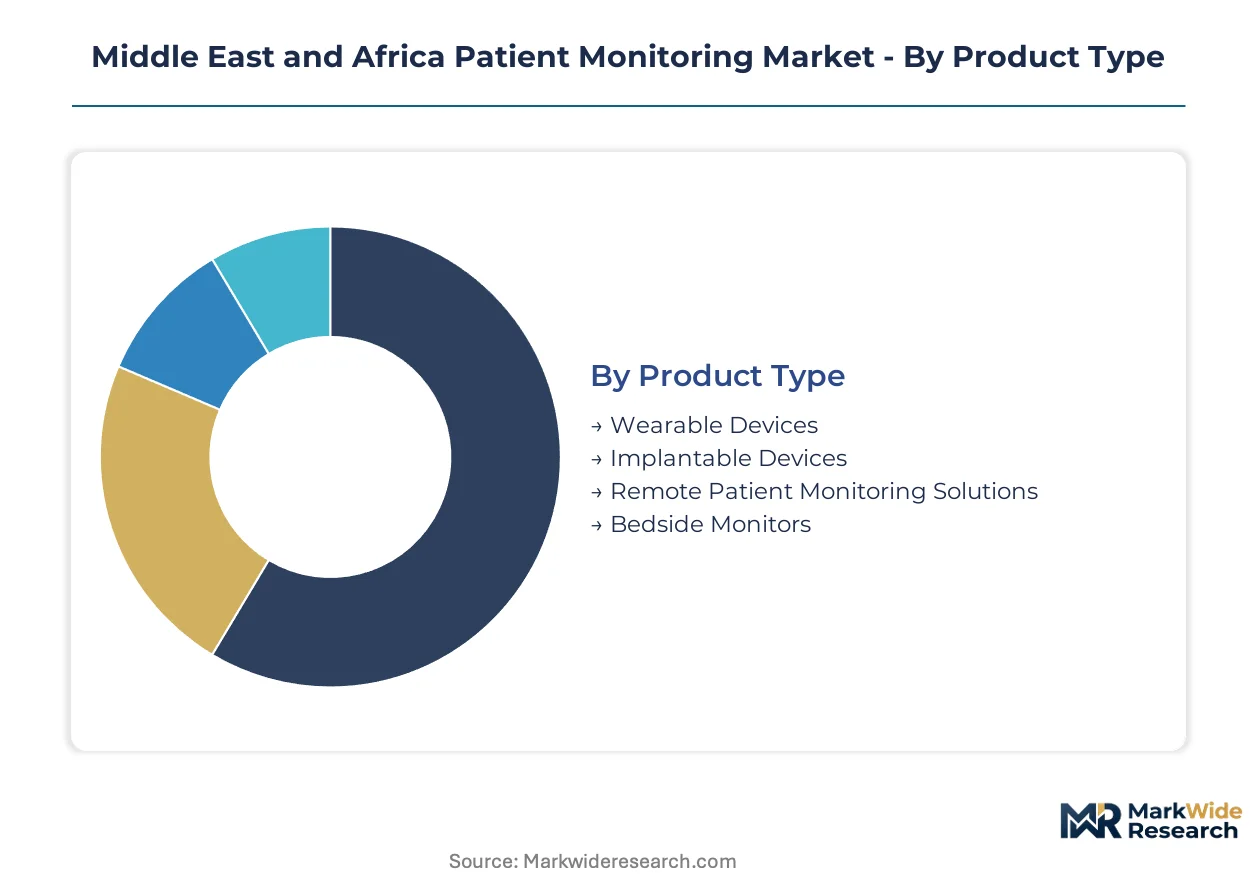
Patient monitoring procurement across the Middle East and Africa follows distinct technical and economic logics that reshape vendor positioning. Hospital networks prioritize interoperability standards while home care expansion creates parallel demand for simplified, durable form factors suited to regional climate and infrastructure conditions.
Product Type:
Purchase committees weigh total cost of ownership against clinical workflow integration when selecting device categories.
- Remote Patient Monitoring Solutions:Ward-to-cloud telemetry infrastructure captures continuous physiological data for post-acute surveillance. Saudi Arabia's SFDA mandates for cardiac patient monitoring are accelerating tertiary hospital deployments across Riyadh and Jeddah medical cities.
- Wearable Devices:Ambulatory form factors incorporate Bluetooth Low Energy modules with extended battery architectures for hot-climate durability. UAE and Qatar health systems are scaling these devices into primary care networks for diabetes and cardiovascular program management.
- Implantable Devices:Biocompatibility certification requirements and sterile manufacturing protocols elevate per-unit value. South Africa's SAHPRA audit timelines extend working capital cycles for manufacturers.
- Bedside Monitors:Multi-parameter integration systems sustain margin concentration in tertiary critical care installations where real-time multi-vital capture commands premium positioning.
Bedside monitors lead on scale; remote patient monitoring solutions lead on momentum.
Technology:
Data transmission architecture determines regulatory pathway complexity and hospital IT integration feasibility.
- Bluetooth:Medical-grade BLE implementations enable 30-day battery life in ambulatory configurations. Gulf Cooperation Council procurement specifications now mandate this standard for wearable cardiac deployments.
- Cloud Computing:Unified data platforms aggregate physiological signals across acute, ambulatory, and home settings. Dubai Health Authority networks are unbundling hardware from service contracts to enable multi-brand ecosystem integration.
- Wireless Technology:Broader radio-frequency protocols support legacy hospital infrastructure compatibility. Egyptian public hospitals require custom middleware development for 1990s-era patient data management system integration.
- Telemetry:Medical-grade wireless transmission enables real-time ward-to-cloud pipelines for critical care surveillance. SFDA guidelines are institutionalizing this capability in Saudi tertiary facilities.
Bluetooth dominates current procurement volumes; cloud computing is climbing the fastest as health systems consolidate data architectures.
End User:
Facility type dictates device specification, reimbursement pathway, and vendor service contract structure.
- Hospitals:Tertiary institutions command multi-parameter monitoring suites with embedded telemetry. Centralized Gulf procurement tenders favor vendors offering long-term maintenance bundling.
- Home Care Settings:Post-acute surveillance demand is expanding as readmission penalty frameworks mature. South African retail pharmacy chains are establishing direct-to-patient rental models for sleep apnea monitoring.
- Clinics:Primary care networks across Gulf states are integrating connected glucose and ECG platforms for chronic disease surveillance programs.
- Long-term Care Facilities:Extended-stay institutions require durable monitoring with simplified operator interfaces. Nigeria's national health insurance expansion is opening tender channels for low-cost vital signs capture.
Hospitals anchor revenue concentration; home care settings are gaining share fastest on policy-driven surveillance mandates.
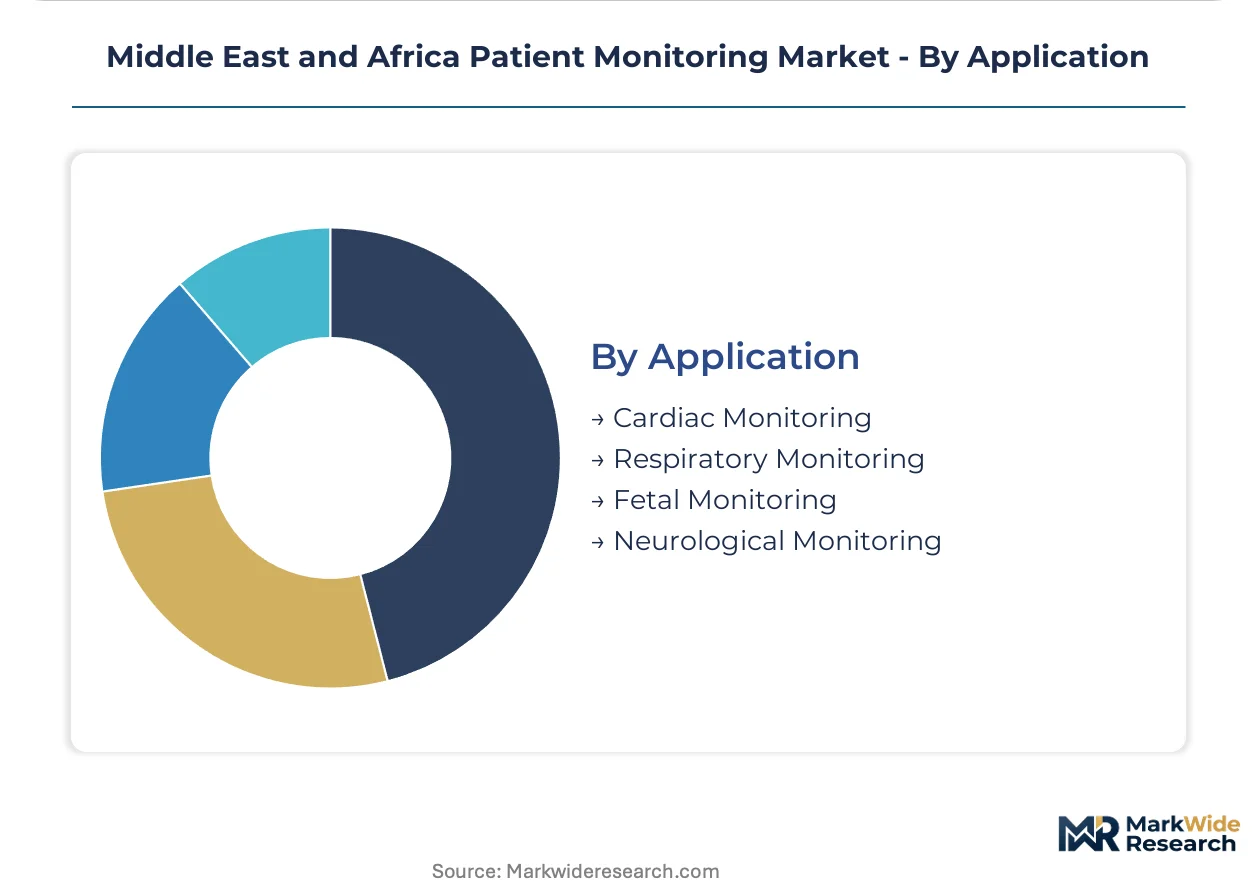
Application:
Clinical use case determines sensor specification, alarm algorithm complexity, and regulatory documentation requirements.
- Cardiac Monitoring:Electrocardiography systems with 250 Hz sampling rates and real-time artifact rejection address arrhythmia detection. Edge computing algorithms embedded in bedside monitors are reducing false alarm rates in Saudi critical care units.
- Respiratory Monitoring:Capnography modules with solid-state infrared sensing are displacing electrochemical analyzers. King Faisal Specialist Hospital has standardized these across Riyadh cardiac surgery wards.
- Neurological Monitoring:Cerebral function assessment requires specialized electrode configurations and signal processing. SAHPRA electromagnetic compatibility standards govern wireless-enabled device market access.
- Fetal Monitoring:Obstetric surveillance combines cardiotocography with maternal vital signs integration. Procurement concentrates in tertiary maternity centers across UAE and Saudi Arabia.
Cardiac monitoring commands the largest installed base; respiratory monitoring shows steepest expansion trajectory on solid-state technology displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineering talent pools cluster in South Africa and the Gulf states, anchoring firmware development for cardiac sampling architectures while Egyptian and Nigerian markets expand procurement capacity through health insurance reforms.
Saudi Arabia
Tertiary hospital networks in Riyadh and Jeddah medical cities are scaling ward-to-cloud telemetry infrastructure. SFDA remote monitoring guidelines mandate post-acute surveillance for cardiac patients, institutionalizing institutional demand. King Faisal Specialist Hospital and Research Centre has standardized solid-state capnography modules across its Riyadh cardiac surgery wards.
United Arab Emirates
Dubai Health Authority networks are unbundling hardware acquisition from long-term service contracts to enable multi-brand monitoring ecosystems. MOHAP enforces electromagnetic compatibility and cybersecurity standards including software bill of materials disclosure for wireless-enabled devices. Procurement committees across Dubai's public-private partnership hospitals now mandate 10-year total cost of ownership analyses.
South Africa
Retail pharmacy chains are establishing direct-to-patient rental models for home sleep apnea monitoring, bypassing hospital procurement bottlenecks. SAHPRA sterile manufacturing audits for implantable devices extend 18-24 months, elevating working capital requirements. Cape Town and Johannesburg medical device distributors face 12-week lead time volatility on analog-to-digital converters and MEMS sensors.
Egypt
Public hospitals require custom middleware development for HL7 FHIR interoperability with 1990s-era patient data management systems, extending deployment timelines. National regulators are adopting European MDR technical documentation requirements, compressing market access windows for CE-marked devices. Cairo-based procurement departments are consolidating tenders for low-cost pulse oximetry devices.
Nigeria
Federal health insurance coverage mandates for rural primary care are opening tender channels for low-cost vital signs capture devices. Lagos and Abuja hospital networks are expanding chronic disease surveillance programs for diabetes and cardiovascular conditions. The national medicines regulatory authority is harmonizing standards with the broader African Medicines Regulatory Harmonization initiative.
Middle East and Africa Patient Monitoring Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Middle East and Africa patient monitoring market, creating a tiered structure where imaging-service infrastructure bundling clashes with wearable form factor innovation. Hospital procurement consolidation favors vendors offering multi-parameter monitoring suites with embedded telemetry and long-term maintenance contracts. Three archetypes dominate: diversified medical technology conglomerates with established service networks, cardiac-focused device specialists with implantable portfolios, and emerging connectivity-platform vendors. Competitive moves concentrate on strategic partnerships for local regulatory navigation and portfolio diversification into metabolic tracking platforms.
Among diversified medical technology conglomerates, GE Healthcare and Koninklijke Philips NV exemplify contrasting approaches to regional market penetration. GE Healthcare leverages its established imaging-service infrastructure to bundle monitoring hardware with long-term maintenance contracts across Gulf hospital networks. Philips anchors its competitive position through intensive allocation toward wearable cardiac form factors suited to hot-climate durability requirements in UAE and Qatar. Medtronic occupies a distinct position extending its diabetes monitoring portfolio into broader metabolic tracking platforms for hospital networks. These three companies represent the dominant competitive anchors shaping procurement dynamics across Saudi Arabia, the UAE, and South Africa.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips NV |
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Becton Dickinson and Company |
| Siemens Healthcare GmbH |
| OMRON Corporation |
| Nihon Kohden Corporation |
| Others |
Value Chain & Pricing Dynamics
MEMS sensor pricing indices from East Asian foundries cascade through procurement tiers into three distinct cost structures across Gulf hospital networks and African distributor channels. Biocompatibility certification grades and telemetry module specifications segment hardware into premium, standard, and economy positioning, with semiconductor volatility compressing margins at the entry tier.
Pricing Analysis
The bundled-versus-unbundled service split now dominates procurement negotiations across Dubai Health Authority networks and Saudi tertiary facilities. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier and after-sales maintenance bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because Gulf centralized tenders favor multi-parameter suites with embedded telemetry. Public-private partnership hospitals exhibit lowest price sensitivity due to 10-year total cost of ownership mandates, while Nigerian rural primary care tenders show highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Firmware engineering talent scarcity in South Africa and the Gulf states constrains manufacturing scale-up for cardiac sampling architectures at 250 Hz specifications. Analog-to-digital converters and MEMS sensors draw from Taiwan, South Korea, and Japan, with sterile manufacturing protocols for implantable devices resting on specialized cleanroom capacity in Germany and Switzerland. Single-source vulnerability in BLE module supply creates exposure for wearable device producers targeting UAE and Qatar deployments. Distribution runs through Cape Town and Johannesburg medical device distributors serving sub-Saharan markets, with direct hospital contracting dominating Gulf procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cloud-platform unbundling that shifts revenue toward recurring service streams and away from commoditized hardware tiers. Solid-state capnography displacement of electrochemical sensors illustrates how premium-tier technology shifts capture maintenance revenue from legacy replacement cycles.
For Market Incumbents: Deploy long-term maintenance contract bundling to defend installed base positions against emerging connectivity-platform vendors. Deepen backward integration into medical-grade BLE module sourcing to reduce exposure to East Asian foundry lead time volatility. Anchor defensive positioning through SAHPRA and SFDA certification investments that extend audit timelines for challengers.
For New Entrants and Emerging Players: Begin with Nigeria's national health insurance rural primary care tenders, where low-cost pulse oximetry and temperature monitoring devices face minimal incumbent saturation. Target South African retail pharmacy rental models for home sleep apnea monitoring as the most penetrable channel bypassing hospital procurement bottlenecks. Pursue direct-to-patient go-to-market angles that circumvent centralized Gulf tender consolidation.
For Investors and Strategic Acquirers: Asymmetric upside sits with connectivity-platform vendors possessing edge computing algorithm capabilities for AI-enabled arrhythmia detection. Long-term viability over the projection horizon favors acquisition targets with established HL7 FHIR interoperability middleware for Egyptian public hospital integration. Watch SAHPRA-SFDA-MOHAP regulatory harmonization progress as the inflection signal for cross-border scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Accelerates market access for cardiac telemetry devices in Saudi tertiary hospitals. |
| Cloud Platform Unbundling | Enables multi-brand ecosystem integration across Dubai Health Authority networks. |
| BLE Module Supply Agreement | Secures 30-day battery life specifications for hot-climate wearable deployments. |
| Pharmacy Retail Partnership | Opens direct-to-patient channels for home sleep apnea monitoring in South Africa. |
| AI Algorithm Development | Reduces false alarm rates in Saudi critical care units through edge computing. |
Study Parameters
Multiple input streams — hospital procurement database analysis, regulatory filing review, and distributor channel mapping — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and SFDA regulatory affairs leads. Secondary validation drew from SFDA remote monitoring guidelines, SAHPRA electromagnetic compatibility standards, Dubai Health Authority tender disclosures, and African Medicines Regulatory Harmonization initiative documentation. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology architecture, end-user facility tier, and clinical application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by procurement volume concentration in Saudi Arabia, UAE, and South Africa. Forecast inputs incorporated SFDA mandate implementation timelines, national health insurance coverage expansion rates, and semiconductor supply lead time volatility assumptions.
Several conditions sit outside the modeled scope, including abrupt regulatory harmonization reversals, Gulf sovereign wealth fund healthcare privatization policy shifts, and pandemic-era emergency procurement reinstatements. Forecasts reflect documented assumptions regarding chronic disease surveillance program scaling and BLE battery life advancement curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
Blood Temperature Indicator Market