
 Germany Neurology Devices Market | 2026-2036
Germany Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Neurology Devices Market Foresight
Polymer-based biocompatible coatings is hardening as the preferred barrier material over traditional metal interfaces in implantable neurostimulators, reducing corrosion risk and extending device longevity. Medtronic PLC leverages its deep manufacturing footprint in Germany to sustain local production of invasive implantable systems. Stryker Corporation anchors its European neurology portfolio through specialized hospitals and rehabilitation centers. Abbott Laboratories differentiates with wireless-enabled diagnostic platforms that compete across outpatient and inpatient settings.
Germany neurology devices comprise instruments and systems designed to monitor, diagnose, or modulate nervous system function, typically operating at signal frequencies below 10 kHz for EEG and EMG acquisition with electrode impedances under 5 kΩ for clinical-grade measurement. These devices serve to detect epileptiform activity, restore motor function through electrical stimulation, or assess nerve conduction velocity for diagnostic certainty. Neurostimulators command substantial margin pools due to long implant lifecycles and recurring programming services, while AI-enabled technology segments attract fastest-growing demand from diagnostic labs seeking automated seizure detection. Wearable formats remain nascent in reimbursement coverage but occupy expanding roles in sleep disorder diagnosis within home-based monitoring protocols.
CE marking under the EU MDR and Germany's BfArM registration requirements shape market access timelines, with notified body capacity constraints extending conformity assessment durations for novel implantable devices. The G-BA's benefit assessment framework for medical devices determines reimbursement eligibility, directly influencing hospital procurement decisions and manufacturer commercialization strategies. Stakeholders must monitor evolving NIS2 cybersecurity mandates for connected neurology devices and anticipate how BfArM real-world evidence requirements will reshape post-market clinical follow-up obligations.
Market Dynamics
EU MDR transition timelines and BfArM registration bottlenecks are compressing market entry windows for novel implantable neurostimulators, forcing manufacturers to front-load clinical evidence generation and restructure European distribution footprints around notified body capacity constraints.
Growth Catalysts
- Bavaria university hospital clusters:Clinical trial volumes in Erlangen and Munich accelerate early technology validation for movement disorder devices, creating reference sites that drive downstream adoption across German-speaking regions.
- G-BA reimbursement reforms:The benefit assessment framework for medical devices now explicitly covers digital therapeutics and AI-enabled diagnostics, expanding addressable markets for automated seizure detection platforms.
- Polymer-based biocompatible coatings:These materials reduce corrosion risk in implantable neurostimulators, extending device longevity and reducing revision surgery rates that strain hospital budgets.
Market Restraints
- Notified body capacity shortages:EU MDR conformity assessment durations for novel implantable devices now extend 18-24 months, freezing commercialization timelines and capital deployment.
- Platinum-iridium electrode supply:Concentration of refined precious metal sourcing in South Africa creates input cost volatility for deep brain stimulation leads.
- Reimbursement lag for wearables:Home-based sleep disorder monitors lack G-BA coverage codes, forcing out-of-pocket payment and limiting addressable patient populations.
Strategic Opportunities
- North Rhine-Westphalia rehabilitation networks:Post-stroke care infrastructure in Cologne-Düsseldorf corridor remains undersupplied with robotic neurorehabilitation systems, creating first-mover advantages for integrated device-therapy platforms.
- NIS2 cybersecurity mandates:Connected neurology devices face new technical documentation requirements that favor manufacturers with pre-built secure-by-design architectures.
- AI-EEG convergence:Automated epileptiform detection algorithms trained on German hospital data lakes enable point-of-care diagnostics that bypass centralized neurophysiology lab bottlenecks.
Industry Challenges
- Clinical neurophysiologist shortages:German university programs graduate insufficient specialists to operate expanding EMG/EEG service lines, forcing device manufacturers to embed automated interpretation software.
- Legacy hospital IT integration:Epilepsy monitoring units run proprietary data formats that resist interoperability with cloud-based AI platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Neurology Devices Market |
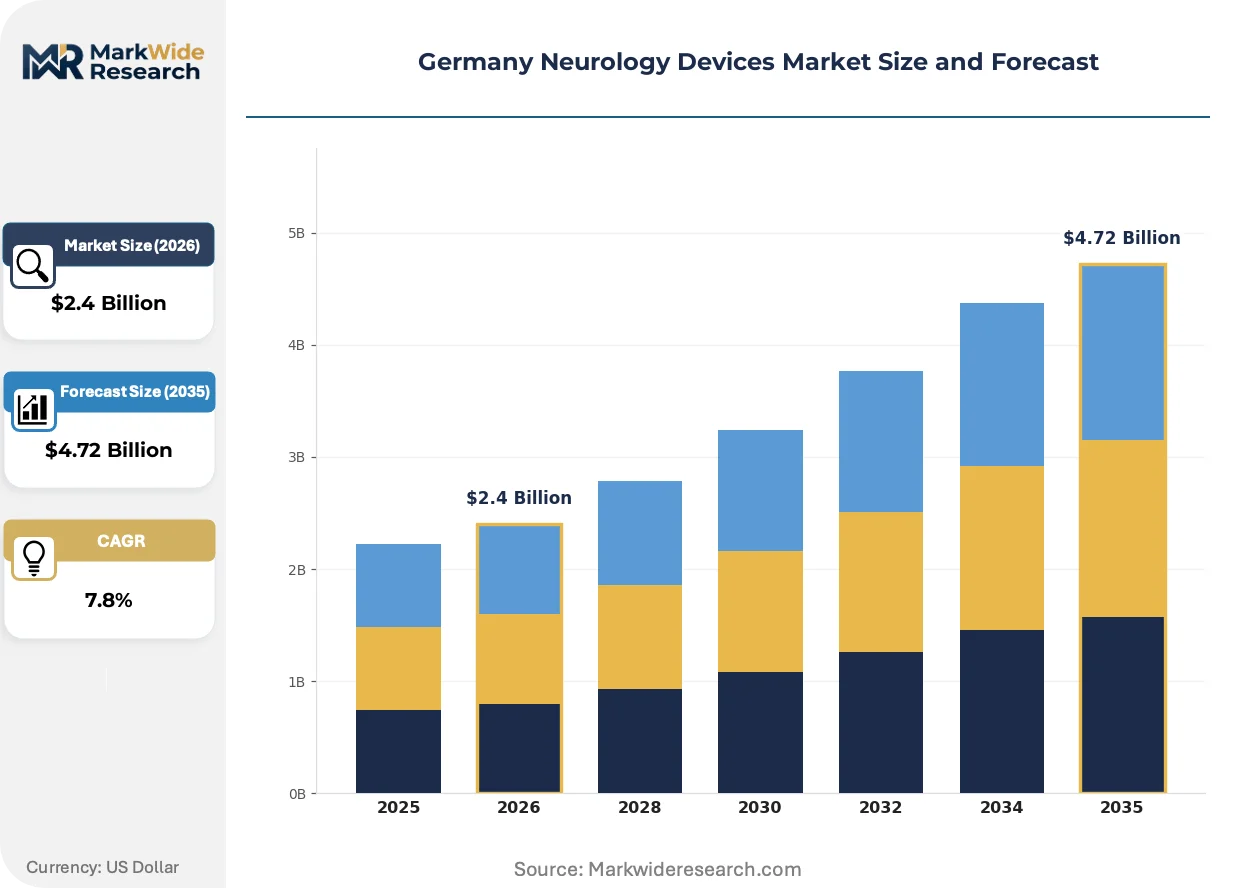
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Devices, Neurostimulators, EMG Devices, Nerve Conduction Equipment, Cranial Electrotherapy Stimulators Technology: Non-Invasive, Invasive Implantable, Wearable, Wireless, AI-Enabled Application: Seizure Monitoring, Neuropathic Pain Management, Stroke Rehabilitation, Movement Disorder Treatment, Sleep Disorder Diagnosis End User: Neurology Clinics, Research Institutes, Diagnostic Labs, Rehabilitation Centers, Specialized Hospitals |
| Companies Covered | B. Braun Melsungen AG, Johnson & Johnson, Medtronic PLC, Penumbra, Inc., Integra LifeSciences Holdings Corporation, Stryker Corporation, Abbott Laboratories, Terumo Corporation, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Neurology Devices Market Shifts & Advancements
Neurology device development is pivoting from hardware-centric margins toward software-enabled recurring revenue, with AI diagnostics and remote programming services capturing value previously locked in implantable hardware replacement cycles.
Closed-loop adaptive neurostimulation is consolidating competitive positioning around real-time biomarker feedback. Deep brain stimulation systems now incorporate local field potential sensing that automatically adjusts therapeutic output. University hospitals in Heidelberg and Tübingen prioritize these platforms for Parkinson's disease protocols, compressing differentiation timelines for manufacturers lacking sensing-enabled hardware portfolios.
EU MDR post-market surveillance requirements are extending clinical follow-up obligations for implantable neuromodulators. Manufacturers must now submit periodic safety update reports with real-world evidence from German implant registries. Active implantable device segments face the steepest compliance cost escalation, with small-cap specialists exiting rather than funding expanded quality management systems.
Hospital procurement departments are unbundling device acquisition from programming service contracts. Previously bundled 5-year service agreements now separate into capital equipment purchases and per-procedure technical support fees. This shift is most visible in North Rhine-Westphalia, where hospital group purchasing organizations negotiate hardware discounts independently from clinical training and remote monitoring subscriptions.
Germany Neurology Devices Market Segmentation
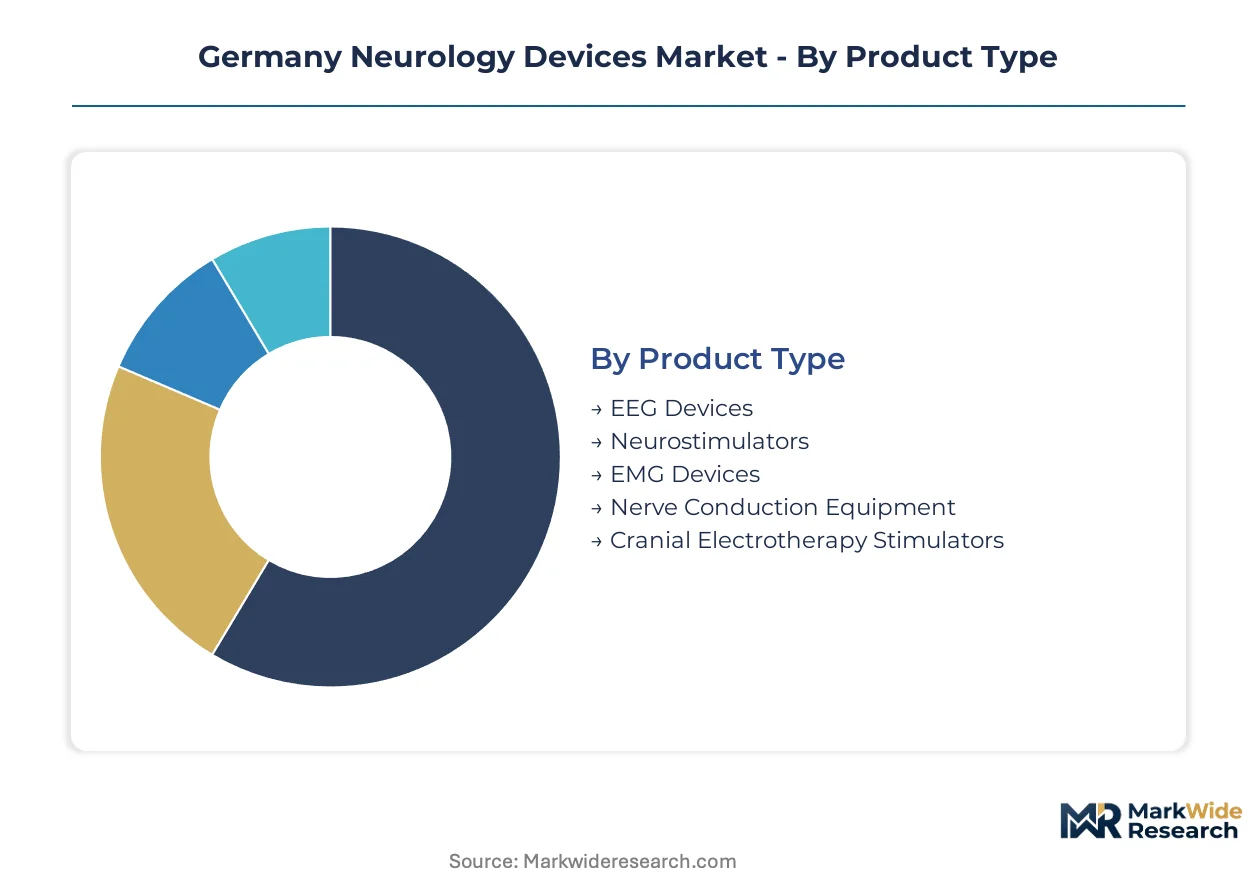
Neurology device procurement in Germany follows distinct pathways across clinical settings, with reimbursement codes and MDR compliance requirements fragmenting addressable markets. Manufacturers must align product architectures to specific end-user workflows rather than deploying universal platforms.
Product Type:
Volume concentration sits with diagnostic hardware, while margin pools cluster around implantable therapeutic systems requiring long-term service relationships.
- EEG Devices:Multi-channel electroencephalography systems acquire cortical signals below 10 kHz with electrode impedances under 5 kΩ for clinical-grade measurement. Bavaria university hospital clusters in Erlangen and Munich deploy high-density arrays for epilepsy surgical planning, driving demand for research-grade specifications that cascade into community hospital procurement standards.
- Neurostimulators:Implantable pulse generators deliver electrical modulation to central or peripheral nervous system targets through leads with platinum-iridium electrodes. Deep brain stimulation systems for Parkinson's disease command premium pricing in Heidelberg and Tübingen movement disorder centers, where closed-loop adaptive platforms compress competitive differentiation timelines.
- EMG Devices:Electromyography systems measure skeletal muscle electrical activity through needle or surface electrodes for diagnostic certainty in neuromuscular disorders.
- Nerve Conduction Equipment:Peripheral nerve stimulation and recording systems assess conduction velocity for carpal tunnel syndrome and radiculopathy diagnosis.
- Cranial Electrotherapy Stimulators:Transcranial electrical stimulation devices deliver low-intensity current for anxiety and insomnia management through outpatient protocols.
Today's leader: Neurostimulators. Tomorrow's challenger: AI-integrated EEG platforms.
Technology:
Regulatory burden scales with invasiveness, concentrating fastest development velocity in non-invasive and wearable formats where MDR pathways remain streamlined.
- Non-Invasive:External neuromodulation and diagnostic systems operate without breach of skin or skull, encompassing transcranial magnetic stimulation and surface EMG. Diagnostic labs across North Rhine-Westphalia prioritize these platforms for throughput scalability where clinical neurophysiologist shortages constrain service expansion.
- Invasive Implantable:Active implantable medical devices require BfArM registration and EU MDR Class III conformity assessment with extended clinical follow-up obligations. Manufacturers face 18-24 month notified body capacity bottlenecks that freeze commercialization timelines for novel movement disorder and pain management systems.
- Wearable:Ambulatory monitoring formats for sleep disorder diagnosis and seizure detection lack G-BA reimbursement coverage, forcing out-of-pocket payment models.
- Wireless:Bluetooth and proprietary radio-enabled devices transmit diagnostic data to cloud platforms for remote monitoring and automated analysis.
- AI-Enabled:Machine learning algorithms trained on German hospital data lakes enable automated epileptiform detection and predictive seizure forecasting.
Non-invasive platforms anchor current procurement volumes. AI-enabled systems are climbing the fastest as diagnostic labs seek automated interpretation to offset specialist shortages.
Application:
Reimbursement density varies sharply across clinical indications, with stroke rehabilitation and movement disorder treatment capturing prioritized G-BA benefit assessment pathways.
- Seizure Monitoring:Continuous EEG and video-telemetry systems for epilepsy diagnosis and surgical candidacy evaluation. Specialized hospitals in Bavaria operate high-volume monitoring units that generate reference data for algorithm training and clinical protocol standardization.
- Neuropathic Pain Management:Spinal cord stimulation and peripheral nerve field stimulation for chronic pain refractory to pharmacotherapy. Implant lifecycle economics favor manufacturers with established service infrastructures in German-speaking regions.
- Stroke Rehabilitation:Robotic neurorehabilitation systems and functional electrical stimulation for motor recovery. The Cologne-Düsseldorf corridor remains undersupplied with integrated device-therapy platforms, creating first-mover advantages for vendors with comprehensive training programs.
- Movement Disorder Treatment:Deep brain stimulation for Parkinson's disease, essential tremor, and dystonia.
- Sleep Disorder Diagnosis:Polysomnography and home sleep apnea testing for obstructive sleep apnea and narcolepsy.
Stroke rehabilitation offers the steepest expansion trajectory. Sleep disorder diagnosis faces reimbursement headwinds limiting near-term addressable populations.
End User:
Procurement authority concentrates in hospital group purchasing organizations, while research institutes drive early technology validation that shapes downstream clinical adoption.
- Specialized Hospitals:Academic medical centers and dedicated neurology hospitals with comprehensive epilepsy monitoring units and deep brain stimulation programs. University hospital clusters in Heidelberg, Tübingen, Erlangen, and Munich function as reference sites whose protocol choices cascade into community hospital standards across German-speaking Europe.
- Neurology Clinics:Outpatient-focused practices delivering diagnostic workup and non-invasive therapy. These settings prioritize portable EMG and EEG systems with streamlined workflows over research-grade specifications.
- Rehabilitation Centers:Post-acute care facilities in North Rhine-Westphalia managing stroke recovery and neurodegenerative disease progression.
- Diagnostic Labs:Centralized neurophysiology services processing EMG, EEG, and nerve conduction studies for referring physicians.
- Research Institutes:Academic and industry-sponsored clinical trial sites conducting pivotal studies for EU MDR compliance and G-BA benefit assessment.
Specialized hospitals dominate high-value procurement. Rehabilitation centers represent the most underpenetrated addressable market for robotic neurorehabilitation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's university hospital clusters in Erlangen and Munich anchor Germany's neurology device demand, generating clinical trial volumes that cascade into procurement standards across German-speaking Europe.
Bavaria
Deep brain stimulation programs at Erlangen and Munich academic medical centers drive movement disorder device validation. BfArM registration requirements for active implantables compress commercialization timelines for novel neurostimulators. The Nuremberg-Munich corridor concentrates manufacturing footprints for invasive implantable systems serving Parkinson's disease protocols.
North Rhine-Westphalia
Post-stroke rehabilitation infrastructure in the Cologne-Düsseldorf corridor remains undersupplied with robotic neurorehabilitation systems. G-BA reimbursement reforms for digital therapeutics expand addressable markets for AI-enabled diagnostic platforms. Hospital group purchasing organizations in Düsseldorf negotiate hardware discounts independently from service contracts.
Baden-Württemberg
Heidelberg and Tübingen movement disorder centers prioritize closed-loop adaptive neurostimulation with local field potential sensing. EU MDR post-market surveillance requirements extend clinical follow-up obligations for implant registries. The Stuttgart-Karlsruhe axis hosts quality management system providers serving small-cap device specialists.
Hesse
Frankfurt's diagnostic lab networks seek automated EEG interpretation to offset clinical neurophysiologist shortages. NIS2 cybersecurity mandates for connected devices favor manufacturers with secure-by-design architectures. The Rhine-Main metropolitan region concentrates outpatient neurology clinics deploying portable EMG systems.
Berlin-Brandenburg
Research institutes in Berlin conduct pivotal studies for EU MDR compliance and G-BA benefit assessments. Notified body capacity constraints delay conformity assessments for novel wearable seizure monitors. The capital region's epilepsy monitoring units generate reference data for algorithm training across federal procurement networks.
Germany Neurology Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities, with consolidated implantable segments contrasting fragmented diagnostic hardware tiers. Market structure reflects tiered positioning around MDR readiness, reimbursement navigation, and service infrastructure depth. Three archetypes dominate: diversified multinationals with captive notified body relationships, mid-cap specialists with university hospital anchor accounts, and emerging AI-platform vendors with software-enabled recurring models. Competitive moves concentrate on M&A for notified body capacity access and strategic partnerships for real-world evidence generation.
Within the diversified multinational tier, Medtronic PLC and Stryker Corporation exemplify archetypes built on manufacturing footprint depth and hospital system integration respectively. Abbott Laboratories occupies a position bridging diagnostic and therapeutic segments with wireless-enabled platform architectures. These three anchors represent contrasting strategic postures: local production leverage, specialized hospital channel control, and convergent technology portfolios spanning inpatient and outpatient settings.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Johnson & Johnson |
| Medtronic PLC |
| Penumbra, Inc. |
| Integra LifeSciences Holdings Corporation |
| Stryker Corporation |
| Abbott Laboratories |
| Terumo Corporation |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap device specialists in Baden-Württemberg anchor supply-side discipline through captive precision-manufacturing assets, enabling pricing power that resists commodity erosion while EU MDR compliance costs concentrate procurement decisions among notified body-preferred vendors.
Pricing Analysis
Platinum-iridium electrode cost pass-through from South African concentrate suppliers compresses margins on deep brain stimulation leads, forcing manufacturers toward polymer-based biocompatible coating alternatives. Three-tier pricing structure across premium closed-loop adaptive systems, standard programmable neurostimulators, and economy fixed-output devices separates university hospital procurement from community hospital budgets. Pricing pressure stems from hospital group purchasing organizations unbundling hardware from service contracts in North Rhine-Westphalia. Rehabilitation centers exhibit highest price sensitivity due to G-BA reimbursement lag for robotic neurorehabilitation systems.
Supply Chain Analysis
Freight cost volatility on precision electronics from Taiwan and South Korea disrupts just-in-time delivery schedules for EEG amplifier components destined to Bavaria manufacturing clusters. Active implantable pulse generators draw from Swiss microcontroller foundries and Irish sterile packaging facilities, creating EU-internal dependency chains. Single-source vulnerability concentrates in South African platinum-iridium refining for neurostimulation electrodes. Distribution runs through specialized hospital procurement networks with direct manufacturer relationships bypassing traditional medtech distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's neurology device market functions as a geographic-arbitrage play where EU MDR compliance investments in Heidelberg and Tübingen clinical registries yield faster G-BA reimbursement decisions than equivalent spending in Southern European markets with weaker notified body access.
For Market Incumbents: Anchor defensive positioning through backward integration into polymer-based biocompatible coating production, eliminating precious metal cost volatility that threatens deep brain stimulation margins. Secure captive notified body relationships by acquiring small-cap specialists facing EU MDR quality management system cost escalation. Threat concentration sits with AI-platform vendors automating epileptiform detection that bypasses proprietary hardware ecosystems. For New Entrants and Emerging Players: Rehabilitation center networks in the Cologne-Düsseldorf corridor offer the most penetrable white-space, with undersupplied robotic neurorehabilitation systems and unbundled service contract structures lowering incumbent lock-in. Target AI-EEG convergence for diagnostic labs facing clinical neurophysiologist shortages. Go-to-market angle should emphasize secure-by-design architectures that preempt NIS2 cybersecurity mandate compliance costs. For Investors and Strategic Acquirers: Valuations sit cheapest among small-cap implantable specialists exiting rather than funding expanded EU MDR post-market surveillance obligations. Long-term viability over a multi-year window hinges on software-enabled recurring revenue models displacing hardware replacement cycles. Watch BfArM real-world evidence requirement implementation as the inflection signal determining which notified body relationships convert to sustainable competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III conformity assessment timelines determine commercialization windows for novel neurostimulators. |
| Hospital System Partnership | University hospital clusters in Bavaria generate reference data that cascades into German-speaking procurement standards. |
| Software Companion Development | AI-enabled epileptiform detection platforms capture value from diagnostic lab automation demand. |
| Reimbursement Strategy | G-BA benefit assessment navigation determines addressable patient populations for wearable sleep monitors. |
| Backward Integration | Captive polymer-based biocompatible coating production insulates margins from platinum-iridium volatility. |
Research Methodology
Coverage spans Germany's federal states with primary inputs from each major neurology device cluster, combining structured interviews with hospital purchasing committee members, biomedical engineers at university hospital clusters, GPO contracts managers in North Rhine-Westphalia, and regulatory affairs leads navigating BfArM registration pathways. Secondary validation draws from BfArM device registries, G-BA benefit assessment documentation, EU MDR notified body capacity reports, and hospital procurement database extracts. Bottom-up installation base modeling triangulates against top-down reimbursement code analysis.
Granularity-level framing applies product-type splits for neurostimulators, EEG devices, and EMG systems; technology tiers separating invasive implantable from AI-enabled formats; and end-user segmentation across specialized hospitals, rehabilitation centers, and diagnostic labs. CAGRs derive from installed base growth rates, replacement cycle compression, and service revenue attachment factors. Forecast inputs incorporate EU MDR transition timeline assumptions and G-BA digital therapeutics reimbursement expansion scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to notified body capacity constraints, platinum-iridium supply disruptions, and clinical neurophysiologist workforce expansion rates. Forecasts reflect documented assumptions regarding MDR implementation pacing and G-BA technology assessment criteria. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Spain Neurology Devices Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
UAE Neurology Devices Market
Neurology
CNS Treatment and Therapy Market
Neurology
Neurology Services Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Global Neuromarketing Market
Neurology
CNS Therapeutics Market
Neurology
Status Epilepticus Treatment Market
Neurology
Acute Repetitive Seizures Market
Neurology
CNS Lymphoma Market
Neurology
Chordoma Disease Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market