
 US Optic Neuritis Market | 2026-2036
US Optic Neuritis Market Size, Share, and Industry Trends Forecast 2026-2036
US Optic Neuritis Market Analytics
Neurology clinics is expanding their share of the patient pathway as referral networks consolidate around subspecialty centers. Mallinckrodt anchors its position through corticosteroid supply relationships with major hospital systems. AbbVie differentiates via immunotherapy R&D pipelines targeting underlying autoimmune triggers. Novartis competes through ophthalmology franchise extensions that bridge neuro-ophthalmology and multiple sclerosis care.
Optic neuritis denotes acute inflammatory demyelination of the optic nerve, typically presenting with subacute vision loss, pain with eye movement, and relative afferent pupillary defect; MRI with gadolinium enhancement serves as the diagnostic gold standard to detect optic nerve sheath inflammation and exclude compressive lesions. Corticosteroids dominate current prescribing patterns as the established acute intervention, while immunotherapy represents the fastest-growing treatment category as disease-modifying approaches gain traction in recurrent cases. Diagnosis method selection increasingly favors ocular MRI over fundoscopy alone, reflecting structural pressure for higher sensitivity in first-episode presentations.
FDA oversight shapes drug approval requirements for neuro-ophthalmology indications, while HIPAA governs patient data flows across the multi-site care teams typical in optic neuritis management. The country's national pharmaceutical regulator maintains stringent manufacturing standards for corticosteroid and immunotherapy production. Stakeholders must monitor how CMS reimbursement adjustments for outpatient neurology services reshape site-of-care economics between hospitals and private practices.
Market Dynamics
FDA accelerated approval pathways compress commercialization timelines for neuro-ophthalmology therapies, forcing manufacturers to front-load clinical evidence generation while academic medical centers consolidate referral networks around demyelinating disease specialists.
Growth Catalysts
- IRA Medicare drug pricing provisions:CMS reimbursement stability incentivizes hospital systems to expand outpatient neurology service lines for optic neuritis management.
- Immunotherapy pipeline maturation:Disease-modifying approaches targeting underlying autoimmune triggers gain prescriber traction in recurrent cases previously managed with corticosteroids alone.
- Northeast corridor demand concentration:Academic medical centers in Boston, New York, and Philadelphia anchor specialized referral networks that concentrate high-complexity cases.
Market Restraints
- Corticosteroid manufacturing concentration:Active pharmaceutical ingredient supply for methylprednisolone concentrates among a limited supplier base, creating vulnerability to quality enforcement actions.
- MRI gadolinium cost volatility:Contrast agent pricing fluctuations directly impact diagnostic workup economics for first-episode presentations.
- HIPAA compliance friction:Multi-site care team coordination across hospitals and private practices generates administrative burden that slows patient pathway velocity.
Strategic Opportunities
- Telemedicine-enabled rural penetration:Underserved markets in the Mountain West and Great Plains lack neuro-ophthalmology specialist density, creating white space for remote consultation models.
- Biomarker-guided patient stratification:Integration of aquaporin-4 and MOG antibody testing with MRI protocols enables precision immunotherapy selection.
- FDA breakthrough therapy designation:Expedited regulatory pathways reward sponsors investing in novel mechanisms for steroid-refractory or recurrent disease.
Industry Challenges
- Neuro-ophthalmology fellowship scarcity:The pipeline of subspecialty-trained clinicians fails to match referral network expansion, creating diagnostic bottleneck capacity constraints.
- Legacy EHR interoperability gaps:Multi-site care coordination requires data exchange between hospital systems and community neurology practices with incompatible technical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Optic Neuritis Market |
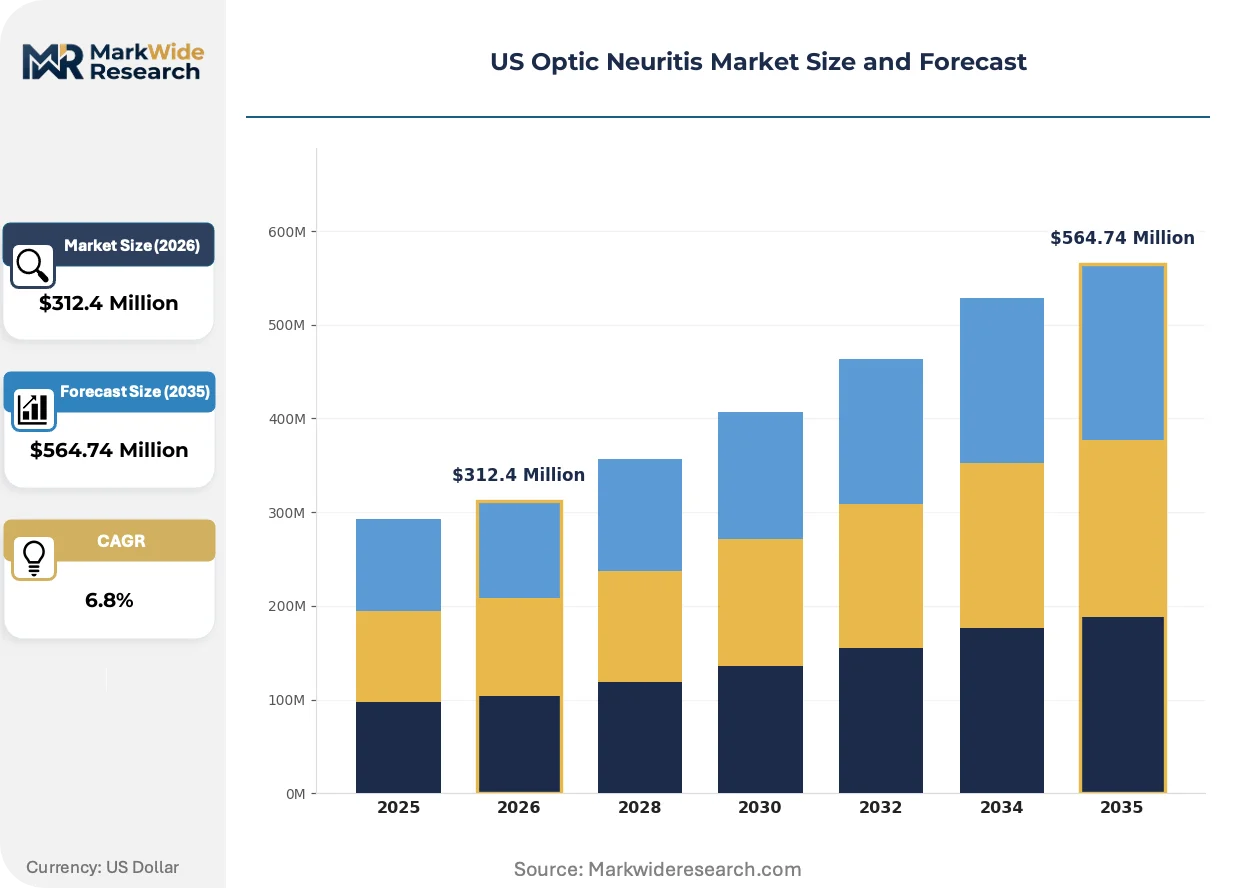
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Corticosteroids, Immunotherapy, Plasma Exchange, Nutritional Supplements Diagnosis Method: Ocular MRI, Visual Field Test, Fundoscopy, Electrophysiology End User: Neurology Clinics, Hospitals, Rehabilitation Centers, Private Practices Severity Level: Mild, Moderate, Severe, Recurrent |
| Companies Covered | Mallinckrodt, AbbVie, Novartis, Santen Pharmaceutical, Sanofi, Pfizer, Teijin Pharmaceutical, Oculis, Trethera Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Optic Neuritis Market Evolving Landscape
Artificial intelligence and advanced imaging analytics are compressing diagnostic timelines while regulatory frameworks adapt to accommodate novel therapeutic mechanisms in neuro-ophthalmology.
Machine learning algorithms applied to orbital MRI sequences are automating optic nerve sheath inflammation quantification, reducing radiologist interpretation time from hours to minutes. Major academic medical centers in the Northeast corridor deploy these tools for first-episode triage, enabling same-day treatment initiation that corticosteroid protocols require. This compression of diagnostic-to-treatment intervals is automating patient pathway logistics previously managed through manual scheduling coordination.
CMS reimbursement adjustments for outpatient neurology services reshape site-of-care economics, favoring hospital-based infusion centers over private practice settings for immunotherapy administration. The agency's facility fee differentials incentivize vertical integration of acute and chronic care within health system boundaries. Private practices in the Southeast and Midwest respond by affiliating with hospital networks or divesting infusion capabilities entirely.
Patient advocacy organizations drive certification-driven preference shifts, pressuring treatment centers to achieve multiple sclerosis center of excellence designation that encompasses optic neuritis management. Buyers now weight care team credentialing density heavily in referral decisions, displacing geographic convenience as the primary selection criterion. This behavioral change concentrates volume in designated centers across California, Texas, and the Northeast corridor, fragmenting the community neurology patient base.
US Optic Neuritis Market Segmentation
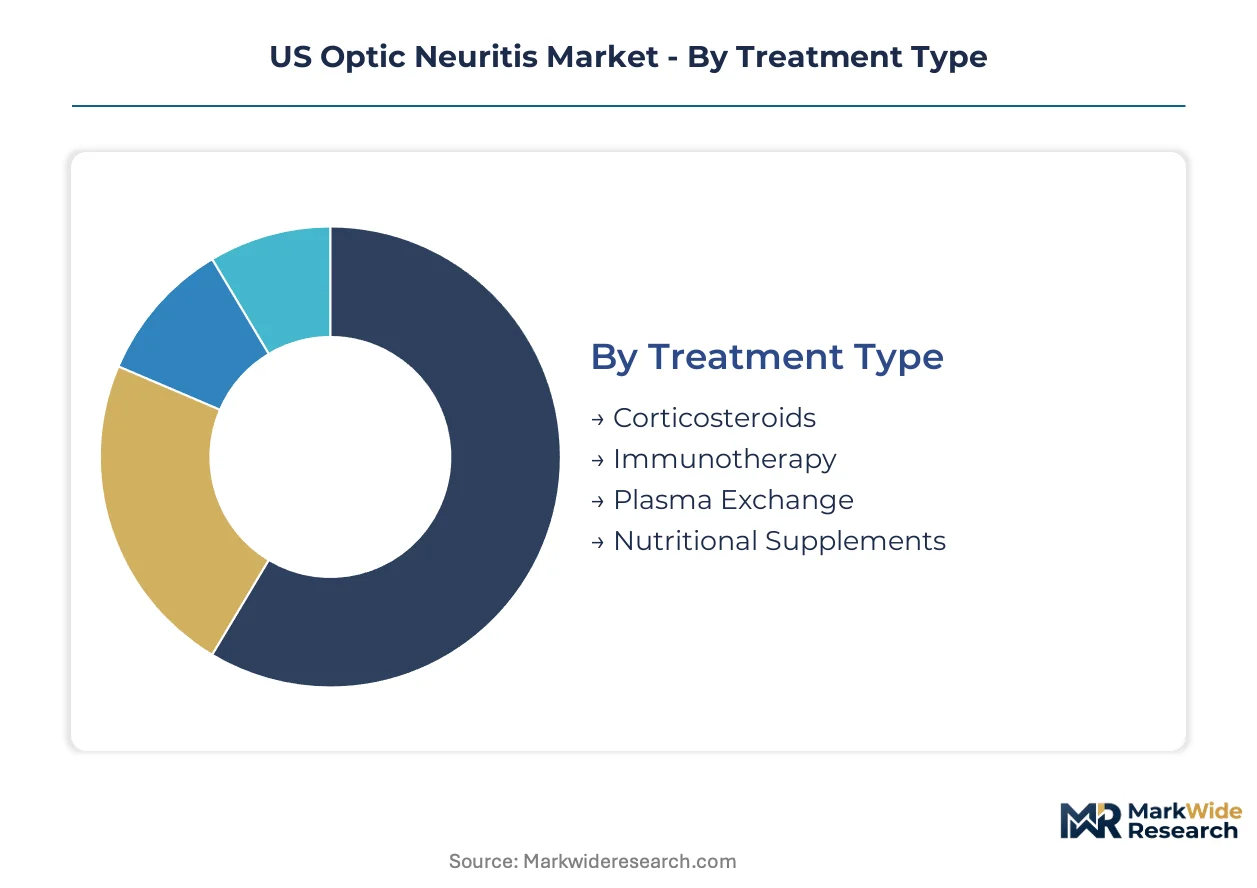
Optic neuritis management fragments across four distinct classification schemes that shape procurement patterns and site-of-care economics. Each segmentation layer reveals divergent margin profiles and regulatory exposure that manufacturers must navigate simultaneously.
Treatment Type:
Standardization dominates acute intervention protocols while chronic disease management tilts toward customized immunotherapy regimens.
- Corticosteroids:High-dose intravenous methylprednisolone remains the established first-line protocol for acute demyelinating episodes. Northeast corridor academic medical centers anchor demand through standardized infusion protocols that compress treatment windows to 3-5 days.
- Immunotherapy:Monoclonal antibodies and disease-modifying therapies target underlying autoimmune triggers in recurrent or steroid-refractory cases. FDA breakthrough therapy designations accelerate pipeline candidates addressing aquaporin-4 and MOG antibody-positive subpopulations.
- Plasma Exchange:Therapeutic apheresis serves as rescue therapy for severe corticosteroid-resistant presentations requiring rapid humoral factor removal.
- Nutritional Supplements:Adjunctive vitamin D and omega-3 formulations support neuroprotection protocols in outpatient maintenance settings.
Leading the category by volume: Corticosteroids. Expanding most quickly: Immunotherapy.
Diagnosis Method:
Cost tier stratification separates high-sensitivity structural imaging from functional assessment tools deployed in resource-constrained settings.
- Ocular MRI:Gadolinium-enhanced orbital sequences detect optic nerve sheath inflammation with superior sensitivity for first-episode presentations. Machine learning algorithms at Boston and New York academic centers now automate inflammation quantification, compressing radiologist interpretation from hours to minutes.
- Visual Field Test:Automated perimetry maps scotoma patterns to localize optic nerve dysfunction, serving as the functional complement to structural imaging.
- Fundoscopy:Direct optic disc examination remains accessible in community settings though sensitivity lags MRI for retrobulbar inflammation detection.
- Electrophysiology:Visual evoked potential testing quantifies optic nerve conduction velocity, supporting differential diagnosis in atypical presentations.
Dominant by procedure volume: Ocular MRI. Gaining share fastest: Electrophysiology integration with antibody biomarker panels.
End User:
Site-of-care economics drive patient pathway consolidation toward hospital-affiliated settings with infusion capabilities.
- Neurology Clinics:Subspecialty centers concentrate demyelinating disease expertise and anchor referral networks across the Northeast corridor. CMS facility fee differentials incentivize vertical integration of acute and chronic care within health system boundaries.
- Hospitals:Inpatient and emergency departments manage acute vision loss presentations requiring rapid corticosteroid initiation.
- Rehabilitation Centers:Post-acute facilities address residual visual dysfunction through low-vision therapy and adaptive training.
- Private Practices:Community neurology settings face affiliation pressure as independent infusion economics deteriorate under reimbursement adjustments.
Capturing highest case complexity: Neurology Clinics. Facing steepest consolidation pressure: Private Practices.
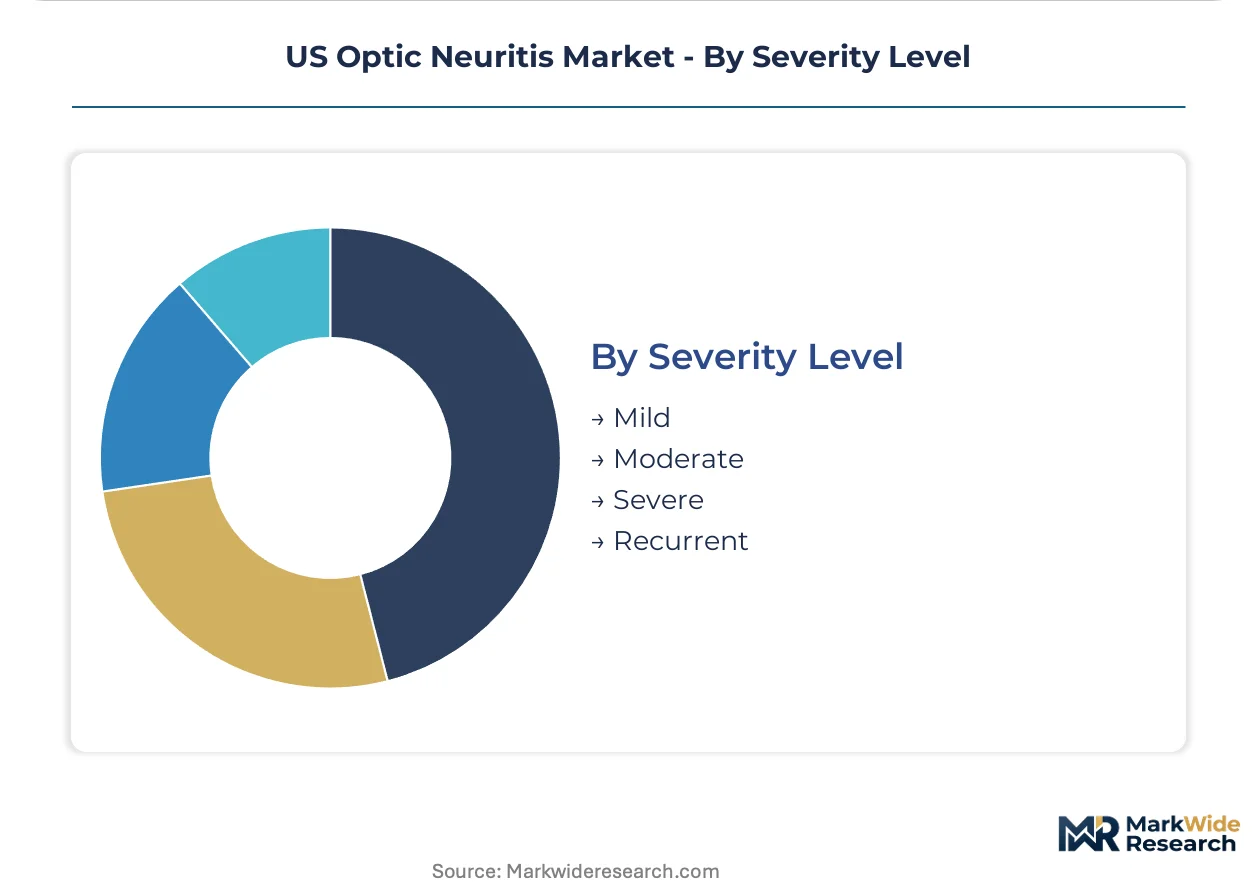
Severity Level:
Maturity gradients separate well-established acute protocols from emerging precision approaches in recurrent phenotypes.
- Mild:Subtle visual acuity decrements often managed with observation or abbreviated corticosteroid courses in outpatient settings.
- Moderate:Significant vision impairment triggers standard high-dose steroid protocols with structured follow-up imaging.
- Severe:Profound vision loss or bilateral involvement escalates to plasma exchange rescue therapy and expedited immunotherapy evaluation.
- Recurrent:Repeated episodes drive disease-modifying therapy selection guided by aquaporin-4 and MOG antibody stratification.
Highest protocol standardization: Moderate. Steepest therapeutic evolution: Recurrent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones across the Northeast corridor concentrate neuro-ophthalmology infrastructure through tax-advantaged capital deployment. Massachusetts, New York, and Pennsylvania anchor this concentration with overlapping hospital networks and research institutions. FDA regional offices in these states accelerate clinical trial site activation for demyelinating disease therapies.
Northeast Corridor
Academic medical centers in Boston, New York City, and Philadelphia generate concentrated demand for optic neuritis diagnostics and acute corticosteroid protocols. NIH funding flows disproportionately to institutions in this corridor through NINDS and NEI research grants. Massachusetts General Hospital and Columbia University Irving Medical Center operate referral networks that capture complex cases from adjacent states.
Southeast
Florida and Georgia neurology practices affiliate with hospital systems to maintain infusion center economics under CMS reimbursement adjustments. The National Multiple Sclerosis Society accredits centers of excellence in Atlanta and Miami that encompass optic neuritis management. Duke University and Emory University anchor research collaborations with Northeast corridor institutions for biomarker validation studies.
Midwest
Chicago and Cleveland hospital systems consolidate demyelinating disease expertise through subspecialty fellowship programs at Northwestern and Case Western Reserve. The Great Lakes region exhibits lower neuro-ophthalmologist density per capita, extending patient travel times for specialized care. Cleveland Clinic operates one of the highest-volume optic neuritis referral centers outside the Northeast.
Pacific Coast
California academic medical centers at Stanford, UCSF, and UCLA compete for NIH neuro-ophthalmology training grants that shape regional specialist supply. The state's health plans increasingly require center-of-excellence designation for immunotherapy authorization. Telemedicine networks extend consultation reach into inland Mountain West states with specialist shortages.
Southwest
Texas Medical Center in Houston anchors the largest demyelinating disease patient volume in the southern United States. Baylor College of Medicine and UT Southwestern operate overlapping referral networks that capture cases from Oklahoma, Arkansas, and Louisiana. The region's independent neurology practices face accelerating affiliation pressure from hospital system expansion.
US Optic Neuritis Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with acute corticosteroid supply concentrating among established hospital system suppliers while immunotherapy development fragments across biopharma pipelines. The market exhibits tiered consolidation: acute intervention protocols favor incumbent pharmaceutical relationships, whereas disease-modifying therapy selection depends on emerging clinical evidence and prescriber education. Two strategic archetypes dominate—corticosteroid supply anchors defending hospital system contracts, and immunotherapy developers pursuing FDA breakthrough designations for recurrent phenotypes. Competitive moves center on vertical integration of infusion center networks and strategic partnerships for biomarker-guided patient identification.
Within the corticosteroid supply tier, Mallinckrodt occupies a position representing incumbent acute intervention relationships with major health systems. Among immunotherapy developers, AbbVie and Novartis exemplify contrasting pipeline strategies—AbbVie through autoimmune-targeted mechanisms and Novartis through ophthalmology franchise extensions bridging multiple sclerosis and neuro-ophthalmology care. These three companies anchor the competitive structure visible in current prescribing patterns and clinical trial activity.
| Leading Market Players |
|---|
| Mallinckrodt |
| AbbVie |
| Novartis |
| Santen Pharmaceutical |
| Sanofi |
| Pfizer |
| Teijin Pharmaceutical |
| Oculis |
| Trethera Corporation |
| Others |
Value Network & Pricing Analysis
FDA Current Good Manufacturing Practice enforcement for sterile corticosteroid production gates qualified supply access and premium-tier pricing eligibility, compressing margins for manufacturers lacking validated cold-chain infrastructure while rewarding hospital system suppliers with documented batch traceability.
Pricing Analysis
Short lead-time premiums for methylprednisolone sodium succinate concentrate among Northeast corridor academic medical centers, while spot inventory discounts emerge in private practice settings facing affiliation pressure. Contract-based long-term offtake dominates corticosteroid procurement, with price differentiation resting on FDA validation tier and volume scale through GPO aggregation. Cost compression in the standard tier intensifies because CMS facility fee differentials erode independent infusion economics. Hospital systems exhibit lowest price sensitivity due to captive patient flow, while divesting private practices in the Southeast and Midwest face acute margin pressure.
Supply Chain Analysis
Freight cost volatility for temperature-controlled methylprednisolone API shipments from Ireland and Italy amplifies landed cost uncertainty for US compounding facilities. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with gadolinium contrast agent supply anchored in Japan and Germany. Raw material dependencies span corticosteroid precursors, sterile diluents, and MRI contrast chelates. Single-source vulnerability in high-purity gadolinium manufacturing creates exposure to quality enforcement actions. Distribution runs through hospital system central pharmacies and specialty distributor networks with validated cold-chain documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over infusion center networks determines patient capture rates and immunotherapy administration economics.
For Market Incumbents: Anticipate biomarker-guided patient stratification reshaping prescriber loyalty by securing exclusive aquaporin-4 and MOG antibody testing partnerships with Northeast corridor reference laboratories. Defend corticosteroid supply contracts through backward integration into 503B compounding capabilities that shorten lead times for hospital system customers. Capacity addition in Texas Medical Center and Pacific Coast clusters captures volume migrating from fragmented private practices. For New Entrants and Emerging Players: Telemedicine platform providers represent the most penetrable channel partner type for reaching Mountain West and Great Plains markets lacking neuro-ophthalmologist density. White-space targets include FDA breakthrough therapy designation pursuit for steroid-refractory phenotypes and remote consultation models that bypass physical infrastructure requirements. The go-to-market angle centers on academic medical center affiliation programs that credential remote specialists for complex case triage. For Investors and Strategic Acquirers: FDA accelerated approval pathway activation for novel immunotherapy mechanisms is the leading indicator that disease-modifying therapy selection criteria are stabilizing sufficiently for durable revenue forecasting. Long-term viability across the analysis window favors acquisition targets with integrated biomarker diagnostic capabilities and established Northeast corridor referral relationships. The signal to monitor is CMS reimbursement rulemaking for outpatient neurology services that reshapes site-of-care economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough therapy designation accelerates recurrent phenotype immunotherapy candidates through expedited review pathways. |
| Hospital System Partnership | Vertical integration of infusion capabilities secures corticosteroid administration volume under CMS facility fee structures. |
| Biomarker Integration | Aquaporin-4 and MOG antibody testing partnerships enable precision immunotherapy selection in recurrent cases. |
| Telemedicine Platform Development | Remote consultation models penetrate Mountain West and Great Plains markets lacking specialist density. |
| Regulatory Approval Pathway | Accelerated FDA pathways compress commercialization timelines for neuro-ophthalmology disease-modifying therapies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews with hospital pharmacy directors, neuro-ophthalmology fellowship program directors, GPO contracts managers, and CMS reimbursement policy specialists. Secondary sources encompassed FDA 510(k) and NDA submissions, ClinicalTrials.gov protocol registrations, hospital procurement databases, and CMS Medicare Part B claims data. Bottom-up prescription volume modeling triangulated against top-down health system expenditure estimates.
Granularity-level modeling deployed treatment type, diagnosis method, end user, and severity level as core segmentation dimensions across the projection horizon. CAGRs derived from trend extrapolation of acute intervention protocol standardization and immunotherapy pipeline maturation. Forecast inputs incorporated FDA approval pathway velocity, neuro-ophthalmology fellowship graduation rates, and CMS outpatient neurology reimbursement adjustment trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to gadolinium contrast agent supply chains and unanticipated FDA enforcement actions against corticosteroid API manufacturers. Forecasts reflect documented assumptions that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Brazil Neurology Devices Market
Neurology
Neurocutaneous Disorders Market
Neurology
South Korea Neurology Devices Market
Neurology
Narcolepsy Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
CNS Therapeutics Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Ulnar Nerve Treatment Market
Neurology
South America Neurology Monitoring Market