
 Demyelinating Diseases Therapeutics Market | 2026-2036
Demyelinating Diseases Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Demyelinating Diseases Therapeutics Market Outlook
Modular dosing regimens combining induction and maintenance phases is recalibrating how payers evaluate total cost of ownership for chronic demyelinating therapy. Novartis AG leverages its integrated neuroscience manufacturing network to sustain supply security for high-volume monoclonal antibody production. Roche anchors European market access through established relationships with national health technology assessment bodies. Teva Pharmaceutical Industries Ltd competes on the strength of its long-acting interferon portfolio and established generic substitution capabilities.
Demyelinating diseases therapeutics comprise pharmaceutical agents designed to modulate immune-mediated destruction of myelin sheaths surrounding axons in the central and peripheral nervous systems, with formulations ranging from recombinant protein biologics requiring cold-chain distribution to small molecules stable at ambient temperatures. These therapies serve to reduce relapse frequency, delay disability progression, and manage acute inflammatory episodes in conditions such as multiple sclerosis and neuromyelitis optica. Monoclonal antibodies command the largest revenue share among product types due to superior efficacy in aggressive disease phenotypes and premium pricing supported by clinical differentiation. Small molecule drugs represent the fastest-expanding category as oral formulations displace injectable therapies in first-line settings, particularly among patients prioritizing convenience and self-administration.
The FDA's Breakthrough Therapy designation and the EMA's PRIME scheme are accelerating market entry for novel demyelinating disease therapies by enabling rolling review and enhanced regulatory dialogue. REACH compliance and the EU Green Deal pharmaceutical strategy are forcing reformulation of manufacturing processes to reduce solvent emissions and enable sustainable active pharmaceutical ingredient sourcing. Stakeholders must monitor evolving CMS coverage determination processes for infused biologics and prepare for potential indication-based pricing agreements as competitive intensity rises across the multiple sclerosis therapy landscape.
Market Dynamics
Modular dosing regimens combining induction and maintenance phases are recalibrating payer evaluation frameworks for chronic demyelinating therapy, compressing traditional annual cost models into episode-based accounting structures that favor biologics with predictable administration intervals.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated review timelines compress development-to-commercialization cycles for novel monoclonal antibodies targeting aggressive multiple sclerosis phenotypes.
- Specialty pharmacy networks:United States-based distribution infrastructure enables cold-chain biologic delivery with patient adherence monitoring embedded in reimbursement protocols.
- Oral small molecule formulations:Self-administered therapies displace injectable first-line treatments in patient populations prioritizing convenience over clinical setting dependency.
Market Restraints
- Cold-chain distribution costs:Temperature-controlled logistics for monoclonal antibodies impose infrastructure requirements that limit pharmacy participation in rural and exurban territories.
- EMA pricing negotiations:National health technology assessment bodies in Germany, France, and Italy impose reference pricing mechanisms that compress net revenue for premium therapies.
- Interferon substitution pressure:Generic long-acting formulations create downward price pressure on established injectable categories despite inferior efficacy profiles.
Strategic Opportunities
- Neuromyelitis optica spectrum disorder:Underpenetrated indication space with limited approved therapies offers first-mover advantage for complement inhibitor developers.
- EU Green Deal pharmaceutical strategy:REACH compliance mandates for sustainable active pharmaceutical ingredient sourcing favor manufacturers with retooled solvent recovery systems.
- Home infusion services:Channel innovation bypasses hospital-based neurology department capacity constraints while capturing margin from site-of-care differentials.
Industry Challenges
- Neuroimmunology specialist shortage:Fellowship-trained clinicians capable of managing progressive multifocal leukoencephalopathy risk stratification remain concentrated in academic medical centers.
- Biologic manufacturing scale-up:Single-use bioreactor capacity constraints and viral clearance validation timelines extend lead times for commercial batch release.
- Cross-border reference pricing:Parallel trade arbitrage across European single-market jurisdictions erodes country-specific net pricing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demyelinating Diseases Therapeutics Market |
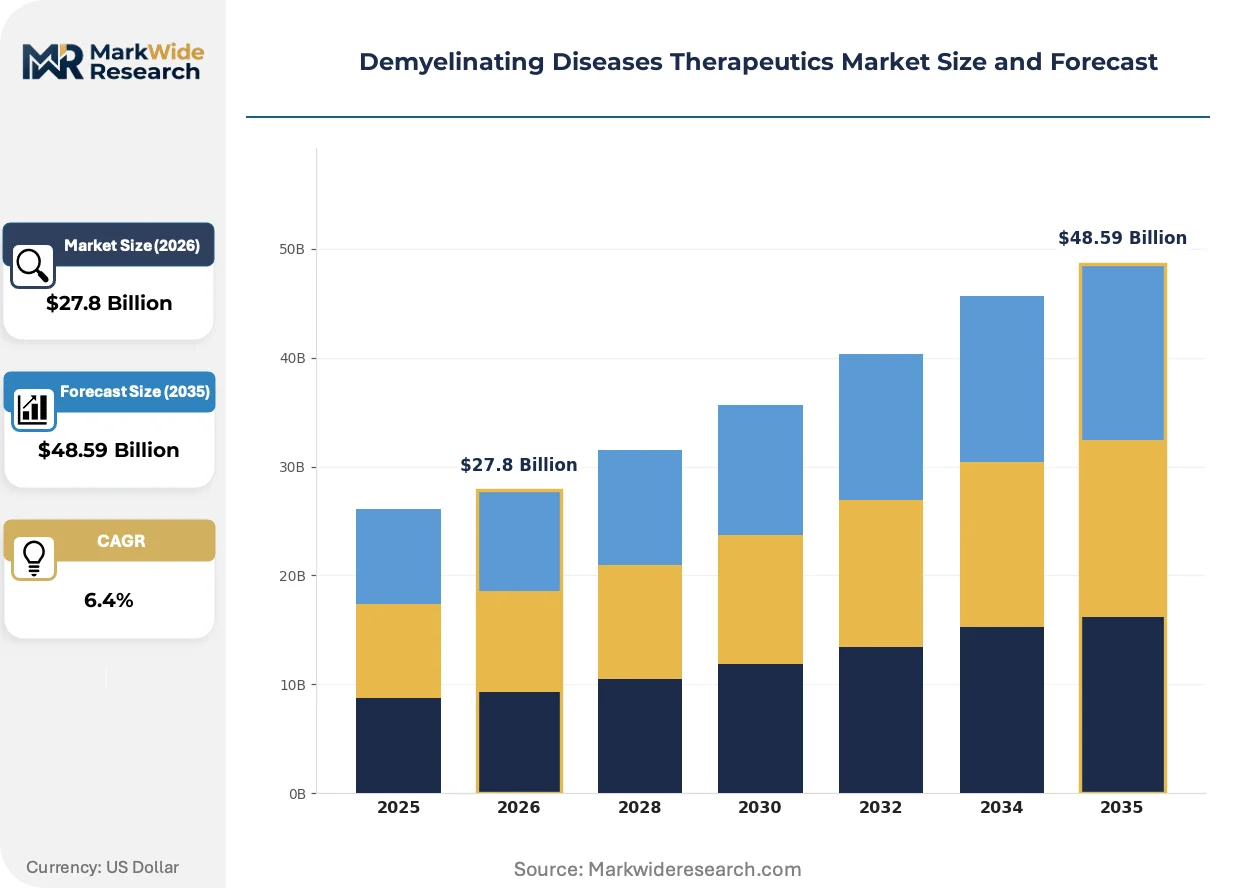
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
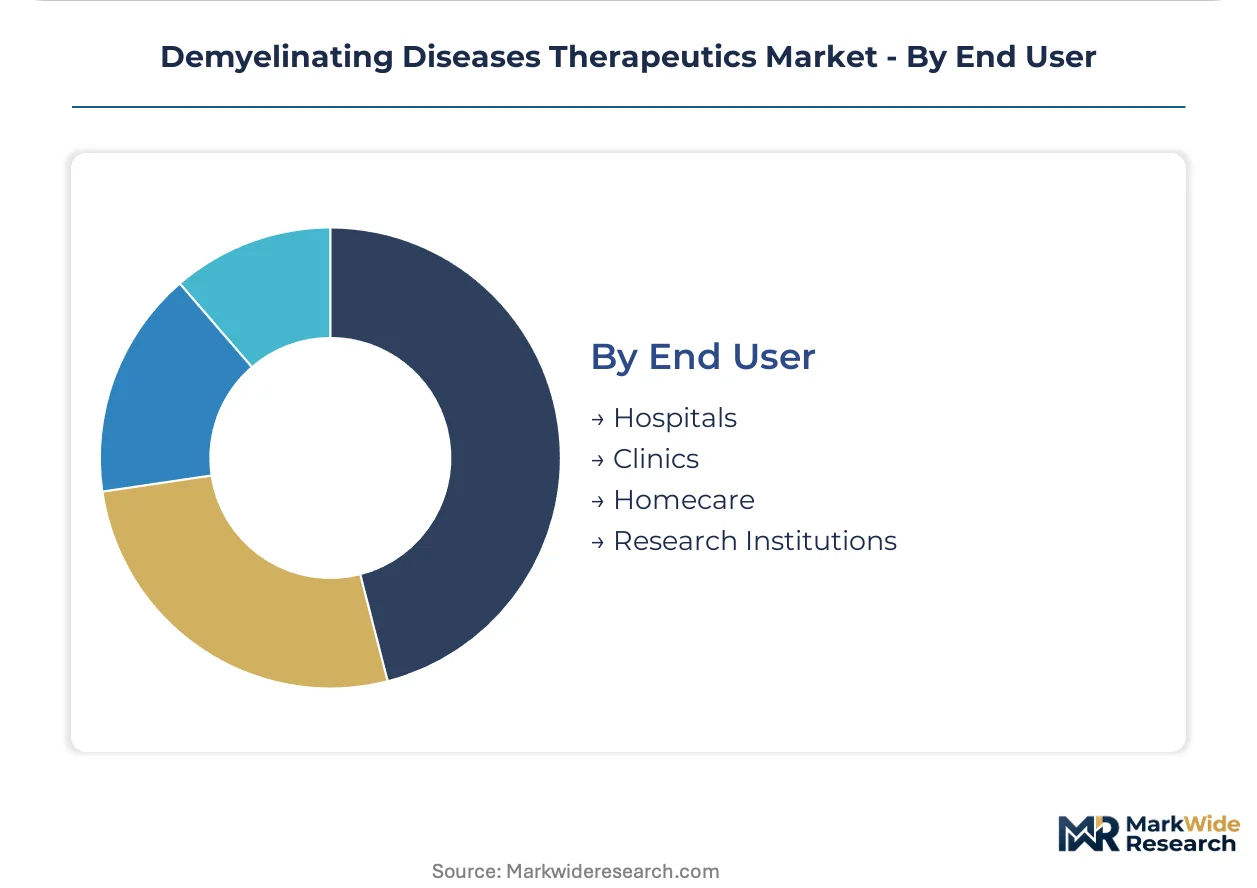
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Drugs, Interferons, Immunomodulators Therapy Area: Multiple Sclerosis, Neuromyelitis Optica, Acute Disseminated Encephalomyelitis, Chronic Inflammatory Demyelinating Polyneuropathy Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Novartis AG, Roche, Sanofi, Merck KGaA, Teva Pharmaceutical Industries Ltd, Bayer AG, AbbVie Inc, CSL Behring, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demyelinating Diseases Therapeutics Market Strategic Shifts
Adaptive trial designs and real-world evidence integration are compressing the evidentiary gap between regulatory approval and payer acceptance, forcing manufacturers to embed health economics endpoints into Phase III protocols rather than retrofitting post-hoc.
Subcutaneous autoinjector platforms for anti-CD20 monoclonal antibodies are modularizing administration protocols previously restricted to infusion centers. Neurology practices in the United States and Germany are adopting these devices for maintenance-phase therapy. This shift is compressing site-of-care costs while transferring monitoring responsibility to specialty pharmacy nursing networks.
REACH compliance and the EU Green Deal pharmaceutical strategy are forcing reformulation of manufacturing processes to reduce solvent emissions and enable sustainable active pharmaceutical ingredient sourcing. Contract manufacturing organizations serving European markets must retrofit facilities with closed-loop solvent recovery systems. Small-molecule synthetic routes requiring halogenated solvents face disproportionate compliance cost escalation.
Patient-driven therapy selection is displacing physician-directed protocol adherence as the dominant decision architecture in first-line multiple sclerosis treatment. Digital health platforms enabling side-effect reporting and efficacy self-assessment are fragmenting traditional prescriber-patient information asymmetry. This behavioral shift concentrates in United States commercial insurance populations with high-deductible health plans and pharmacy benefit manager transparency tools.
Demyelinating Diseases Therapeutics Market Segmentation
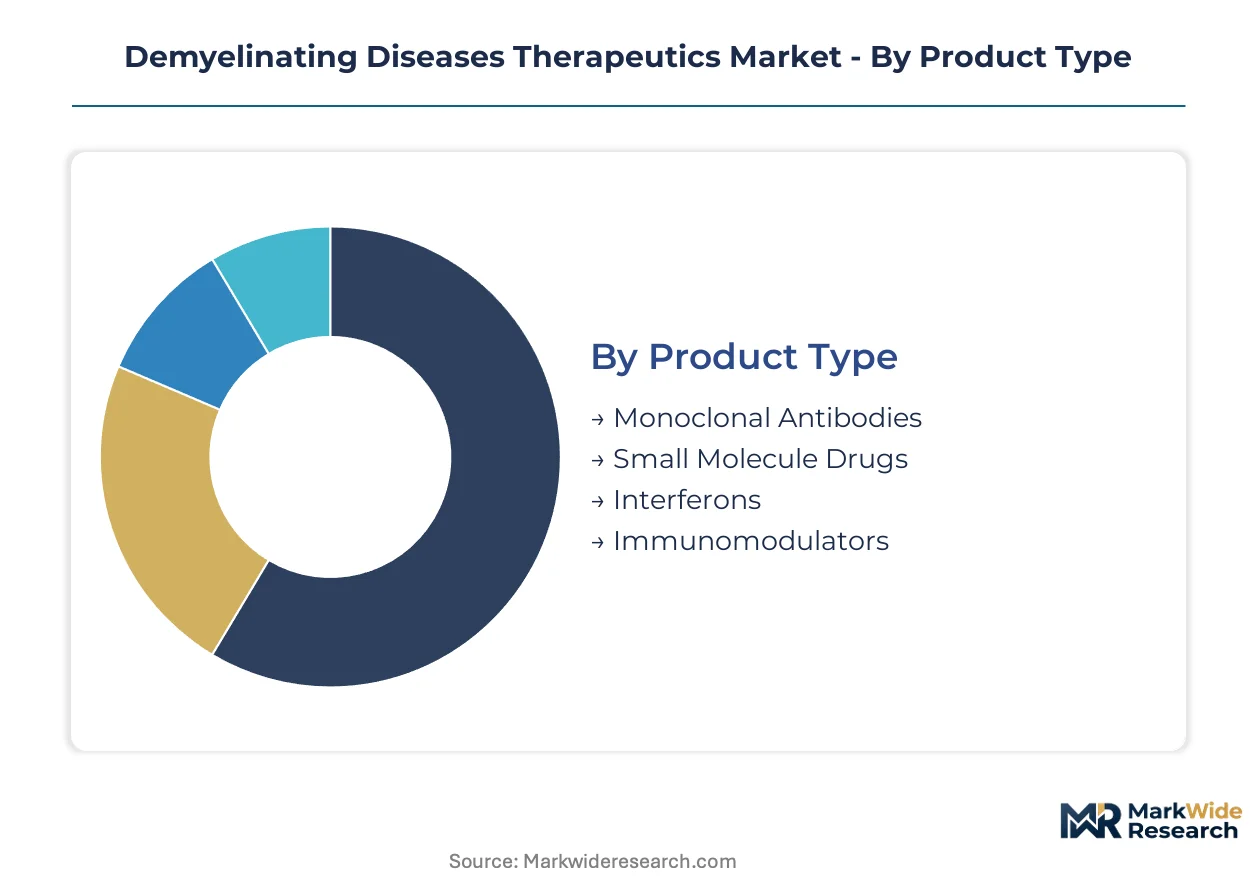
Therapeutic modality selection in demyelinating diseases hinges on disease severity, patient lifestyle preferences, and payer reimbursement frameworks. Segmentation reveals divergent growth trajectories between premium biologics and commoditized injectables, with administration convenience reshaping competitive boundaries across patient populations.
Product Type:
Volume concentration favors established injectable categories, while premium capture concentrates in biologics with superior efficacy differentiation against aggressive phenotypes.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD20, CD52, or IL-2 receptor subunits enable selective B-cell depletion or T-cell modulation with extended dosing intervals. Demand clusters in United States academic medical centers managing highly active relapsing-remitting multiple sclerosis, where breakthrough therapy designation accelerates formulary access. Payer preference for predictable administration schedules favors agents with quarterly or biannual maintenance dosing.
- Small Molecule Drugs:Oral formulations including sphingosine-1-phosphate receptor modulators and dihydroorotate dehydrogenase inhibitors penetrate first-line settings through self-administration convenience. Prescription volume concentrates among United States commercial insurance populations prioritizing therapy flexibility over clinical monitoring intensity. Convenience-driven switching from injectable platforms sustains expansion velocity in newly diagnosed cohorts.
- Interferons:Recombinant cytokine therapies with established generic substitution pathways face revenue compression despite long-acting formulation improvements.
- Immunomodulators:Polyclonal immunoglobulin and glatiramer acetate formulations serve cost-sensitive segments with moderate disease activity profiles.
Today's leader: Monoclonal Antibodies. Tomorrow's challenger: Small Molecule Drugs.
Therapy Area:
Indication breadth determines manufacturing scale economics, with narrow-label rare diseases commanding price premiums against high-volume chronic conditions.
- Multiple Sclerosis:The dominant addressable population spans relapsing-remitting, primary progressive, and secondary progressive phenotypes requiring chronic immunomodulation. Treatment penetration in Germany and France follows EMA centralized approval pathways with subsequent national pricing negotiations. Diagnostic expansion through revised McDonald criteria continues enlarging the eligible patient pool.
- Neuromyelitis Optica:Aquaporin-4 antibody-positive spectrum disorder represents an underpenetrated indication with limited approved complement inhibitors. United States orphan drug exclusivity provisions protect premium pricing for first entrants. Neurology specialist concentration in academic centers constrains prescriber base expansion.
- Acute Disseminated Encephalomyelitis:Post-infectious monophasic demyelination requires acute immunosuppression with limited chronic therapy opportunity.
- Chronic Inflammatory Demyelinating Polyneuropathy:Peripheral nervous system indication with intravenous immunoglobulin dependence and suboptimal small-molecule alternatives.
Multiple Sclerosis anchors current revenue; Neuromyelitis Optica offers the steepest expansion trajectory for novel mechanism developers.
Administration Route:
Site-of-care economics increasingly favor modalities transferring monitoring burden from hospital infusion centers to ambulatory or home settings.
- Intravenous:Hospital-based infusion of monoclonal antibodies and high-dose corticosteroids retains dominance for induction protocols and acute relapse management. United States site-of-care reimbursement differentials sustain hospital pharmacy capture despite higher per-dose costs.
- Subcutaneous:Autoinjector platforms for anti-CD20 maintenance therapy enable neurology practice-based administration in Germany and United States outpatient settings. Specialty pharmacy nursing networks assume adherence monitoring responsibilities.
- Oral:Self-administered small molecules eliminate cold-chain logistics and clinical scheduling constraints for stable patients.
- Intramuscular:Long-acting interferon formulations persist in cost-sensitive segments with established injection training infrastructure.
Intravenous maintains procedural revenue capture; Subcutaneous autoinjectors are gaining share fastest through site-of-care arbitrage.
End User:
Care setting fragmentation reflects therapy risk stratification requirements and reimbursement channel complexity across acute versus chronic management.
- Hospitals:Academic medical centers concentrate progressive multifocal leukoencephalopathy risk monitoring and aggressive phenotype induction therapy. United States 340B drug pricing program participation influences biologic procurement patterns.
- Clinics:Community neurology practices in United States metropolitan areas handle stable maintenance therapy with embedded specialty pharmacy relationships.
- Homecare:Infusion nursing services bypass hospital capacity constraints for maintenance-phase biologics with favorable safety profiles.
- Research Institutions:Phase III trial sites and compassionate use programs access pre-commercial therapies through investigator-sponsored protocols.
Hospitals retain high-complexity cases; Homecare channels are expanding most quickly through reimbursement-driven site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demyelinating diseases therapeutics industry traces its commercial scale to Swiss and German pharmaceutical corridors, where recombinant protein manufacturing and monoclonal antibody platforms were industrialized during the late twentieth century.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive adoption of infusion-based biologics for aggressive multiple sclerosis phenotypes. The FDA's Breakthrough Therapy designation compresses development timelines for novel monoclonal antibodies. Specialty pharmacy networks in metropolitan corridors enable cold-chain distribution with embedded adherence monitoring.
Germany
National health technology assessment bodies impose reference pricing that compresses net revenue for premium therapies despite high clinical efficacy. The EMA's centralized approval pathways enable rapid market access following positive CHMP opinions. Manufacturing clusters in North Rhine-Westphalia concentrate fill-finish capacity for European supply security.
Switzerland
Integrated neuroscience manufacturing networks sustain high-volume monoclonal antibody production for global export markets. Swissmedic maintains alignment with EMA regulatory standards while enabling faster national authorization timelines. Basel and Zurich anchor biologics development with established viral clearance validation expertise.
Japan
PMDA's Sakigake designation system accelerates priority review for novel demyelinating disease therapies with unmet medical need. The aging population expands the addressable patient pool for progressive multiple sclerosis management. Tokyo-Osaka pharmaceutical corridors concentrate neurology specialist training and clinical trial site infrastructure.
Demyelinating Diseases Therapeutics Market Competitive Environment
Premium-margin players sit above commodity-margin players across efficacy differentiation and administration convenience dimensions, with biologics commanding price multiples over generic interferon formulations. The vendor base organizes into three tiers: integrated multinational pharmaceutical conglomerates with neuroscience manufacturing networks, mid-cap biotechnology specialists with single-asset platforms, and generic manufacturers competing on established injectable categories. Dominant competitive moves include subcutaneous autoinjector platform development to capture site-of-care arbitrage and strategic partnerships with specialty pharmacy networks for patient adherence monitoring.
Within the integrated multinational tier, Novartis AG and Roche exemplify archetypes with established relationships to national health technology assessment bodies and cold-chain distribution infrastructure. Teva Pharmaceutical Industries Ltd occupies a position representing generic substitution capabilities and long-acting interferon portfolio breadth. These three anchors illustrate divergent strategic postures across premium biologic, mid-tier oral small molecule, and commoditized injectable market segments.
| Leading Market Players |
|---|
| Novartis AG |
| Roche |
| Sanofi |
| Merck KGaA |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| AbbVie Inc |
| CSL Behring |
| Takeda Pharmaceutical Company |
| Others |
Value Chain & Pricing Dynamics
Specialized viral clearance engineers in Basel and Boston command wage premiums that compress manufacturing margins for high-volume monoclonal antibody production, widening the spread between premium biologic pricing and commoditized interferon tiers. Labor-cost differentials across these neuroscience manufacturing clusters directly feed into three-tier pricing stratification that separates breakthrough-designated therapies from established generic alternatives.
Pricing Analysis
Episode-based accounting for induction-maintenance protocols separates premium biologics with predictable quarterly dosing from standard small-molecule oral regimens and economy-tier long-acting interferons. Price differentiation rests on FDA Breakthrough Therapy designation status and administration convenience rather than raw clinical efficacy alone. Cost compression in the interferon category is intensifying because generic substitution pathways have matured, while pricing softness in oral small molecules reflects pharmacy benefit manager formulary exclusion battles. Academic medical centers with 340B pricing participation demonstrate the lowest price sensitivity; rural community clinics dependent on Medicare Part B reimbursement exhibit the highest.
Supply Chain Analysis
EMA Good Manufacturing Practice certification and FDA current Good Manufacturing Practice compliance gate access to the United States, Germany, and Switzerland as the dominant supply nodes for finished biologic drug substance. Cold-chain distribution draws from specialized fill-finish capacity in North Rhine-Westphalia and the Swiss Basel corridor, with active pharmaceutical ingredient synthesis anchored in Ireland and Singapore. Single-source vulnerability concentrates in viral clearance validation services, where limited third-party testing capacity extends batch release timelines. Distribution runs through specialty pharmacy networks with embedded nursing adherence monitoring rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The demyelinating diseases therapeutics market functions as a stable compounder anchored by chronic disease management requirements that sustain recurring revenue across relapsing-remitting and progressive multiple sclerosis phenotypes.
For Market Incumbents: To counter biosimilar encroachment on established anti-CD20 franchises, deepen captive supply of single-use bioreactor capacity in Switzerland and Germany while securing exclusive specialty pharmacy network partnerships for patient adherence data access. FDA Breakthrough Therapy designation pursuit for next-generation complement inhibitors represents the critical R&D lever for pricing power defense.
For New Entrants and Emerging Players: Begin with neuromyelitis optica spectrum disorder as the most penetrable indication space, where limited approved therapies and orphan drug exclusivity provisions protect premium pricing for first entrants. Target United States academic medical centers with embedded home infusion nursing capabilities as the initial go-to-market channel, leveraging site-of-care arbitrage to bypass hospital pharmacy procurement gatekeepers.
For Investors and Strategic Acquirers: Integrated multinational pharmaceutical conglomerates with neuroscience manufacturing networks are the most active acquirers in this space, seeking subcutaneous autoinjector platform capabilities and established health technology assessment body relationships. Mid-cap biotechnology specialists with Phase III-ready monoclonal antibodies in multiple sclerosis represent the priority acquisition archetype. The signal to watch is EMA CHMP opinion timing for novel mechanism agents, which typically precedes United States formulary access negotiations by twelve to eighteen months.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Autoinjector Platform Development | Site-of-care migration from hospital infusion centers to specialty pharmacy networks captures reimbursement differentials. |
| FDA Breakthrough Therapy Designation Pursuit | Accelerated review timelines compress development-to-commercialization cycles for aggressive phenotype indications. |
| Specialty Pharmacy Network Partnership | Embedded nursing adherence monitoring satisfies payer requirements for outcomes-based reimbursement contracts. |
| EU REACH Compliance Retrofit | Closed-loop solvent recovery systems enable continued European market access under Green Deal pharmaceutical mandates. |
| Neuromyelitis Optica Indication Expansion | Orphan drug exclusivity provisions protect premium pricing in underpenetrated aquaporin-4 antibody-positive populations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers with secondary validation against FDA filings, EMA submission documents, ClinicalTrials.gov protocols, and formulary database snapshots. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates across the analysis window.
Comparable historical periods anchored the projection horizon, with analytical frameworks modeling treatment line, administration route, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from fitted growth curves applied to diagnosed prevalence expansion and therapy penetration rates, with inputs including McDonald criteria diagnostic revision impacts and specialty pharmacy network expansion trajectories.
Caveats apply where EMA pricing negotiation outcomes or CMS coverage determination reversals could materially shift the outlook, as forecasts reflect assumptions about payer access continuity and manufacturing scale-up execution. A model refresh is warranted upon material change in FDA breakthrough therapy designation granting patterns or European reference pricing mechanism reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Chiari Malformation Treatment Market
Neurology
Neurology Devices Market
Neurology
China Neurology Devices Market
Neurology
Optic Neuropathy Management Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Netherlands Neurology Devices Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Spasticity Treatment Market
Neurology
North America Neurology Devices Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Interventional Neurology Market
Neurology
Brain Ischemia Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Brain Tumor Diagnosis and Treatments Market