
 Argentina Neurology Devices Market | 2026-2036
Argentina Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Neurology Devices Market Outlook
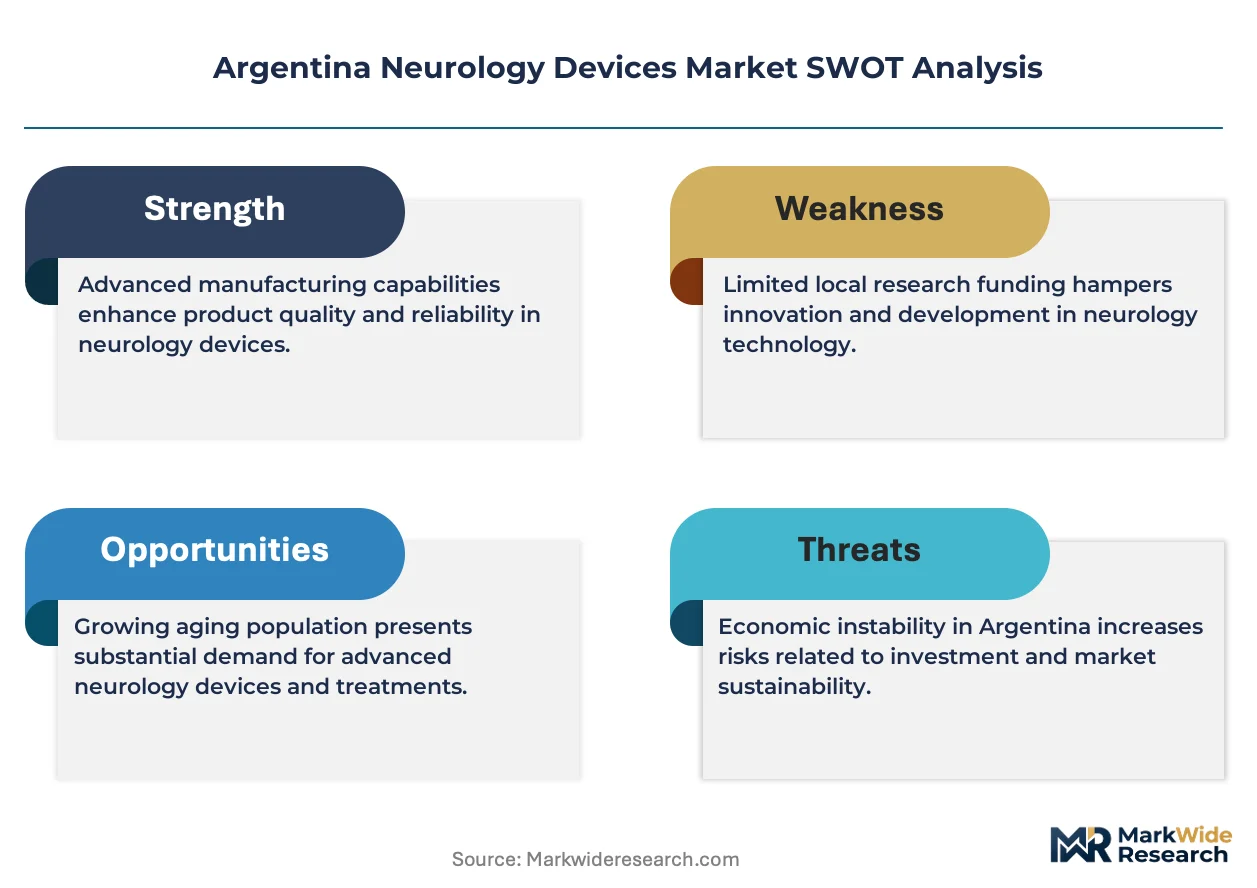
Bioresorbable polymers are restructuring implant economics across Argentina's neurology device supply chain. Medtronic PLC leverages its deep neurostimulation portfolio to dominate deep brain stimulation referrals in Cordoba and Rosario academic hospitals. Abbott Laboratories anchors its position through sustained R&D intensity in spinal cord modulation platforms tailored to Latin American patient profiles. B Braun Melsungen AG competes on manufacturing scale for neurosurgical instruments, occupying a defensible niche in public sector tenders.
Neurology devices encompass instruments, implants, and electronic systems engineered for diagnosis, surgical intervention, or therapeutic modulation of the central and peripheral nervous systems, typically incorporating biocompatible alloys, platinum-iridium electrodes, or programmable pulse generators operating at frequencies between 2-180 Hz. These systems serve to restore motor function, suppress pathological neural signaling, or enable real-time intraoperative monitoring in cranial and spinal procedures. Neurostimulation devices lead value generation due to high replacement cycles and recurring programming services, while neurosurgery instruments represent a mature margin pool where local distributors control aftermarket revenue. Imaging systems are gaining traction fastest among research institutions deploying intraoperative MRI guidance for tumor resections.
ANMAT enforces medical device registration under Resolución 5269/2017, requiring clinical evidence submissions that filter out uncertified neurostimulation imports and protect established suppliers with validated dossiers. The national Ministry of Health coordinates with provincial hospital networks to standardize procurement specifications, creating tiered access between Buenos Aires metro centers and interior provinces. Stakeholders must monitor pending reimbursement reforms for ambulatory neurology procedures and position for shifts in public-private partnership models for neurosurgery unit deployment.
Market Dynamics
ANMAT's streamlined registration pathways under Resolución 5269/2017 are compressing time-to-market for imported neurostimulation systems while provincial procurement programs in Buenos Aires Province concentrate purchasing power around validated suppliers.
Growth Catalysts
- Neurostimulation programming services:Recurring revenue from device reprogramming creates sticky supplier relationships in academic hospitals across Córdoba and Rosario.
- ANMAT registration reform:Accelerated dossier review for platinum-iridium electrode systems reduces barrier-to-entry for certified manufacturers.
- Buenos Aires Province procurement centralization:Consolidated tender processes favor suppliers with established service infrastructure.
Market Restraints
- Bioresorbable polymer supply concentration:Limited domestic production of implant-grade polymers forces dependency on imported raw materials.
- ANMAT clinical evidence requirements:Substantiation burdens for novel neurostimulation algorithms delay market entry for iterative product updates.
- Metropolitan demand concentration:Interior provinces lack specialized neurosurgery centers capable of supporting high-value device utilization.
Strategic Opportunities
- Intraoperative MRI guidance systems:Research institutions in metropolitan Buenos Aires are expanding adoption for precision tumor resections.
- Public-private neurosurgery units:Ministry of Health partnership models enable capital-light entry for device suppliers in underserved provinces.
- Ambulatory procedure reimbursement reform:Pending policy shifts would expand addressable volume for spinal cord modulation therapies.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized neurostimulation programming expertise concentrates in Buenos Aires academic centers.
- Legacy system integration friction:Public hospital infrastructure requires bridging protocols for next-generation pulse generators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Neurology Devices Market |
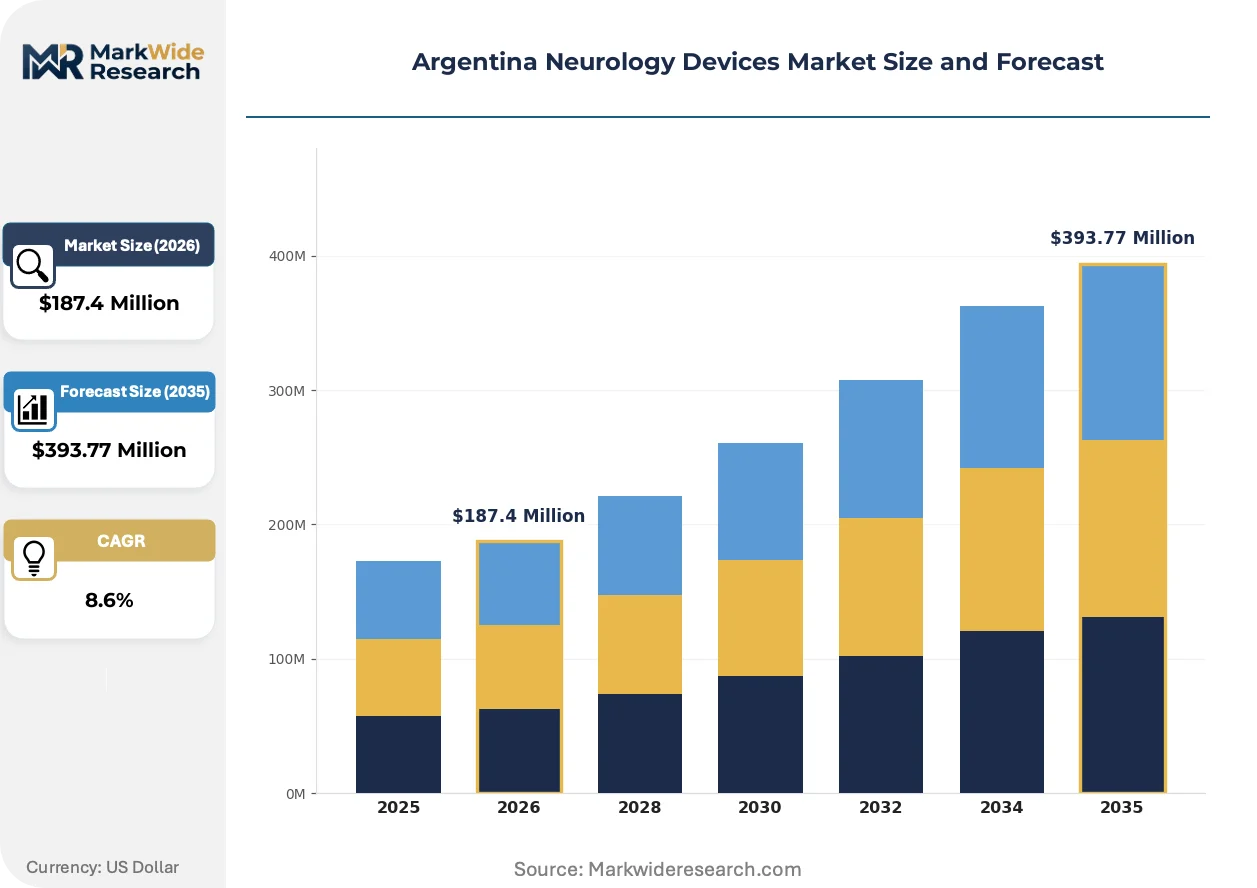
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Neurosurgery Devices, Imaging Systems, Monitoring Systems Application: Alzheimer's Treatment, Epilepsy Management, Pain Management, Stroke Rehabilitation End User: Hospitals, Clinics, Research Institutions, Home Care Settings Technology: Electronic, Software-Based, Imaging Technology, Biomechanical |
| Companies Covered | Medtronic PLC, Abbott Laboratories, Johnson and Johnson, Stryker Corporation, Integra LifeSciences Corporation, B Braun Melsungen AG, Elekta AB, Nihon Kohden Corporation, Smith & Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Neurology Devices Market Strategic Shifts
Bioresorbable materials and programmable neurostimulation architectures are restructuring device economics across Argentine neurology care, while regulatory acceleration and procurement centralization reshape competitive access.
Platinum-iridium electrode arrays with closed-loop feedback capabilities are overtaking fixed-parameter systems in deep brain stimulation applications. Academic hospitals in Rosario and Córdoba are piloting adaptive algorithms that adjust stimulation based on real-time neural biomarkers. This capability compression is collapsing the service interval from quarterly to on-demand programming, altering supplier economics.
ANMAT's implementation of risk-based classification under Resolución 5269/2017 is compressing review timelines for Class III neurostimulation devices. The industrial consequence is a filtering effect that advantages established suppliers with validated quality management systems. High-complexity implantable pulse generators face the steepest compliance gradient, with dossier preparation now requiring local clinical evidence generation.
After-sales service unbundling is fragmenting traditional distributor relationships in metropolitan Buenos Aires. Public hospital networks are separating device procurement from programming and maintenance contracts, creating direct channels between manufacturers and specialized clinical engineering units. This disintermediation is most visible in the Province's consolidated tender system, where service-level agreements now carry independent weighting in award criteria.
Argentina Neurology Devices Market Segmentation
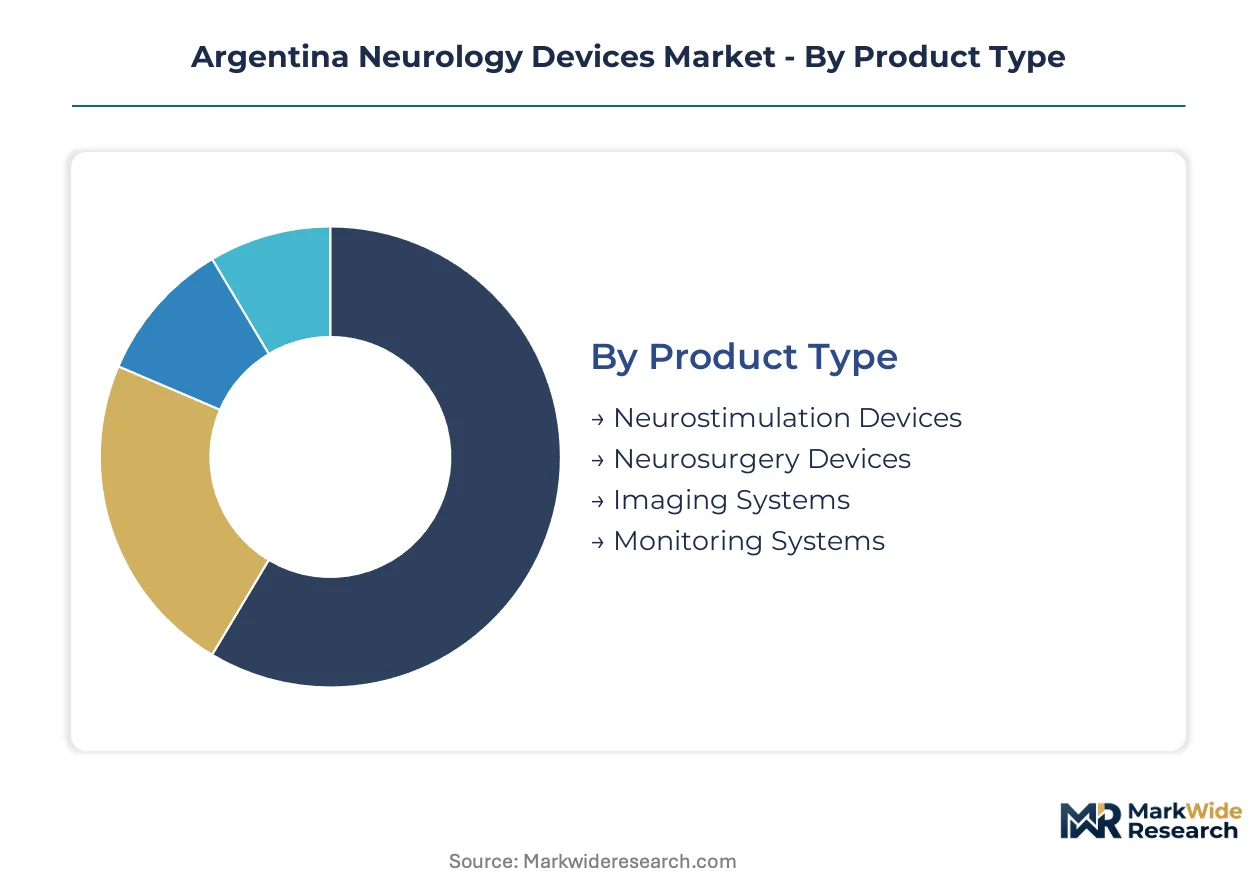
Device segmentation in Argentina's neurology market reveals how procurement centralization and reimbursement tiers concentrate purchasing power around specific product categories. Understanding these splits enables suppliers to align service infrastructure with where replacement cycles and programming demands cluster.
Product Type:
Replacement cycles vary sharply across implantable versus capital equipment categories, with programmable systems generating recurring revenue streams that reshape supplier economics.
- Neurostimulation Devices:Implantable pulse generators paired with platinum-iridium electrode arrays deliver therapeutic modulation at 2-180 Hz frequencies. Demand clusters in Buenos Aires Province academic hospitals where centralized procurement favors suppliers with embedded programming services.
- Neurosurgery Devices:Biocompatible alloy instruments and navigation platforms enable cranial and spinal interventions. Public hospital tenders in Córdoba and Rosario prioritize durability specifications and established distributor relationships for aftermarket support.
- Imaging Systems:Intraoperative MRI guidance platforms for precision tumor resections.
- Monitoring Systems:Real-time neural signal acquisition hardware for surgical and critical care settings.
Neurosurgery Devices sits at the top of the volume ranking, with Imaging Systems climbing the fastest.
Application:
Clinical indications split the addressable patient pool between chronic disease management and acute intervention pathways, each carrying distinct reimbursement and device utilization profiles.
- Pain Management:Spinal cord modulation therapies for refractory neuropathic conditions. Pending ambulatory procedure reimbursement reforms would expand addressable volume beyond metropolitan Buenos Aires into provincial hospital networks.
- Epilepsy Management:Responsive neurostimulation systems with closed-loop seizure detection. Academic centers in Rosario pilot adaptive algorithms that adjust stimulation based on real-time biomarkers, compressing service intervals.
- Alzheimer's Treatment:Experimental deep brain stimulation protocols for cognitive modulation.
- Stroke Rehabilitation:Functional electrical stimulation and motor cortex modulation for post-stroke recovery.
Pain Management commands the largest installed base, while Epilepsy Management gains share fastest on algorithmic advancement.
End User:
Facility type determines capital availability, technical staffing depth, and procurement autonomy, creating tiered access patterns across Argentina's healthcare infrastructure.
- Hospitals:Public sector networks in Buenos Aires Province leverage consolidated tender processes that separate device procurement from programming contracts. ANMAT registration requirements filter supplier pools to established manufacturers with validated quality systems.
- Research Institutions:Metropolitan Buenos Aires academic centers deploy intraoperative MRI guidance and pilot adaptive neurostimulation algorithms. These sites drive early adoption curves for next-generation device architectures.
- Clinics:Private outpatient facilities with limited neurosurgical capabilities.
- Home Care Settings:Emerging channel for portable monitoring and telemedicine-integrated devices.
Hospitals absorb the dominant share of high-value implant expenditures, with Research Institutions expanding most quickly on innovation partnerships.
Technology:
Underlying technology platforms differentiate margin structures, with software-enabled systems capturing recurring revenue versus hardware-only categories.
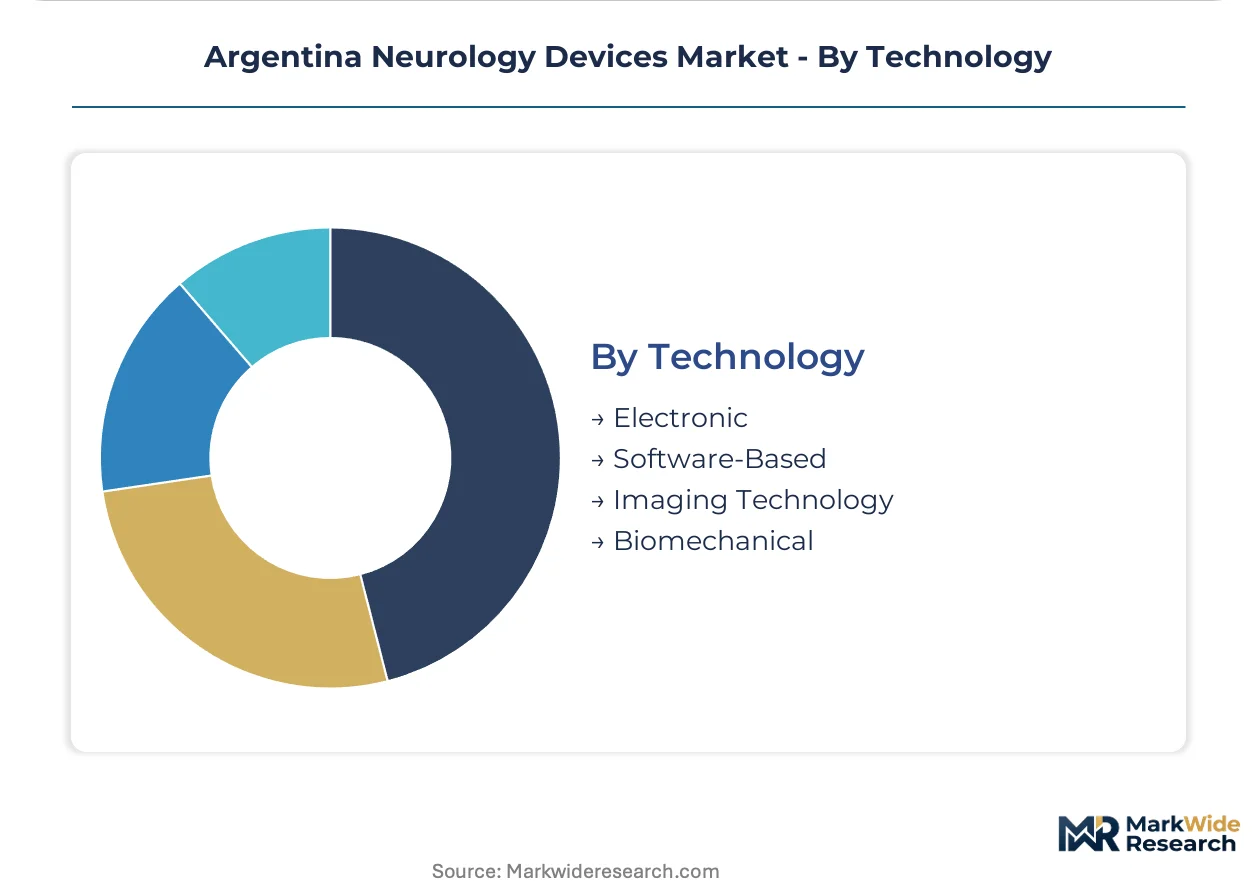
- Electronic:Programmable pulse generators and electrode systems with embedded firmware. ANMAT's risk-based classification under Resolución 5269/2017 compresses review timelines for validated Class III devices while filtering uncertified imports.
- Software-Based:Algorithmic control systems enabling closed-loop feedback and remote programming capabilities. After-sales service unbundling in Buenos Aires Province creates direct manufacturer channels separate from traditional distributor relationships.
- Imaging Technology:MRI-compatible hardware and intraoperative visualization platforms.
- Biomechanical:Structural implants and fixation systems utilizing bioresorbable polymers.
Electronic technology anchors current revenue, with Software-Based systems following the steepest expansion trajectory on service model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Buenos Aires concentrates Argentina's neurology device demand through its cluster of academic medical centers and specialized neurosurgery units. Provincial procurement centralization under Buenos Aires Province health networks redirects purchasing power toward validated suppliers with embedded service infrastructure. Interior regions lag in device utilization due to scarcity of specialized surgical capacity and programming expertise.
Buenos Aires Province
Public hospital procurement programs under the provincial Ministry of Health consolidate tender processes for neurostimulation systems and neurosurgical instruments. ANMAT registration requirements filter supplier pools to established manufacturers with validated quality management systems. The metropolitan corridor linking Buenos Aires city to La Plata anchors the country's deepest concentration of deep brain stimulation and spinal cord modulation procedures.
Córdoba
Academic hospitals in this central province pilot adaptive neurostimulation algorithms with closed-loop feedback capabilities for epilepsy management. Provincial health authorities coordinate with the national Ministry of Health to standardize device specifications across public hospital networks. The city of Córdoba hosts the interior's most advanced neurosurgery referral center, attracting patients from surrounding provinces for high-complexity implant procedures.
Rosario
Santa Fe Province's largest city sustains competitive demand for programmable pulse generators through its university hospital system and private neurosurgery centers. ANMAT's risk-based classification under Resolución 5269/2017 accelerates market access for Class III devices with local clinical evidence. The Rosario medical corridor functions as the primary device servicing hub for the Litoral region, concentrating biomedical engineering talent for neurostimulation programming.
Mendoza
This western province demonstrates emerging demand for portable neural monitoring systems amid expansion of telemedicine-integrated care models. Provincial health budgets prioritize basic neurosurgical instrumentation over high-value implantable systems due to reimbursement constraints. The Greater Mendoza metro area lacks the specialized surgical volume to support full neurostimulation service infrastructure, creating dependency on Buenos Aires-based programming networks.
Patagonian Provinces
Southern regions including Neuquén, Río Negro, and Chubut exhibit minimal device utilization outside emergency neurosurgical instrumentation for trauma cases. Geographic isolation and limited provincial health expenditure compress addressable demand to essential capital equipment categories. The city of Neuquén anchors the sparsest regional concentration of neurological care, with patients requiring advanced implants referred to Buenos Aires academic centers.
Argentina Neurology Devices Market Competitive Environment
Global majors compete with regional champions across service infrastructure and programming capabilities in Argentina's neurology device sector. The supplier base stratifies into three tiers: multinational corporations with full neurostimulation portfolios, mid-scale instrument manufacturers with public sector tender expertise, and specialized distributors controlling aftermarket service relationships. Consolidation pressures concentrate around programming service unbundling in Buenos Aires Province, where hospital networks now separate device procurement from maintenance contracts. Dominant competitive moves include direct manufacturer engagement with clinical engineering units and partnerships with academic centers for algorithm validation.
Among the multinational tier, Medtronic PLC and Abbott Laboratories exemplify contrasting strategic positions. Medtronic anchors the deep brain stimulation segment through embedded service relationships with academic hospitals in Córdoba and Rosario. Abbott occupies a parallel position in spinal cord modulation, leveraging sustained R&D positioning for Latin American patient profiles. B Braun Melsungen AG represents the manufacturing-scale archetype, competing through durability specifications and public sector tender compliance rather than programmable system architectures. These three suppliers collectively illustrate how device economics fragment across implantable electronics, surgical instruments, and service-dependent programming revenue.
| Leading Market Players |
|---|
| Medtronic PLC |
| Abbott Laboratories |
| Johnson and Johnson |
| Stryker Corporation |
| Integra LifeSciences Corporation |
| B Braun Melsungen AG |
| Elekta AB |
| Nihon Kohden Corporation |
| Smith & Nephew |
| Others |
Value Chain & Pricing Dynamics
Closed-loop neurostimulation architectures with embedded biomarker feedback are simultaneously collapsing service intervals and concentrating procurement leverage among Buenos Aires academic hospitals that command programming economies of scale. This technology compression redraws cost structures across implantable pulse generators while bioresorbable polymer sourcing constraints tether margin performance to imported raw material availability.
Pricing Analysis
Platinum-iridium electrode input costs pass through directly to implantable system pricing, with ANMAT registration tiers creating three-tier pricing structure across premium, standard, and economy levels based on clinical evidence depth. Price differentiation hinges on software-enabled closed-loop capabilities versus fixed-parameter systems, and on after-sales service bundling versus unbundled procurement. Pricing pressure stems from public hospital tender consolidation in Buenos Aires Province that forces volume discounts. Provincial hospital networks exhibit highest price sensitivity, while metropolitan academic centers prioritize algorithmic performance over unit cost.
Supply Chain Analysis
Warehouse-distribution layers for neurostimulation systems concentrate through Buenos Aires-based regional distribution centers serving Córdoba and Rosario via hub-and-spoke logistics. Manufacturing concentration rests on Germany, Ireland, and the United States for implantable pulse generators, while platinum-iridium electrodes and bioresorbable polymers draw from specialized foundries in Switzerland and Japan. Single-source vulnerability for bioresorbable polymer feedstocks creates structural risk exposure. Distribution runs through manufacturer-direct channels to hospital clinical engineering units, bypassing traditional distributor intermediation in consolidated tender markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's neurology device sector functions as a stable compounder anchored by recurring neurostimulation programming revenue that locks in supplier relationships across academic hospital networks. ANMAT regulatory acceleration and provincial procurement centralization together reinforce incumbent positioning while constraining disruptive entry pathways.
For Market Incumbents: To counter service unbundling by Buenos Aires Province hospital networks, embed proprietary algorithm development partnerships with Rosario and Córdoba academic centers. Secure backward integration into platinum-iridium electrode sourcing to buffer raw material pass-through volatility. Maintain ANMAT dossier currency through local clinical evidence generation that filters competitor re-registration attempts. For New Entrants and Emerging Players: Enter via ambulatory spinal cord modulation clinics in Mendoza and Patagonian provinces where reimbursement reform pending at the national Ministry of Health would expand addressable volume ahead of metropolitan saturation. Target portable neural monitoring systems for telemedicine-integrated deployment in underserved interior regions. Pursue public-private partnership models for neurosurgery unit capital deployment to bypass direct tender competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale neurosurgical instrument manufacturers with established public sector tender compliance and durable aftermarket revenue streams. Long-term viability over a multi-year horizon rests on software-enabled system architectures capturing recurring programming revenue rather than hardware-only margin pools. Watch ANMAT reimbursement rulings for ambulatory neurology procedures as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Pathway Acceleration | Compressed dossier review timelines under Resolución 5269/2017 advantage validated quality management systems. |
| Academic Hospital Algorithm Partnership | Closed-loop biomarker development with Rosario and Córdoba centers secures programming service lock-in. |
| Provincial Public-Private Unit Deployment | Ministry of Health partnership models enable capital-light entry in Mendoza and Patagonian provinces. |
| After-Sales Service Unbundling Response | Direct manufacturer channels to clinical engineering units counter distributor disintermediation in Buenos Aires tenders. |
| Bioresorbable Polymer Supply Security | Upstream control over implant-grade polymer sourcing mitigates single-source dependency risk from Swiss and Japanese suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neurosurgeons, biomedical engineers, hospital purchasing committee members, and ANMAT regulatory affairs specialists with secondary validation against hospital procurement databases, GPO contracts, and ANMAT registration filings. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored market size estimates.
Comparable-period anchoring linked historical neurostimulation implant volumes to provincial health budget allocations across the projection horizon. Segmentation modeling spanned product type, application indication, end-user facility tier, and technology platform complexity. CAGRs were derived from trend extrapolation of replacement cycle compression and programming service expansion, with neurostimulation algorithm advancement and reimbursement policy shifts as key forecast inputs.
Inputs from hospital procurement databases and ANMAT registration records were available through the study window; gaps in interior province device utilization data introduce uncertainty bands around Patagonian and Mendoza market estimates. Forecasts reflect documented assumptions regarding ANMAT regulatory timelines and provincial health expenditure growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurological Biomarkers Market
Neurology
US Optic Neuritis Market
Neurology
Spinal Laminoplasty Market
Neurology
Global Vertigo Treatment Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Arachnoiditis Treatment Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Acute Repetitive Seizures Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Europe Neurology Monitoring Market
Neurology
CNS Lymphoma Market
Neurology
Status Epilepticus Treatment Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Global Diabetic Neuropathy Treatment Market