
 Global Neuroblastoma Market | 2026-2036
Global Neuroblastoma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuroblastoma Market Foresight
Specialty distribution networks for pediatric oncology biologics is rewriting how therapies reach treatment centers. United Therapeutics Corporation leverages its rare disease infrastructure to sustain access in complex care settings. Pfizer Inc. competes through manufacturing scale across multiple oncology modalities. Y-mAbs Therapeutics Inc. specializes in antibody-based approaches that differentiate its portfolio from conventional chemotherapy suppliers.
Neuroblastoma is a malignant tumor arising from primitive sympathetic nervous system cells, most commonly originating in the adrenal medulla or paraspinal ganglia, with disease stratification based on MYCN amplification status and INSS staging criteria. The condition primarily demands multimodal intervention combining induction chemotherapy, surgical resection, and consolidation with autologous stem cell transplant or immunotherapy. Immunotherapy commands the highest margin pool within product type segmentation, while targeted therapy represents the fastest-expanding category driven by ALK and GD2-directed mechanisms. Pediatric hospitals anchor end-user demand through centralized high-risk case management, though specialty clinics are capturing share in maintenance-phase follow-up care.
The FDA maintains pediatric study requirements through the Pediatric Research Equity Act, while the EMA enforces pediatric investigation plans under EU Regulation 1901/2006, collectively shaping trial design and market entry sequencing. The WHO includes neuroblastoma in its Global Initiative for Childhood Cancer, establishing treatment protocol benchmarks that influence national procurement decisions. Stakeholders must monitor how GD2-targeted therapy reimbursement evolves against emerging bispecific antibody alternatives.
Market Dynamics
The FDA's pediatric priority review voucher program is compressing development timelines for high-risk neuroblastoma therapies, while GD2-directed immunotherapy reimbursement battles are forcing manufacturers to demonstrate superior progression-free survival against established benchmarks.
Growth Catalysts
- Pediatric Research Equity Act (US):Mandatory pediatric study requirements ensure trial infrastructure investment, creating a pipeline of age-appropriate formulations that expand addressable patient populations.
- Stem cell transplant centers:Expansion of accredited transplant units in pediatric hospitals enables consolidation-phase therapy delivery, anchoring multimodal treatment protocols.
- ALK inhibitor development:Targeted therapy pipelines addressing oncogenic driver mutations are opening precision medicine pathways previously unavailable in neuroblastoma care.
Market Restraints
- GD2 antibody manufacturing complexity:Mammalian cell culture requirements for chimeric and humanized antibodies constrain batch yields and create supply vulnerability.
- EU Regulation 1901/2006 pediatric investigation plans:Parallel EMA filing obligations extend regulatory timelines and duplicate clinical expenditure for developers.
- Autologous stem cell collection logistics:Harvest timing coordination with chemotherapy cycles creates capacity bottlenecks at transplant centers.
Strategic Opportunities
- Maintenance-phase specialty clinics:Post-consolidation follow-up care is migrating from hospital-based oncology units to dedicated pediatric survivorship centers.
- Bispecific antibody platforms:Dual-targeting constructs that engage T-cells without cytokine release syndrome profiles are creating differentiation space against legacy GD2 monoclonals.
- Japan's PMDA orphan drug designation:Accelerated review pathways for rare pediatric malignancies offer faster market access in a high-reimbursement jurisdiction.
Industry Challenges
- Pediatric oncology nursing specialization:Stem cell transplant and immunotherapy administration require certified competencies that face persistent training pipeline gaps.
- MYCN biomarker assay standardization:Discordant FISH and PCR protocols across reference laboratories create staging ambiguity and treatment decision delays.
- Cold-chain distribution to treatment centers:Temperature-sensitive biologics require validated logistics that strain regional pharmacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuroblastoma Market |
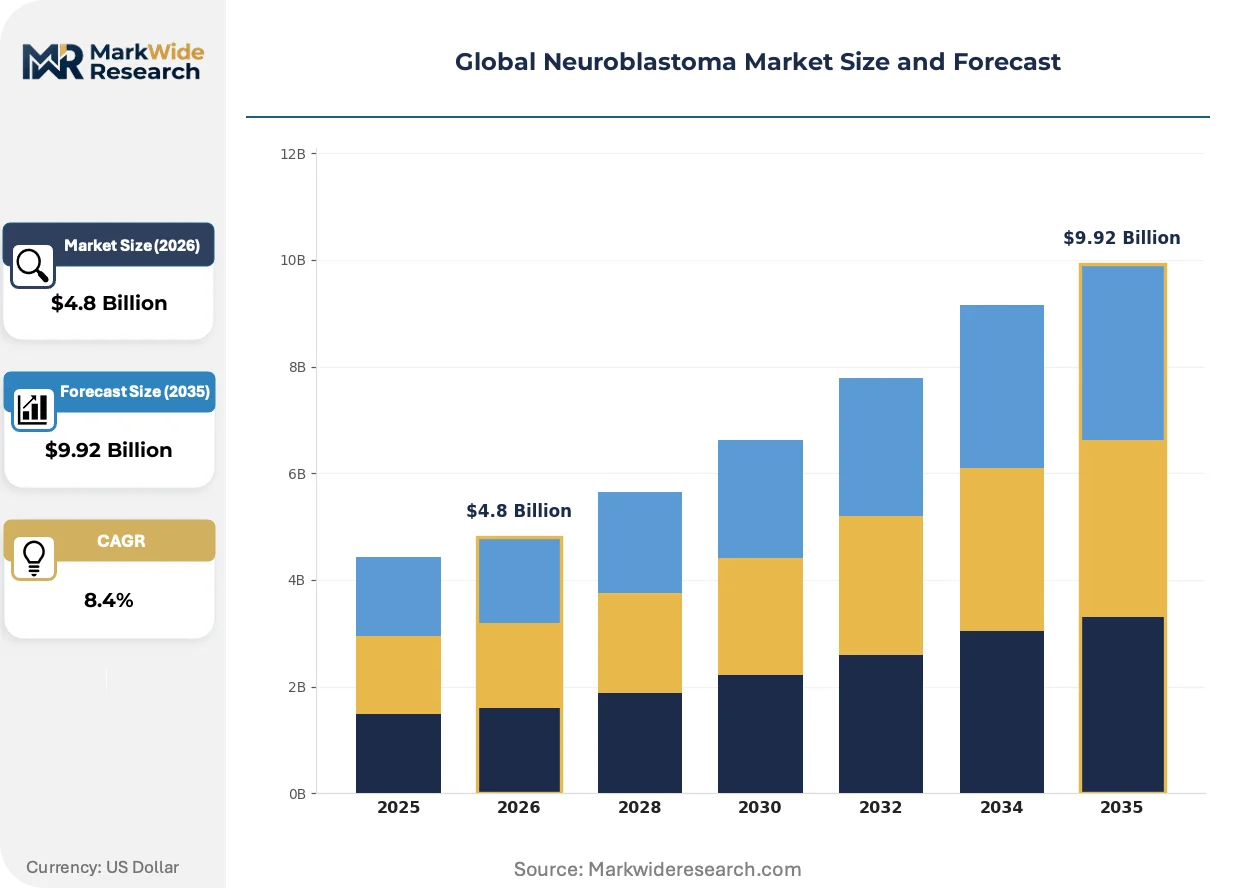
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Chemotherapy, Radiotherapy, Targeted Therapy, Stem Cell Transplant Therapy Area: Pediatric Oncology, Rare Tumor Treatment, Neuro-Oncology, Genetic Mutation Targeting, Tumor Microenvironment End User: Specialty Clinics, Pediatric Hospitals, Research Institutes, Cancer Treatment Centers, Diagnostic Laboratories Delivery Mode: Intravenous, Oral, Subcutaneous, Radiation, Intra-tumoral |
| Companies Covered | United Therapeutics Corporation, Y-mAbs Therapeutics Inc., Pfizer Inc., Cellectar Biosciences Inc., Baxter International Inc., MacroGenics Inc., Sartorius AG, EUSA Pharma, US WorldMeds LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuroblastoma Market Shifts & Advancements
Neuroblastoma therapeutics are pivoting from cytotoxic dominance toward mechanism-based interventions, with three converging developments compressing traditional treatment paradigms and redrawing competitive boundaries.
Artificial intelligence-enabled imaging analysis is virtualizing radiologic response assessment in pediatric oncology trials. Children's Oncology Group sites are deploying machine learning algorithms to standardize tumor volume measurements across multi-center studies. This virtualization is compressing inter-reader variability and accelerating endpoint determination for regulatory submissions.
REACH authorization requirements in Europe are tightening scrutiny of residual solvents in antibody manufacturing processes. EMA inspections now prioritize detection limits for process-related impurities in biologic drug substances. High-risk neuroblastoma antibody suppliers are responding by retrofitting purification trains and revalidating release specifications ahead of MDR implementation deadlines.
Consolidation therapy procurement is fragmenting as hospital pharmacy committees unbundle stem cell transplant from immunotherapy purchasing. Academic medical centers are negotiating antibody supply separately from ablative regimen components. Germany's university hospitals are most advanced in this unbundling, creating direct manufacturer relationships that bypass traditional wholesale distribution.
Global Neuroblastoma Market Segmentation
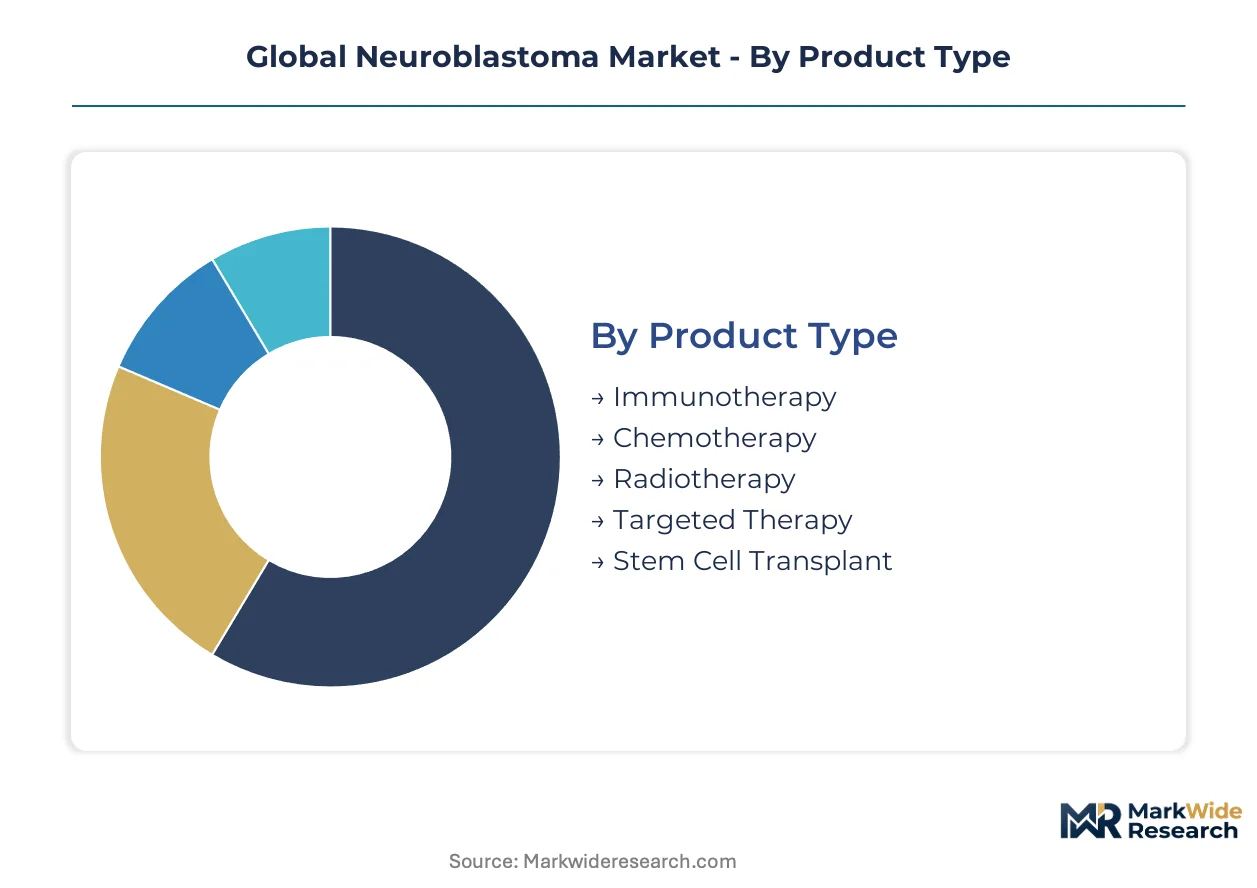
Neuroblastoma treatment protocols stratify across multiple dimensions, with modality selection driven by risk classification, patient age, and biomarker profile. Understanding how these segments intersect reveals where capital deployment and clinical development resources generate highest returns.
Product Type:
Use-case spectrum spans curative-intent multimodal regimens through palliative symptom management, with each modality occupying distinct positions in the treatment sequence.
- Immunotherapy:GD2-directed monoclonal antibodies and chimeric antigen receptor constructs engage tumor-associated antigens with engineered specificity. Pediatric hospitals in the United States and Germany concentrate demand for consolidation-phase antibody therapy, driven by reimbursement frameworks that reward progression-free survival endpoints.
- Targeted Therapy:Small-molecule inhibitors against ALK mutations and MEK pathways interrupt oncogenic signaling cascades. Research institutes in Japan and Switzerland are accelerating adoption through basket trial enrollment, constrained by biomarker assay availability at reference laboratories.
- Chemotherapy:Platinum-based induction regimens and topoisomerase inhibitors remain backbone therapy for high-risk disease stratification.
- Radiotherapy:External beam and metaiodobenzylguanidine therapy address residual disease and metastatic foci.
- Stem Cell Transplant:Autologous hematopoietic rescue follows myeloablative conditioning in consolidation protocols.
The dominant share belongs to Immunotherapy, while Targeted Therapy is closing the gap fastest.
Therapy Area:
Cost tier differentiation separates resource-intensive precision interventions from standardized protocol-based care.
- Pediatric Oncology:Age-specific dosing algorithms and organ-sparing protocols define this core treatment setting. Cancer treatment centers in the United States, Japan, and Germany anchor volume through centralized high-risk case referral networks.
- Genetic Mutation Targeting:ALK, MYCN, and RAS pathway-directed approaches stratify patients for matched therapy assignment. Specialty clinics in Switzerland and the Netherlands are expanding molecular tumor board infrastructure, limited by turnaround time for next-generation sequencing panels.
- Rare Tumor Treatment:Orphan disease designation pathways accelerate regulatory access for ultra-rare neuroblastoma subtypes.
- Neuro-Oncology:Central nervous system metastasis protocols and paraspinal ganglia primary resections occupy specialized surgical capacity.
- Tumor Microenvironment:Macrophage reprogramming and angiogenesis inhibition approaches modify immunosuppressive stromal contexts.
Pediatric Oncology commands the largest patient volume, with Genetic Mutation Targeting gaining share fastest through companion diagnostic expansion.
End User:
Customer type fragmentation reflects care migration from acute inpatient settings toward distributed survivorship infrastructure.
- Pediatric Hospitals:Comprehensive cancer centers integrate induction chemotherapy, surgery, and transplant under single institutional governance. Major facilities in Boston, Heidelberg, and Tokyo maintain accredited stem cell transplant units with dedicated pediatric oncology nursing cadres.
- Specialty Clinics:Maintenance-phase and relapse surveillance care is decentralizing to community-based pediatric hematology-oncology practices. Networks in California and Bavaria are capturing follow-up volume, constrained by credentialing requirements for late-effects monitoring.
- Cancer Treatment Centers:Adult oncology facilities with pediatric capacity handle overflow and young adult transition cases.
- Research Institutes:Phase I/II trial sites and correlative science laboratories drive pipeline access.
- Diagnostic Laboratories:Reference MYCN FISH and circulating tumor DNA testing support staging and response assessment.
Pediatric Hospitals retain the dominant position, while Specialty Clinics are expanding most quickly through survivorship care migration.
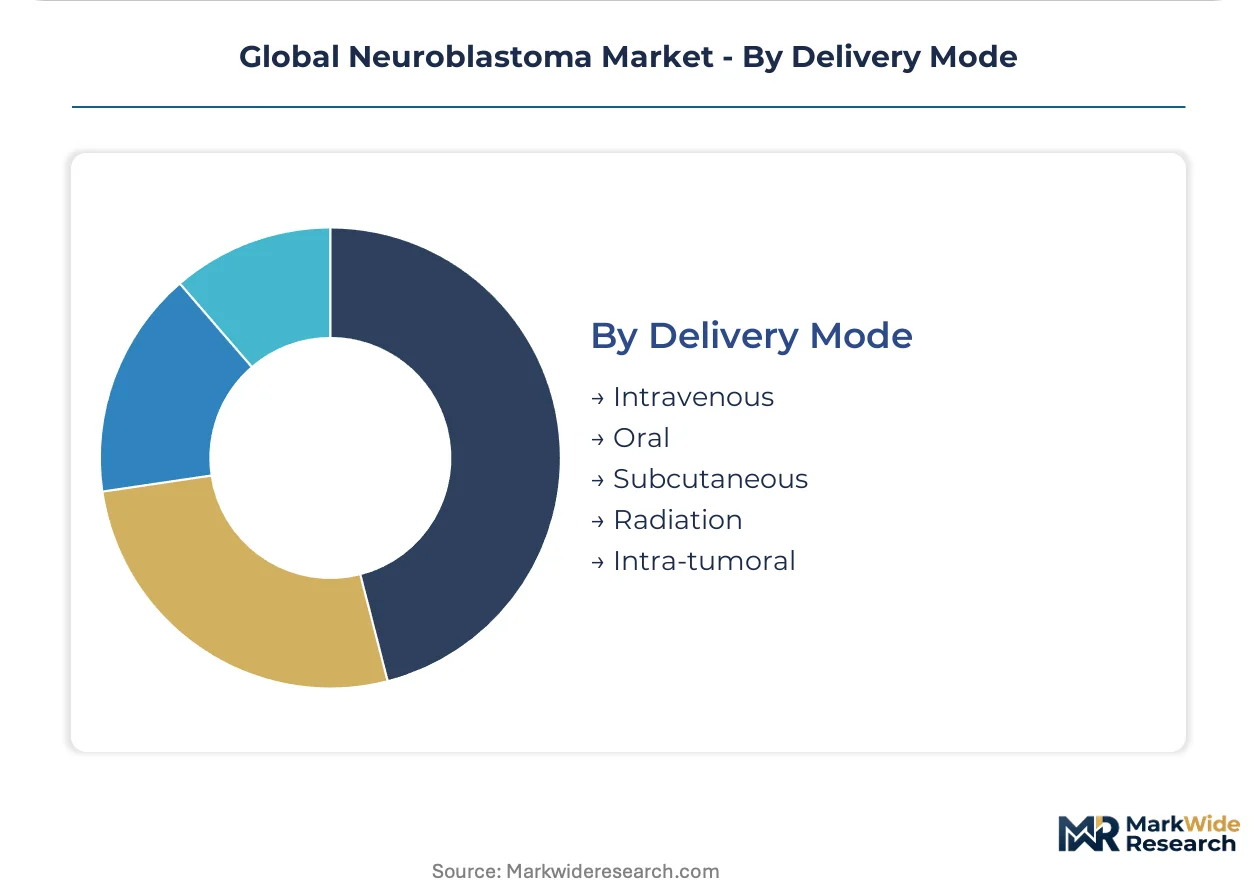
Delivery Mode:
Supply concentration in parenteral manufacturing creates bottlenecks that oral and subcutaneous alternatives are engineered to circumvent.
- Intravenous:Infusion center capacity and vascular access device management dominate high-risk neuroblastoma treatment delivery. Pediatric hospitals in the United States and Japan invest in central line infection prevention protocols to sustain treatment intensity.
- Subcutaneous:Cytokine and antibody formulations enable outpatient administration with reduced pharmacy compounding burden. Home health agencies in Germany and the Netherlands are piloting patient-administered maintenance regimens, limited by cold-chain distribution validation.
- Oral:ALK inhibitor and retinoid maintenance therapy improves patient compliance and quality-of-life metrics.
- Radiation:External beam and molecular radiotherapy require linear accelerator and nuclear medicine infrastructure.
- Intra-tumoral:Image-guided injection of oncolytic viruses and immune activators targets refractory lesions.
Intravenous administration maintains the largest share, while Subcutaneous delivery is climbing the fastest through patient convenience and cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's pediatric priority review voucher program compresses development timelines and concentrates commercial investment in jurisdictions with mature regulatory frameworks for rare pediatric malignancies.
United States
Memorial Sloan Kettering Cancer Center and Children's Hospital of Philadelphia anchor high-risk case volume through centralized referral networks. The FDA maintains pediatric study requirements through the Pediatric Research Equity Act, ensuring age-appropriate formulation pipelines. Boston's Dana-Farber Cancer Institute maintains accredited stem cell transplant units with dedicated pediatric oncology nursing cadres.
Germany
University hospitals in Heidelberg and Berlin unbundle consolidation therapy procurement, negotiating antibody supply separately from ablative regimen components. The EMA enforces pediatric investigation plans under EU Regulation 1901/2006, extending regulatory timelines for parallel filings. Bavaria's pediatric hematology-oncology networks capture maintenance-phase follow-up volume from hospital-based units.
Japan
PMDA orphan drug designation pathways accelerate market access for rare pediatric malignancies in a high-reimbursement jurisdiction. Tokyo's National Cancer Center for Children and Osaka's National Hospital Organization anchor clinical trial enrollment for ALK inhibitor development. METI funding supports domestic manufacturing capacity for temperature-sensitive biologics.
Switzerland
Specialty clinics in Zurich and Geneva expand molecular tumor board infrastructure for genetic mutation targeting, constrained by next-generation sequencing panel turnaround times. Swissmedic maintains alignment with EMA pediatric investigation requirements while offering streamlined review for ultra-rare indications. Basel's research institutes drive correlative science for biomarker assay standardization.
Global Neuroblastoma Market Competitive Landscape
On the supply side, the industry is consolidating around biologics manufacturing scale and rare disease commercial infrastructure. Large-cap pharmaceutical manufacturers compete through multi-modality oncology portfolios, while mid-cap specialists concentrate on antibody engineering and cell therapy platforms. Strategic archetypes include integrated rare disease commercializers, precision oncology biotechs, and contract manufacturing organizations. Competitive moves center on manufacturing capacity expansion for mammalian cell culture and strategic partnerships for cold-chain distribution.
Within the integrated rare disease tier, United Therapeutics Corporation leverages existing infrastructure for complex care settings, while Pfizer Inc. competes through manufacturing scale across multiple oncology modalities. Y-mAbs Therapeutics Inc. occupies a specialist position in antibody-based approaches that differentiate from conventional chemotherapy suppliers. These three represent the dominant competitive archetypes: commercial infrastructure deployers, scale-driven manufacturers, and targeted biologics developers.
| Leading Market Players |
|---|
| United Therapeutics Corporation |
| Y-mAbs Therapeutics Inc. |
| Pfizer Inc. |
| Cellectar Biosciences Inc. |
| Baxter International Inc. |
| MacroGenics Inc. |
| Sartorius AG |
| EUSA Pharma |
| US WorldMeds LLC |
| Others |
Supply & Pricing Matrix
Single-source dependency on mammalian cell culture capacity for GD2 antibody production compresses pricing spreads between originator biologics and biosimilar alternatives while forcing supply chain redundancy investments. FDA batch release requirements and EMA REACH authorization timelines for residual solvent testing amplify cost differentials across certification tiers and determine regional distribution node placement.
Pricing Analysis
Certification level (FDA-grade BLA approval versus EMA conditional authorization) creates the primary spread between premium originator antibodies and mid-tier contract manufacturing alternatives. Pricing stratifies across premium, standard, and economy tiers based on GMP compliance depth and cold-chain validation documentation. Cost compression in the standard tier is intensifying because German university hospitals unbundle consolidation therapy procurement and negotiate antibody supply separately from ablative regimen components. Pediatric hospitals in the United States exhibit lowest price sensitivity due to reimbursement frameworks rewarding progression-free survival endpoints, while specialty clinics in maintenance-phase care demonstrate highest sensitivity to per-dose economics.
Supply Chain Analysis
Export-control restrictions on dual-use bioreactor technology and mammalian cell line intellectual property limit capacity expansion in emerging manufacturing jurisdictions. Supply concentrates in the United States, Germany, and Switzerland for antibody drug substance production, drawing from Chinese-sourced media components and single-use bioreactor bags. Single-source vulnerability at the purification resin level creates chokepoints that strain batch release timelines. Distribution runs through specialty pharmaceutical wholesalers with validated cold-chain capabilities to pediatric hospital pharmacy committees and academic medical center procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuroblastoma therapeutics market presents a defensive-moat structure anchored by regulatory entrenchment. Pediatric Research Equity Act requirements and EMA pediatric investigation plans create switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Insulate manufacturing margins by securing captive mammalian cell culture capacity in Switzerland or Germany ahead of REACH authorization deadline clustering. Deepen backward integration into critical raw material suppliers for purification resins and cell culture media to offset single-source vulnerability from Chinese-sourced inputs. Channel control through direct relationships with German university hospital pharmacy committees bypasses wholesale margin erosion from unbundled procurement patterns. For New Entrants and Emerging Players: Build out bispecific antibody platforms targeting the maintenance-phase specialty clinic segment where credentialing requirements for late-effects monitoring create incumbent blind spots. Japan's PMDA orphan drug designation pathway offers the most penetrable regulatory geography for ultra-rare neuroblastoma subtypes. A go-to-market angle centered on subcutaneous delivery formats addresses home health agency pilot programs in Germany and the Netherlands that seek patient-administered alternatives. For Investors and Strategic Acquirers: The market sits at a consolidation-phase window that favors precision oncology biotechs with validated biomarker assay partnerships. Long-term viability over the next decade hinges on ALK inhibitor pipeline depth and companion diagnostic regulatory alignment. Acquisition target archetypes include mid-cap antibody engineering specialists with differentiated T-cell engaging platforms. The signal to watch is GD2-directed therapy reimbursement evolution against emerging bispecific alternatives in United States and German payer frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Children's Oncology Group site activation compresses endpoint determination timelines for regulatory submissions. |
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Basel anchors EMA-compliant antibody drug substance supply. |
| Regulatory Approval Pathway | PMDA orphan drug designation accelerates market access in Japan's high-reimbursement jurisdiction. |
| Pipeline Diversification | ALK and MEK inhibitor portfolios reduce dependency on GD2 monoclonal revenue concentration. |
| Strategic Partnership | Reference laboratory alliances for MYCN FISH standardization address staging ambiguity delays. |
Research Methodology
The analysis maps immunotherapy, targeted therapy, chemotherapy, and stem cell transplant modalities, each validated through drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchor the evidence base. Bottom-up patient population modeling and top-down revenue triangulation cross-validate segment sizing across treatment lines, administration routes, and regional regulatory clusters.
Assumptions held fixed include prevailing reimbursement frameworks for GD2-directed therapy and current pediatric hospital capacity expansion trajectories, while variables tested include bispecific antibody adoption curves and ALK inhibitor biomarker assay penetration. The analytical framework projects volume and value outputs across the projection horizon through patient-flow modeling segmented by risk classification, therapy modality, and end-user type. CAGRs derive from treatment protocol evolution assumptions and pricing trajectory sensitivity analysis, with inputs including stem cell transplant center accreditation rates and immunotherapy progression-free survival benchmark updates.
Practitioners should monitor reimbursement policy shifts for GD2-directed agents and bispecific antibody alternatives as early signals of demand migration. Forecasts reflect assumptions about regulatory timeline stability and cold-chain distribution infrastructure investment continuity. Material shifts in FDA pediatric priority review voucher program scope or EMA REACH authorization stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
United Kingdom Neurology Devices Market
Neurology
US Optic Neuritis Market
Neurology
Cervical Dystonia Treatment Market
Neurology
North America Neurology Devices Market
Neurology
Status Epilepticus Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
Nerve Repair Market
Neurology
Labyrinthitis Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
3D Neuroscience Market
Neurology
Germany Neurology Devices Market
Neurology
Spain Neurology Devices Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Interventional Neurology Market