
 Frontotemporal Disorders Treatment Market | 2026-2036
Frontotemporal Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Frontotemporal Disorders Treatment Market Intelligence
The development of disease-modifying biologics is bifurcating the therapeutic landscape from older, purely symptomatic treatments. This shift creates distinct value tiers for novel versus established therapies. Alector Inc. specializes in immuno-neurology platforms to target underlying FTD pathologies. Denali Therapeutics Inc. focuses on overcoming the blood-brain barrier, a critical challenge in drug delivery, while Biogen Inc. leverages its broad neuroscience pipeline to address multiple FTD subtypes.
Frontotemporal disorders treatment encompasses medical interventions designed to manage a spectrum of brain diseases characterized by progressive nerve cell loss in the frontal or temporal lobes. These therapies often target the pathological accumulation of proteins such as tau and TDP-43 to slow neurodegeneration. While pharmaceuticals for symptomatic relief constitute a large segment, new biologics represent the fastest-growing product type. Oral administration routes are standard for existing drugs, but injectable methods are becoming essential for delivering advanced protein-based therapeutics.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and Japan's Pharmaceuticals and Medical Devices Agency (PMDA) are critical. Their guidelines on orphan drug designations and accelerated approval pathways heavily influence development timelines and investment priorities. The validation of reliable biomarkers for patient stratification and measuring therapeutic response remains a central challenge for drug developers to resolve.
Market Dynamics
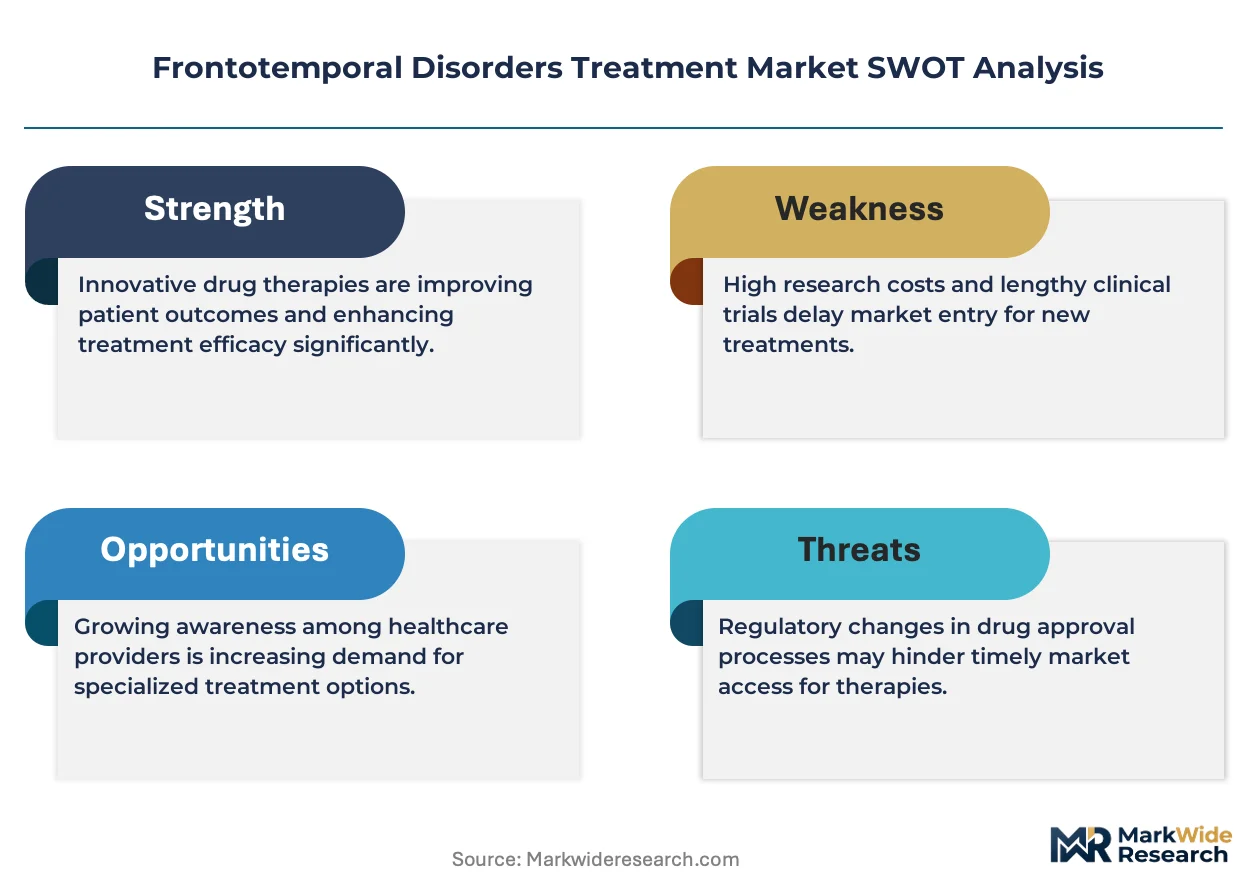
The central structural force shaping the market is the scientific pivot from broad symptomatic relief to targeted, disease-modifying biologics. This transition, enabled by advancements in genetic sequencing and supported by accelerated regulatory pathways, is creating distinct therapeutic and value tiers.
Growth Catalysts
- Advancing Regulatory Pathways:The U.S. Food and Drug Administration's accelerated approval framework for neurodegenerative diseases shortens development timelines, incentivizing investment in novel FTD therapies and enabling faster market access for breakthrough treatments.
- Biomarker Validation:Progress in identifying and validating reliable biomarkers, such as neurofilament light chain, improves patient stratification for clinical trials and provides objective measures for assessing therapeutic efficacy, reducing trial failure rates.
- Expanding Geriatric Population:A growing elderly demographic, particularly in developed nations like Japan and Germany, increases the prevalence of neurodegenerative conditions, thereby expanding the addressable patient population for FTD treatments.
Market Restraints
- Blood-Brain Barrier Permeability:The physiological challenge of delivering large-molecule biologics across the blood-brain barrier remains a significant technical restraint, limiting the efficacy of many promising protein-based and gene therapies under development.
- High R&D Attrition:The development of drugs for neurodegenerative disorders is characterized by exceptionally high clinical trial failure rates and substantial financial investment, deterring some biopharmaceutical companies from entering the FTD space.
- Diagnostic Complexity:The clinical and pathological heterogeneity of FTD subtypes complicates accurate and timely diagnosis, creating significant hurdles for patient recruitment into specific, mutation-targeted clinical trials.
Strategic Opportunities
- Precision Medicine Development:Targeting specific genetic drivers of FTD, such as progranulin (GRN) or C9orf72 mutations, presents a substantial opportunity to develop highly effective, personalized therapies for distinct patient subpopulations.
- Clinical Trial Expansion in Asia:Establishing clinical trial infrastructure in populous countries like China and India offers access to large, treatment-naive patient pools, potentially accelerating recruitment and generating diverse clinical data.
- Combination Therapy Regimens:The convergence of anti-tau antibodies with small molecule drugs targeting different pathological pathways offers a strategic opportunity to develop synergistic combination therapies that could provide enhanced clinical benefits.
Industry Challenges
- Patient Recruitment Bottlenecks:A scarcity of specialized neurology clinics and trained investigators focused on FTD creates significant operational challenges in recruiting and retaining sufficient patient numbers for pivotal clinical studies.
- Standardization of Clinical Endpoints:The lack of universally accepted clinical endpoints for FTD trials is a major challenge, complicating the comparison of results across different studies and delaying regulatory consensus.
- Payer Reimbursement Hurdles:Securing favorable reimbursement for high-cost novel biologics requires demonstrating clear long-term value and clinical benefit over existing standards of care, a significant challenge for developers to overcome.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frontotemporal Disorders Treatment Market |
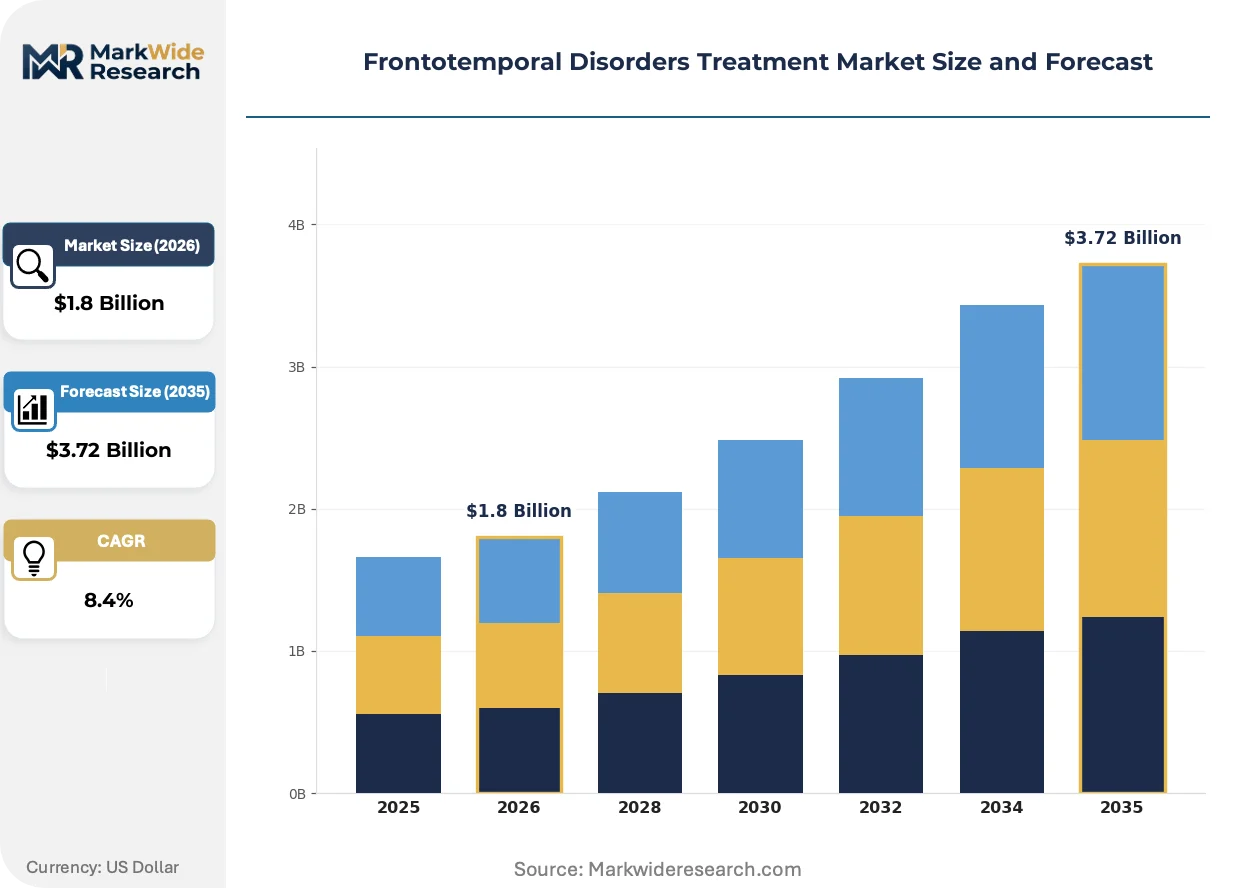
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Therapeutics, Biologics, Diagnostics Patient Age Group: Adults, Seniors, Geriatrics, Young Adults Administration Route: Oral, Injection, Transdermal, Intranasal Care Setting: Home Care, Outpatient Clinics, Hospitals, Rehabilitation Centers |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Biogen Inc., Pfizer Inc., AstraZeneca PLC, Lundbeck A/S, Alector Inc., Denali Therapeutics Inc., F. Hoffmann-La Roche Ltd., Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frontotemporal Disorders Treatment Market Strategic Shifts & Innovations
A fundamental re-evaluation of therapeutic targets defines the current market trajectory, shifting the industry's focus from generalized symptom management to the underlying genetic and protein pathologies of the disease. This evolution is driven by deeper biological understanding and new drug development platforms.
Immuno-neurology platforms are designed to modulate the immune system's response to pathological protein accumulations like tau and TDP-43. Biopharmaceutical research teams are rapidly adopting these platforms for their lead drug candidates in preclinical and early-phase trials. This targeted biological approach is decomposing the monolithic market for symptomatic treatments into highly specific, pathology-defined sub-segments requiring distinct therapeutic interventions.
Frameworks like the European Medicines Agency's PRIME scheme offer enhanced scientific and regulatory support for medicines addressing significant unmet medical needs. This program accelerates the assessment of promising therapies, such as those for rare neurodegenerative diseases, potentially shortening review times. Consequently, developers of gene therapies for FTD subtypes are aligning their clinical strategies to meet PRIME eligibility criteria for faster market authorization in Europe.
Patient advocacy groups are increasingly creating and managing registries in direct partnership with clinical research organizations. This collaborative model disrupts traditional, investigator-led recruitment by providing researchers with direct access to well-characterized, trial-ready patient cohorts. The trend is most visible in the United States and the United Kingdom, where strong patient networks for rare diseases like FTD are well-established and actively engaged in research.
Frontotemporal Disorders Treatment Market Segmentation
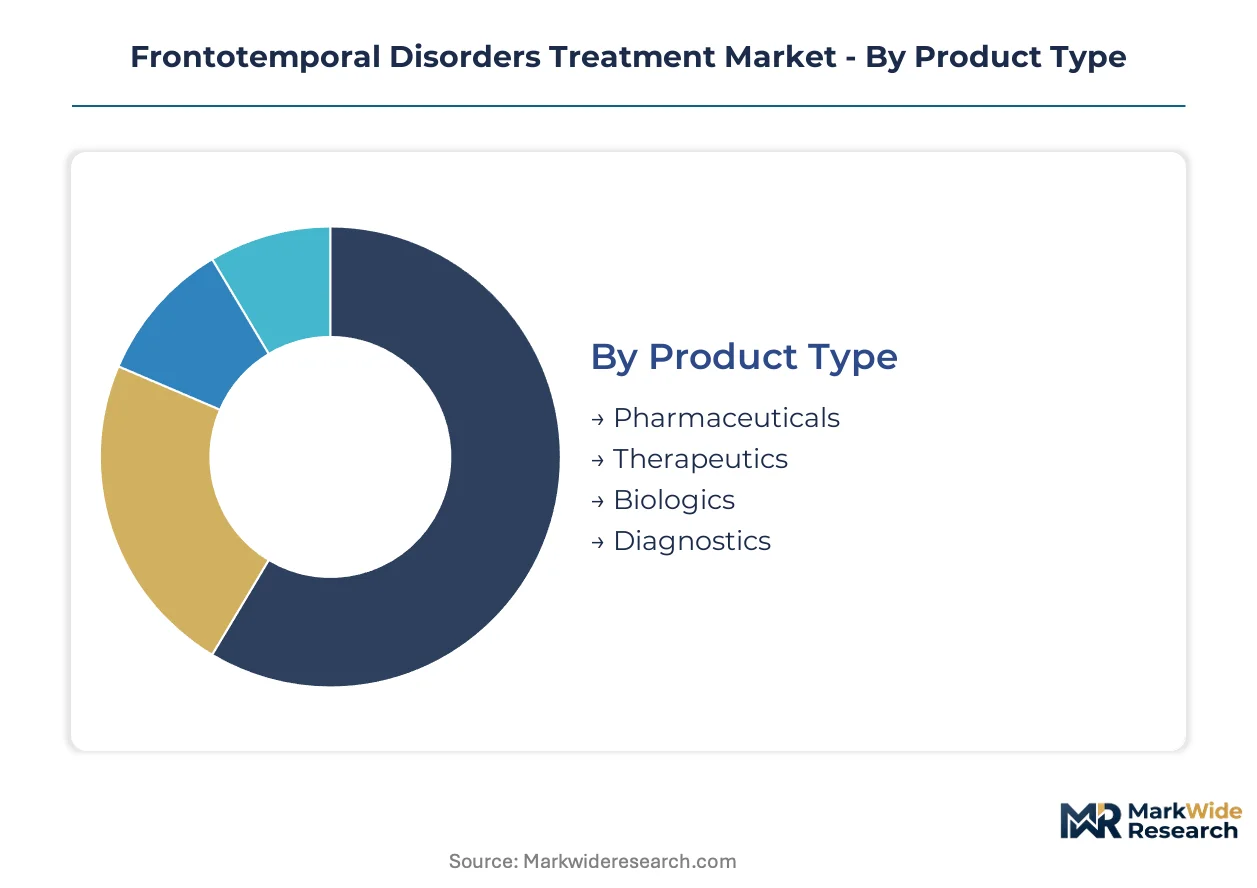
The Frontotemporal Disorders Treatment Market features distinct segmentation across product types, patient demographics, administration routes, and care settings. Understanding these categories is crucial for biopharmaceutical companies to strategically allocate research and development resources and tailor commercialization efforts for novel therapies.
Product Type:
Margin pools within the product type category are increasingly concentrating around advanced biological therapies due to their high development costs and premium pricing. These innovative treatments offer significant value propositions by targeting underlying disease pathologies.
- Biologics:These advanced therapeutic agents, often large protein-based molecules, are designed to modify disease progression by targeting specific pathological proteins like tau and TDP-43. Demand for biologics is concentrating in developed nations such as the United States and Germany, driven by significant investment in neurodegenerative disease research and specialized clinical infrastructure.
- Pharmaceuticals:This segment includes small molecule drugs primarily focused on symptomatic relief and managing behavioral disturbances associated with frontotemporal disorders. Existing demand for pharmaceuticals is widespread, particularly in primary care settings across countries like Japan and the United Kingdom, where managing patient symptoms remains a core treatment approach.
- Therapeutics:This broad category encompasses various non-pharmacological interventions, including cognitive behavioral therapy and supportive care, aimed at improving patient quality of life. Therapeutic approaches are often integrated into comprehensive care plans, particularly in rehabilitation centers.
- Diagnostics:This segment involves tools and methods for accurate FTD identification, including imaging techniques and biomarker assays. Progress in biomarker validation is enhancing the precision of diagnostic methods.
The dominant share belongs to Pharmaceuticals, while Biologics is closing the gap fastest.
Patient Age Group:
The demand for FTD treatments across patient age groups highlights the demographic shifts influencing disease prevalence and care requirements.
- Geriatrics:This segment focuses on individuals over 65 years, who represent a rapidly expanding demographic with a heightened risk of neurodegenerative conditions. Treatment demand for geriatric patients is especially pronounced in countries with aging populations, such as Japan and Italy, necessitating specialized care pathways.
- Seniors:Encompassing patients typically between 50 and 64 years of age, this group often experiences earlier onset FTD variants or progressive symptoms requiring specific medical interventions. The need for early and accurate diagnosis in this age group drives demand for targeted therapies.
- Adults:This category includes individuals aged 18 to 49 who may present with rare, early-onset forms of frontotemporal disorders. Genetic testing and counseling are often critical for this patient population.
- Young Adults:While extremely rare, FTD can manifest in individuals under 30, necessitating highly specialized diagnostic and treatment approaches. These cases often involve specific genetic mutations requiring precision medicine.
The Geriatrics segment leads in patient volume, while the Seniors segment is expanding most quickly due to increased diagnostic capabilities.
Administration Route:
The choice of administration route directly impacts drug efficacy, patient compliance, and the delivery of novel protein-based therapies.
- Injection:This route is essential for delivering large-molecule biologics that cannot effectively cross the blood-brain barrier via oral administration. Injectable methods are gaining traction for advanced protein-based therapeutics in clinical trials across the United States and Canada.
- Oral:Oral administration remains the standard for most existing symptomatic pharmaceutical drugs due to its convenience and patient acceptability. This route dominates the current market for FTD treatments, particularly in settings like outpatient clinics and home care.
- Transdermal:This route involves medication delivery through the skin, offering a sustained release profile and avoiding first-pass metabolism. Transdermal patches could enhance patient adherence for certain FTD medications.
- Intranasal:Intranasal delivery allows for direct drug access to the central nervous system, potentially bypassing the blood-brain barrier for certain small molecules. This method is under investigation for its potential in neurodegenerative drug delivery.
Oral administration maintains the largest market share, with Injection methods demonstrating the steepest expansion trajectory.
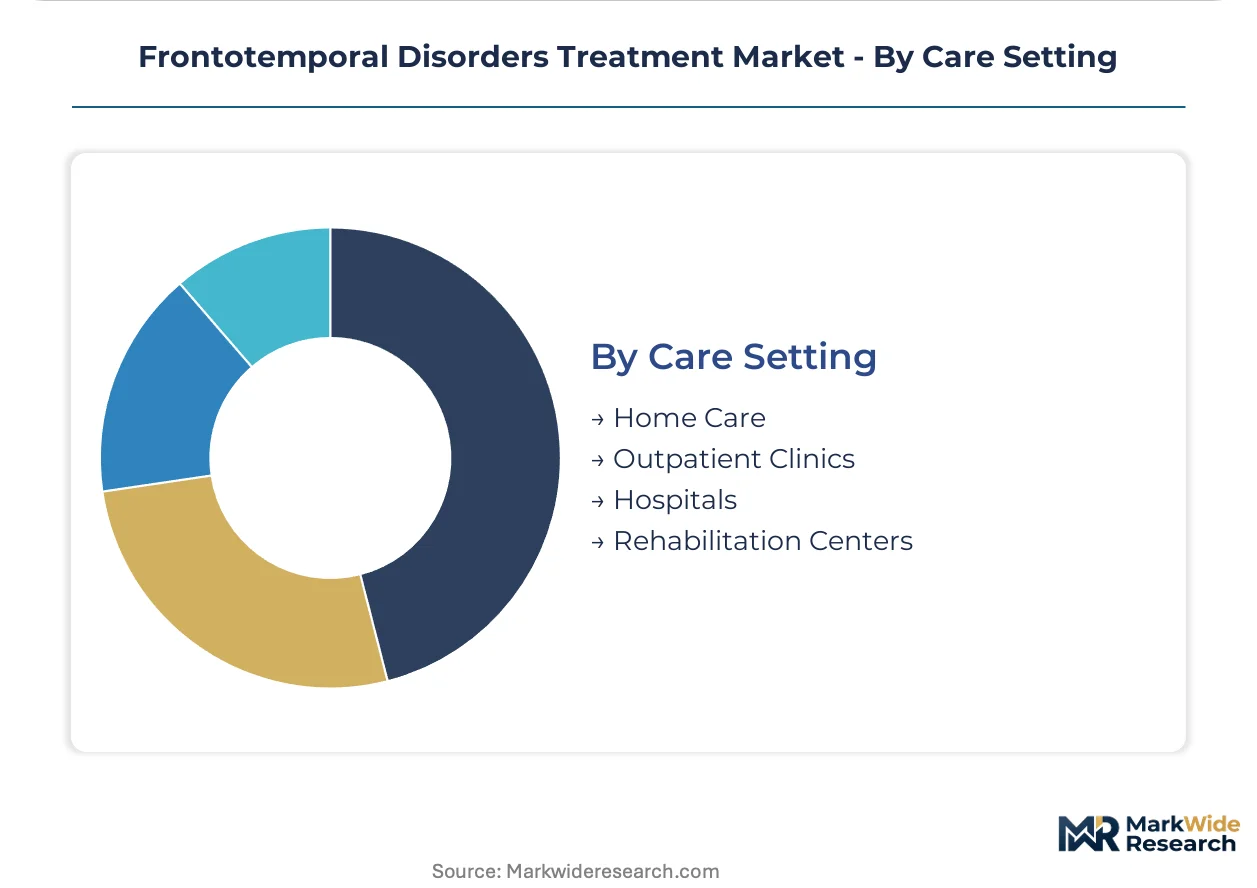
Care Setting:
The care setting for FTD treatment varies based on disease progression, patient needs, and the complexity of required medical interventions.
- Hospitals:These facilities serve as primary centers for initial diagnosis, acute symptom management, and specialized neurological consultations for FTD patients. Hospitals in major urban centers, such as London and New York, often house dedicated neurodegenerative disease units.
- Outpatient Clinics:Outpatient clinics provide ongoing management, regular check-ups, and access to specialized therapies for FTD patients who do not require hospitalization. These clinics are crucial for long-term disease monitoring and therapeutic adjustments.
- Home Care:This setting provides supportive care and assistance with daily activities for FTD patients in their own residences. Home care services are vital for maintaining patient comfort and independence, particularly in later stages of the disease.
- Rehabilitation Centers:These centers offer specialized programs, including physical, occupational, and speech therapy, to help FTD patients manage functional impairments. Rehabilitation services are increasingly integrated into comprehensive FTD care plans.
Hospitals account for the largest proportion of diagnostic and acute care, while Outpatient Clinics are gaining share rapidly for ongoing disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Innovation in Frontotemporal Disorders (FTD) treatment often originates from advanced research hubs in the United States, influencing therapeutic development and market adoption across European and Asian economies. Significant biopharmaceutical investment drives novel drug discovery, with regulatory accelerations facilitating broader access. This global dynamic shapes regional market evolution for FTD therapies.
United States
The United States exhibits strong demand for FTD treatments due to a high prevalence of diagnosed cases and substantial biopharmaceutical research funding. The U.S. Food and Drug Administration's accelerated approval pathway incentivizes rapid development of novel therapies. Boston's biotech corridor fosters extensive clinical trials and drug development for neurodegenerative diseases, attracting significant investment.
Germany
Germany demonstrates robust demand for FTD treatments, driven by its expanding geriatric population and advanced healthcare infrastructure. European Medicines Agency guidelines significantly influence market entry and product standards for new biologics. Munich's life sciences sector sees concentrated efforts in FTD biomarker research and therapeutic innovation, attracting specialized talent.
Japan
Japan's rapidly aging population creates a substantial demand for specialized FTD treatments and geriatric care pathways. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approval for orphan drugs, accelerating patient access. Tokyo's medical research institutions collaborate on FTD genetic studies and early-phase clinical development, enhancing diagnostic precision.
United Kingdom
United Kingdom demand for FTD therapies benefits from strong patient advocacy networks and increasing diagnostic capabilities. The European Medicines Agency's PRIME scheme supports accelerated assessment for promising therapies, including rare neurodegenerative diseases. Cambridge's neuroscience cluster contributes significantly to FTD research, particularly in protein pathology and drug targeting strategies.
Canada
Canada's growing elderly demographic drives demand for FTD treatments, alongside its active participation in global clinical trials. Health Canada aligns with international standards for neurodegenerative drug approvals, facilitating market access. Toronto's medical research community actively participates in FTD clinical trials, testing advanced protein-based therapeutics for various subtypes.
Frontotemporal Disorders Treatment Market Key Industry Players
Listed leaders compete with private specialists across the Frontotemporal Disorders treatment market, creating a bifurcated landscape. Established pharmaceutical companies with broad portfolios often coexist with agile biotech firms focused on innovative platforms. Strategic archetypes include immuno-neurology specialists, blood-brain barrier drug delivery innovators, and broad neuroscience pipeline developers, each pursuing distinct therapeutic avenues. Significant R&D investment and leveraging accelerated regulatory pathways define dominant competitive moves, driving the rapid evolution of this complex market.
Within the advanced biologics tier, companies like Alector Inc. represent immuno-neurology specialists, driving targeted therapies against underlying FTD pathologies. Denali Therapeutics Inc. exemplifies innovators focused on overcoming the critical blood-brain barrier challenge for drug delivery, a significant technical hurdle. Biogen Inc., a prominent biopharmaceutical company, occupies a position leveraging its broad neuroscience pipeline to address multiple FTD subtypes. These entities collectively push the boundaries of therapeutic innovation, emphasizing precision medicine and disease modification over purely symptomatic relief. Their strategic focus on complex biological mechanisms and novel delivery methods differentiates them within the competitive landscape, attracting substantial investment.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Biogen Inc. |
| Pfizer Inc. |
| AstraZeneca PLC |
| Lundbeck A/S |
| Alector Inc. |
| Denali Therapeutics Inc. |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson Services Inc. |
| Others |
Cost & Logistics Intelligence
The multi-year lead times for novel Frontotemporal Disorders treatments directly influence supply chain strategies and premium pricing structures. Specialized manufacturing capacity often dictates initial market availability, creating concentrated pricing power for innovative biologics.
Pricing Analysis
Payer organizations anchor the pricing structure for Frontotemporal Disorders treatments. Value-based pricing models are emerging for novel biologics, reflecting their high development costs and clinical impact; price differentiation also stems from demonstrated clinical efficacy and specific regulatory designations. Pricing pressure for advanced biologics is upward, driven by substantial R&D investment and the significant unmet medical need. Hospital formulary committees exhibit lower price sensitivity for breakthrough therapies offering substantial patient benefits, while primary care settings are more sensitive to the cost of symptomatic relief.
Supply Chain Analysis
The limited inventory of specialized raw materials for advanced biologics impacts the Frontotemporal Disorders treatment supply chain. Geographic supply concentrates in the United States for R&D and advanced manufacturing, alongside Germany and Switzerland for specialized biologics production. Key dependencies include specialized cell culture media and highly purified Active Pharmaceutical Ingredients, creating a structural risk from manufacturing capacity constraints. Distribution runs through a direct-to-specialty pharmacy and hospital model for novel biologics, while established pharmaceuticals utilize broader wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Frontotemporal Disorders treatment market is entering a period of cyclical recovery, driven by renewed biopharmaceutical investment in neurodegenerative disease research. This resurgence follows decades of high R&D attrition and limited therapeutic breakthroughs.
For Market Incumbents: Secure intellectual property for novel targets and invest heavily in next-generation biomarker development. This defends against emerging biotech firms specializing in immuno-neurology platforms. Leveraging existing broad neuroscience pipelines and forming strategic partnerships for advanced drug delivery technologies is crucial. Capacity expansion in specialized manufacturing facilities for biologics will also reinforce market position.
For New Entrants and Emerging Players: Differentiate on precision medicine approaches targeting specific genetic drivers of FTD, such as C9orf72 mutations. White-space opportunities exist in developing therapies for rare, early-onset FTD subtypes with high unmet need. The most penetrable segment involves highly stratified patient populations identified through advanced diagnostics. A focused go-to-market angle emphasizing clinical superiority for a niche genetic subgroup will enable market entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger pharmaceutical companies divesting non-core neurodegenerative assets or from university spin-offs with promising preclinical data. The market exhibits strong long-term viability over the next 5-10 years due to persistent unmet medical need and scientific advancements. Acquisition archetypes include biotech firms with validated early-stage assets or platform technologies for blood-brain barrier penetration. A key signal to watch is positive Phase 2 clinical trial data for disease-modifying biologics.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expedites market access for novel FTD therapies. |
| Regulatory Approval Pathway | Utilizes accelerated programs for faster drug commercialization. |
| Licensing Agreement | Expands therapeutic pipelines and leverages external innovation. |
| Manufacturing Scale-Up | Ensures sufficient supply for high-demand biologics. |
| Pipeline Diversification | Addresses multiple FTD subtypes and underlying pathologies. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, neurologists, and patient advocacy group representatives converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and secondary validation from sources like FDA filings, EMA submissions, and ClinicalTrials.gov. Bottom-up and top-down triangulation ensured data integrity across all market segments.
Product type, patient age group, administration route, care setting, and regional regulatory frameworks were the segmentation dimensions modeled. The analytical framework derived compound annual growth rates (CAGRs) over the projection horizon, integrating market drivers, restraints, and competitive dynamics. Key forecast inputs included clinical trial success rates and biomarker adoption trends, which significantly influence market trajectory.
The analysis sits within stated boundaries; outcomes outside unexpected clinical trial failures or major shifts in regulatory policy would require recalibration. Forecasts reflect assumptions documented on R&D investment and market access. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Global Neuromarketing Market
Neurology
India Neurology Devices Market
Neurology
Nerve Repair Market
Neurology
Global Sciatica Treatment Market
Neurology
Optic Neuropathy Management Market
Neurology
Europe Neurology Monitoring Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Diabetic Neuropathy Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Movement Disorder Market
Neurology
Chile Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
North America Neurology Monitoring Market