
 White Matter Injury Treatment Market | 2026-2036
White Matter Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
White Matter Injury Treatment Market Analytics
Neurocritical care units in tertiary hospitals are reorganizing procurement priorities around regenerative biologics and advanced neuroimaging-guided interventions. Biogen Inc. leverages its deep pipeline in neurodegenerative modalities to sustain R&D leadership across myelination-targeting platforms. Pfizer Inc. anchors its position through manufacturing scale in parenteral formulations for acute white matter damage protocols. Johnson & Johnson competes via integrated device-pharmaceutical bundles that span diagnostic imaging through interventional delivery systems.
White matter injury treatment encompasses pharmacological, biological, and interventional modalities designed to preserve or restore axonal integrity and oligodendrocyte function following hypoxic, traumatic, or inflammatory insult to central nervous system tracts. These interventions typically target glutamate excitotoxicity, oxidative stress cascades, and demyelination pathways, with therapeutic endpoints measured by diffusion tensor imaging biomarkers and functional neurological recovery scales. Pharmaceuticals dominates current revenue flows due to established corticosteroid and neuroprotective agent formularies, while biologics represents the fastest-expanding segment as cell-based therapies and recombinant growth factors advance through late-stage trials. Devices commands concentrated margin pools in intraoperative monitoring and image-guided delivery systems, though volume penetration remains tethered to capital expenditure cycles at hospital systems.
FDA orphan drug incentives and EMA's PRIME designation scheme for regenerative medicines jointly accelerate market access timelines for novel white matter therapeutics, compressing development-to-commercialization pathways by three to five years relative to standard review tracks. The EU Medical Device Regulation imposes heightened clinical evidence requirements on neurostimulation and drug-device combination products, elevating compliance costs for manufacturers seeking CE-marked distribution across European member states. Stakeholders must monitor evolving biomarker qualification pathways at both agencies, as surrogate endpoint acceptance will determine which biologics candidates secure accelerated approval and priority reimbursement status.
Market Dynamics
Regenerative biologics are compressing development timelines and forcing incumbent pharmaceutical portfolios toward cell-based platforms, while reimbursement frameworks struggle to price outcomes-based interventions.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates novel biologics targeting rare white matter disorders through tax credits and waived fees, incentivizing R&D investment in previously neglected indications.
- Diffusion Tensor Imaging:Advanced neuroimaging biomarkers enable earlier intervention windows and objective therapeutic monitoring, expanding addressable patient populations beyond acute care settings.
- Neurocritical Care Infrastructure:United States tertiary hospitals are building dedicated units with integrated device-pharmaceutical protocols, creating concentrated demand for bundled intervention systems.
Market Restraints
- EMA Medical Device Regulation:Heightened clinical evidence requirements for neurostimulation and drug-device combinations elevate compliance costs and delay CE-marked distribution across European member states.
- Oligodendrocyte Progenitor Cell Supply:Manufacturing scale limitations for allogeneic cell therapies concentrate production among a handful of GMP-certified facilities, creating single-source vulnerability.
- Corticosteroid Formularies:Established low-cost protocols in acute protocols create substitution pressure against premium-priced biologics, compressing price realization for novel entrants.
Strategic Opportunities
- Post-Acute Rehabilitation Centers:Service portfolio expansion into neurological recovery creates channel diversification beyond hospital-based acute care for sustained therapeutic administration.
- Biomarker-Qualified Surrogate Endpoints:FDA and EMA pathway development for imaging-based endpoints enables accelerated approval for candidates demonstrating myelination restoration.
- Japan's PMDA Regenerative Medicine Framework:Conditional approval mechanisms for cell therapies compress time-to-market for biologics candidates with early efficacy signals.
Industry Challenges
- Axonal Regeneration Biochemistry:Shortage of translational researchers bridging neurobiology and clinical trial design slows candidate progression from preclinical to Phase II.
- Multi-Site Imaging Standardization:Variability in diffusion tensor acquisition protocols across hospital networks complicates pooled efficacy analysis and regulatory submission packages.
- Device-Pharmaceutical Integration:Legacy procurement silos separate imaging capital budgets from therapeutic formularies, obstructing bundled intervention adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Matter Injury Treatment Market |
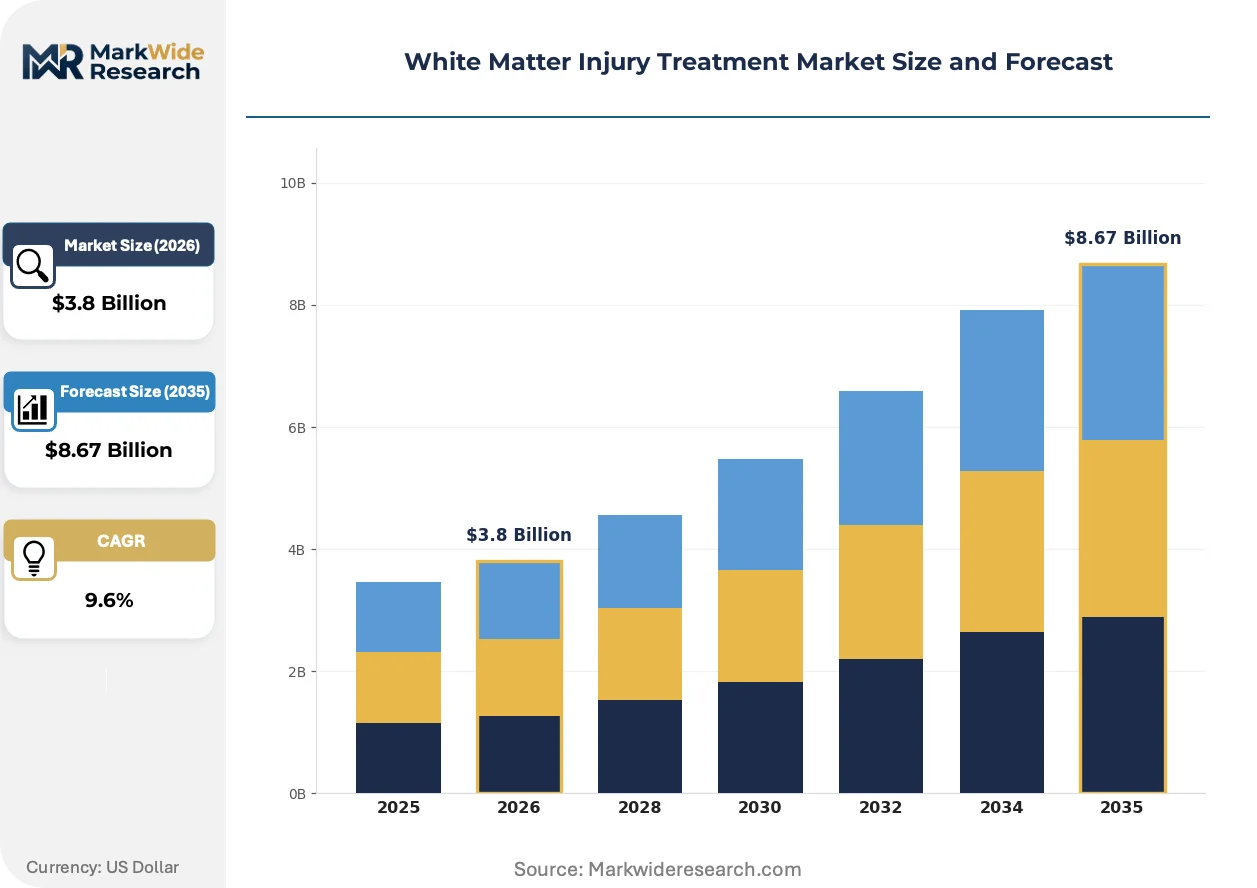
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Devices, Therapies Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Solution: Chronic Care, Acute Management, Preventive Care, Palliative Care |
| Companies Covered | Johnson & Johnson, Pfizer Inc., GE Healthcare, Novartis AG, Sanofi, Merck & Co., Inc., Biogen Inc., Kitov Pharma, United Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Matter Injury Treatment Market Evolving Landscape
Neuroimaging-guided delivery systems and regenerative platforms are converging to enable precision targeting of white matter lesions, compressing the gap between diagnostic localization and therapeutic intervention.
Intraoperative MRI-compatible infusion catheters enable real-time visualization of biologic distribution within demyelinated tracts. Neurosurgical teams at tertiary centers in Germany and the United States are adopting these systems for acute traumatic injury protocols. The technology is miniaturizing access corridors and reducing procedural morbidity, expanding candidacy for previously inoperable deep white matter lesions.
The EU Medical Device Regulation's 2021 implementation imposes clinical investigation requirements on neurostimulation systems previously cleared under the Medical Device Directive. Manufacturers must now generate prospective safety data for CE-marked distribution, elevating development costs for European market entry. Drug-device combination products targeting inflammatory demyelination face the steepest compliance burden under the new classification rules.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases for image-guided delivery platforms. United States neurocritical care units now separately negotiate technical support, software updates, and training modules, pressuring device manufacturers toward transparent service pricing. This disintermediation compresses margin pools historically captured through bundled maintenance agreements.
White Matter Injury Treatment Market Segmentation
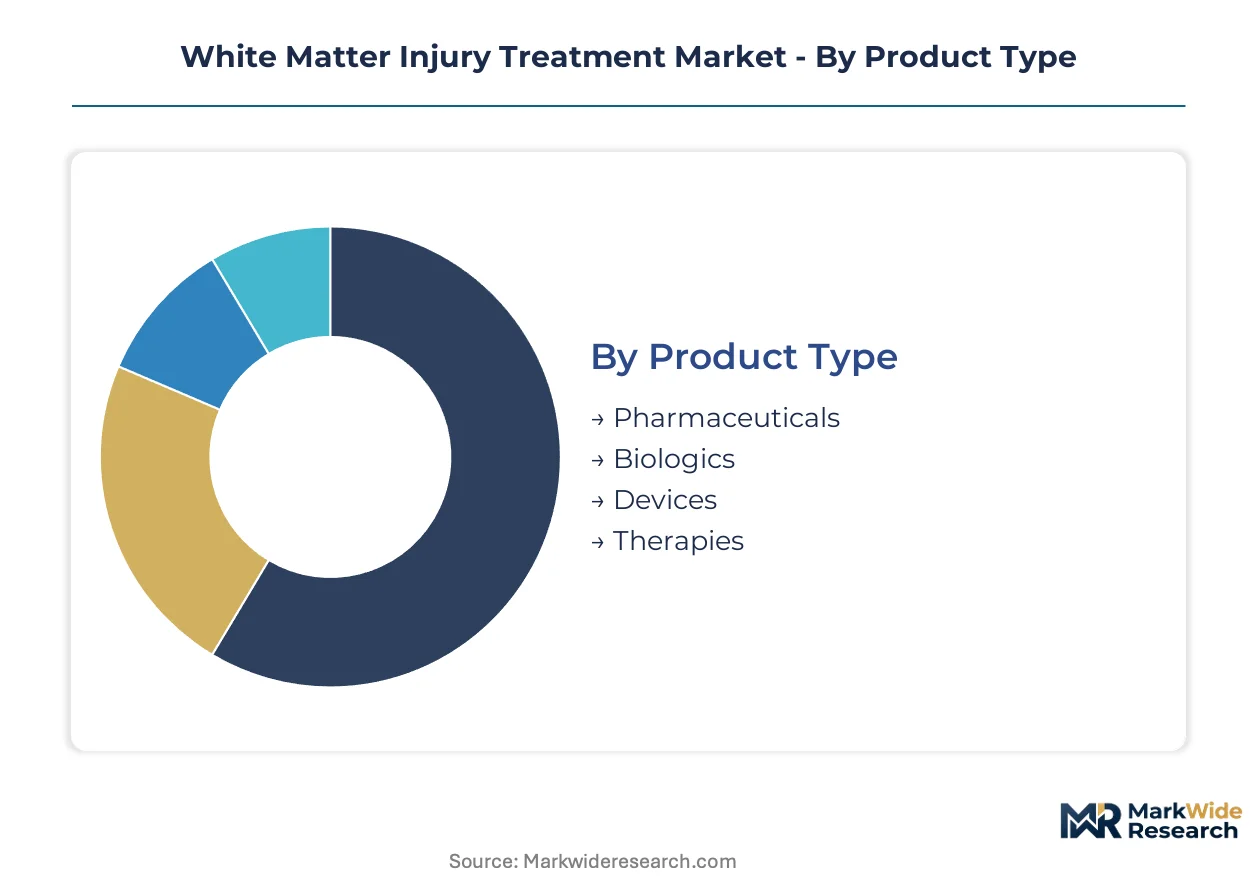
White matter injury treatment modalities traverse distinct procurement channels based on acuity level and reimbursement coding. Channel-mix dynamics determine which segments capture hospital formulary slots versus post-acute facility contracts.
Product Type:
Pharmaceuticals flow through centralized hospital procurement with established GPO contracts, while biologics and devices require specialized neurocritical care committee approval.
- Pharmaceuticals:Corticosteroids and neuroprotective agents dominate acute protocol formularies with immediate IV administration pathways. United States tertiary hospitals concentrate procurement through group purchasing organizations, though substitution pressure from low-cost generics compresses margin realization for novel chemical entities.
- Biologics:Cell-based therapies and recombinant growth factors require cold-chain logistics and specialized infusion infrastructure. Demand concentrates in academic medical centers with GMP-certified pharmacy compounding capabilities, where FDA orphan drug designation accelerates formulary access for rare white matter disorders.
- Devices:Image-guided delivery systems and intraoperative monitoring equipment capture capital expenditure cycles.
- Therapies:Physical and occupational rehabilitation protocols extend treatment duration beyond acute pharmaceutical windows.
By volume, Pharmaceuticals leads. By growth pace, Biologics is ahead.
Delivery Mode:
Route selection hinges on blood-brain barrier penetration requirements and lesion accessibility, with cost tiers separating acute parenteral from maintenance oral administration.
- Intravenous:Enables rapid CNS bioavailability for acute excitotoxicity modulation. Neurocritical care units in Germany and the United States standardize IV neuroprotective protocols, though peripheral line maintenance complicates prolonged administration.
- Oral:Supports chronic demyelination management with patient-administered maintenance dosing. Rehabilitation centers in Japan leverage oral formulations for extended post-acute protocols under PMDA conditional approval frameworks.
- Topical:Limited transdermal penetration restricts application to peripheral nerve adjuvant therapy.
- Inhalation:Investigational delivery for direct olfactory bulb access to circumvent blood-brain barrier constraints.
Intravenous commands the highest per-dose revenue. Oral formulations are expanding most quickly into outpatient channels.
End User:
Facility type determines reimbursement rate and therapeutic intensity, with margin concentration shifting from acute hospitals toward specialized neurological recovery centers.
- Hospitals:Neurocritical care units integrate device-pharmaceutical bundles for acute traumatic and hypoxic injury protocols. United States tertiary centers reorganize procurement around regenerative biologics with diffusion tensor imaging biomarker monitoring.
- Rehabilitation Centers:Post-acute neurological recovery services create sustained administration channels for cell-based therapies. Service portfolio expansion in North American and European markets diversifies revenue beyond acute-care discharge.
- Home Care:Oral maintenance protocols and remote monitoring technologies enable community-based chronic management.
- Clinics:Outpatient neurology practices concentrate diagnostic referral and treatment initiation.
Hospitals retain the largest absolute patient volume. Rehabilitation Centers are gaining share fastest as care pathways lengthen.
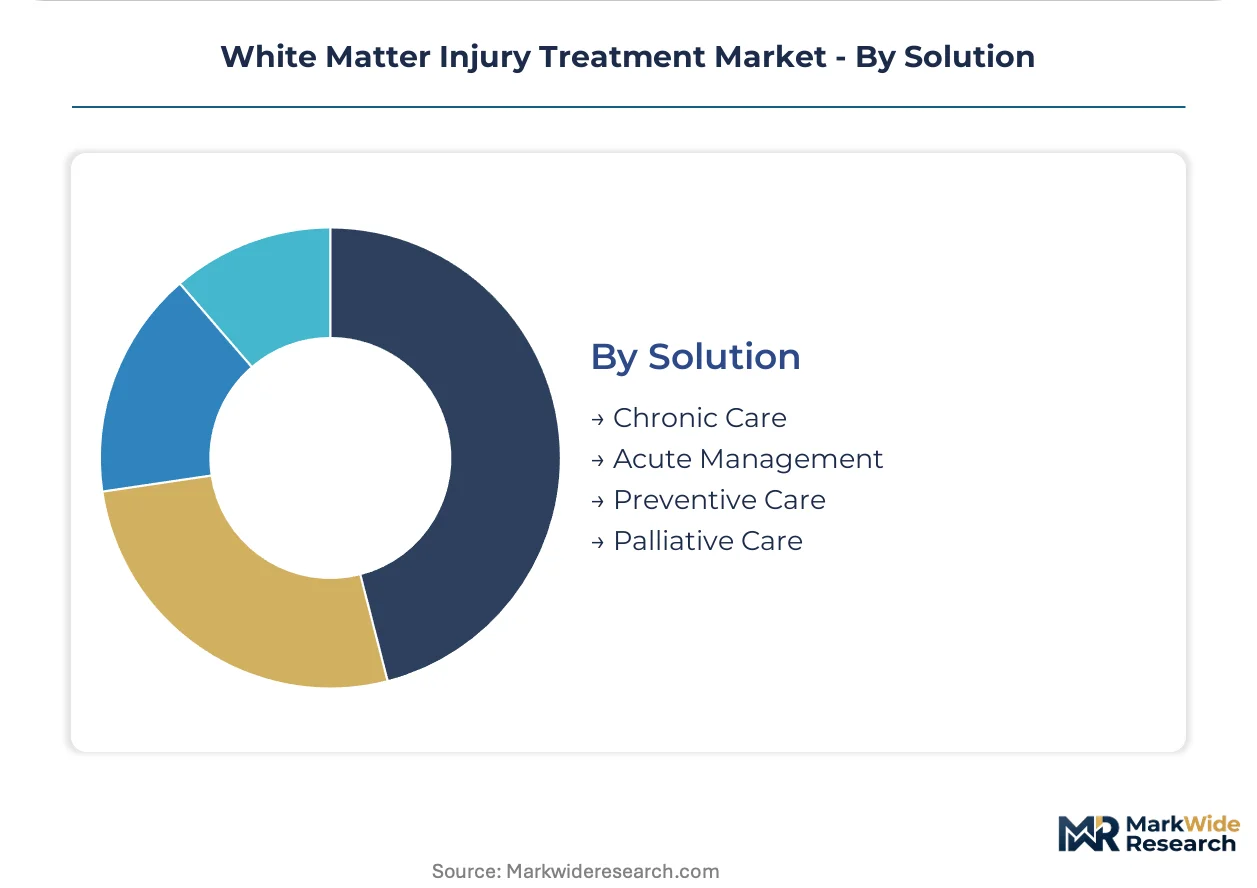
Solution:
Acuity-based segmentation aligns with reimbursement coding, where preventive and chronic categories face coverage variability across national health systems.
- Acute Management:Time-critical interventions target glutamate excitotoxicity and oxidative stress cascades within therapeutic windows. FDA accelerated approval pathways support novel biologics demonstrating functional neurological recovery endpoints.
- Chronic Care:Long-term demyelination management requires sustained oligodendrocyte progenitor cell therapy administration. European rehabilitation networks under EMA PRIME designation schemes expand access to regenerative platforms.
- Preventive Care:Risk stratification for high-risk neonatal and geriatric populations drives screening protocol adoption.
- Palliative Care:Symptom management for progressive white matter degeneration addresses quality-of-life endpoints.
Acute Management generates the highest per-episode revenue. Chronic Care shows the steepest expansion trajectory as cell therapy durability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurocritical care buyers concentrate procurement decisions in tertiary hospital systems with integrated device-pharmaceutical formularies. Reimbursement frameworks and regulatory pathways determine regional access velocity for novel biologics.
United States
FDA orphan drug designation accelerates formulary access for rare white matter disorders at academic medical centers. Medicare reimbursement codes for diffusion tensor imaging biomarker monitoring expand addressable patient populations. The Boston-Cambridge corridor anchors regenerative biologics R&D with concentrated Phase II-III trial activity.
Germany
EMA PRIME designation schemes compress market access timelines for cell-based therapies targeting demyelination. The EU Medical Device Regulation imposes heightened clinical evidence requirements on neurostimulation systems for CE-marked distribution. Heidelberg and Munich tertiary centers pioneer intraoperative MRI-compatible infusion catheter adoption for acute traumatic protocols.
Japan
PMDA conditional approval mechanisms for regenerative medicines enable earlier commercialization of oligodendrocyte progenitor cell therapies. Post-acute rehabilitation networks under national health insurance extend administration channels beyond hospital discharge. Tokyo and Osaka metropolitan areas concentrate GMP-certified pharmacy compounding capabilities for cold-chain biologics.
Switzerland
Swissmedic accelerated pathways for breakthrough therapies attract myelination-targeting platform development from multinational sponsors. Reimbursement autonomy at cantonal level creates variability in biologics access across the confederation. Basel and Zurich hospital networks integrate device-pharmaceutical bundles for neurocritical care procurement.
United Kingdom
NICE technology appraisals determine NHS England coverage for novel white matter therapeutics with functional recovery endpoints. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for regenerative medicines. London and Oxford academic medical centers coordinate multi-site imaging standardization for pooled efficacy analysis.
White Matter Injury Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with neurodegenerative portfolios and specialized biologics developers with regenerative platforms. Market structure concentrates around three tiers: integrated device-pharmaceutical bundlers, cell therapy specialists with GMP manufacturing assets, and neuroimaging-guided delivery system manufacturers. Dominant competitive moves include strategic partnerships between biologics developers and diagnostic imaging firms, plus backward integration into GMP-certified cell production facilities.
Within the integrated pharmaceutical tier, Johnson & Johnson and Pfizer Inc. exemplify device-pharmaceutical bundling strategies that span diagnostic imaging through interventional delivery. Biogen Inc. occupies a distinct position among neurodegenerative-focused developers with deep pipeline exposure to myelination-targeting platforms. These three entities represent contrasting archetypes: diversified healthcare conglomerates leveraging manufacturing scale, and specialized neurology players anchoring regenerative biologics innovation.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| GE Healthcare |
| Novartis AG |
| Sanofi |
| Merck & Co., Inc. |
| Biogen Inc. |
| Kitov Pharma |
| United Therapeutics |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with GMP-certified cell production facilities lock in oligodendrocyte progenitor cell supply and stabilize biologics pricing visibility for academic medical centers in the United States and Germany. These arrangements insulate buyers from spot-market volatility in allogeneic cell therapy inputs while committing manufacturers to capacity utilization guarantees.
Pricing Analysis
Cost-plus contracts indexed to cold-chain logistics and GMP facility operating costs govern biologics procurement between cell therapy developers and tertiary hospital systems. Three-tier pricing structure across premium regenerative platforms, standard neuroprotective agents, and economy corticosteroid formularies separates academic medical centers from community hospitals from rehabilitation centers. Price compression in the standard tier intensifies as low-cost generics displace novel chemical entities in acute protocols. Rehabilitation centers exhibit highest price sensitivity due to fixed reimbursement caps, while neurocritical care units at academic centers demonstrate lowest sensitivity where outcomes-based contracts apply.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical distribution, while biologics developers maintain strategic stockpiles of cryopreserved cell lines at dual GMP facilities. Supply concentrates in the United States, Germany, and Japan for GMP-certified production of oligodendrocyte progenitor cells and recombinant growth factors. Raw material dependencies include fetal bovine serum, synthetic scaffold matrices, and recombinant cytokine media. Single-source vulnerability in allogeneic cell line master banks creates concentration risk. Distribution runs through specialized cold-chain logistics providers with validated temperature monitoring for biologics, bypassing standard pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation and EMA PRIME acceleration for regenerative biologics create a regulatory inflection that compresses development-to-commercialization timelines and rewards first-mover manufacturing scale.
For Market Incumbents: Compound defensive positioning through backward integration into GMP-certified cell production facilities and exclusive diffusion tensor imaging platform partnerships. Corticosteroid generic substitution threatens premium neuroprotective revenue. Capacity addition in Japan under PMDA conditional approval frameworks secures early-mover access to post-acute rehabilitation networks. For New Entrants and Emerging Players: Anchor in post-acute rehabilitation center channels where bundled device-therapeutic protocols remain underpenetrated and procurement committees lack established vendor relationships. Oral maintenance formulations for chronic demyelination management represent the most penetrable segment. Pursue white-label manufacturing partnerships with GMP-certified compounding pharmacies to bypass capital-intensive facility buildout. For Investors and Strategic Acquirers: Capital is best deployed toward cell therapy specialists with captive GMP manufacturing assets and qualified imaging biomarker endpoints. Long-term viability hinges on durability of myelination restoration demonstrated across multi-site trials. Watch FDA biomarker qualification pathway decisions as the signal indicating which candidates secure accelerated approval and priority reimbursement status.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Captive cell production capacity insulates against single-source supply vulnerability for oligodendrocyte therapies. |
| Imaging Biomarker Qualification | FDA acceptance of diffusion tensor surrogate endpoints accelerates approval timelines for myelination-restoration candidates. |
| Rehabilitation Center Partnership | Post-acute channel contracts diversify revenue beyond hospital discharge and extend therapeutic administration windows. |
| Orphan Drug Designation Pursuit | Tax credits and waived fees improve unit economics for rare white matter disorder indications with limited addressable populations. |
| Device-Pharmaceutical Bundling | Integrated procurement contracts capture imaging capital budgets alongside therapeutic formularies in neurocritical care units. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neurocritical care physicians, hospital formulary directors, GMP facility operations managers, and biologics regulatory affairs specialists. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME designation records, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down revenue triangulation across product type, delivery mode, and end-user segments were reconciled to produce volume and value estimates.
Across the analysis window, the forecasting framework modeled treatment modality segmentation by acuity level, reimbursement coding cluster, and regional regulatory pathway. CAGRs were derived from elasticity-adjusted adoption curves for regenerative biologics versus established pharmaceutical protocols. Key inputs included diffusion tensor imaging penetration rates, GMP facility capacity expansion announcements, and conditional approval mechanism utilization under PMDA and Swissmedic frameworks.
Decision-makers should treat outputs as directional under assumptions of stable orphan drug incentive continuity and biomarker qualification pathway progression; material deviation would warrant model refresh. Revision becomes warranted when FDA surrogate endpoint acceptance thresholds or EMA MDR enforcement intensity crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Neuroblastoma Market
Neurology
Moyamoya Disease Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Neuro Critical Care Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Australia Neurology Devices Market
Neurology
CNS Therapeutics Market
Neurology
Brain Ischemia Market
Neurology
Transcranial Doppler Market
Neurology
Neuroprotection Market
Neurology
Optic Neuropathy Management Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Europe Neurology Monitoring Market