
 Benign Positional Vertigo Treatment Market | 2026-2036
Benign Positional Vertigo Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Benign Positional Vertigo Treatment Market Analytics
CE marking under the EU Medical Device Regulation is bifurcating competitive access for vestibular diagnostic platforms entering European markets. Medtronic leverages its neurosurgical navigation infrastructure to sustain leadership in balance training hardware. Pfizer anchors its position through generic meclizine distribution networks that dominate outpatient pharmacy channels.
Benign positional vertigo treatment encompasses pharmacologic, mechanical, and rehabilitative interventions targeting otoconial displacement within the semicircular canals, with canalith repositioning maneuvers such as the Epley procedure requiring precise angular acceleration parameters to achieve particle migration. Canalith repositioning maneuvers command the largest volume share due to guideline endorsement from the American Academy of Neurology, while vestibular rehabilitation captures expanding margins as value-based care contracts reward functional outcome metrics over procedural volume. Diagnostic equipment within the device type dimension concentrates margin pools among manufacturers achieving FDA 510(k) clearance for infrared video goggles with integrated eye-tracking.
FDA 510(k) premarket notification and the EU MDR conformity assessment framework shape product development timelines and commercialization sequencing for device manufacturers, with Japan's PMDA orphan device pathway creating additional regulatory complexity for novel repositioning technologies. The US Centers for Medicare & Medicaid Services physician fee schedule and Germany's G-BA benefit assessment process directly determine reimbursement thresholds that gate patient access across outpatient and hospital settings. Stakeholders must monitor evolving digital therapeutics classification decisions by FDA and notified bodies, as software-guided repositioning applications threaten to displace conventional hardware-dependent treatment protocols.
Market Dynamics
Software-guided canalith repositioning applications are fragmenting traditional hardware-dependent treatment protocols, forcing manufacturers to recalibrate commercialization strategies around digital therapeutics classification pathways.
Growth Catalysts
- Aging Demographics:Geriatric patient volumes in ambulatory settings across the United States, Germany, and Japan concentrate demand for outpatient vestibular interventions.
- FDA 510(k) Pathway:Streamlined premarket notification for infrared video goggles with integrated eye-tracking accelerates diagnostic platform commercialization timelines.
- Canalith Repositioning Maneuvers:Guideline endorsement from the American Academy of Neurology sustains procedural volume leadership over pharmacologic alternatives.
Market Restraints
- Reimbursement Threshold Rigidity:The US Centers for Medicare & Medicaid Services physician fee schedule and Germany's G-BA benefit assessment process gate patient access across care settings.
- Regulatory Fragmentation:Japan's PMDA orphan device pathway creates additional conformity complexity for novel repositioning technologies seeking multi-market entry.
- Specialist Supply Bottleneck:Limited trained vestibular therapists in rural geographies constrain service delivery expansion regardless of device availability.
Strategic Opportunities
- Digital Therapeutics Classification:FDA and EU notified body decisions on software-guided repositioning applications create regulatory tailwinds for algorithm-driven treatment protocols.
- Value-Based Care Contracts:Functional outcome metrics reward vestibular rehabilitation providers, expanding margin capture beyond procedural volume-based reimbursement.
- EU MDR Transition:CE marking bifurcation under the Medical Device Regulation creates competitive access gaps for compliant diagnostic platform entrants.
Industry Challenges
- Angular Acceleration Precision:Canalith repositioning maneuvers require exact parameter calibration, creating execution risk in non-specialist settings without standardized training protocols.
- Legacy Hardware Integration:Balance training hardware manufacturers face retrofit complexity when incorporating eye-tracking diagnostics into existing neurosurgical navigation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign Positional Vertigo Treatment Market |
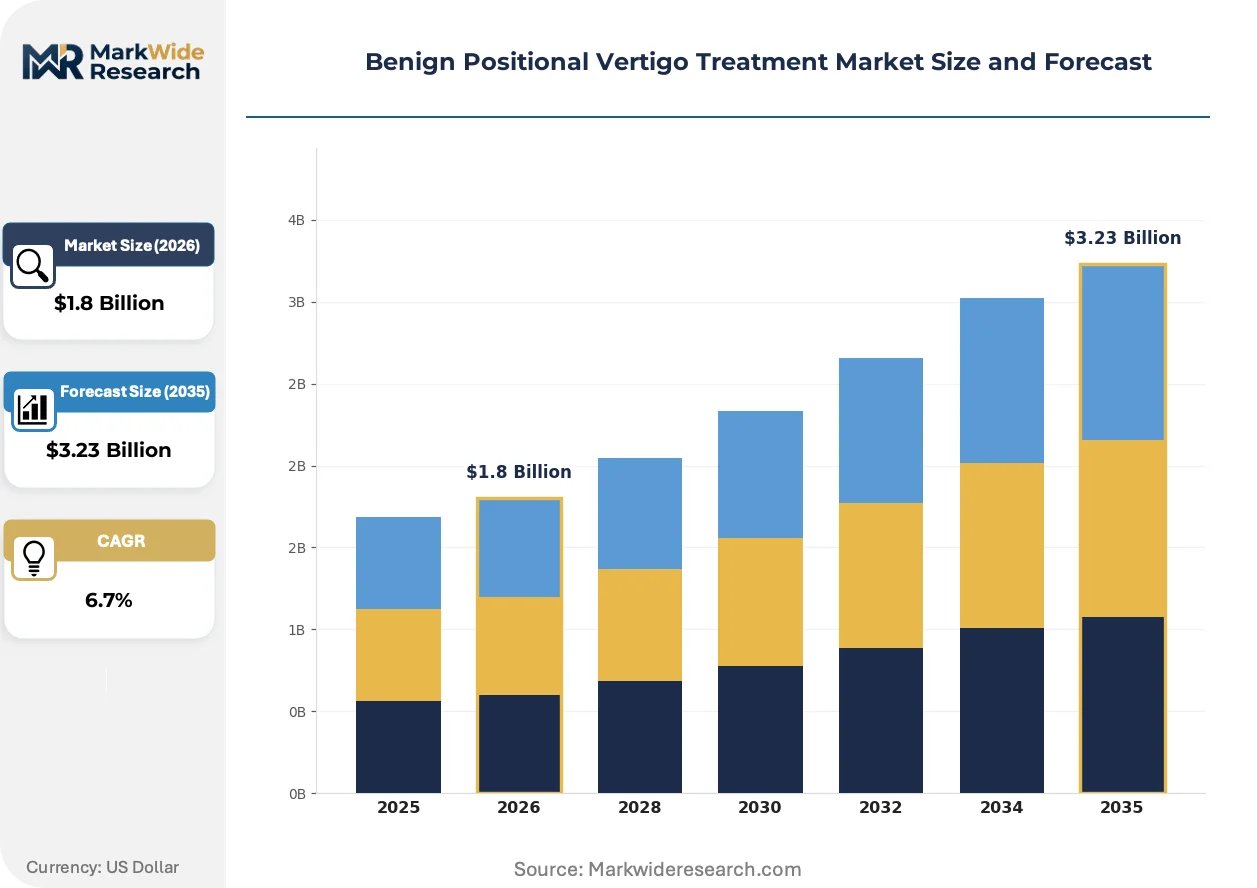
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Method: Medication, Canalith Repositioning Maneuvers, Vestibular Rehabilitation, Surgery Device Type: Diagnostic Equipment, Balance Training Devices, Hearing Aids, Rehabilitation Tools Patient Type: Adult Patients, Geriatric Patients, Pediatric Patients, Chronic Condition Patients Care Setting: Outpatient Clinics, Hospitals, Home Care, Rehabilitation Centers |
| Companies Covered | Dr. Reddy’s Laboratories Ltd., Medtronic, TympaHealth, Viatris Inc., Epic Pharma, LLC, Pfizer Inc., Sanofi, Novartis AG, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign Positional Vertigo Treatment Market Evolving Landscape
Digital therapeutics and sensor-based diagnostics are redrawing competitive boundaries between hardware manufacturers and software developers in vestibular care delivery.
Smartphone-based accelerometer applications for home canalith repositioning are fragmenting the traditional clinic-centric treatment model. Patients in managed care networks are piloting these tools for between-visit monitoring. The technology is fragmenting referral patterns by enabling primary care physicians to initiate treatment without specialist consultation.
The EU Medical Device Regulation's heightened clinical evidence requirements are extending conformity assessment timelines for vestibular diagnostic platforms. Manufacturers are restructuring technical documentation to address notified body backlogs. Infrared video goggle producers with legacy CE certificates under the Medical Device Directive face the steepest recertification burden.
After-sales service unbundling is reshaping procurement patterns for balance training hardware. Hospital systems are separating device acquisition from maintenance contracts, pressuring manufacturers to compete on discrete service modules. This shift is most pronounced in German outpatient rehabilitation centers operating under DRG-budget constraints.
Benign Positional Vertigo Treatment Market Segmentation
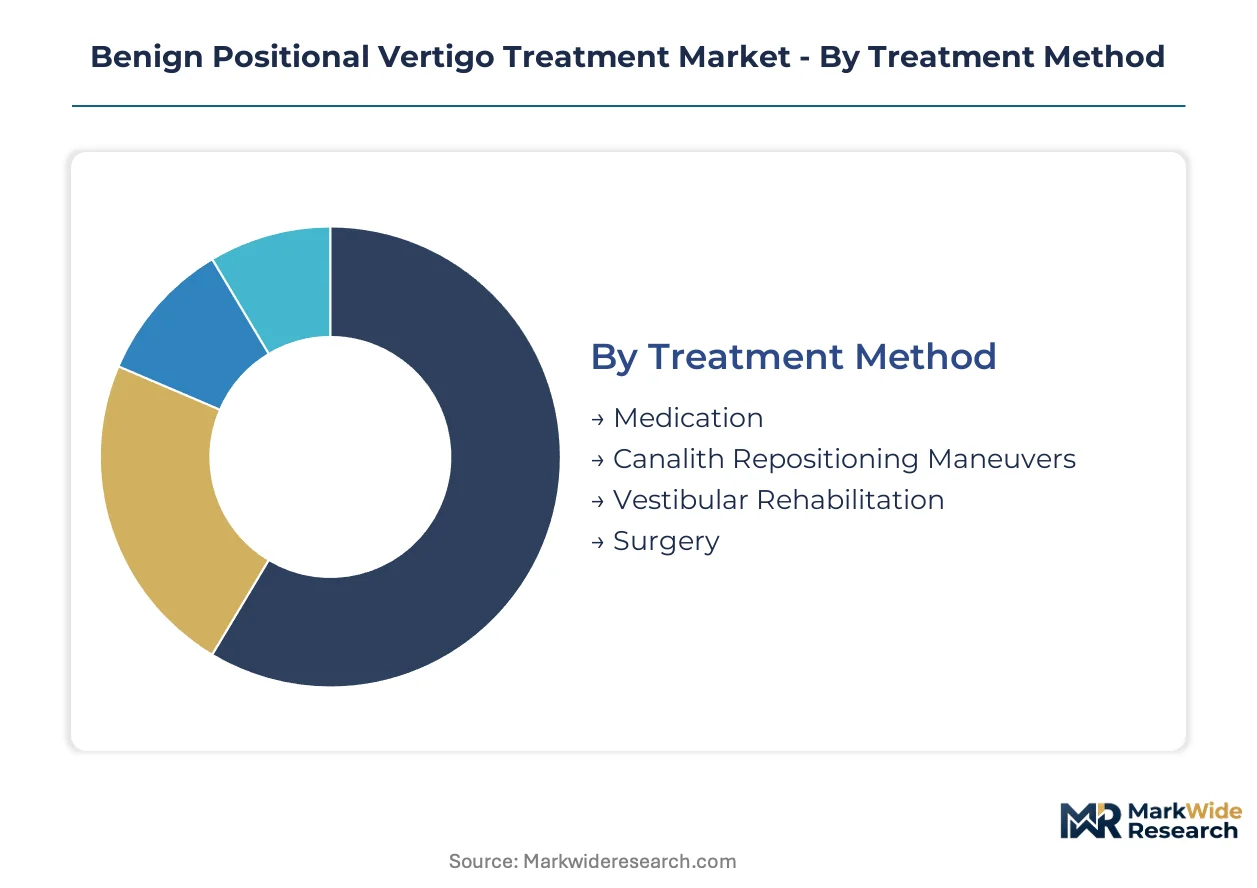
Segmentation in the benign positional vertigo treatment market reveals distinct margin architectures across intervention modalities, patient demographics, and care delivery venues. Each dimension carries unique regulatory, reimbursement, and competitive dynamics that shape vendor positioning and investment priorities.
Treatment Method:
Margin pools concentrate in procedural interventions with guideline endorsement and favorable outpatient reimbursement profiles.
- Canalith Repositioning Maneuvers:The Epley and Semont maneuvers involve precise head positioning sequences to migrate displaced otoconia from posterior semicircular canals. Demand clusters in ambulatory settings across the United States, Germany, and Japan where CMS and G-BA reimbursement codes reward same-day procedural completion.
- Vestibular Rehabilitation:Customized exercise protocols target central compensation mechanisms and gaze stabilization. Functional outcome metrics under value-based care contracts in US Medicare Advantage networks are accelerating provider adoption beyond traditional fee-for-service volumes.
- Medication:Generic vestibular suppressants including meclizine and benzodiazepines address acute symptom control.
- Surgery:Posterior semicircular canal occlusion and singular neurectomy procedures serve refractory cases.
The dominant share belongs to Canalith Repositioning Maneuvers, while Vestibular Rehabilitation is expanding most quickly as outcome-based contracts proliferate.
Device Type:
Technology differentiation separates diagnostic platforms with integrated eye-tracking from commodity rehabilitation hardware.
- Diagnostic Equipment:Infrared video goggles with integrated eye-tracking enable nystagmus recording during positional testing. FDA 510(k) clearance timelines and EU MDR conformity backlogs are concentrating procurement among hospital systems with established neurotology service lines in Boston, Munich, and Tokyo.
- Balance Training Devices:Computerized dynamic posturography systems assess sensory integration and motor control. German outpatient rehabilitation centers operating under DRG-budget constraints are unbundling after-sales service contracts, pressuring manufacturers to compete on discrete maintenance modules.
- Hearing Aids:Amplification devices with vestibular masking functions serve comorbid presentations.
- Rehabilitation Tools:Low-cost home exercise kits support between-visit compliance monitoring.
Diagnostic Equipment commands premium pricing power, though Balance Training Devices face procurement fragmentation as service unbundling spreads.
Patient Type:
Demographic concentration patterns align with aging population distributions and chronic disease prevalence corridors.
- Geriatric Patients:Age-related otoconial degeneration drives the highest procedural volume in Medicare-eligible populations. Ambulatory surgery centers in Florida, Arizona, and Pennsylvania are expanding dedicated vestibular clinics to capture this cohort.
- Adult Patients:Idiopathic and post-traumatic presentations in working-age populations. Employer-sponsored health plans in Japan's metropolitan prefectures are piloting direct-access pathways to reduce specialist referral delays.
- Pediatric Patients:Congenital and post-viral vestibular dysfunction in developmental contexts.
- Chronic Condition Patients:Recurrent or persistent symptoms requiring maintenance protocols.
Geriatric Patients anchor volume leadership, while Adult Patients are climbing the fastest as workplace productivity concerns elevate early intervention priority.
Care Setting:
Site-of-care migration is redistributing revenue between institutional and decentralized delivery models.
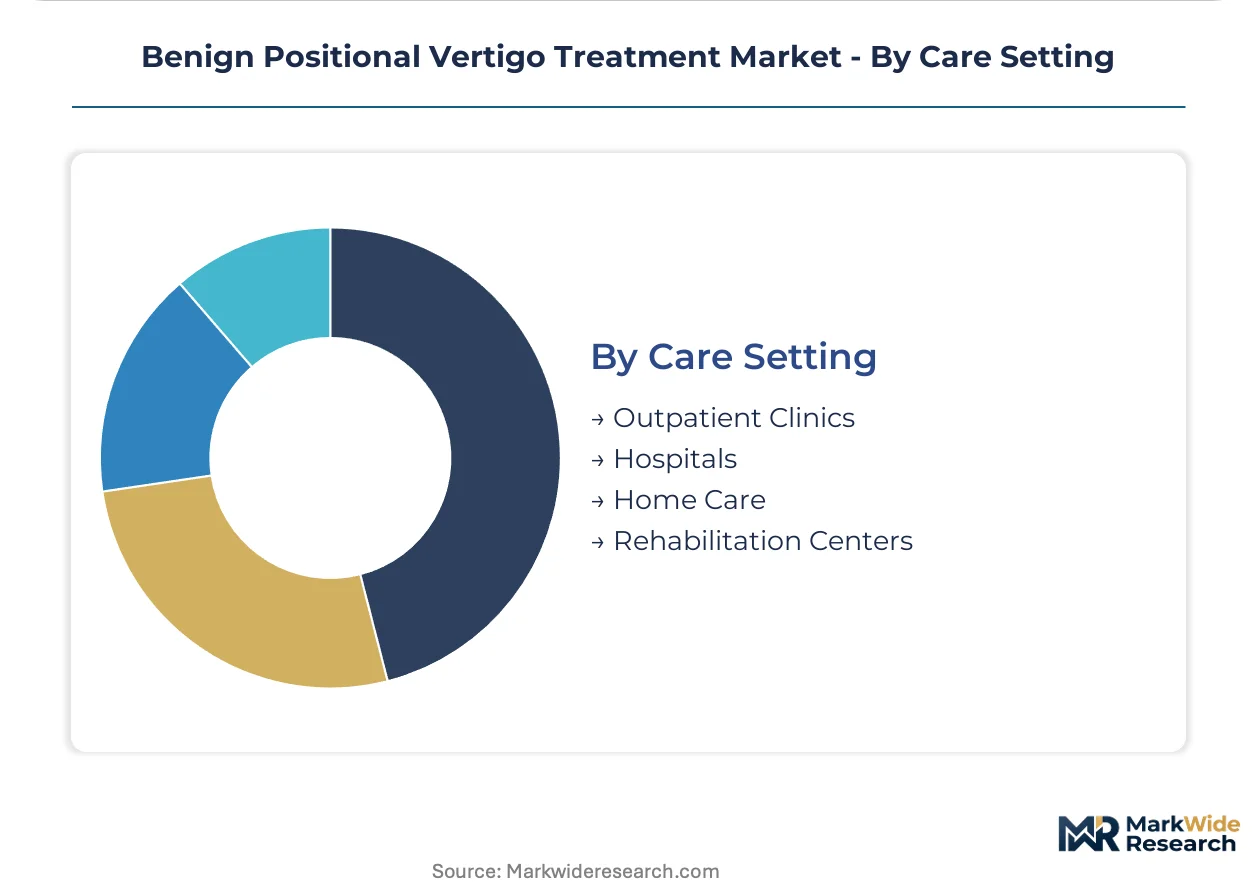
- Outpatient Clinics:Dedicated vestibular specialty practices and ENT group practices deliver the majority of canalith repositioning procedures. CMS physician fee schedule differentials favor office-based over facility-based billing for qualifying maneuvers.
- Home Care:Smartphone-based accelerometer applications and telehealth-guided repositioning are fragmenting traditional referral patterns. Primary care physicians in US managed care networks are initiating treatment without otolaryngology consultation.
- Hospitals:Emergency department evaluation and inpatient consultation for complex presentations.
- Rehabilitation Centers:Structured vestibular rehabilitation programs for functional recovery.
Outpatient Clinics retain the dominant share, though Home Care is gaining share fastest as digital therapeutics erode clinic-centric dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS physician fee schedule differentials favoring office-based billing are accelerating ambulatory vestibular service expansion in Medicare-eligible corridors. Japan's PMDA orphan device pathway and Germany's G-BA benefit assessment process create divergent regulatory entry costs for repositioning technology developers. The analysis concentrates on five countries where aging demographics and reimbursement alignment concentrate procedural volume.
United States
Ambulatory surgery centers in Florida, Arizona, and Pennsylvania are expanding dedicated vestibular clinics to capture geriatric Medicare populations. FDA 510(k) premarket notification streamlines infrared video goggle commercialization for manufacturers with predicate device pathways. The Boston neurotology cluster anchors diagnostic platform procurement among hospital systems with established service lines.
Germany
G-BA benefit assessment thresholds directly determine outpatient reimbursement for canalith repositioning procedures across ambulatory settings. CE marking under EU MDR extends conformity assessment timelines for vestibular diagnostic platforms entering European markets. Munich hospital systems concentrate procurement among manufacturers achieving notified body certification under heightened clinical evidence requirements.
Japan
Employer-sponsored health plans in metropolitan prefectures are piloting direct-access pathways to reduce specialist referral delays for working-age adults. METI industrial policy supports domestic medical device development through targeted subsidy programs. The Tokyo-Kanto corridor hosts the highest density of vestibular rehabilitation providers serving aging prefectural populations.
United Kingdom
NHS England tariff structures differentiate payment rates between community and hospital-based vestibular services. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways divergent from EU MDR timelines. London and Southeast England concentrate private diagnostic equipment procurement among ENT group practices.
India
CDSCO medical device registration requirements are formalizing quality standards for imported repositioning technologies entering private hospital chains. Ayushman Bharat insurance expansion is extending outpatient procedure coverage to tier-2 city populations previously excluded from vestibular care. Maharashtra and Karnataka anchor diagnostic platform distribution through metropolitan hospital networks in Mumbai and Bangalore.
Benign Positional Vertigo Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with generic distribution networks alongside specialized neurosurgical device manufacturers. Tier concentration is moderate, with three distinct competitive archetypes: generic vestibular suppressant suppliers, balance training hardware integrators, and digital therapeutic platform developers. M&A activity targets canalith repositioning device startups with FDA clearance, while strategic partnerships between diagnostic manufacturers and telehealth platforms accelerate home care market entry.
Within the pharmaceutical tier, Pfizer Inc. and Viatris Inc. represent generic meclizine distribution archetypes anchoring outpatient pharmacy channel dominance. Medtronic occupies a position exemplifying neurosurgical navigation infrastructure leverage for balance training hardware leadership. Among specialty pharmaceutical developers, Dr. Reddy's Laboratories Ltd. and Teva Pharmaceuticals sit within the generic vestibular suppressant supplier archetype serving cost-sensitive markets.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories Ltd. |
| Medtronic |
| TympaHealth |
| Viatris Inc. |
| Epic Pharma, LLC |
| Pfizer Inc. |
| Sanofi |
| Novartis AG |
| Teva Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Device manufacturing scale economies in infrared video goggle production concentrate procurement leverage among hospital systems in Boston, Munich, and Tokyo, compressing price floors for smaller diagnostic platform entrants while elevating margin capture for FDA 510(k) cleared manufacturers with established neurosurgical navigation infrastructure.
Pricing Analysis
Certification level (FDA 510(k)/CE MDR/PMDA-grade) creates the primary spread between premium diagnostic platforms and commodity rehabilitation hardware. Three-tier pricing structure across premium, standard, and economy levels stratifies by eye-tracking integration depth and after-sales service bundling. Cost compression in balance training devices is intensifying because German outpatient rehabilitation centers operating under DRG-budget constraints are unbundling maintenance contracts. Primary care networks in US managed care settings exhibit highest price sensitivity, while academic medical centers with established neurotology service lines demonstrate lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Strategic stockpiling of infrared sensor arrays and precision accelerometer components dominates inventory strategy among diagnostic equipment manufacturers navigating EU MDR conformity backlogs. Component sourcing concentrates in Japan for optical sensors, Germany for precision engineering subassemblies, and the United States for integrated eye-tracking modules. Raw material dependencies include semiconductor-grade silicon, rare-earth optical coatings, and medical-grade polymers for goggle housings. Single-source vulnerability in Japanese optical sensor suppliers creates supply chain risk given METI industrial policy constraints. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct tender processes in Germany, and domestic distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics classification decisions by FDA and EU notified bodies are accelerating disruption velocity, compressing traditional hardware-dependent commercialization windows and elevating algorithm-driven treatment protocols as viable substitutes for clinic-centric care delivery.
For Market Incumbents: Compound defensive positioning through backward integration into eye-tracking sensor production and exclusive hospital system partnerships in Medicare Advantage networks. Software-guided repositioning applications threaten to displace conventional diagnostic hardware, making CE MDR recertification investment and service contract unbundling essential margin protection levers. Canalith repositioning device manufacturers must accelerate FDA 510(k) predicate device pathway utilization before digital therapeutic platforms achieve comparable reimbursement codes.
For New Entrants and Emerging Players: Lead with smartphone-based accelerometer applications targeting home care settings where primary care physicians in US managed care networks are piloting direct-access treatment initiation. White-space concentration exists in rural geographies with limited trained vestibular therapists, and in employer-sponsored health plans in Japan's metropolitan prefectures seeking productivity-preserving interventions. Go-to-market execution should emphasize telehealth platform partnerships that fragment traditional specialist referral patterns.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vestibular rehabilitation providers with value-based care contracts in US Medicare Advantage networks, offering superior cash flow quality relative to procedural volume-dependent canalith repositioning device manufacturers. Acquisition target archetypes include FDA-cleared canalith repositioning device startups and digital therapeutic platforms with software-guided repositioning algorithms. The signal to watch is CMS physician fee schedule revisions affecting digital therapeutics reimbursement parity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates infrared video goggle commercialization for manufacturers with predicate device pathways. |
| CE Marking Pathway | Addresses EU MDR clinical evidence requirements that extend conformity assessment timelines. |
| Hospital System Partnership | Secures procurement preference among Boston neurotology clusters and Munich hospital networks. |
| Software Companion Development | Enables digital therapeutics classification for algorithm-driven repositioning protocols. |
| Reimbursement Strategy | Aligns with CMS physician fee schedule differentials favoring office-based billing. |
Research Methodology
Cross-validation between primary interviews with vestibular clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary sources including FDA 510(k) filings, CMS Medicare data, hospital procurement databases, and EU MDR notified body documentation. Bottom-up demand modeling across treatment method, device type, patient demographic, and care setting dimensions triangulates against top-down macroeconomic indicators and aging population projections.
Sensitivity analysis frameworks test forecast robustness across regulatory approval timeline scenarios, reimbursement code revision pathways, and digital therapeutic adoption curves. Segmentation dimensions modeled include intervention modality, technology integration level, patient age cohort, and site-of-care delivery model throughout the projection horizon. CAGRs derive from procedure volume trajectories, device replacement cycles, and pharmaceutical genericization patterns specific to vestibular care markets.
The analysis sits within stated boundaries; outcomes outside FDA digital therapeutics classification timelines, CMS reimbursement parity decisions, or EU MDR conformity assessment completion would require recalibration. Forecasts assume continued aging demographic concentration in ambulatory settings and sustained guideline endorsement from the American Academy of Neurology. Revision becomes warranted when software-guided repositioning applications achieve equivalent clinical outcome metrics to hardware-dependent protocols at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Cerebral Aneurysm Management Market
Neurology
South America Neurology Monitoring Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Status Epilepticus Treatment Market
Neurology
Nerve Repair Market
Neurology
Cluster Headache Syndrome Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Tourette Syndrome Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
India Neurology Devices Market
Neurology
North America Neurology Monitoring Market
Neurology
Vocal Cord Paralysis Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Argentina Neurology Devices Market
Neurology
UAE Neurology Devices Market