
 Parkinsons Disease Therapeutics Market | 2026-2036
Parkinsons Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Parkinsons Disease Therapeutics Market Analysis
Gene-silencing platforms and targeted protein degradation is rewriting the therapeutic architecture for Parkinson's disease, shifting pipelines away from pure symptomatic management toward disease-modifying mechanisms. AbbVie leverages its antibody-drug conjugate expertise to build neurodegeneration assets with blood-brain barrier penetration. Teva Pharmaceutical Industries Ltd. anchors its position through generic levodopa portfolios and complex formulation capabilities. F. Hoffmann-La Roche competes in the biomarker-guided therapy space with cerebrospinal fluid diagnostic platforms.
Parkinson's disease therapeutics comprise pharmaceutical agents designed to modulate dopaminergic neurotransmission, reduce motor complications, or slow neurodegenerative progression through mechanisms targeting alpha-synuclein aggregation, mitochondrial dysfunction, or neuroinflammation. These compounds typically require blood-brain barrier permeability, striatal specificity, and precise pharmacokinetic profiles to manage the progressive loss of substantia nigra dopaminergic neurons. Dopamine Agonists occupy the largest revenue pool as first-line monotherapy for early-stage patients, though their margin profile faces pressure from generic erosion. Disease-Modifying Therapy represents the fastest-expanding treatment approach category, driven by investor funding for immunotherapy and gene therapy candidates. Oral delivery mode retains volume dominance, yet transdermal systems capture premium pricing for patients with dysphagia or fluctuating motor responses.
FDA breakthrough therapy and orphan drug designations shape clinical trial investment and commercial prioritization for developers, while EMA's adaptive pathway accelerates European access for therapies demonstrating surrogate endpoint benefit. The central bank of reimbursement—CMS in the United States and NICE in the United Kingdom—determines real-world uptake through incremental cost-effectiveness thresholds and coverage restrictions. Stakeholders must monitor biomarker validation progress and health technology assessment evolution to align portfolio bets with payer willingness to fund premium-priced disease-modifying interventions.
Market Dynamics
Gene-silencing platforms and targeted protein degradation are rewriting therapeutic architecture, shifting pipelines away from symptomatic management toward disease-modifying mechanisms that alter competitive positioning across the Parkinson's landscape.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses timelines for novel dopaminergic agents, incentivizing investment in neurodegeneration portfolios by reducing regulatory uncertainty and capital lock-up periods.
- Medicare Home Infusion Expansion:CMS coverage broadening for subcutaneous and pump-based delivery systems expands patient access to advanced therapies outside institutional settings, reshaping utilization patterns for late-stage patients.
- Biomarker-Guided Patient Stratification:Cerebrospinal fluid diagnostic platforms enable precision enrollment in clinical trials, improving signal detection for disease-modifying candidates and de-risking late-stage development programs.
Market Restraints
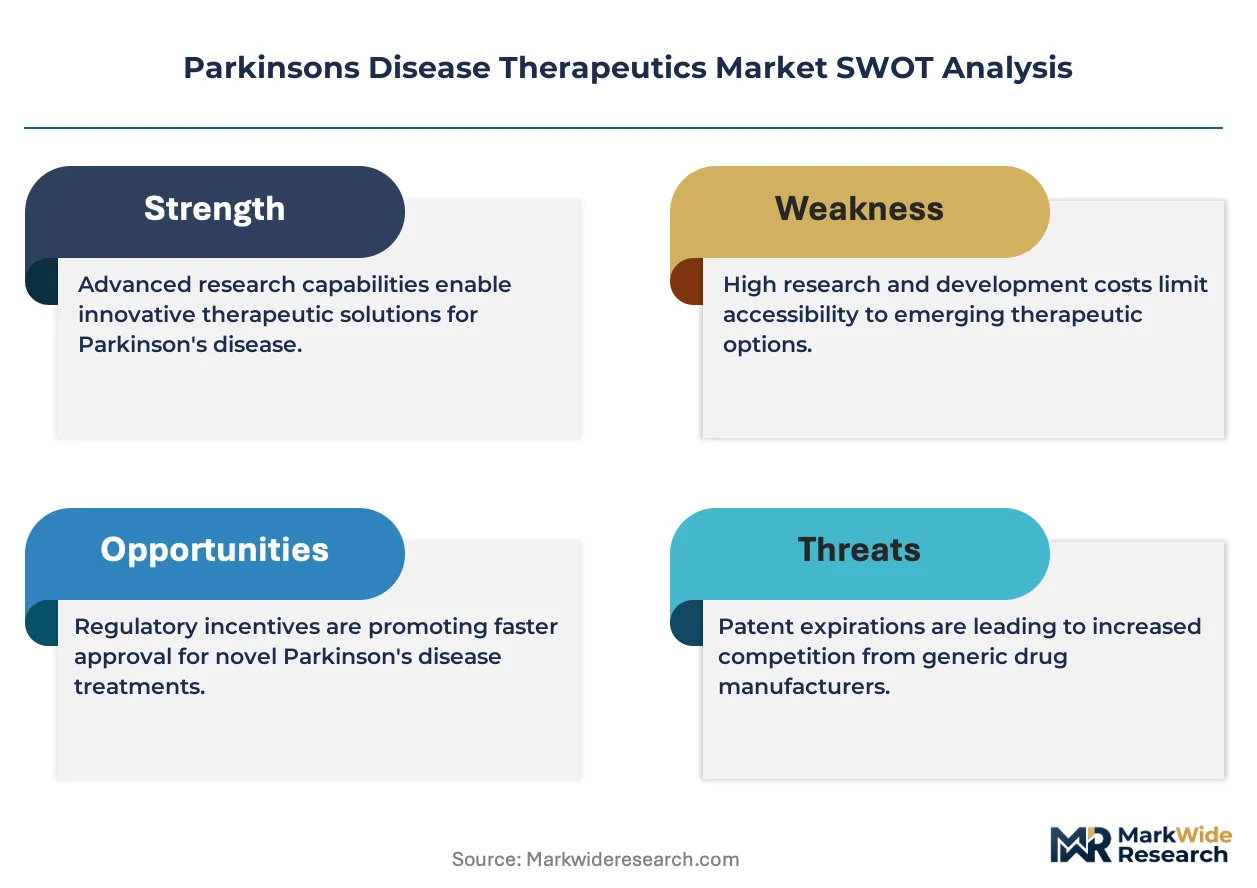
- Generic Levodopa Erosion:Commoditization of first-line dopamine replacement therapies compresses margin pools for oral formulations, forcing developers toward complex delivery systems to defend pricing power.
- Blood-Brain Barrier Impermeability:Structural limitations in CNS drug delivery require costly formulation engineering or invasive administration routes, elevating development costs and restricting viable mechanisms of action.
- EMA Adaptive Pathway Uncertainty:Conditional approval based on surrogate endpoints creates commercial risk for European launches, as subsequent confirmatory trials may fail to validate clinical benefit.
Strategic Opportunities
- Specialty Pharmacy Channel Growth:Distribution through limited-distribution networks for gene therapies and complex biologics enables patient monitoring infrastructure and outcomes-based contracting with payers.
- Transdermal System Expansion:Patch-based delivery addresses dysphagia and motor fluctuation challenges in advanced patients, capturing premium pricing through differentiated administration profiles.
- Alpha-Synuclein Immunotherapy White Space:Active and passive vaccination approaches against pathological protein aggregates represent an underexploited mechanism with potential for disease modification.
Industry Challenges
- Neurodegeneration Clinical Trial Design:Slow disease progression and heterogeneous patient populations require extended observation periods and large enrollment targets, straining capital efficiency.
- Biomarker Validation Timelines:Regulatory acceptance of novel surrogate endpoints for disease modification lags behind scientific discovery, delaying pivotal trial initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parkinsons Disease Therapeutics Market |
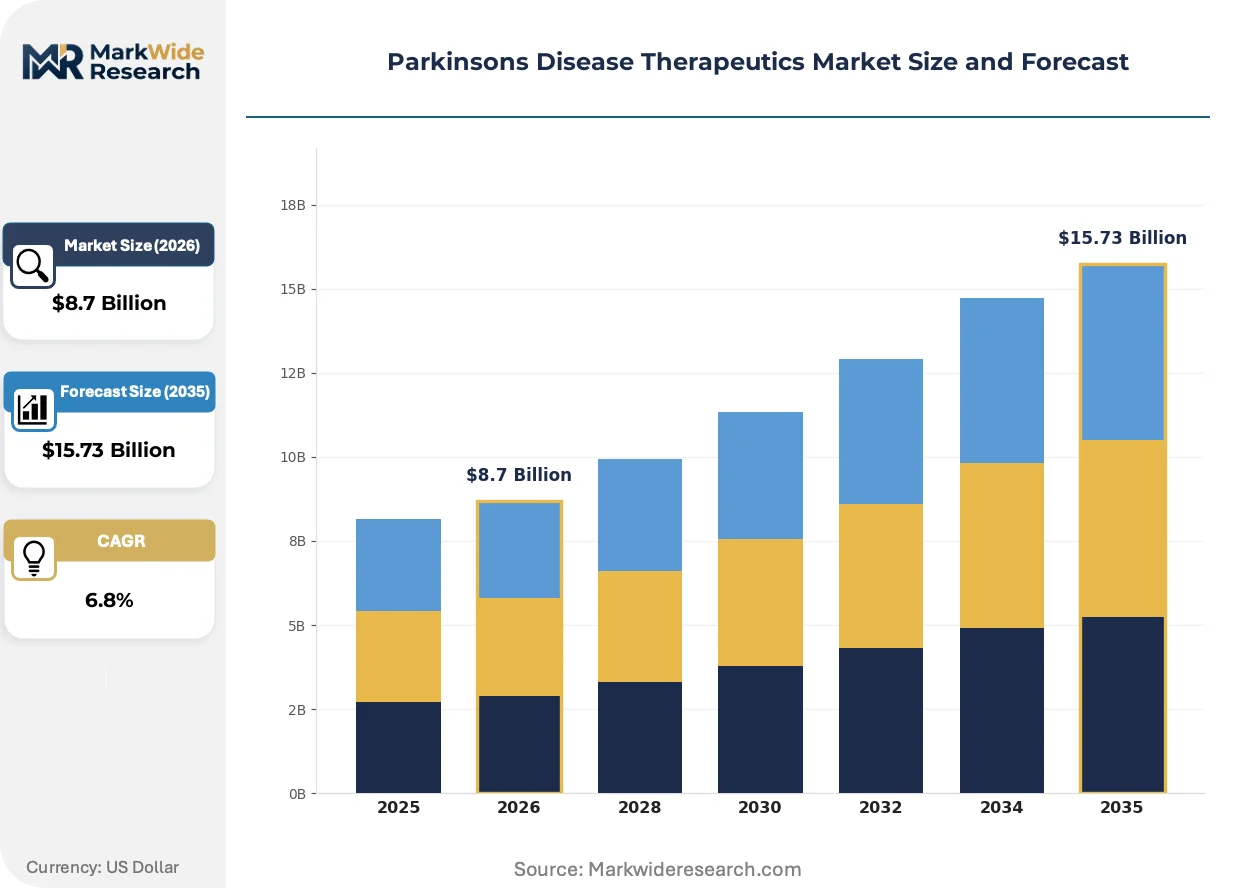
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dopamine Agonists, MAO-B Inhibitors, Anticholinergics, COMT Inhibitors Delivery Mode: Intravenous, Oral, Transdermal, Inhalation End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Treatment Approach: Symptomatic Treatment, Disease-Modifying Therapy, Combination Therapy, Palliative Care |
| Companies Covered | AbbVie, Teva Pharmaceutical Industries Ltd., Novartis AG, F. Hoffmann-La Roche, Acadia Pharmaceuticals, Boehringer Ingelheim, UCB, GlaxoSmithKline, Amneal Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parkinsons Disease Therapeutics Market Emerging Trajectories
Digital biomarker platforms and continuous monitoring systems are virtualizing traditional endpoint capture, compressing trial durations while enabling real-world evidence generation that reshapes how therapeutic value gets demonstrated to payers.
Continuous dopaminergic stimulation via subcutaneous infusion pumps and intestinal gel delivery is virtualizing the pharmacokinetic profile of oral levodopa, eliminating peak-trough fluctuations that drive motor complications. Neurologists in tertiary movement disorder centers are adopting these systems for patients with advanced disease progression. The technology is virtualizing the standard of care for refractory motor fluctuations, compressing hospitalization rates and emergency department utilization.
EMA's adaptive pathway framework for medicines addressing unmet medical needs is accelerating European market access for therapies demonstrating surrogate endpoint benefit in Phase II trials. Developers gain conditional approval with post-marketing confirmatory obligations, reducing time-to-revenue but introducing commercial risk. Disease-modifying immunotherapy candidates with cerebrospinal fluid biomarker readouts are most affected, with sponsors building European launch infrastructure earlier in development cycles.
Home-based care models are displacing institutional infusion centers for advanced Parkinson's therapies, with specialty pharmacies deploying nursing networks for subcutaneous administration and device management. This channel shift reduces patient travel burden and caregiver time costs while enabling real-world outcomes data capture. The United States exhibits the most pronounced migration, driven by Medicare reimbursement alignment with home health service expansion.
Parkinsons Disease Therapeutics Market Segmentation
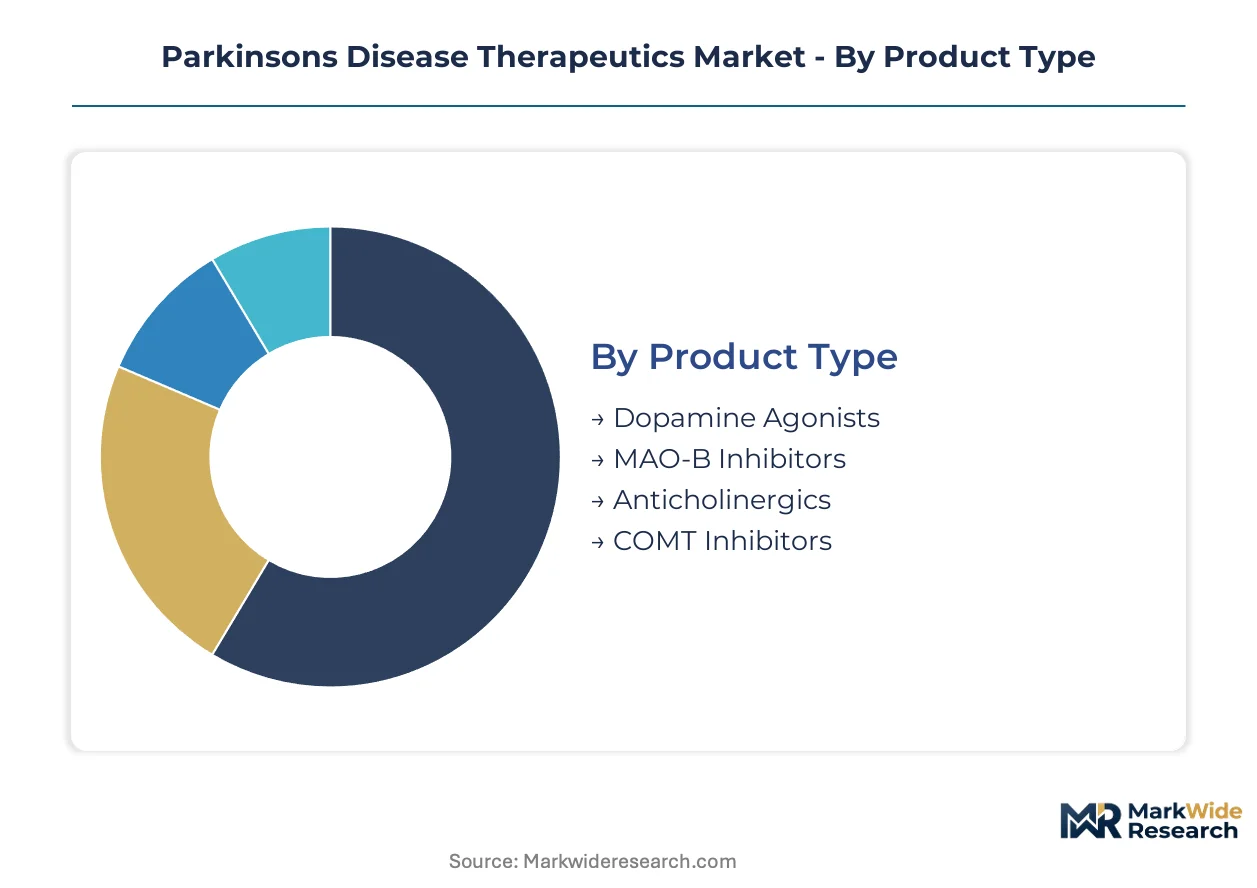
Therapeutic segmentation in Parkinson's disease reflects divergent clinical priorities across disease stages, from early motor symptom control to late-stage complication management. Product type and delivery mode selections directly determine reimbursement pathways, prescriber specialization requirements, and patient adherence profiles.
Product Type:
Use-case spectrum spans first-line monotherapy for de novo patients through adjunctive agents for motor fluctuation management in advanced disease.
- Dopamine Agonists:Non-ergot compounds such as pramipexole and ropinirole directly stimulate striatal dopamine receptors without metabolic conversion. Demand concentrates in the United States among movement disorder specialists managing early-stage patients, though generic erosion pressures originator pricing. The dominant share belongs to Dopamine Agonists, while Disease-Modifying Therapy is closing the gap fastest.
- MAO-B Inhibitors:Selective monoamine oxidase-B blockade extends endogenous dopamine half-life through reduced catabolism. Rasagiline and selegiline formulations see strongest uptake in European markets where EMA guidelines emphasize neuroprotection hypotheses, constrained by mixed clinical trial outcomes for disease modification claims.
- Anticholinergics:Centrally acting muscarinic antagonists address tremor-predominant phenotypes in younger patients. Germany's neurology practices retain higher utilization than Anglo-American markets due to divergent risk-benefit assessments for cognitive side effects.
- COMT Inhibitors:Catechol-O-methyltransferase inhibition extends levodopa bioavailability when co-administered with carbidopa-levodopa. Entacapone and opicapone serve adjunctive roles in patients experiencing wearing-off phenomena, with opicapone's once-daily profile gaining formulary preference in NHS England territories.
Margin concentration follows patent exclusivity, with extended-release formulations and fixed-dose combinations defending premium positioning against commodity oral generics.
Delivery Mode:
Route selection maps to disease progression trajectory and swallowing function preservation, creating distinct competitive arenas by administration complexity.
- Oral:Immediate-release and extended-release tablets dominate prescription volume through familiarity and pharmacy accessibility. Japan's PMDA has accelerated reviews for levodopa-carbidopa intestinal gel oral equivalents, though true bioequivalence remains challenging for narrow therapeutic index compounds.
- Transdermal:Rotigotine patches provide continuous dopaminergic stimulation without gastrointestinal absorption variability. Demand clusters in Germany and France among patients with dysphagia or unpredictable gastric emptying, where specialty nursing support enables patch rotation protocols.
- Intravenous:Subcutaneous apomorphine infusion and levodopa-carbidopa intestinal gel require surgical placement of gastrostomy or duodenal access ports. The United Kingdom's NICE technology appraisals restrict coverage to tertiary movement disorder centers with demonstrated complication management capabilities.
- Inhalation:Inhaled levodopa powder addresses acute off-episodes through rapid pulmonary absorption. US Medicare coverage expansion for home self-administration has shifted utilization from emergency departments to patient-controlled rescue therapy, though bronchospasm risk requires spirometry screening.
Oral administration retains volume leadership, yet transdermal and infusion modalities capture disproportionate value through differentiated clinical outcomes in refractory populations.
End User:
Site-of-care migration reflects reimbursement incentives, therapy complexity, and caregiver burden redistribution across the disease continuum.
- Specialty Pharmacies:Limited-distribution networks manage gene therapy candidates, complex biologics, and infusion pump supplies with mandatory patient monitoring. The United States exhibits the most pronounced channel concentration, driven by Medicare alignment with home health service expansion and outcomes-based contracting infrastructure.
- Hospitals:Tertiary academic medical centers handle deep brain stimulation programming, pump implantation surgeries, and acute complication management. Germany's university hospitals anchor European volume for device-augmented therapies through integrated movement disorder multidisciplinary teams.
- Home Care:Subcutaneous infusion and oral therapies with stable dosing regimens shift to residential settings as disease progresses. France's HAS reimbursement reforms have accelerated nursing deployment for apomorphine administration, reducing institutional days.
- Clinics:Community neurology practices manage stable patients on oral monotherapy with periodic specialist referral for motor complication emergence. India's tier-2 cities see clinic concentration as CDSCO streamlined approvals expand generic levodopa access beyond metropolitan hospitals.
Institutional sites anchor complex intervention volume, though home-based administration is gaining share fastest as infusion technologies simplify.
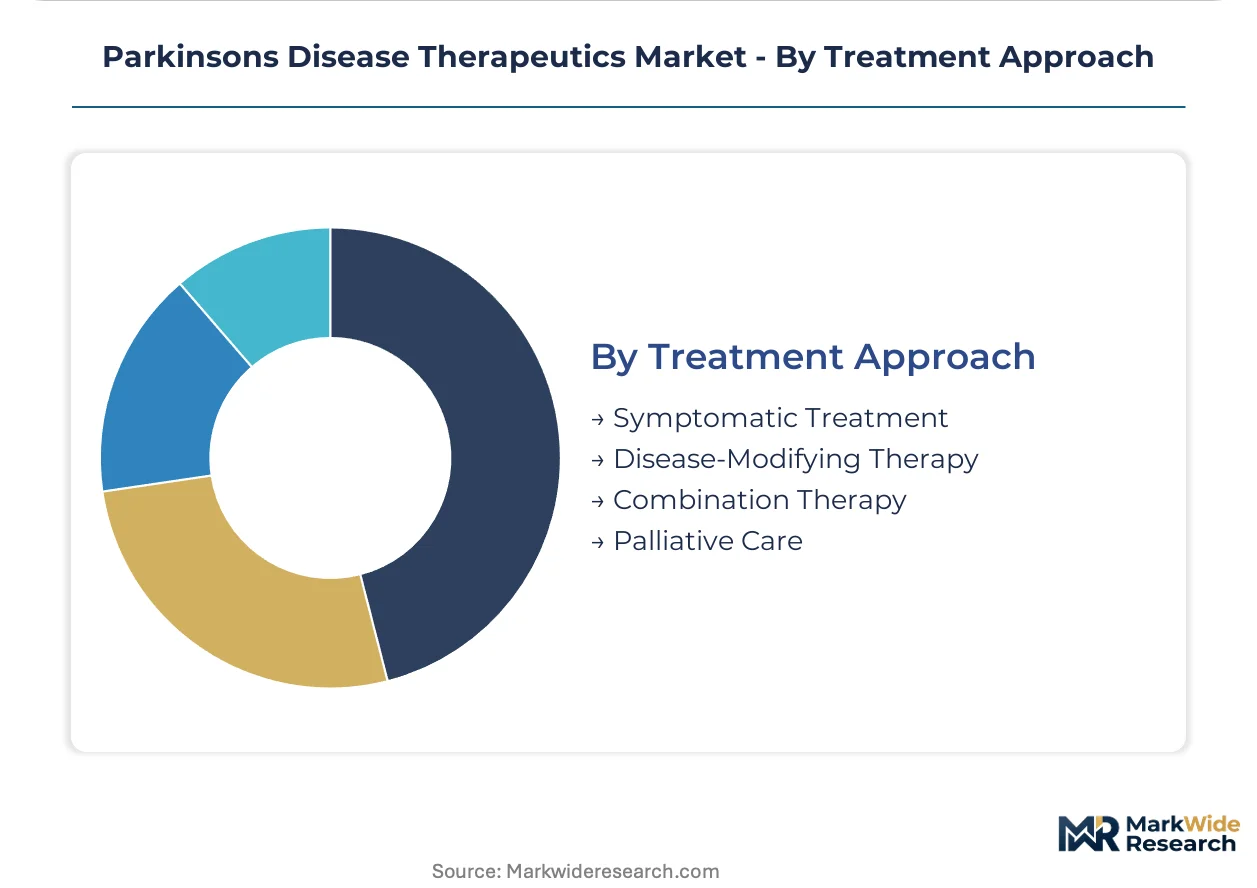
Treatment Approach:
Strategic positioning divides between symptom palliation with established mechanisms and disease modification with unproven but potentially transformative mechanisms.
- Symptomatic Treatment:Dopamine replacement and receptor stimulation address motor and non-motor manifestations without altering neurodegenerative progression. This segment commands current revenue concentration through mature portfolios at AbbVie, Teva, and Sunovion.
- Disease-Modifying Therapy:Immunotherapy against alpha-synuclein, gene silencing platforms, and targeted protein degradation aim to slow or halt neuronal loss. Roche's cerebrospinal fluid diagnostic platforms enable patient stratification for these candidates, though regulatory acceptance of surrogate endpoints remains pending at FDA and EMA.
- Combination Therapy:Rational polypharmacy combining levodopa with dopamine agonists, COMT inhibitors, or MAO-B inhibitors optimizes motor control while minimizing individual agent adverse effects. Prescribing patterns vary substantially between US academic centers and European community neurology.
- Palliative Care:Late-stage management addresses dysphagia, dementia, and autonomic failure through multidisciplinary supportive services. Hospice integration remains underdeveloped relative to oncology, presenting structural opportunity for payers and providers.
Symptomatic approaches retain commercial dominance, yet disease-modifying candidates are expanding most quickly through venture funding and pharmaceutical pipeline prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in Parkinson's disease therapeutics favor net-importing markets with aging populations and established reimbursement infrastructure. The United States absorbs the largest share of advanced therapy shipments, while Germany and Japan concentrate manufacturing of dopaminergic active pharmaceutical ingredients. Switzerland and the United Kingdom function as specialized hubs for clinical trial logistics and biomarker platform development.
United States
Medicare coverage expansion for home infusion services and subcutaneous pump delivery is reshaping patient access patterns for advanced Parkinson's therapies. FDA breakthrough therapy designations compress approval timelines for novel dopaminergic agents, accelerating commercial launches. The Boston-Cambridge corridor anchors neurodegeneration R&D concentration, with Massachusetts General Hospital's movement disorder center driving protocol development for disease-modifying trials.
Germany
University hospitals in Bavaria and North Rhine-Westphalia retain higher utilization of device-augmented therapies than Anglo-American markets, with integrated multidisciplinary teams managing complex pump implantations. The country's national pharmaceutical regulator, BfArM, maintains stringent requirements for orphan drug pricing negotiations, constraining premium positioning for novel agents. Frankfurt's specialty pharmacy networks concentrate distribution for transdermal rotigotine systems across the DACH region.
Japan
PMDA accelerated review pathways for levodopa-carbidopa intestinal gel equivalents address the world's most aged population, where dysphagia prevalence drives demand for non-oral delivery modes. The Ministry of Health, Labour and Welfare's reimbursement listing process prioritizes therapies demonstrating reduction in caregiver burden. Tokyo's metropolitan hospital clusters dominate deep brain stimulation volume, with Keio University Hospital anchoring surgical training programs.
Switzerland
Swissmedic's early access programs for medicines addressing unmet medical needs attract pharmaceutical sponsors seeking European launch infrastructure. Basel's pharmaceutical corridor concentrates headquarters for neurodegeneration portfolio holders, with proximity to Novartis and Roche driving biomarker-guided therapy development. Geneva's contract research organizations specialize in cerebrospinal fluid diagnostic logistics for multinational trials.
United Kingdom
NICE technology appraisals restrict coverage for intestinal gel and apomorphine infusion to tertiary movement disorder centers with demonstrated complication management capabilities, concentrating advanced therapy access. The NHS England's specialized commissioning framework centralizes funding for disease-modifying immunotherapy candidates entering conditional approval pathways. London's National Hospital for Neurology and Neurosurgery anchors the country's largest deep brain stimulation programming volume.
Parkinsons Disease Therapeutics Market Vendor Landscape
On the supply side, the industry is consolidating around large-cap pharmaceutical portfolios with neurodegeneration assets, while mid-cap specialists defend positions through complex formulation capabilities and generic substitution strategies. Three archetypes dominate: diversified conglomerates with antibody-drug conjugate expertise, pure-play neurology specialists with movement disorder focus, and generic manufacturers with vertical integration into active pharmaceutical ingredients. Competitive moves center on biomarker platform acquisitions and specialty pharmacy channel partnerships to secure limited-distribution networks.
Within the diversified pharmaceutical tier, AbbVie and F. Hoffmann-La Roche occupy positions exemplifying contrasting strategic approaches to neurodegeneration—one leveraging immunology infrastructure, the other anchoring diagnostic-guided therapy development. Teva Pharmaceutical Industries Ltd. represents the generic-complex formulation hybrid archetype, with its portfolio spanning commodity levodopa through advanced delivery systems. These three entities illustrate how therapeutic architecture shifts from symptomatic management toward disease-modifying mechanisms are reshaping competitive positioning across the Parkinson's landscape.
| Leading Market Players |
|---|
| AbbVie |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| F. Hoffmann-La Roche |
| Acadia Pharmaceuticals |
| Boehringer Ingelheim |
| UCB |
| GlaxoSmithKline |
| Amneal Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Basel's pharmaceutical corridor anchors European manufacturing of dopaminergic active pharmaceutical ingredients, with capacity utilization rates at contract manufacturers directly conditioning pricing power for finished dosage forms. This geographic concentration creates asymmetric negotiating leverage for originators of complex delivery systems against generic commoditization pressures in oral levodopa markets.
Pricing Analysis
Next-generation disease-modifying immunotherapy candidates command substantial premiums over established dopamine agonist formulations and commodity levodopa generics. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy candidates with orphan drug exclusivity from extended-release formulations and immediate-release generics. Pricing pressure stems from Medicare's incremental cost-effectiveness thresholds for disease-modifying therapies, constraining premium capture. Hospital procurement committees exhibit highest price sensitivity for oral generics, while movement disorder specialists in tertiary centers demonstrate lowest sensitivity for device-augmented delivery systems.
Supply Chain Analysis
Extended payment terms from specialty pharmacy distributors to manufacturers have become standard practice, with supply-chain finance facilities enabling working capital management for mid-cap formulation specialists. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with hyoscine, levodopa, and carbidopa as critical inputs. Single-source vulnerability for blood-brain barrier penetration technologies elevates risk profiles for novel neurodegeneration assets. Distribution runs through limited-distribution specialty pharmacy networks for gene therapies and complex biologics, with hospital-based procurement handling device-augmented interventions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parkinson's disease therapeutics operates as a defensive-moat market where regulatory entrenchment through FDA breakthrough therapy and orphan drug designations creates durable competitive barriers against generic substitution and biosimilar entry.
For Market Incumbents: Build regulatory entrenchment through biomarker-guided patient stratification platforms that de-risk late-stage development and accelerate approval timelines. Secure limited-distribution specialty pharmacy partnerships to control channel access for complex delivery systems against emerging generic manufacturers. Vertical integration into cerebrospinal fluid diagnostic capabilities reinforces differentiation as payer access tightens for premium-priced disease-modifying candidates. For New Entrants and Emerging Players: Establish a beachhead in alpha-synuclein immunotherapy white space, where active and passive vaccination approaches remain underexploited relative to symptomatic management mechanisms. Target transdermal system expansion for dysphagia patients as the most penetrable delivery mode segment, capturing premium pricing through differentiated administration profiles. Pursue outcomes-based contracting with Medicare Advantage plans as the primary go-to-market angle, leveraging real-world evidence generation infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with device-augmented therapy portfolios and long-term infusion pump supply agreements. Long-term viability across the projection horizon favors acquisition targets with biomarker platform assets and blood-brain barrier penetration technologies rather than pure-play generic manufacturers. Watch for FDA acceptance of novel surrogate endpoints for disease modification as the critical inflection indicator for pipeline valuation re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Platform Acquisition | Roche's cerebrospinal fluid diagnostics enable precision enrollment in disease-modifying trials, de-risking late-stage development. |
| Specialty Pharmacy Partnership | Limited-distribution networks for gene therapies create mandatory patient monitoring infrastructure and outcomes-based contracting capability. |
| Transdermal System Expansion | Patch-based rotigotine delivery addresses dysphagia and motor fluctuation challenges, capturing premium pricing in Germany and France. |
| Regulatory Pathway Optimization | FDA breakthrough therapy designation compresses approval timelines for novel dopaminergic agents, reducing capital lock-up periods. |
| Home Infusion Infrastructure | Medicare coverage expansion for subcutaneous pump delivery reshapes patient access patterns outside institutional settings. |
Methodological Framework
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary fieldwork with hospital procurement managers and movement disorder neurologists validated secondary findings on utilization patterns and reimbursement dynamics. Bottom-up patient-flow modeling and top-down epidemiological triangulation converged on market size estimates across segmentation dimensions.
Assumptions held fixed include current FDA and EMA regulatory frameworks, existing Medicare reimbursement structures for home infusion services, and prevailing specialty pharmacy distribution economics. Variable assumptions encompass biomarker validation timelines, surrogate endpoint acceptance criteria, and payer willingness-to-pay thresholds for disease-modifying therapies. The analytical framework modeled treatment line, dosage form, administration route, and patient population segments across the analysis window. CAGRs derived from patent expiry schedules, generic entry assumptions, and pipeline probability-adjusted revenue forecasts.
Sensitivities concentrate around regulatory acceptance of novel surrogate endpoints, confirmatory trial outcomes for conditionally approved therapies, and CMS coverage determinations for premium-priced interventions. Forecasts reflect documented assumptions regarding biomarker platform adoption and health technology assessment evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Chordoma Disease Market
Neurology
Neurological Biomarkers Market
Neurology
US Optic Neuritis Market
Neurology
Brazil Neurology Devices Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Arachnoiditis Treatment Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Japan Neurology Devices Market
Neurology
Spain Neurology Devices Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
United States Neurology Devices Market
Neurology
Hepatic Encephalopathy Market
Neurology
Arachnoiditis Market
Neurology
Global MRI Guided Neurosurgical Ablation Market