
 Middle-East and Africa Meglitinide Market | 2026-2036
Middle-East and Africa Meglitinide Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Meglitinide Market Foresight
Capital-intensity divergence between large-scale API manufacturers and regional formulation packagers is reorganizing competitive tiers in the Middle-East and Africa Meglitinide Market. Novo Nordisk leverages its integrated insulin-to-oral glucose-lowering portfolio to dominate hospital tenders across the Gulf Cooperation Council. Glenmark Pharmaceuticals anchors its position through aggressive generic repaglinide pricing in Sub-Saharan Africa. Hikma Pharmaceuticals competes via localized manufacturing licenses in Egypt and Jordan, reducing import duty exposure.
Meglitinides comprise a class of non-sulfonylurea insulin secretagogues that bind to ATP-dependent potassium channels on pancreatic beta cells, triggering rapid, glucose-dependent insulin release with shorter duration than sulfonylureas. Repaglinide and nateglinide serve primarily as prandial glucose regulators for Type 2 diabetes patients with erratic meal timing or sulfonylurea intolerance. Among product types, generics occupy the volume lead due to compulsory licensing pressures and national tender systems, while combination therapies containing repaglinide-metformin capture widening prescriber preference in outpatient clinics. Tablet formulations sustain dominant share across distribution channels, though oral suspension demand is accelerating in pediatric and geriatric home care segments where swallowing difficulties limit tablet adherence.
South Africa's SAHPRA enforces bioequivalence protocols for generic meglitinides that delay market entry but elevate clinical confidence among endocrinologists. Egypt's EDA and Saudi Arabia's SFDA have both aligned with ICH stability guidelines, forcing reformulation investments for heat-stressed supply chains. Stakeholders must monitor how Gulf states' localization mandates reshape manufacturing partnerships and whether Nigeria's NAFDAC harmonization with WHO prequalification opens new procurement corridors.
Market Dynamics
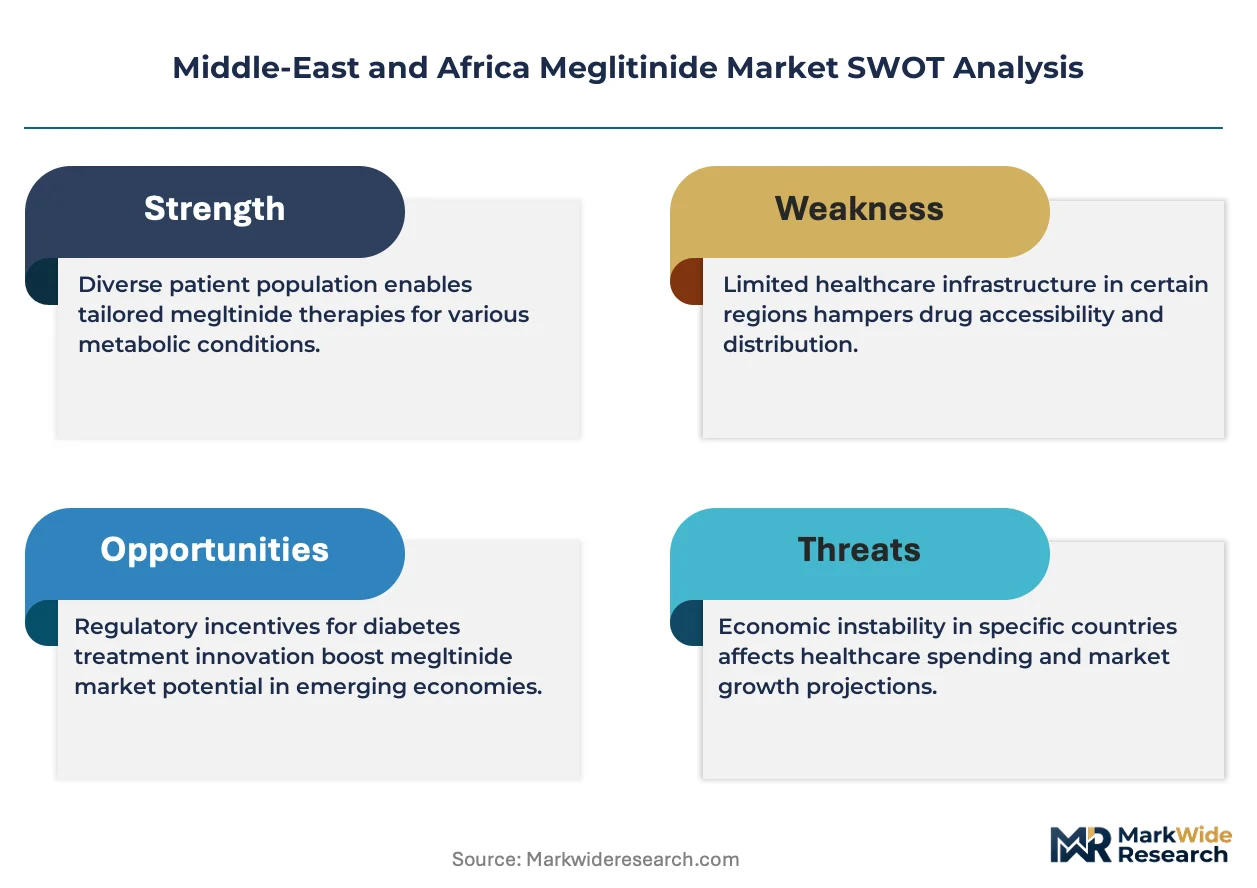
Hospital tender systems across the Gulf Cooperation Council are consolidating procurement volumes, forcing manufacturers to choose between margin compression and exit from public sector channels. This structural pressure is redrawing competitive boundaries between multinational originators and regional generic suppliers.
Growth Catalysts
- Prandial glucose management protocols:Endocrinology departments in Saudi Arabia and UAE are expanding repaglinide use for patients with irregular meal patterns. This clinical preference shift drives volume through hospital formularies.
- SFDA bioequivalence alignment:Saudi Arabia's tightened generic approval standards are elevating prescriber confidence in locally manufactured meglitinides. Hospital pharmacists increasingly favor certified domestic suppliers.
- Heat-stability formulation investments:Egyptian manufacturers are reformulating tablet coatings to withstand 40°C+ supply chain conditions. This technical adaptation opens distribution to Saharan and Sahel markets previously served by cold-chain-dependent alternatives.
Market Restraints
- API import dependency:Regional formulators rely on Chinese and Indian active pharmaceutical ingredient suppliers. Concentration risk in upstream sourcing exposes margins to currency volatility and geopolitical friction.
- Sulfonylurea substitution economics:Glimepiride and gliclazide dominate public tenders at 60-70% lower unit cost. Payers in Nigeria and Kenya default to these alternatives unless contraindication documentation is provided.
- Bioequivalence study costs:SAHPRA and SFDA now mandate local clinical trials for generic registration. Small-scale manufacturers in Jordan and Lebanon lack capital to complete these studies, freezing market entry.
Strategic Opportunities
- Ethiopian outpatient clinic expansion:Addis Ababa's diabetes center network is adding satellite facilities in regional cities. First-mover generic suppliers can anchor distribution before tender systems formalize.
- Repaglinide-metformin FDC development:Fixed-dose combinations streamline adherence for dual-therapy patients. Egyptian and South African regulators have issued guidance favoring these formulations in national procurement.
- WHO prequalification corridor:Nigeria's NAFDAC is harmonizing with WHO standards. Manufacturers holding prequalification status gain accelerated access to West African pooled procurement mechanisms.
Industry Challenges
- Pharmacovigilance infrastructure gaps:National regulators in Sudan and Libya lack adverse event reporting systems. Manufacturers must build proprietary post-market surveillance networks to meet originator-level compliance.
- Multimodal distribution complexity:Last-mile delivery to Saharan clinics requires combining air freight, temperature-controlled trucking, and camel-borne cold boxes. Integrating these channels without breakage or excursion demands capital investment few regional players can deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Meglitinide Market |
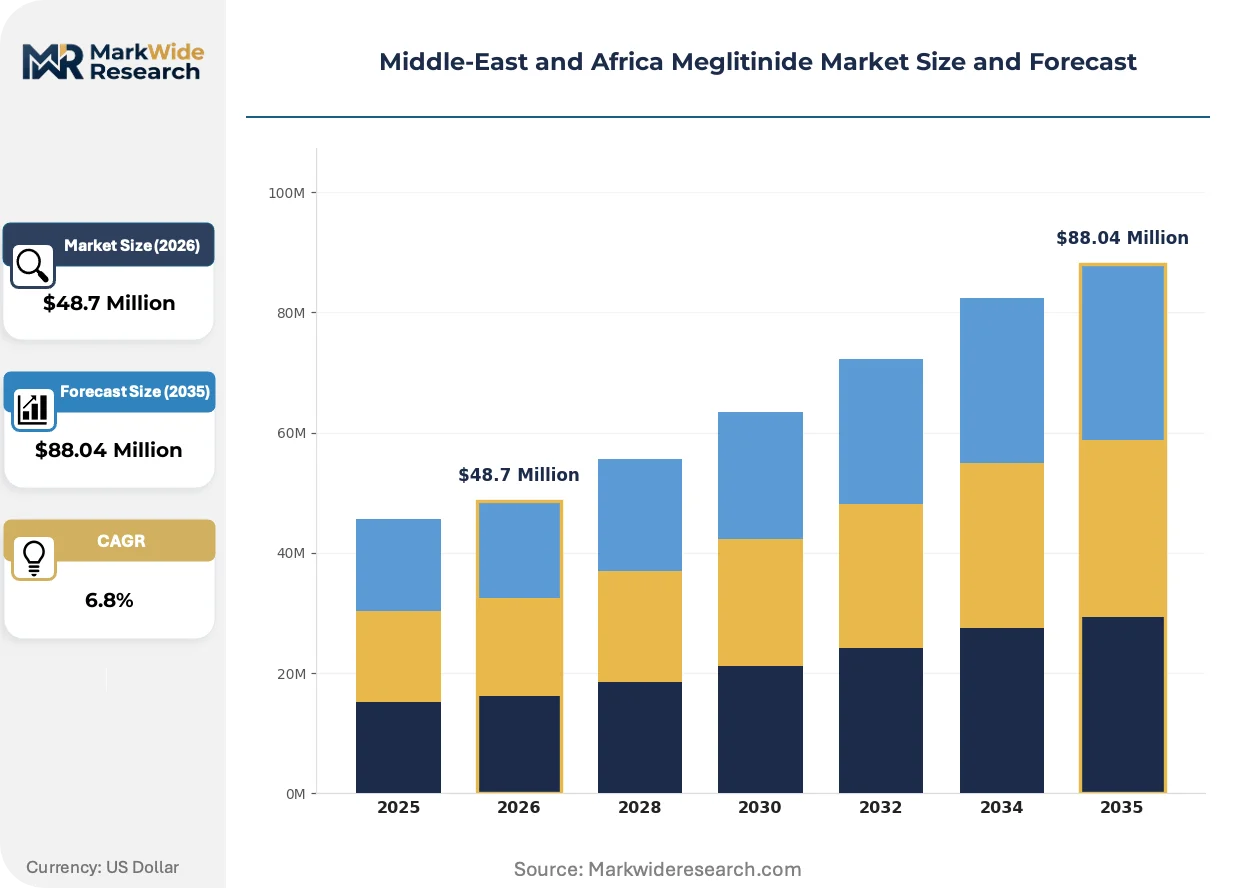
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repaglinide, Nateglinide, Combination Therapies, Generics End User: Hospitals, Outpatient Clinics, Home Care, Pharmacies Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacies, Online Pharmacies Formulation: Tablets, Injectable Solutions, Oral Suspension, Others |
| Companies Covered | Novo Nordisk, Novartis, Glenmark Pharmaceuticals, Kissei Pharmaceutical, Biocon, Sanofi, Eli Lilly and Company, Hikma Pharmaceuticals, AstraZeneca, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Meglitinide Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape how meglitinides reach patients in climates and health systems that originator products were not designed to serve. Three developments are altering competitive requirements.
Modified-release coating technologies are decomposing the traditional tablet-dominant product architecture. Egyptian manufacturers including EIPICO are deploying hydroxypropyl methylcellulose matrices that extend stability beyond 36 months at 30°C/75% RH. Hospital procurement committees in Riyadh and Jeddah are rewriting tender specifications to require these heat-stressed stability profiles, effectively disqualifying imports that lack localized validation data.
SFDA's 2023 bioequivalence guideline revision is forcing parallel reformulation investments across the Gulf. The regulation now requires demonstration of equivalence under fasting and fed conditions specific to regional dietary patterns. Generic sponsors must repeat studies using Middle Eastern meal compositions, adding 8-12 months to approval timelines but creating a regulatory moat against non-compliant imports.
Home care channels are fragmenting demand away from hospital-centric dispensing. Diabetes nurses in Cairo's informal settlements now coordinate direct-to-patient delivery of 30-day repaglinide supplies, bypassing pharmacy markup. This channel shift compresses working capital cycles for manufacturers while requiring new patient-authentication and cold-chain-last-mile capabilities that outpatient clinic networks are only now assembling.
Middle-East and Africa Meglitinide Market Segmentation
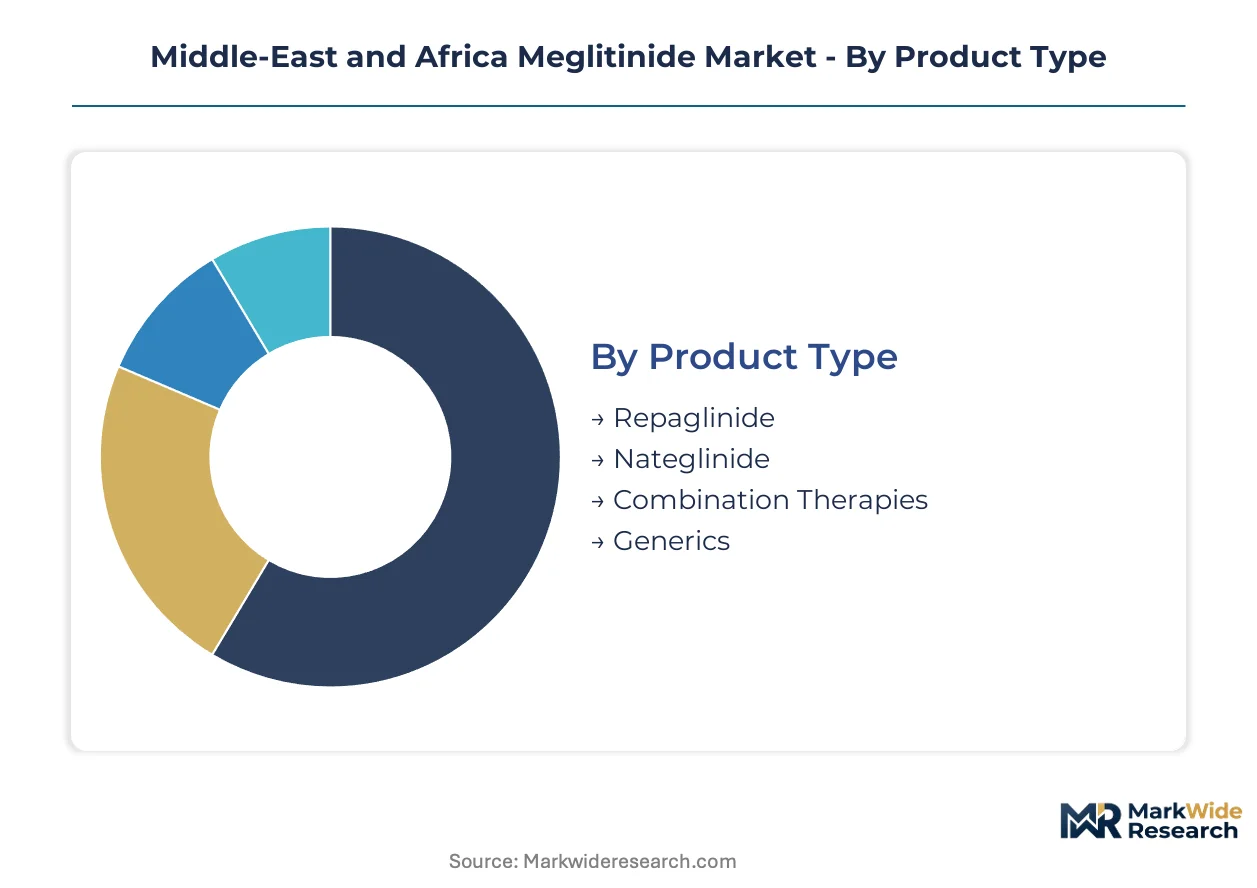
Segmentation in the Middle-East and Africa Meglitinide Market reveals how clinical utility, supply chain resilience, and patient access modalities intersect. Manufacturers must align portfolio investments with the region's hospital-centric procurement systems while capturing emerging outpatient and home care channels.
Product Type:
Margin pools concentrate in formulations that navigate bioequivalence barriers and heat-stability requirements most effectively.
- Repaglinide:The benzamidine-derived insulin secretagogue triggers rapid, short-duration glucose-dependent insulin release. Demand clusters in Egypt's outpatient diabetes centers and Saudi hospital formularies where prandial glucose management protocols are expanding. SFDA's tightened bioequivalence standards favor manufacturers with localized clinical data.
- Generics:Compulsory licensing pressures and national tender systems across Sub-Saharan Africa drive volume concentration. Glenmark Pharmaceuticals and Hikma Pharmaceuticals compete through aggressive pricing and localized manufacturing licenses that reduce import duty exposure in Egypt and Jordan.
- Nateglinide:The D-phenylalanine derivative offers faster onset and shorter duration than repaglinide for patients with highly irregular meal timing. Prescription volumes trail repaglinide across Gulf Cooperation Council markets.
- Combination Therapies:Repaglinide-metformin fixed-dose combinations streamline adherence for dual-therapy patients. Egyptian and South African regulators have issued procurement guidance favoring these formulations.
Repaglinide holds installed capacity. Combination therapies are rotating up the share rankings.
End User:
Volume distribution tracks the divergence between consolidated hospital procurement and fragmented outpatient access pathways.
- Hospitals:Tender systems across the Gulf Cooperation Council consolidate procurement volumes, forcing margin compression. Novo Nordisk dominates these channels through integrated insulin-to-oral glucose-lowering portfolios.
- Outpatient Clinics:Cairo and Alexandria diabetes clinics drive Egyptian volume for repaglinide formulations. Addis Ababa's expanding satellite facility network offers first-mover anchoring opportunities for generic suppliers.
- Home Care:Direct-to-patient delivery models in Cairo's informal settlements bypass pharmacy markup. Diabetes nurses coordinate 30-day supply distribution, compressing working capital cycles.
- Pharmacies:Retail dispensing remains concentrated in urban centers with cold-chain infrastructure. Last-mile penetration to Saharan clinics requires multimodal distribution combining air freight, temperature-controlled trucking, and camel-borne cold boxes.
Hospitals command procurement scale. Outpatient clinics are climbing the fastest.
Distribution Channel:
Channel economics reflect the trade-off between margin retention and market access breadth across diverse national regulatory environments.
- Wholesalers:Regional distributors manage inventory across SAHPRA-regulated South Africa, SFDA-regulated Saudi Arabia, and EDA-regulated Egypt. Currency volatility in upstream API sourcing from India and China squeezes wholesaler margins.
- Direct Sales:Hospital tender participation requires direct manufacturer engagement with procurement committees in Riyadh, Jeddah, and Dubai. Relationship investments lock in multi-year supply agreements.
- Retail Pharmacies:Urban pharmacy networks in Johannesburg, Lagos, and Casablanca serve insured patient segments with brand preference.
- Online Pharmacies:Digital dispensing platforms are emerging in UAE and South Africa, though regulatory frameworks remain under development.
Wholesalers maintain network density. Direct sales are gaining share fastest.
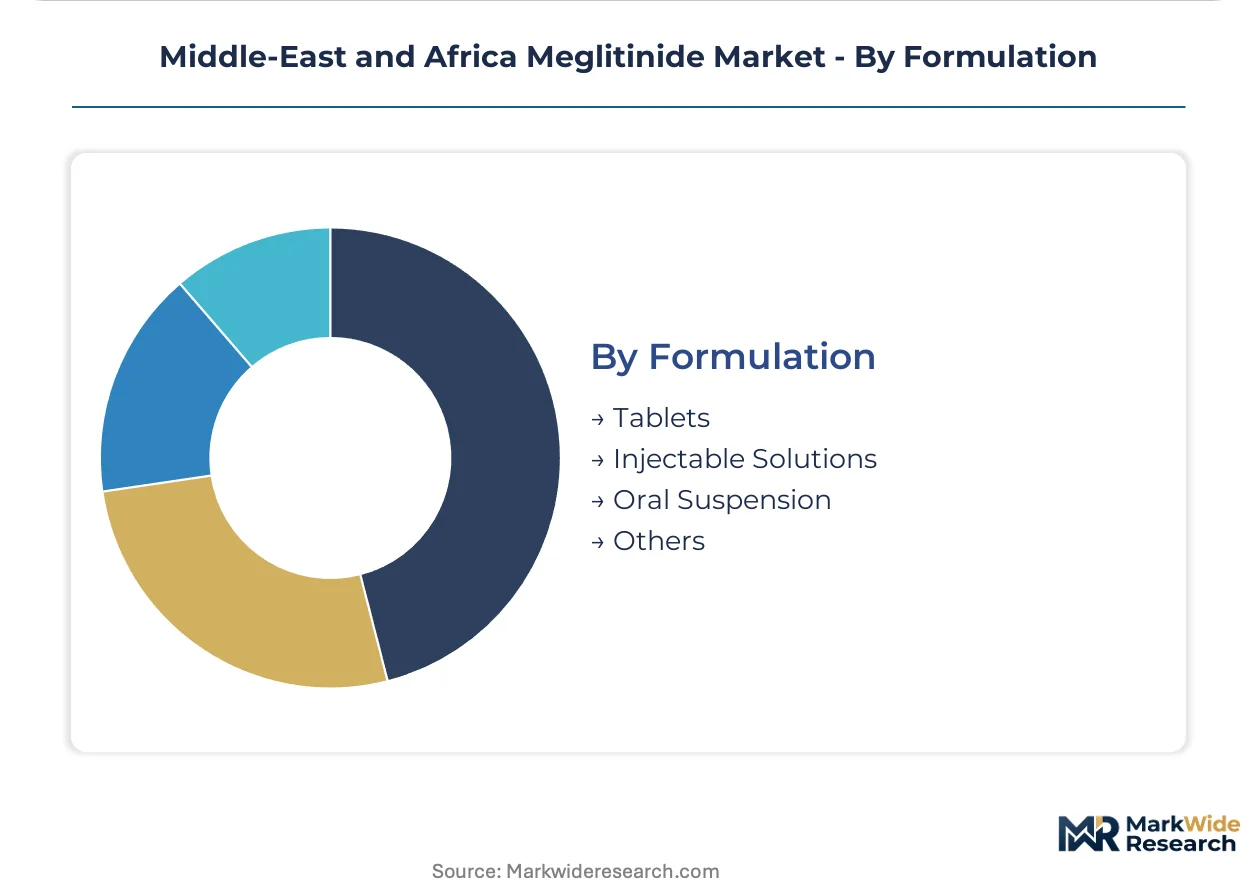
Formulation:
Technology investments cluster around stability validation for heat-stressed supply chains and patient adherence optimization.
- Tablets:Hydroxypropyl methylcellulose matrix coatings from Egyptian manufacturers including EIPICO extend stability beyond 36 months at 30°C/75% RH. Riyadh and Jeddah procurement committees now require these specifications.
- Oral Suspension:Liquid formulations address pediatric and geriatric swallowing difficulties in home care segments. Demand accelerates where tablet adherence fails.
- Injectable Solutions:Parenteral meglitinide delivery remains minimal, limited to hospital-based acute glucose management protocols.
- Others:Modified-release and fixed-dose combination formats represent formulation innovation targets for regional manufacturers.
Tablets dominate installed capacity. Oral suspension shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Saudi Arabia's hospital tender systems diverges sharply from Egypt's outpatient clinic channels, where aggressive generic competition compresses margins. This asymmetry shapes manufacturer portfolio decisions across the Middle-East and Africa Meglitinide Market.
Saudi Arabia
SFDA's tightened bioequivalence requirements for generic meglitinides are elevating prescriber confidence in certified domestic suppliers. Hospital pharmacists in Riyadh and Jeddah increasingly favor locally validated repaglinide formulations. The Eastern Province's pharmaceutical manufacturing cluster is absorbing reformulation investments to meet heat-stability specifications.
Egypt
Outpatient diabetes clinics in Cairo and Alexandria drive volume demand for repaglinide formulations, with EIPICO deploying modified-release coatings for Saharan distribution. The Egyptian Drug Authority's alignment with ICH stability guidelines forces technical upgrades. Local manufacturers are capturing share through direct-to-patient delivery models in informal settlements.
South Africa
SAHPRA's bioequivalence protocols delay generic market entry but strengthen clinical confidence among endocrinologists. Johannesburg's private hospital networks sustain originator prescribing for insured patients. The Western Cape's clinical trial infrastructure supports regional generic sponsors navigating registration requirements.
United Arab Emirates
MOHAP's procurement centralization through Dubai and Abu Dhabi health authorities consolidates tender volumes for hospital formularies. Repaglinide demand concentrates in prandial glucose management protocols for expatriate populations with irregular work schedules. Sharjah's logistics hub enables temperature-controlled distribution across Gulf Cooperation Council markets.
Nigeria
NAFDAC's harmonization with WHO prequalification standards is opening procurement corridors for certified generic suppliers. Lagos and Abuja's tertiary hospitals anchor initial volume before pooled procurement mechanisms activate. The northern region's clinic network remains underserved due to multimodal distribution complexity.
Middle-East and Africa Meglitinide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa Meglitinide Market. Originators with integrated insulin-to-oral portfolios dominate Gulf hospital tenders through relationship-locked multi-year agreements. Regional generic manufacturers compete on localized production licenses and heat-stability formulation capabilities. The competitive terrain rewards three strategic archetypes: multinational portfolio integrators, regional license holders, and generic volume specialists. Dominant competitive moves include reformulation investments for bioequivalence compliance and direct distribution partnerships with outpatient clinic networks.
Among the multinational originators, Novo Nordisk and Novartis occupy positions defined by integrated glucose-lowering portfolios spanning injectable and oral therapies. Glenmark Pharmaceuticals exemplifies the generic volume specialist archetype through aggressive pricing in Sub-Saharan African markets. Hikma Pharmaceuticals represents the regional license holder model with manufacturing positions in Egypt and Jordan that reduce import duty exposure. These three anchors illustrate how competitive positioning fragments across technology-intensive originators, cost-optimized generics, and geographically embedded regional players.
| Leading Market Players |
|---|
| Novo Nordisk |
| Novartis |
| Glenmark Pharmaceuticals |
| Kissei Pharmaceutical |
| Biocon |
| Sanofi |
| Eli Lilly and Company |
| Hikma Pharmaceuticals |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Chinese API substitution for European-sourced meglitinide precursors simultaneously redraws procurement geography toward Indian intermediaries and compresses margin structures for Egyptian and Jordanian formulators bidding into Gulf tender systems.
Pricing Analysis
The customization-premium spread separates originator repaglinide formulations from certified generic equivalents across Saudi hospital formularies. Pricing stratifies across premium, standard, and economy tiers based on bioequivalence certification status and heat-stability validation. Cost compression in the standard tier intensifies because SAHPRA and SFDA mandate local clinical trials that small-scale manufacturers cannot fund. Public tender participants in Nigeria and Kenya exhibit highest price sensitivity, while insured segments in Johannesburg and Dubai private hospitals show lowest.
Supply Chain Analysis
Inbound logistics costs through Jeddah Islamic Port congestion and Red Sea container availability constraints elevate working capital requirements for API shipments from India and China. Active pharmaceutical ingredient supply concentrates in China and India, with formulation finishing in Egypt and Jordan. Raw material dependencies include repaglinide base compound, nateglinide D-phenylalanine derivative, and hydroxypropyl methylcellulose coating matrices. Single-source vulnerability from concentrated Chinese API manufacturing exposes margins to geopolitical friction. Distribution runs through regional wholesalers managing SAHPRA, SFDA, and EDA regulatory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capability for heat-stable meglitinide formulations runs ahead of clinical trial infrastructure, creating a bottleneck where sponsors with validated bioequivalence data capture disproportionate share in tightening regulatory environments.
For Market Incumbents: Compound defensive positioning through backward integration into API sourcing and exclusive distribution partnerships with Cairo's outpatient clinic networks. Novo Nordisk's integrated insulin-to-oral portfolio demonstrates how formulary lock-in resists glimepiride substitution economics. Capacity addition in Egypt's Eastern Province manufacturing cluster reduces import duty exposure against Gulf localization mandates. For New Entrants and Emerging Players: Differentiate on heat-stability formulation science for Saharan distribution corridors underserved by cold-chain-dependent alternatives. Ethiopia's satellite clinic expansion in Addis Ababa offers the most penetrable geography before tender systems formalize. Direct-to-patient delivery partnerships with diabetes nurses in informal settlements provide a go-to-market angle bypassing pharmacy markup compression. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors manufacturers with completed bioequivalence studies and localized validation data. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than pure cost position. Acquisition targets should display SFDA or SAHPRA approval dossiers. The signal to watch is NAFDAC's full harmonization with WHO prequalification standards activating West African pooled procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Bioequivalence Study Completion | SFDA and SAHPRA mandates now require local clinical trials using regional meal compositions. |
| Heat-Stability Formulation Investment | EIPICO's hydroxypropyl methylcellulose matrices extend stability beyond 36 months at 30°C/75% RH. |
| Direct-to-Patient Distribution Partnership | Cairo's diabetes nurses coordinate 30-day repaglinide supply delivery bypassing pharmacy channels. |
| API Sourcing Backward Integration | Regional formulators reduce Chinese and Indian supplier concentration risk and currency volatility exposure. |
| WHO Prequalification Pursuit | NAFDAC harmonization opens accelerated access to West African pooled procurement mechanisms. |
Research Methodology
A spread of perspectives from formulary directors at Saudi tertiary hospitals, regulatory affairs leads navigating SFDA bioequivalence guidelines, Egyptian outpatient clinic procurement managers, and API sourcing specialists at Indian manufacturers converged on the working assumptions. Primary interview insights combined with secondary validation from SFDA regulatory filings, EDA stability guideline documentation, SAHPRA registration databases, and hospital tender records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated on segment-level estimates.
Segmentation dimensions modeled include product type, end user channel, distribution pathway, and formulation technology across the analysis window. CAGRs derived from regression analysis of historical prescription trends and forward projection of regulatory approval timelines. Industry-specific forecast inputs incorporated bioequivalence study completion rates and heat-stability validation success frequencies for regional manufacturers.
The analysis sits within stated boundaries; outcomes outside sustained regulatory alignment between Gulf Cooperation Council authorities and ICH stability guidelines would require recalibration. Forecasts reflect assumptions regarding continued API import dependency and tender system consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market