
 Vertebrobasilar Insufficiency Treatment Market | 2026-2036
Vertebrobasilar Insufficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vertebrobasilar Insufficiency Treatment Market Analytics
Neurovascular device manufacturing in Ireland is realigning toward catheter-based delivery systems for posterior circulation interventions. Abbott Laboratories leverages its endovascular portfolio to sustain leadership in stent-retriever technology for acute basilar artery occlusion. Bayer AG anchors its position through anticoagulant R&D intensity targeting secondary stroke prevention protocols.
Vertebrobasilar insufficiency treatment encompasses pharmacological, interventional, and diagnostic modalities addressing hemodynamic compromise of the posterior cerebral circulation, typically involving stenosis or occlusion of the vertebral and basilar arteries with peak systolic velocity thresholds exceeding 140 cm/s on transcranial Doppler. The primary purpose centers on preventing posterior circulation stroke and managing transient ischemic symptoms through revascularization or medical optimization. Medications dominate current revenue as antiplatelet and anticoagulant protocols form first-line management, while surgical procedures command premium pricing due to specialized neurointerventionalist requirements and device costs. Diagnostic tools represent the fastest-expanding segment as computed tomography angiography and magnetic resonance angiography replace conventional angiography for initial assessment across hospital systems.
FDA neurovascular device regulations and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for stent and thrombectomy systems seeking market access. The European Medicines Agency coordinates centralized marketing authorization for novel antithrombotic therapies used in secondary prevention, directly influencing prescribing patterns across member states. Stakeholders must monitor evolving reimbursement thresholds for mechanical thrombectomy in posterior circulation strokes as health technology assessments in major markets redefine intervention criteria.
Market Dynamics
Catheter-based mechanical thrombectomy is rewriting clinical workflows for posterior circulation stroke, compressing the window for intervention and elevating neurointerventionalist training requirements across tertiary care networks.
Growth Catalysts
- EU MDR streamlining:The Medical Device Regulation's centralized conformity assessment for Class III neurovascular implants accelerates market entry for novel stent-retriever systems across member states.
- Stroke center certification:Joint Commission accreditation requirements in the United States mandate 24/7 neurointerventional coverage, institutionalizing demand for posterior circulation intervention capacity.
- Computed tomography perfusion:This imaging modality enables rapid penumbra assessment in emergency departments, expanding eligible patient pools for revascularization beyond traditional time windows.
Market Restraints
- Platinum-iridium alloy costs:Raw material price volatility for thrombectomy device construction compresses gross margins for manufacturers dependent on imported precious metals.
- Neurointerventionalist scarcity:Fellowship training bottlenecks in Germany, France, and the United States limit procedure volume growth regardless of device availability.
- Conventional angiography substitution:Non-invasive CTA and MRA protocols displace diagnostic catheterization, eroding the traditional entry point for interventional conversion.
Strategic Opportunities
- Mobile stroke units:Prehospital CT-equipped ambulance fleets in the Netherlands and Germany enable field diagnosis and direct routing to thrombectomy-capable centers, bypassing spoke hospitals.
- Artificial intelligence triage:FDA-cleared algorithms for large vessel occlusion detection on non-contrast CT are compressing door-to-needle intervals and expanding treatment eligibility.
- India's tertiary expansion:Greenfield hospital construction in Mumbai, Delhi, and Bangalore incorporates hybrid angiography suites as standard infrastructure, creating first-mover positioning for device suppliers.
Industry Challenges
- Credentialing complexity:Hospital privileging requirements for mechanical thrombectomy vary by state medical boards in the United States, creating inconsistent access patterns.
- Reimbursement lag:DRG coding for posterior circulation stroke interventions remains imprecise in multiple European health systems, delaying adequate compensation for high-acuity procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertebrobasilar Insufficiency Treatment Market |
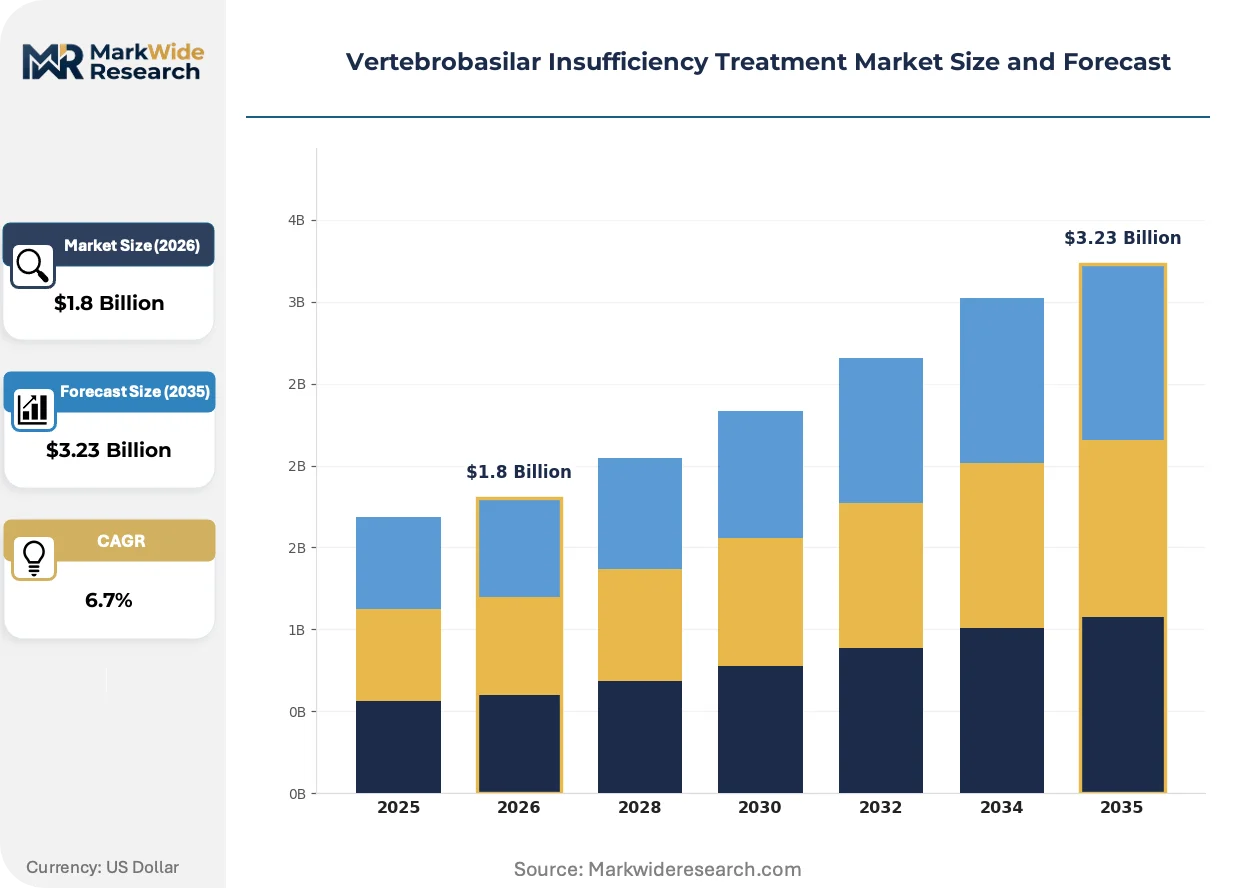
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Procedures, Diagnostic Tools, Assistive Devices Delivery Mode: Intravenous, Oral, Topical, Intra-arterial End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Solution: Pharmacological Therapy, Surgical Interventions, Imaging Solutions, Rehabilitation Strategies |
| Companies Covered | Abbott Laboratories, Merck & Co., Inc., Novartis AG, Pfizer Inc., Johnson & Johnson Services, Inc., Boehringer Ingelheim International GmbH, AstraZeneca, Bayer AG, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertebrobasilar Insufficiency Treatment Market Evolving Landscape
Digital twin modeling of cerebral hemodynamics and polymer science advances in catheter construction are converging to enable patient-specific intervention planning. These developments compress procedural variability and elevate technical success benchmarks.
Distal access catheter technology is rewriting the anatomical reach of endovascular intervention. Devices capable of navigating tortuous vertebral artery geometry now reach basilar apex occlusions previously requiring open surgical approaches. Academic medical centers in Switzerland and the United States are adopting these platforms for routine posterior circulation access, compressing the role of craniotomy in acute stroke management.
EMA's centralized marketing authorization for novel antithrombotic therapies is compressing time-to-market for secondary prevention protocols across European member states. The agency's accelerated assessment pathway for medicines addressing unmet medical need is prioritizing direct oral anticoagulant submissions. Hospital formularies in France and Italy are responding with rapid therapeutic substitution policies, displacing legacy vitamin K antagonist protocols.
Integrated care networks are consolidating stroke referral patterns around comprehensive centers with 24/7 thrombectomy capability. Community hospitals in Bavaria and North Rhine-Westphalia are exiting acute intervention services, redirecting patients to university-affiliated hubs. This geographic rationalization concentrates procedure volumes and device procurement decisions within narrower institutional frameworks, elevating the strategic importance of GPO contracting relationships.
Vertebrobasilar Insufficiency Treatment Market Segmentation
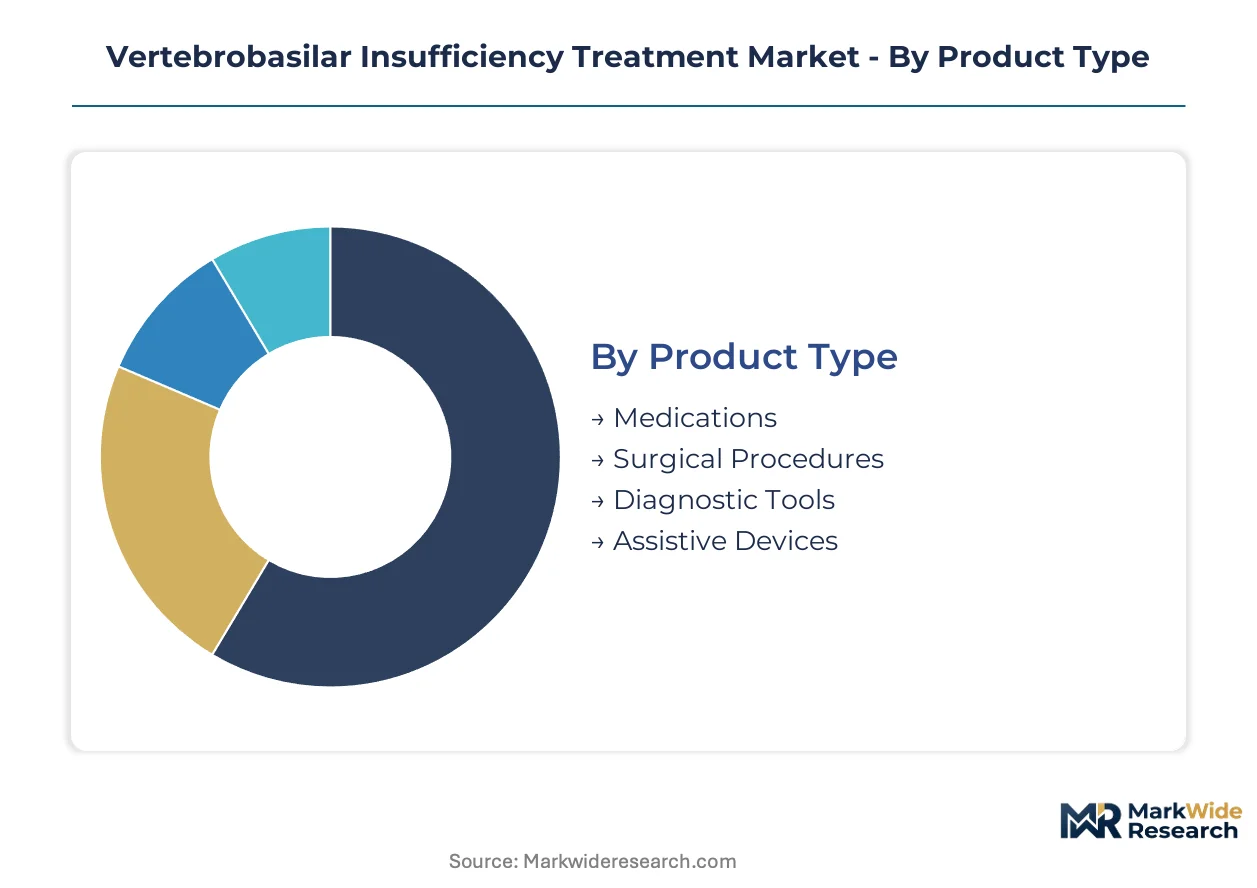
Segmentation in vertebrobasilar insufficiency treatment reveals distinct procurement patterns across acute intervention versus chronic management pathways. Standalone surgical and diagnostic systems command capital-intensive purchasing cycles, while pharmacological segments integrate into recurring hospital formularies and outpatient protocols.
Product Type:
Integration depth varies sharply: medications and diagnostic tools embed into continuous care workflows, whereas surgical procedures and assistive devices operate as episodic, standalone interventions.
- Medications:Antiplatelet agents, anticoagulants, and statin protocols constitute the revenue foundation through chronic administration regimens. German cerebrovascular clinics and US stroke centers drive volume through standardized secondary prevention pathways mandated by Joint Commission and EMA guidelines.
- Surgical Procedures:Mechanical thrombectomy, angioplasty, and stenting require dedicated neurointerventional infrastructure and disposable device ecosystems. Abbott Laboratories and specialized catheter manufacturers capture value through procedure-linked consumable models rather than capital equipment sales.
- Diagnostic Tools:Transcranial Doppler, CTA, and MRA systems enable hemodynamic assessment and treatment eligibility determination.
- Assistive Devices:Mobility aids and monitoring equipment support post-stroke rehabilitation and long-term functional recovery.
Medications lead volumes today; diagnostic tools are gaining share fastest through non-invasive imaging substitution.
Delivery Mode:
Cost tier stratification separates acute intervention delivery from maintenance protocols, with intra-arterial and intravenous approaches commanding premium reimbursement versus oral chronic therapy.
- Intravenous:Thrombolytic administration in emergency departments requires precise timing infrastructure and specialized nursing protocols. Mobile stroke units in the Netherlands and Germany are expanding IV-tPA delivery into prehospital settings.
- Intra-arterial:Catheter-based drug delivery directly to occluded posterior circulation vessels enables localized therapeutic concentration. Swiss and US academic medical centers are standardizing this approach for basilar artery interventions previously deemed surgically inaccessible.
- Oral:Chronic antithrombotic and lipid-lowering regimens dominate prescription volume through primary care and neurology outpatient channels.
- Topical:Limited application in transdermal neurological symptom management and adjunctive therapy delivery.
Oral delivery leads volumes today; intra-arterial routes are climbing the fastest through thrombectomy protocol expansion.
End User:
Customer type concentration centers on tertiary hospitals with comprehensive stroke certification, while outpatient and home segments capture post-acute care migration.
- Hospitals:Comprehensive stroke centers with 24/7 neurointerventional coverage concentrate procedure volume and device procurement authority. Bavarian university hospitals and North Rhine-Westphalia hubs are consolidating regional referral patterns.
- Outpatient Clinics:Neurology practices and dedicated cerebrovascular clinics manage chronic antithrombotic therapy and surveillance imaging.
- Rehabilitation Centers:Post-acute facilities address functional recovery following posterior circulation stroke events.
- Home Care:Remote monitoring and medication adherence support extend chronic management beyond institutional settings.
Hospitals lead volumes today; outpatient clinics are expanding most quickly through diagnostic imaging decentralization.
Solution:
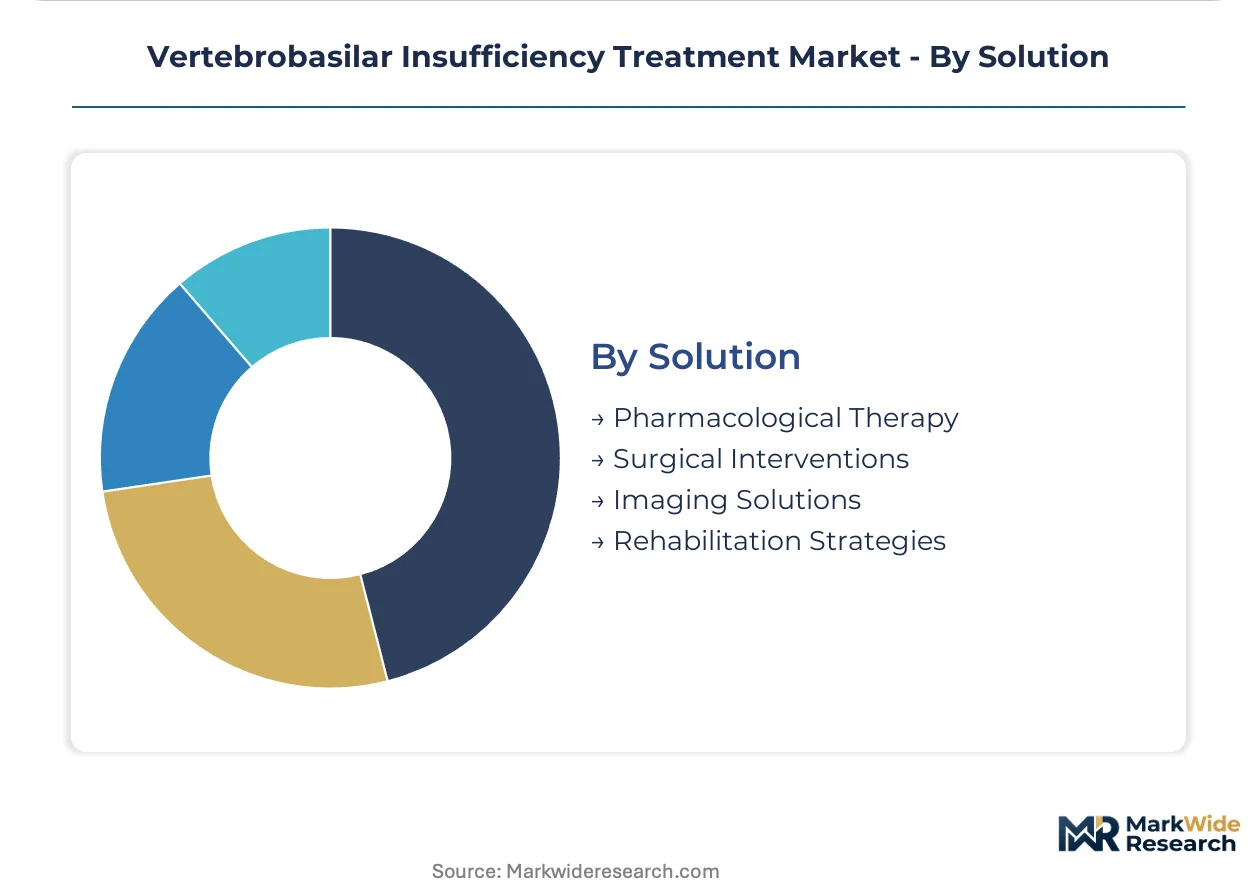
Maturity differentiation separates established pharmacological protocols from emerging imaging and interventional technologies in commercialization trajectory.
- Pharmacological Therapy:Antiplatelet, anticoagulant, and neuroprotective drug protocols form the evidence-based foundation of secondary stroke prevention. Bayer AG's R&D intensity targets direct oral anticoagulant substitution of legacy vitamin K antagonist regimens.
- Surgical Interventions:Endovascular revascularization techniques are displacing craniotomy for posterior circulation occlusion through distal access catheter advances.
- Imaging Solutions:CTA and MRA protocols replace conventional angiography for initial assessment, compressing door-to-treatment intervals.
- Rehabilitation Strategies:Multidisciplinary recovery protocols address cognitive, motor, and functional deficits following vertebrobasilar events.
Pharmacological therapy leads volumes today; imaging solutions are on the steepest expansion trajectory through AI-augmented triage adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cerebrovascular clinic density around university hospitals contrasts with India's emerging hybrid angiography infrastructure in metropolitan hospital construction. Stroke center certification requirements and neurointerventional training capacity diverge sharply between established European networks and expanding Asian tertiary care systems.
United States
Joint Commission stroke center accreditation mandates 24/7 neurointerventional coverage, institutionalizing demand for posterior circulation intervention capacity across tertiary networks. FDA neurovascular device regulations streamline clearance pathways for stent-retriever systems seeking market access. Comprehensive stroke centers in the Southeast and Pacific Northwest concentrate regional referral patterns and device procurement authority.
Germany
Specialized cerebrovascular clinics cluster around university hospitals in Bavaria and North Rhine-Westphalia, driving concentrated demand for mechanical thrombectomy procedures. EU Medical Device Regulation centralized conformity assessment accelerates market entry for Class III neurovascular implants across member states. Mobile stroke units equipped with CT scanners operate in prehospital settings, enabling field diagnosis and direct routing to thrombectomy-capable centers.
Switzerland
Academic medical centers standardize distal access catheter platforms for basilar apex interventions previously requiring open surgical approaches. Swissmedic coordinates marketing authorization for novel antithrombotic therapies used in secondary stroke prevention protocols. Zurich and Geneva hospital networks consolidate procedure volumes within narrower institutional frameworks, elevating GPO contracting importance.
India
Greenfield hospital construction in Mumbai, Delhi, and Bangalore incorporates hybrid angiography suites as standard infrastructure, creating first-mover positioning for device suppliers. CDSCO regulatory pathways shape product development timelines for stent and thrombectomy systems seeking market access. Tertiary expansion concentrates neurointerventional capacity in metropolitan corridors while fellowship training bottlenecks limit specialist availability.
Netherlands
Prehospital CT-equipped ambulance fleets enable field diagnosis and direct routing to thrombectomy-capable centers, bypassing spoke hospitals entirely. EMA centralized marketing authorization for direct oral anticoagulants prioritizes submissions addressing unmet medical need. Amsterdam and Rotterdam integrated care networks consolidate stroke referral patterns around comprehensive centers with continuous intervention capability.
Vertebrobasilar Insufficiency Treatment Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in antithrombotic therapy development. The market structure concentrates around diversified pharmaceutical conglomerates with endovascular device portfolios and dedicated neurovascular technology developers. Three archetypes dominate: diversified healthcare conglomerates with stroke care franchises, specialized interventional device manufacturers, and research-intensive pharmaceutical developers. Competitive dynamics center on portfolio diversification into catheter-based delivery systems and strategic partnerships for AI-augmented triage technologies.
Within the diversified healthcare tier, Abbott Laboratories and Johnson & Johnson Services, Inc. exemplify integrated endovascular positioning. Among pharmaceutical developers, Bayer AG and Boehringer Ingelheim International GmbH occupy positions anchored in anticoagulant research intensity. These entities represent contrasting strategic postures: device-centric conglomerates leverage procedure-linked consumable models while pharmaceutical specialists target chronic administration regimens through direct oral anticoagulant substitution of legacy protocols.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Merck & Co., Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Boehringer Ingelheim International GmbH |
| AstraZeneca |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Device-certification tier divergence between FDA-cleared Class III neurovascular implants and CE-marked equivalents manifests in premium pricing for US-market stent-retrievers and concentrated supply chain control by Irish catheter manufacturing hubs serving Abbott Laboratories. This bifurcation compresses margins for second-tier manufacturers while elevating procurement leverage among German university hospital networks with dedicated cerebrovascular clinics.
Pricing Analysis
Distributor margins on mechanical thrombectomy devices absorb 15-25 percent of landed cost before hospital GPO contracting. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough designation status and distal access catheter performance specifications. Pricing pressure stems from platinum-iridium alloy cost volatility and Indian greenfield hospital procurement standardization. Academic medical centers in Switzerland and the United States exhibit lowest price sensitivity due to bundled reimbursement protocols; community hospitals in Bavaria face highest sensitivity from DRG coding imprecision.
Supply Chain Analysis
Freight costs for temperature-sensitive catheter shipments from Ireland to German stroke centers run through specialized cold-chain logistics providers with EU MDR documentation requirements. Manufacturing concentrates in Ireland, Switzerland, and the United States for Class III device final assembly; raw material sourcing draws from South African platinum mines, Japanese nitinol suppliers, and German precision polymer producers. Single-source vulnerability sits with iridium refining capacity concentrated in South Africa. Distribution runs through hospital GPOs in North America and direct tender processes in European member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through aging demographics and stroke center certification mandates that institutionalize intervention demand regardless of economic cycles.
For Market Incumbents: Deepen catheter-based delivery system R&D intensity to defend against distal access platform substitution by specialized entrants. Anchor procurement relationships through exclusive GPO contracting with Bavarian and North Rhine-Westphalia university hospital networks. Prioritize backward integration into nitinol wire production to offset Japanese supplier concentration risk. For New Entrants and Emerging Players: AI-augmented triage algorithms for large vessel occlusion detection offer a technology-first wedge against established imaging incumbents. Target India's metropolitan greenfield hospital construction in Mumbai and Bangalore where hybrid angiography suite standardization creates first-mover positioning without entrenched supplier relationships. Pursue CDSCO regulatory pathway acceleration through local clinical trial partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where fellowship training bottlenecks limit neurointerventionalist supply regardless of device innovation pace. Position for 5-10 year holding periods anchored by irreversible stroke center infrastructure buildout. Target mid-cap catheter manufacturers with distal access platform FDA submissions pending. Watch EMA accelerated assessment pathway designations for direct oral anticoagulants as inflection signal for therapeutic substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Abbott Laboratories leverages this status to compress review timelines for basilar artery stent-retrievers. |
| CE Marking Under EU MDR | Centralized conformity assessment accelerates Class III neurovascular implant market entry across German member states. |
| Hospital System Partnership | Exclusive GPO contracting with Bavarian university hospitals concentrates procurement authority and locks out competitors. |
| Software Companion Development | AI-augmented large vessel occlusion detection on non-contrast CT compresses door-to-needle intervals for thrombectomy eligibility. |
| Reimbursement Strategy | DRG coding precision for posterior circulation stroke interventions determines adequate compensation in European health systems. |
Research Methodology
Bottom-up stroke center capacity modeling reconciled against top-down neurovascular device shipment tracking forms the analytical core of this study. Primary interviews with neurointerventionalists, hospital purchasing committee chairs, GPO contracts managers, and EMA regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, EMA centralized marketing authorization databases, hospital procurement records, and stroke center certification registries. Triangulation between demand-side procedure volume estimates and supply-side manufacturer capacity data ensures cross-verified output integrity.
Input-output matrices map catheter-based intervention volumes against antiplatelet prescription trends across product type, delivery mode, end user, and solution segmentation dimensions. CAGRs derive from logistic diffusion curves fitted to stroke center certification saturation rates and neurointerventionalist fellowship completion trajectories. Forecast inputs incorporate EU MDR implementation pace, Joint Commission accreditation expansion timelines, and platinum-group metal price elasticity coefficients for device manufacturing cost structures across the analysis window.
The model holds under stable regulatory reimbursement environments; deviation in DRG coding revisions or neurointerventionalist training pipeline expansion would shift volume concentration assumptions. Forecasts reflect documented assumptions regarding stroke center referral pattern consolidation and antithrombotic therapeutic substitution velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
United Kingdom Neurology Devices Market
Neurology
Cognitive Neuroscience Market
Neurology
Global Vertigo Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Chronic Brain Damage Management Market
Neurology
Movement Disorder Market
Neurology
South America Neurology Monitoring Market
Neurology
Canada Neurology Devices Market
Neurology
Moyamoya Disease Market
Neurology
Chile Neurology Devices Market
Neurology
Transverse Myelitis Treatment Market
Neurology
CNS Lymphoma Market
Neurology
Labyrinthitis Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Europe Neurology Monitoring Market