
 Middle East and Africa Remote Patient Monitoring Market | 2026-2036
Middle East and Africa Remote Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Remote Patient Monitoring Market Foresight
Hospital-at-home programs are decoupling from traditional inpatient models across the Middle East and Africa, creating dedicated procurement channels for remote monitoring infrastructure. Philips Healthcare leverages its installed base of acute-care devices to extend into home-based telemetry services across Gulf state health systems. Medtronic anchors its regional position through cardiac implantable electronic devices with embedded remote monitoring capabilities. Abbott Laboratories differentiates via glucose monitoring platforms that integrate with clinician dashboards in South African diabetes networks.
Remote patient monitoring encompasses the collection, transmission, and analysis of physiological data from patients outside conventional clinical settings through networked sensors, wearable biosensors, and cloud-connected diagnostic peripherals. These systems typically employ Bluetooth Low Energy for local device pairing, cellular modems for continuous data backhaul, and encrypted cloud architectures enabling real-time clinician alerts when vital signs breach programmed thresholds. Wearable devices and home monitoring systems occupy the dominant product positions, with chronic disease management applications generating the deepest margin pools due to recurring reimbursement structures and long patient engagement cycles. Telehealth solutions represent the fastest-expanding segment as video consultation platforms integrate natively with biometric data streams, collapsing the distance between diagnostic capture and clinical intervention.
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and the UAE's MOHAP collectively shape device registration, data localization requirements, and cross-border telehealth licensing across the region. SFDA's software-as-medical-device framework and MOHAP's digital health accelerators are compressing regulatory timelines for connected monitoring platforms entering Gulf markets. Stakeholders must track evolving data sovereignty mandates and interoperability standards as health information exchanges proliferate from Nairobi to Riyadh.
Market Dynamics
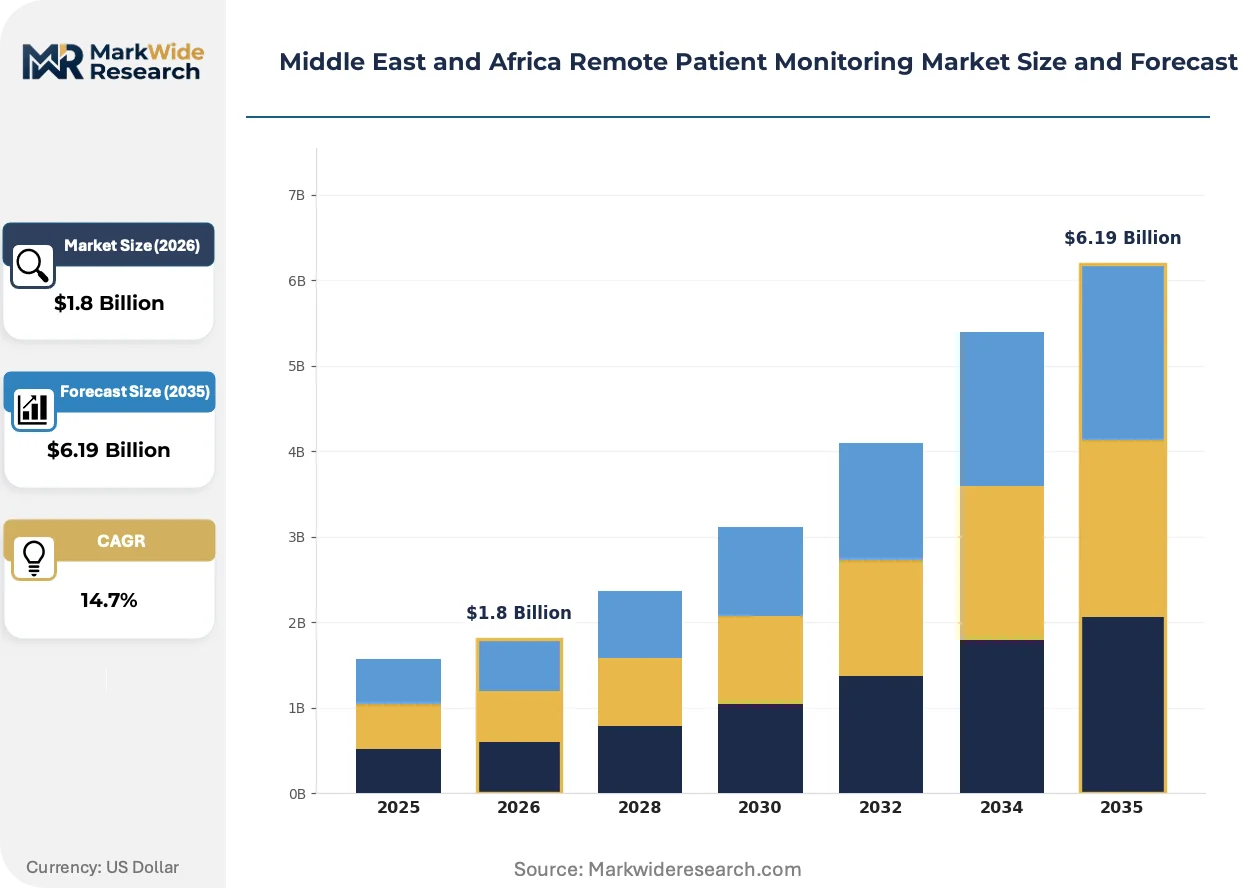
Government-backed telehealth infrastructure investments across Gulf Cooperation Council states are compressing procurement cycles for connected monitoring platforms while aging demographics concentrate demand for chronic disease telemetry services.
Growth Catalysts
- SFDA Software-as-Medical-Device Framework:Saudi Arabia's streamlined registration pathways reduce time-to-market for digital health vendors deploying remote monitoring applications across hospital networks.
- Hospital-at-Home Program Expansion:Decoupling from traditional inpatient models creates dedicated procurement channels for wearable biosensors and cloud-connected diagnostic peripherals in acute-care extension settings.
- Cellular Modem Penetration:Continuous data backhaul capabilities enable real-time clinician alerts when vital signs breach programmed thresholds, supporting cardiac and diabetes management protocols.
Market Restraints
- Data Localization Mandates:Cross-border telehealth licensing restrictions and evolving data sovereignty requirements create compliance friction for vendors operating across multiple Middle East and Africa jurisdictions.
- Bluetooth Low Energy Interoperability Gaps:Fragmented device pairing standards between wearable biosensors and clinician dashboards limit seamless integration in multi-vendor hospital deployments.
- Reimbursement Structure Misalignment:Recurring chronic disease management reimbursement pools concentrate in Gulf states while sub-Saharan African markets lack comparable payment mechanisms for remote monitoring services.
Strategic Opportunities
- MOHAP Digital Health Accelerators:UAE Ministry of Health and Prevention initiatives compress regulatory timelines for connected monitoring platforms entering Dubai and Abu Dhabi health systems.
- Video-Telemetry Convergence:Telehealth solutions integrating native biometric data streams with video consultation platforms collapse diagnostic capture-to-intervention latency in home-based care models.
- Kenya Health Information Exchange Buildout:Interoperability standards proliferation from Nairobi creates first-mover positioning for vendors establishing cloud architecture footholds in East African markets.
Industry Challenges
- Encrypted Cloud Architecture Talent Scarcity:Shortage of cybersecurity specialists familiar with healthcare-grade encryption standards for real-time physiological data transmission delays platform deployments.
- Multi-Regulator Certification Complexity:Simultaneous navigation of South Africa's Health Products Regulatory Authority, Saudi SFDA, and UAE MOHAP requirements extends product launch timelines for regional rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Remote Patient Monitoring Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Home Monitoring Systems, Imaging Devices, Telehealth Solutions End User: Healthcare Providers, Patients, Caregivers, Clinics Technology: Bluetooth, Wi-Fi, Cellular, Cloud Computing Application: Chronic Disease Management, Post-operative Care, Mental Health Monitoring, Vital Sign Tracking |
| Companies Covered | Philips Healthcare, Medtronic, Boston Scientific Corporation, GE Healthcare, BIOTRONIK, Honeywell International, Abbott Laboratories, OMRON Corporation, Nihon Kohden Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Remote Patient Monitoring Market Shifts & Advancements
Telehealth infrastructure is absorbing artificial intelligence diagnostic layers while wearable form factors compress toward clinical-grade accuracy, reshaping competitive requirements for remote monitoring vendors across Middle East and Africa health systems.
Continuous glucose monitoring platforms with embedded cellular modems are absorbing predictive algorithm capabilities that flag hypoglycemic events before symptomatic onset. Endocrinology networks in South African diabetes management programs are deploying these systems at scale. The technology is absorbing functions previously requiring dedicated telemetry nurses, compressing staffing requirements for remote patient oversight.
SFDA's software-as-medical-device registration framework is mandating clinical validation datasets for algorithm-driven diagnostic alerts. This regulatory evolution elevates barriers for non-validated monitoring applications. Cardiac implantable electronic device manufacturers with embedded remote monitoring capabilities are most affected, accelerating investment in prospective outcome studies for Gulf market entry.
Hospital procurement committees are consolidating vendor selection around integrated platform ecosystems rather than standalone device purchases. Specialist telehealth service providers are displacing fragmented equipment-only suppliers in Gulf state health system tenders. This concentration is most visible in Saudi Arabia's Ministry of Health hospital-at-home program expansions, where single-source platform contracts now dominate infrastructure awards.
Middle East and Africa Remote Patient Monitoring Market Segmentation
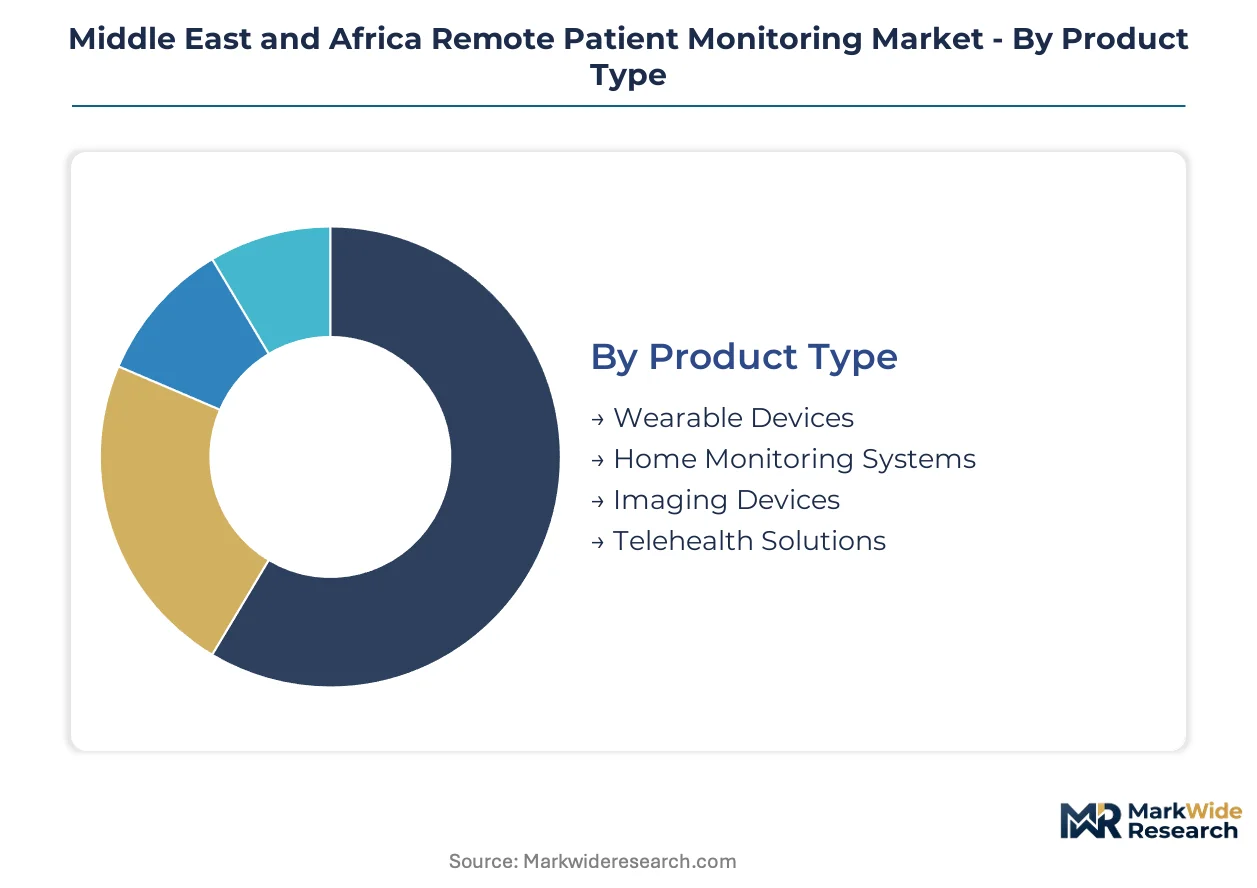
Segmentation in Middle East and Africa remote patient monitoring reveals where procurement budgets concentrate and which technology configurations match specific care delivery models. Hospital-at-home programs and chronic disease networks drive divergent product requirements across the region.
Product Type:
Standardization dominates wearable biosensors while home monitoring systems demand customization for specific disease protocols and clinician dashboard integrations.
- Wearable Devices:Bluetooth Low Energy-enabled biosensors capture continuous physiological parameters through wrist-worn or patch-based form factors. Demand concentrates in Saudi Arabia's Ministry of Health hospital-at-home expansions, where cardiac and diabetes management protocols require real-time telemetry without patient intervention.
- Home Monitoring Systems:Cloud-connected diagnostic peripherals integrate multiple vital sign capture modalities into single-platform deployments for chronic disease oversight. South African diabetes networks and UAE endocrinology clinics prioritize these systems for their embedded cellular modems enabling direct clinician alerts.
- Imaging Devices:Portable ultrasound and dermatology cameras with encrypted transmission capabilities serve remote consultation workflows.
- Telehealth Solutions:Video consultation platforms with native biometric data stream integration collapse diagnostic capture-to-intervention latency.
Most installed capacity flows through Wearable Devices. Expansion is steepest in Telehealth Solutions.
End User:
Volume concentrates with institutional purchasers while margin pools deepen through direct-to-patient subscription models.
- Healthcare Providers:Hospital networks and integrated health systems procure enterprise-scale monitoring platforms with multi-patient clinician dashboards. Gulf Cooperation Council government-backed telehealth infrastructure investments compress procurement cycles for these buyers.
- Patients:Direct-accelerating glucose monitoring and cardiac telemetry subscriptions bypass institutional procurement in South African private diabetes management programs.
- Caregivers:Family members purchasing remote oversight tools for aging relatives represent an emerging payment channel in UAE and Saudi aging demographic concentrations.
- Clinics:Specialist outpatient facilities deploy condition-specific monitoring bundles for post-operative and chronic disease cohorts.
Procurement volume clusters with Healthcare Providers. Margin expansion tracks fastest in direct-to-Patient channels.
Technology:
Maturity gradients separate established local pairing protocols from emerging continuous backhaul architectures.
- Cellular:Embedded modems enable uninterrupted data transmission from patient homes to cloud architectures without Wi-Fi dependency. SFDA software-as-medical-device registration pathways specifically validate these configurations for cardiac implantable electronic device remote monitoring.
- Bluetooth:Low Energy pairing standards dominate wearable-to-smartphone local connectivity, though fragmented interoperability between vendor ecosystems creates integration friction in multi-device hospital deployments.
- Wi-Fi:Home monitoring systems leverage existing residential broadband for stationary diagnostic peripheral connectivity.
- Cloud Computing:Encrypted architectures with healthcare-grade security standards enable real-time clinician alert generation and longitudinal patient data analytics.
Deployment density peaks with Bluetooth-enabled configurations. Infrastructure investment is climbing fastest for Cellular backhaul capabilities.
Application:
Recurring reimbursement structures align with chronic conditions while acute episode monitoring follows episodic payment models.
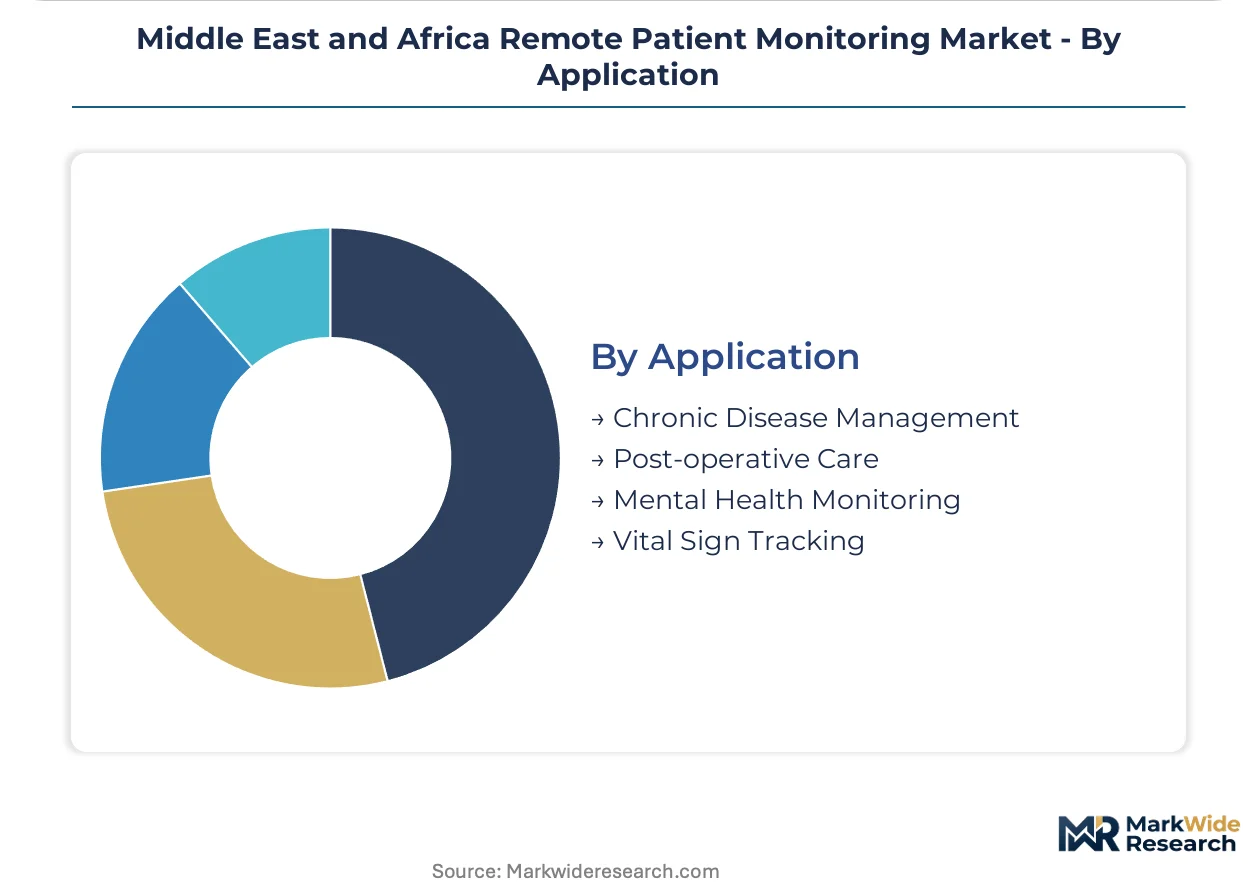
- Chronic Disease Management:Diabetes and cardiovascular telemetry programs generate sustained revenue through long patient engagement cycles and recurring device consumables. South African Health Products Regulatory Authority streamlined registration pathways accelerate vendor entry into these high-margin application areas.
- Post-operative Care:Hospital-at-home programs across Saudi Arabia and UAE deploy surgical recovery monitoring to reduce readmission penalties and inpatient bed utilization.
- Mental Health Monitoring:Behavioral health platforms integrate sleep and activity pattern recognition for remote psychiatric oversight.
- Vital Sign Tracking:General physiological parameter surveillance serves undifferentiated acute-care extension and wellness program use cases.
Revenue concentration pools deepest in Chronic Disease Management. Program launches are accelerating most quickly in Post-operative Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing vendor attention toward Gulf Cooperation Council states, where streamlined software-as-medical-device pathways compress compliance costs relative to European or North American equivalents. South Africa's Health Products Regulatory Authority offers intermediate complexity, while sub-Saharan markets outside Kenya and Nigeria present registration friction without offsetting procurement scale.
Saudi Arabia
Hospital-at-home program expansions by the Ministry of Health are generating concentrated demand for cardiac and diabetes telemetry platforms. SFDA's software-as-medical-device framework validates embedded cellular modem configurations, reducing time-to-market for connected monitoring applications. Riyadh anchors procurement volume, with Eastern Province health clusters following in deployment scale.
United Arab Emirates
MOHAP digital health accelerators compress regulatory timelines for vendors entering Dubai and Abu Dhabi health systems. Government-backed telehealth infrastructure investments are collapsing procurement cycles for enterprise-scale monitoring platforms. Dubai Health Authority clusters concentrate demand for integrated video-biometric systems in specialist outpatient settings.
South Africa
Private diabetes management networks are deploying direct-to-patient glucose monitoring subscriptions outside institutional procurement channels. Health Products Regulatory Authority streamlined registration pathways accelerate vendor entry into chronic disease telemetry segments. Gauteng Province health clusters dominate installed capacity, with Western Cape networks expanding hospital-at-home pilots.
Israel
Cardiac implantable electronic device manufacturers leverage embedded remote monitoring capabilities for regional export positioning. Ministry of Health digital health licensing frameworks support cross-border telehealth service provision into Gulf markets. Tel Aviv metropolitan clusters concentrate algorithm development talent for predictive diagnostic alert systems.
Kenya
Health information exchange buildout from Nairobi is establishing interoperability standards for cloud-connected diagnostic peripherals. National hospital insurance fund reimbursement pilots for remote monitoring services are testing sustainable payment mechanisms. Nairobi metropolitan health clusters anchor East African market development, with Mombasa corridor networks following in connectivity infrastructure.
Middle East and Africa Remote Patient Monitoring Market Competitive Landscape
Platform consolidation dominates the current landscape as hospital procurement committees shift from standalone device purchases toward integrated ecosystem awards. The vendor base separates into three tiers: diversified medical technology conglomerates with acute-care installed bases, specialist telehealth service providers, and component-focused equipment manufacturers. Strategic archetypes include acute-care extenders leveraging hospital relationships for home-telemetry entry, and pure-play remote monitoring platforms displacing fragmented suppliers in Gulf state tenders. M&A activity and strategic partnerships represent the dominant competitive vectors as vendors seek regulatory expertise and local deployment capabilities.
Among diversified medical technology conglomerates, Philips Healthcare, Medtronic, and Abbott Laboratories exemplify distinct positioning archetypes. Philips Healthcare occupies the acute-care extender position, leveraging installed bases of hospital devices to secure home-telemetry contracts across Saudi and UAE health systems. Medtronic anchors the cardiac telemetry segment through implantable device portfolios with embedded connectivity. Abbott Laboratories sits within the diabetes-focused tier, representing the chronic disease management archetype through glucose monitoring platforms integrated with clinician dashboards in South African networks.
| Leading Market Players |
|---|
| Philips Healthcare |
| Medtronic |
| Boston Scientific Corporation |
| GE Healthcare |
| BIOTRONIK |
| Honeywell International |
| Abbott Laboratories |
| OMRON Corporation |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Gulf state hospital procurement committees are consolidating vendor selection around integrated platform ecosystems, forcing equipment-only suppliers to absorb margin compression or invest in software development capabilities to remain competitive.
Pricing Analysis
Distributor margins for wearable biosensors and home monitoring systems typically range from 15-25 percent in Saudi Arabia and UAE health system tenders, with direct-to-patient subscription models in South African diabetes networks bypassing this layer entirely. Price differentiation centers on cellular modem integration and SFDA software-as-medical-device certification tier, with fully validated platforms commanding premiums over basic Bluetooth-enabled configurations. Pricing pressure stems from government-backed telehealth infrastructure investments compressing procurement cycles and favoring volume-discounted enterprise contracts. Healthcare providers exhibit highest price sensitivity due to budget consolidation pressures, while direct-to-patient channels show greater willingness to absorb premium pricing for embedded predictive algorithm capabilities.
Supply Chain Analysis
Workforce availability constraints in semiconductor packaging and cellular modem assembly are concentrating component sourcing in Malaysia, Vietnam, and mainland China manufacturing zones. Raw material dependencies include lithium-ion cells for wearable power systems, medical-grade sensors for physiological parameter capture, and encrypted cloud server capacity for real-time data backhaul. Single-source vulnerability around Bluetooth Low Energy chipsets creates supply chain risk given fragmented interoperability standards between vendor ecosystems. Distribution runs through specialist medical device distributors in Gulf Cooperation Council states and direct OEM relationships with South African private health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by aging demographics and government-mandated telehealth infrastructure investments that lock in recurring procurement cycles across hospital networks.
For Market Incumbents: Cement market position through backward integration into cloud architecture development and cellular modem supply agreements, reducing dependency on third-party platform providers. Invest in prospective outcome studies for SFDA software-as-medical-device validation to elevate barriers against non-validated monitoring applications entering Gulf state tenders.
For New Entrants and Emerging Players: Capture whitespace in Kenya's health information exchange buildout and Nigeria's emerging telehealth reimbursement pilots before incumbent platform consolidation hardens. Prioritize direct-to-patient subscription models in South African private diabetes management networks, where institutional procurement bypass creates faster revenue traction than enterprise healthcare provider sales cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialist telehealth service providers possessing regulatory expertise across SFDA, MOHAP, and South Africa's Health Products Regulatory Authority frameworks. The five-to-ten year viability window favors acquisition targets with embedded cellular modem configurations and validated clinical algorithm datasets. Watch for MOHAP digital health accelerator cohort announcements as inflection indicators for platform vendor selection momentum in UAE health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Software-as-Medical-Device Registration | Validated clinical algorithm datasets accelerate market entry into Saudi hospital-at-home programs. |
| Cellular Modem Supply Agreement | Direct component sourcing compresses hardware costs for Gulf state volume tenders. |
| Hospital System Partnership | Enterprise platform contracts with Saudi Ministry of Health anchor recurring revenue streams. |
| Software Companion Development | Predictive alert algorithms integrated with clinician dashboards displace telemetry nursing costs. |
| Reimbursement Strategy | Direct-to-patient subscription models bypass institutional procurement friction in South African networks. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts managers, and telehealth platform engineers grounded the qualitative foundation, cross-referenced against SFDA registration filings, MOHAP digital health accelerator disclosures, South African Health Products Regulatory Authority approval databases, and hospital procurement contract records. Bottom-up and top-down triangulation validated segment-level assumptions across product type, end user, technology, and application dimensions.
Bottom-up modeling aggregated individual country market sizing through the projection horizon, while top-down approaches tested aggregate figures against regional healthcare expenditure patterns and telehealth infrastructure investment disclosures. Segmentation dimensions included wearable versus stationary form factors, institutional versus direct-to-patient procurement channels, Bluetooth versus cellular connectivity architectures, and chronic disease management versus acute episode monitoring applications. CAGRs were derived from fitted growth curves anchored to disclosed procurement pipeline values and patient population epidemiology.
Regulatory timeline delays, data sovereignty mandate expansion, and cellular connectivity infrastructure buildout pace are the dominant revision risks to modeled forecasts. Forecasts reflect assumptions around SFDA framework stability and Gulf state reimbursement continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
North America Patient Temperature Management Market