
 Asia Pacific Battery Management System Market | 2026-2036
Asia Pacific Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Battery Management System Market Outlook
South Korean lithium-ion cell manufacturers is restructuring capacity allocation across the Asia Pacific Battery Management System value chain. Contemporary Amperex Technology Co Limited leverages vertical integration into cell-to-pack architectures to sustain cost advantages in automotive contracts. Panasonic Industry Co Ltd anchors premium industrial applications through precision voltage sensing technology. Texas Instruments Incorporated competes on semiconductor IP density, controlling analog front-end chip supply to tier-one module assemblers.
A battery management system comprises embedded electronics, sensing arrays, and balancing circuitry that monitor cell voltage, temperature, and state-of-charge to prevent thermal runaway and optimize cycle life in multi-cell configurations. These systems typically operate across voltage ranges from 12V to 800V+ depending on series-parallel topology, with automotive-grade units integrating ISO 26262 functional safety compliance for fail-operational performance. Battery Packs as a product category dominates value capture where integrated BMS-module assemblies command margin premiums over discrete component sales. Electric Vehicles as an end-user segment leads volume absorption, while Energy Storage Systems applications are expanding fastest behind utility-scale solar and wind pairing mandates across the region.
China's MIIT enforces GB/T standards for battery traceability and thermal propagation containment, compelling system redesigns with redundant sensing architectures. South Korea's KATS aligns BMS testing protocols with UN ECE R100 through MFDS-adjacent certification pathways for exported automotive modules. Japan's METI directs JIS standard harmonization toward solid-state battery readiness, shaping next-generation BMS semiconductor roadmaps. Stakeholders must decide whether to specialize in high-voltage automotive stacks or diversify into stationary storage where software-defined battery lifecycle management is becoming the primary differentiation axis.
Market Dynamics
China's MIIT traceability mandates are forcing system integrators to redesign sensing architectures around redundant cell-monitoring topologies, compressing development cycles while elevating functional safety requirements across automotive and stationary storage deployments.
Growth Catalysts
- Electric vehicle procurement acceleration:Automotive OEMs across South Korea and Japan are scaling long-term supply agreements for high-voltage BMS modules to support platform electrification roadmaps.
- GB/T 34014 battery traceability mandate:China's MIIT enforcement of cell-level digital passports is creating compliance-driven replacement demand for legacy management systems lacking data-logging capabilities.
- Lithium-ion manufacturing corridor concentration:South Korea's Gyeonggi-do province anchors regional cell production, generating captive demand for precision balancing circuitry and thermal sensing arrays.
Market Restraints
- Analog front-end semiconductor supply concentration:Discreet chip sourcing depends on a concentrated foundry base in Taiwan, exposing module assemblers to capacity allocation volatility.
- High-voltage isolation component cost structure:Automotive-grade optocouplers and isolated ADCs carry 3-4x premiums over industrial equivalents, compressing margins in cost-sensitive EV segments.
- Solid-state battery readiness gap:Japan's METI-directed JIS harmonization for next-generation chemistries is creating design-in uncertainty for incumbent BMS architectures optimized for liquid electrolyte cells.
Strategic Opportunities
- Utility-scale energy storage pairing mandates:Australia's state-level renewable integration requirements are accelerating procurement of software-defined lifecycle management platforms for grid-scale battery farms.
- Second-life automotive pack redeployment:Retired EV modules in China are creating aftermarket demand for refurbished BMS units with recalibrated state-of-health algorithms.
- Cross-border certification pathway convergence:South Korea's KATS alignment with UN ECE R100 through MFDS-adjacent testing is opening streamlined export access for domestic module suppliers.
Industry Challenges
- Functional safety engineering talent scarcity:ISO 26262-certified firmware developers remain concentrated in Germany and Japan, forcing Asia Pacific system houses to compete for remote expertise or absorb training costs.
- Cell-to-pack integration complexity:Elimination of module-level housing is compressing BMS physical design cycles while demanding closer collaboration with pack thermal engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Battery Management System Market |
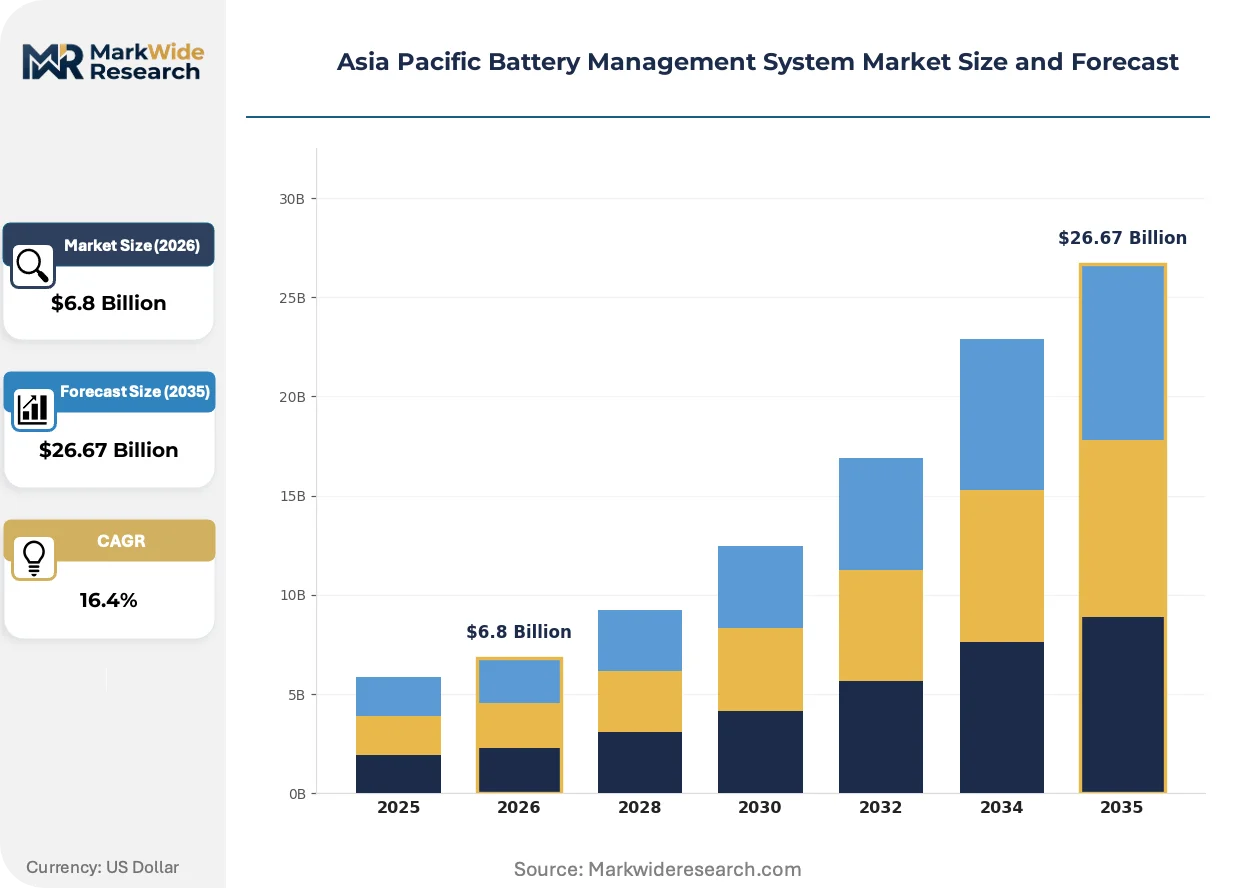
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Packs, Battery Chargers, Battery analyzers, Battery Monitors End User: Electric Vehicles, Renewable Energy, Consumer Electronics, Industrial Applications Technology: Lithium-ion, Lead-acid, Nickel-metal Hydride, Supercapacitors Application: Energy Storage Systems, Automotive, Telecommunications, Uninterruptible Power Supply |
| Companies Covered | Amara Raja Batteries Ltd, Sensata Technologies Inc, Contemporary Amperex Technology Co Limited, Samsung SDI, LG Energy Solution, Panasonic Industry Co Ltd, Texas Instruments Incorporated, BYD, Exide Industries Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Battery Management System Market Strategic Shifts
Embedded intelligence and predictive analytics are migrating from cloud platforms onto edge-processing units within battery modules, enabling real-time state estimation without latency penalties from wireless backhaul.
Wireless battery management systems are converging with automotive Ethernet backbones to eliminate wiring harness weight and assembly complexity. Tier-one suppliers in South Korea are piloting Bluetooth Low Energy mesh topologies for 400V passenger car platforms. This architecture is converging with zone-based vehicle electronics to reduce connector count and enable flexible pack scaling across SUV and sedan variants.
China's MIIT is tightening GB/T 38031 thermal propagation containment standards, mandating multi-point temperature sensing and active venting coordination. System integrators must now validate arc-fault detection algorithms under compressed certification timelines. High-voltage automotive stacks face the steepest redesign burden, with domestic OEMs accelerating supplier qualification for fail-operational architectures.
Cell manufacturers are unbundling hardware supply from software licensing, creating recurring revenue streams through subscription-based state-of-health monitoring. Industrial ESS buyers in Australia and Japan are resisting perpetual-license models, favoring performance-guaranteed service contracts tied to cycle-life outcomes. This shift is most visible in utility procurement frameworks where asset owners prioritize availability commitments over upfront capital minimization.
Asia Pacific Battery Management System Market Segmentation
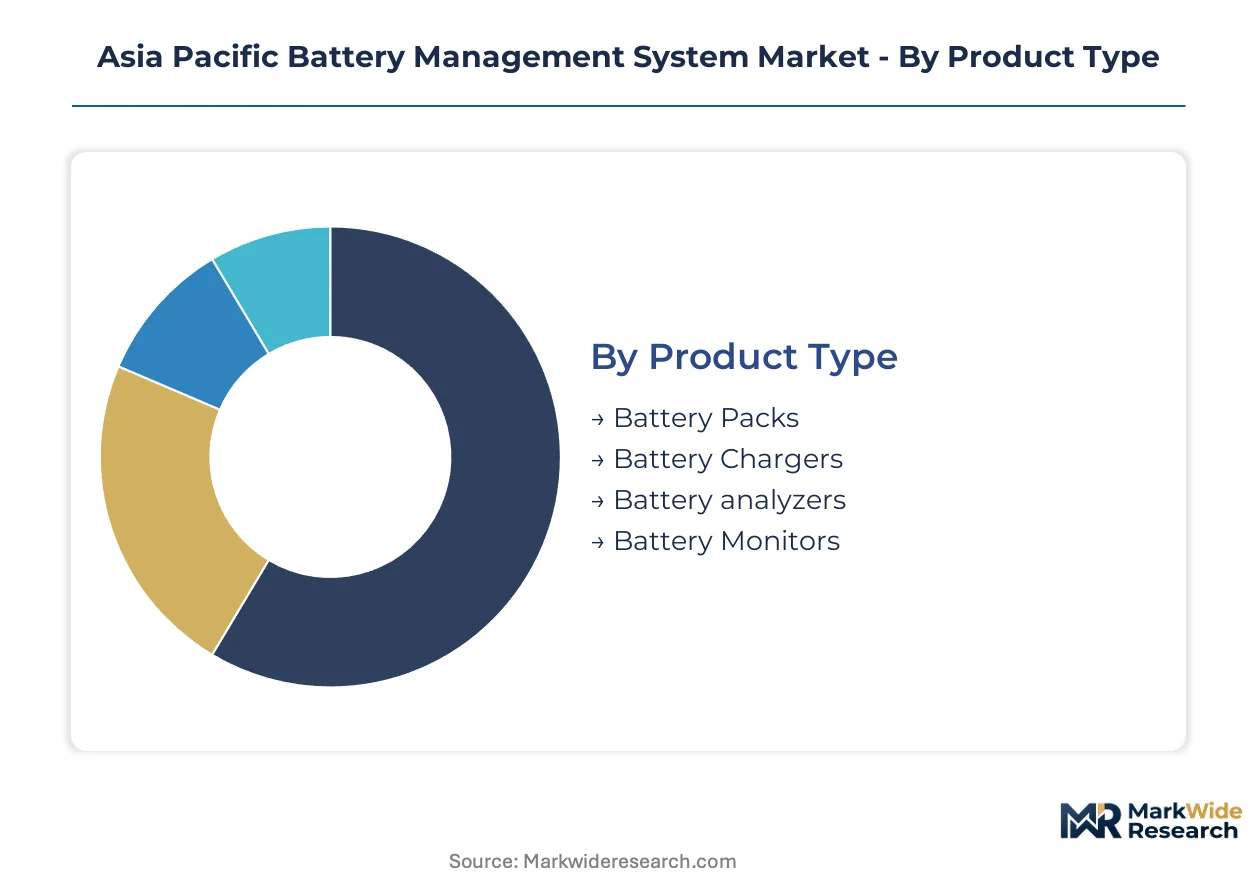
Battery management system procurement patterns diverge sharply across product architectures and end-use requirements. Capital allocation decisions hinge on whether buyers prioritize integrated pack-level solutions or discrete component flexibility.
Product Type:
Integrated assemblies demand substantially higher upfront engineering investment than modular alternatives, with pack-level designs requiring thermal-mechanical co-development.
- Battery Packs:Integrated BMS-module assemblies incorporate cell monitoring units, balancing circuitry, and thermal management interfaces within sealed enclosures. Automotive OEMs in South Korea and Japan concentrate procurement here for platform electrification programs, paying margin premiums over discrete component sourcing.
- Battery Chargers:AC-DC conversion stages with integrated communication protocols for CAN bus and automotive Ethernet backbones. China's MIIT traceability mandates are accelerating replacement of legacy units lacking data-logging capabilities in commercial EV fleets.
- Battery analyzers:Diagnostic platforms for state-of-health estimation and cycle-life prediction.
- Battery Monitors:Standalone voltage and temperature sensing arrays for retrofit applications.
Most installed capacity flows through Battery Packs. Expansion is steepest in Battery Chargers.
End User:
Volume concentration and margin profiles split across mobility-focused versus stationary applications, with divergent certification burdens shaping supplier selection.
- Electric Vehicles:High-voltage architectures spanning 400V to 800V topologies with ISO 26262 functional safety compliance. South Korean cell manufacturers anchor regional demand through Samsung SDI and LG Energy Solution supply agreements.
- Renewable Energy:Utility-scale solar and wind pairing mandates across Australia and Japan drive procurement of software-defined lifecycle management platforms. Asset owners prioritize availability commitments over upfront capital minimization.
- Consumer Electronics:Low-voltage single-cell and multi-cell management for portable devices.
- Industrial Applications:Forklift, robotics, and material handling equipment with extended cycle-life requirements.
Electric Vehicles absorb the greatest component volume. Renewable Energy is climbing the fastest.
Technology:
Electrochemistry determines sensing precision requirements and balancing algorithm complexity, with lithium-ion commanding the most sophisticated management architectures.
- Lithium-ion:Multi-point voltage sensing, active cell balancing, and thermal runaway prevention for nickel-manganese-cobalt and lithium-iron-phosphate chemistries. South Korea's Gyeonggi-do manufacturing corridor generates captive demand for precision balancing circuitry.
- Lead-acid:Simpler float-voltage management for starter batteries and stationary backup systems.
- Nickel-metal Hydride:Legacy hybrid vehicle applications with memory-effect mitigation protocols.
- Supercapacitors:Rapid charge-discharge cycling management for regenerative braking and grid stabilization.
Lithium-ion dominates capital deployment. Supercapacitors are gaining share fastest in grid-frequency regulation.
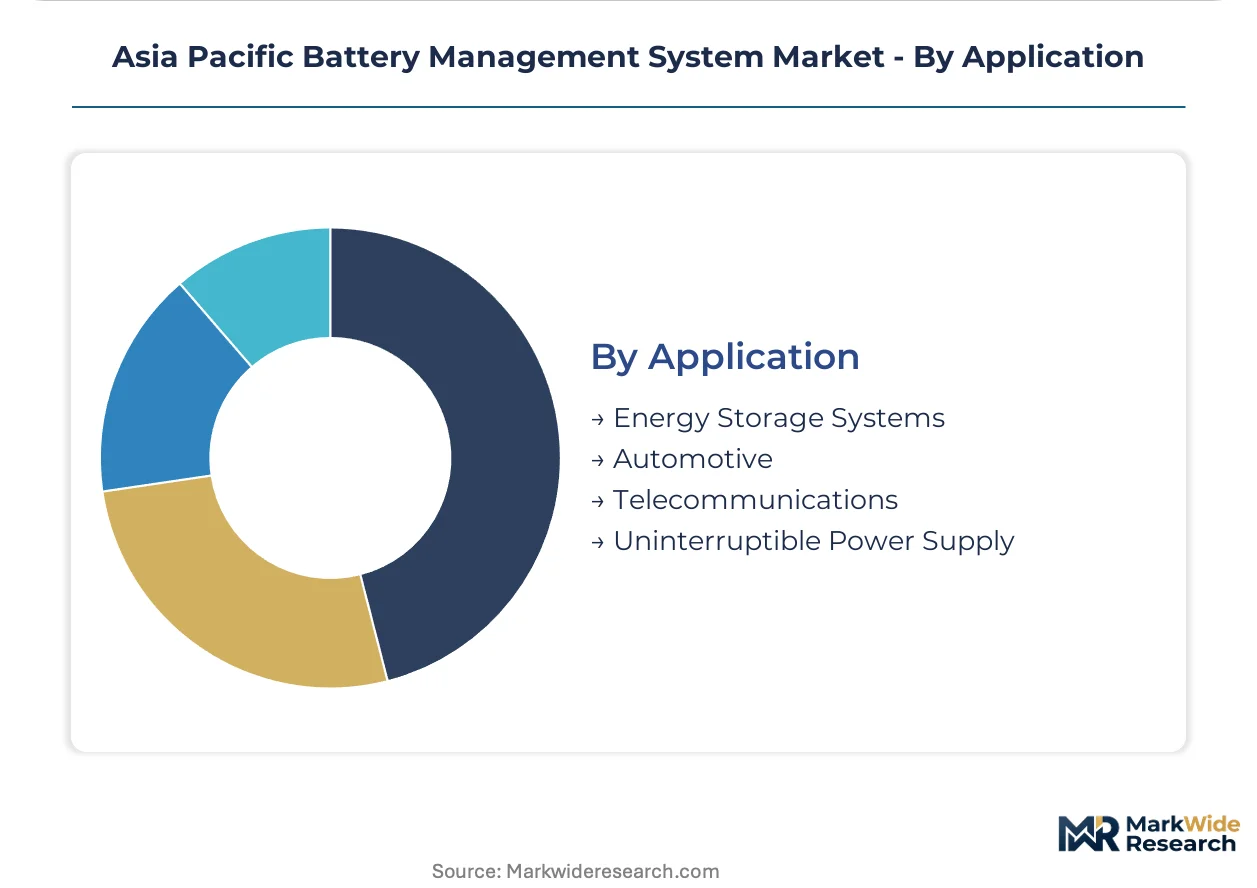
Application:
Functional safety tiers and voltage isolation requirements stratify the addressable market, with automotive and grid-storage presenting divergent engineering priorities.
- Energy Storage Systems:Containerized battery farms with centralized master-slave architectures and cloud-connected predictive analytics. Australia's state-level renewable integration requirements accelerate procurement of software-defined platforms.
- Automotive:Fail-operational designs with redundant sensing and arc-fault detection validated under compressed certification timelines. China's MIIT GB/T 38031 thermal propagation standards impose the steepest redesign burden.
- Telecommunications:Backup power systems with remote monitoring for base station continuity.
- Uninterruptible Power Supply:Data center and critical infrastructure applications with instantaneous switching requirements.
Automotive channels the most engineering resources. Energy Storage Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions offering streamlined certification pathways and lower cost-of-compliance for automotive-grade battery management systems. South Korea's alignment with UN ECE R100 through MFDS-adjacent testing creates arbitrage opportunities against China's stricter GB/T traceability mandates. System integrators relocate module assembly to exploit these regulatory gaps.
China
Domestic EV procurement and utility-scale storage deployment absorb the greatest component volume. MIIT enforces GB/T 34014 battery traceability and GB/T 38031 thermal propagation standards, compelling redundant sensing architectures. The Yangtze River Delta manufacturing cluster concentrates cell-to-pack integration capacity.
South Korea
Samsung SDI and LG Energy Solution anchor captive demand for precision balancing circuitry. KATS aligns BMS testing with UN ECE R100 through MFDS-adjacent certification, streamlining export access. The Gyeonggi-do province hosts the regional lithium-ion manufacturing corridor.
Japan
Premium industrial applications and solid-state battery readiness programs drive semiconductor IP procurement. METI directs JIS standard harmonization toward next-generation chemistries. The Kansai/Osaka industrial belt concentrates precision voltage sensing technology development.
Australia
State-level renewable integration mandates accelerate procurement of software-defined lifecycle management platforms. Utility-scale solar and wind pairing requirements prioritize availability commitments over upfront capital. New South Wales and Victoria host the fastest-expanding grid-scale battery farm deployments.
India
Commercial EV fleet electrification and second-life automotive pack redeployment create aftermarket demand. The national automotive regulator enforces cell-level safety protocols for imported modules. Maharashtra and Gujarat concentrate domestic module assembly and thermal sensing array fabrication.
Asia Pacific Battery Management System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined battery lifecycle management and second-life pack refurbishment. The market structures around three tiers: integrated cell-to-pack specialists, semiconductor IP licensors, and discrete component assemblers. Dominant competitive moves include backward integration into analog front-end chip supply and capacity expansion across automotive-grade isolation component manufacturing. Strategic partnerships between tier-one module assemblers and foundry operators concentrate in Taiwan and South Korea.
Within the integrated cell-to-pack tier, Contemporary Amperex Technology Co Limited and BYD exemplify captive supply strategies. Among semiconductor-focused suppliers, Texas Instruments Incorporated occupies a position controlling analog front-end density for tier-one module assemblers. Samsung SDI and LG Energy Solution sit within the cell manufacturing archetype, generating internal demand for precision balancing circuitry. Sensata Technologies Inc represents the tier-one module assembler category, bridging semiconductor inputs with automotive OEM qualification requirements.
| Leading Market Players |
|---|
| Amara Raja Batteries Ltd |
| Sensata Technologies Inc |
| Contemporary Amperex Technology Co Limited |
| Samsung SDI |
| LG Energy Solution |
| Panasonic Industry Co Ltd |
| Texas Instruments Incorporated |
| BYD |
| Exide Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate spot indices cascading through cathode precursor markets compress margin structures for battery management system assemblers across tiered automotive and stationary storage contracts. China's MIIT traceability mandates add compliance-premium layers that OEMs pass downstream, while Taiwan foundry capacity constraints amplify analog front-end chip pricing volatility.
Pricing Analysis
Distributor margins spanning 12-18 percent separate module assemblers from direct OEM procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 certification grade and volume commitment scale. Cost compression in economy-tier EV modules intensifies because BYD and CATL captive supply eliminates third-party margin capture. Fleet operators in commercial EV segments exhibit highest price sensitivity, while premium automotive OEMs prioritize fail-operational architectures over unit cost minimization.
Supply Chain Analysis
Workforce availability constraints in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor corridor constrain analog front-end chip expansion timelines. Supply concentrates in Taiwan for discrete semiconductor fabrication, South Korea for lithium-ion cell manufacturing, and Japan for precision voltage sensing components. Raw material dependencies span high-purity silicon wafers, automotive-grade isolation substrates, and rare-earth magnet materials for thermal management assemblies. Single-source vulnerability in Taiwan foundry capacity represents the dominant structural risk. Distribution runs through tier-one module assemblers holding direct qualification pathways with Samsung SDI, LG Energy Solution, and CATL.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific battery management system demand compounds through regulatory ratchet effects, with China's MIIT GB/T 38031 thermal propagation standards forcing system redesigns across every deployment scale.
For Market Incumbents: Anchor ISO 26262 certification depth against emerging software-defined battery lifecycle platforms threatening hardware commoditization. Deepen backward integration into analog front-end chip supply through strategic foundry partnerships in Taiwan. Expand Gyeonggi-do province balancing circuitry capacity to capture LG Energy Solution and Samsung SDI procurement acceleration. For New Entrants and Emerging Players: Capture Australia's utility-scale energy storage software-defined lifecycle management segment where incumbent hardware suppliers lack cloud-native analytics capabilities. Target second-life automotive pack refurbishment in China's Yangtze River Delta aftermarket. Pursue performance-guaranteed service contracts rather than perpetual-license models to bypass capital-constrained buyer resistance. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor IP licensors controlling analog front-end density for tier-one module assemblers. Five-to-ten year viability hinges on solid-state battery readiness positioning. Monitor Japan METI JIS harmonization announcements as inflection indicator for next-generation chemistry design-in windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Analog Front-End Supply | Taiwan foundry partnerships secure chip allocation priority for automotive-grade BMS module production. |
| ISO 26262 Functional Safety Certification Investment | Fail-operational architecture qualification opens direct supply agreements with South Korean and Japanese OEMs. |
| Software-Defined Lifecycle Management Platform Launch | Cloud-native analytics differentiate utility-scale ESS offerings in Australia's renewable integration procurement. |
| Second-Life Pack Refurbishment Capacity Buildout | Retired EV module redeployment in China creates aftermarket BMS recalibration service revenue streams. |
| Cross-Border Certification Pathway Convergence | KATS-UN ECE R100 alignment streamlines export access for South Korean module suppliers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate battery management system procurement patterns across the Asia Pacific region. Primary fieldwork engaged BMS platform engineers at automotive OEMs, procurement directors at lithium-ion cell manufacturers, firmware development leads at tier-one module assemblers, and utility-scale ESS asset managers in Australia. Secondary validation drew from MIIT GB/T standard filings, KATS certification registries, METI JIS harmonization announcements, customs trade data for semiconductor imports, and IHS Markit vehicle production databases. Bottom-up component demand modeling and top-down OEM platform electrification roadmaps were cross-referenced for convergence.
Segment-weighting approaches distributed value capture across integrated pack-level assemblies, discrete component sales, and software licensing streams. Analytical frameworks modeled technology splits by lithium-ion, lead-acid, nickel-metal hydride, and supercapacitor electrochemistries; application splits across automotive, energy storage systems, telecommunications, and uninterruptible power supply; and end-user splits spanning electric vehicles, renewable energy, consumer electronics, and industrial equipment. CAGRs were derived from regression analysis against EV penetration curves and utility-scale storage deployment pipelines. Forecast inputs incorporated GB/T 38031 thermal propagation compliance timelines and solid-state battery readiness gaps.
Regulatory enforcement delays, Taiwan foundry capacity allocation shocks, and solid-state battery commercialization acceleration are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding MIIT mandate implementation pacing and OEM platform electrification commitment durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Amplifier Modules Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Global Fault Current Limiter Market
Power Systems
BCD Power IC Market
Power Systems
Vehicle Inverter Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Power Electronics Market
Power Systems
Space DC-DC Converters Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market