

Surface Mounted Medium Voltage Distribution Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mounted Medium Voltage Distribution Panel Market Insights
Multi-source procurement for vacuum interrupter assemblies is pivoting toward vertically qualified suppliers as lead times for ceramic-metal seals extend across the supply base. Schneider Electric leverages captive production of vacuum bottles to sustain delivery commitments for European utility contracts. Siemens anchors its competitive stance through integrated digital twin commissioning tools that reduce field installation cycles. Eaton differentiates via modular busbar architectures that accommodate retrofits in aging North American substations.
A surface mounted medium voltage distribution panel houses switching, protection, and metering apparatus in an enclosure designed for wall or structure mounting without floor-mounted footprint, typically rated between 1 kV and 52 kV with busbar systems constructed from tin-plated copper or aluminum alloys rated to 3150 A continuous current. The assembly serves to distribute electrical power from incoming feeders to multiple outgoing circuits while providing fault isolation and operational visibility for substation operators and facility engineers. Vacuum interruption technology leads installed base economics due to minimal maintenance intervals and elimination of greenhouse gas insulation, while insulated gate bipolar transistor modules represent the fastest-expanding technology segment as utilities deploy solid-state switchgear for microsecond-level fault current limitation. Gas insulated switchgear occupies premium margin pools in coastal and contaminated environments where compact footprint outweighs capital cost premiums.
The International Electrotechnical Commission's IEC 62271-200 standard for metal-enclosed switchgear and the IEEE C37.20.2 specification for metal-clad switchgear govern arc containment, accessibility, and internal fault withstand ratings that manufacturers must certify before utility procurement eligibility. China's National Energy Administration enforces GB 3906 type-testing protocols that restrict market access for uncertified panel assemblies in state grid tenders. Stakeholders must monitor evolving F-Gas Regulation restrictions in Europe and corresponding EPA SNAP program deliberations in the United States, as these frameworks progressively constrain SF6 circuit breaker viability and redirect R&D investment toward vacuum and solid dielectric alternatives.
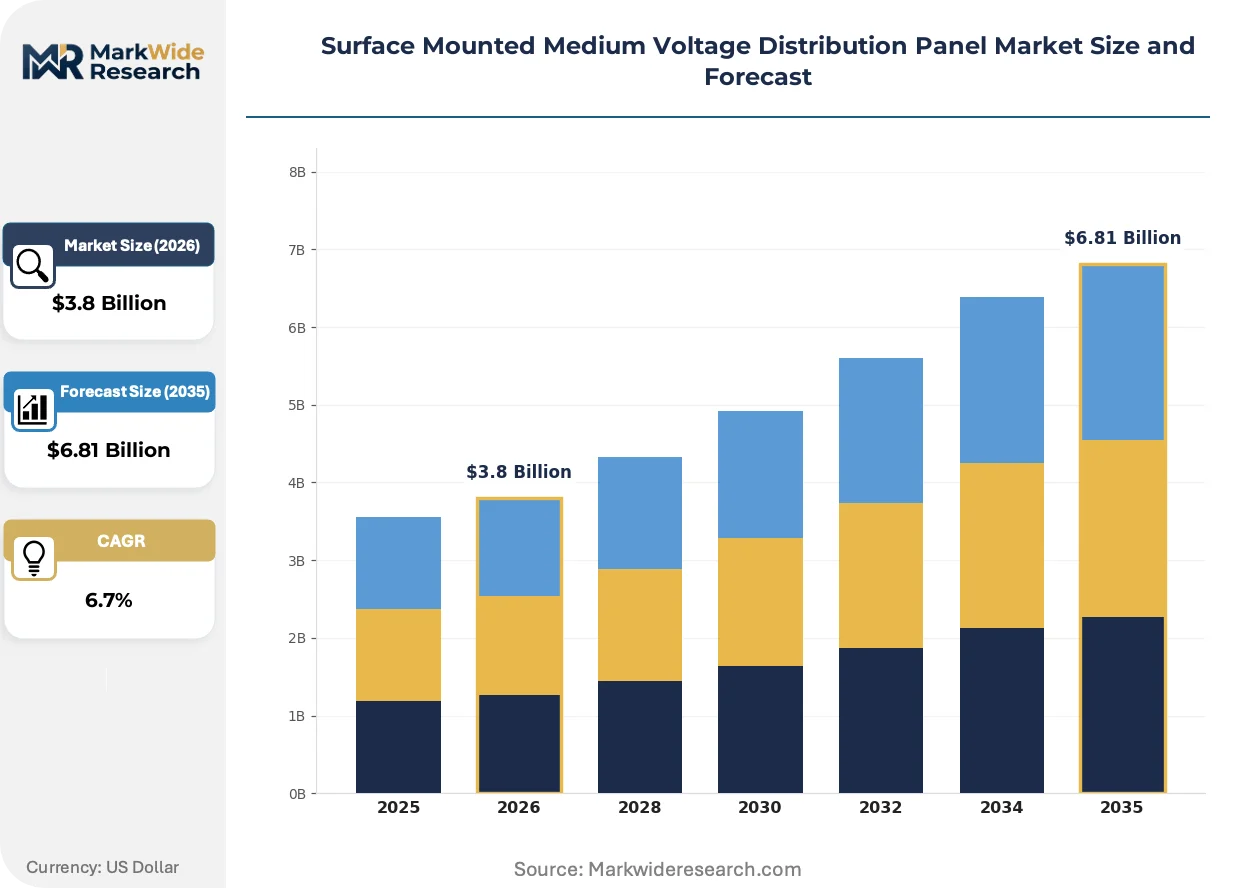
Market Dynamics
Vacuum interruption technology is compressing maintenance cycles across utility fleets while arc-flash containment standards from IEC 62271-200 and IEEE C37.20.2 are forcing enclosure redesigns that absorb engineering resources and extend certification timelines.
Growth Catalysts
- Data center electrification clusters:Hyperscale operators in Northern Virginia and Frankfurt are procuring surface-mounted panels to support substation automation for multi-hundred-megawatt facilities.
- China's state grid modernization:Eastern coastal provinces are accelerating panel deployment for renewable integration projects under National Energy Administration procurement mandates.
- F-Gas Regulation phase-down:The European framework is redirecting utility capital toward vacuum and solid dielectric alternatives, expanding addressable market for SF6-free assemblies.
Market Restraints
- Ceramic-metal seal supply concentration:Vacuum interrupter lead times extend across the supply base as vertically qualified suppliers capture procurement allocations.
- Seismic certification costs:IEEE C37.98 testing requirements for high-risk zones add material and validation burden to enclosure engineering.
- Copper busbar price volatility:Tin-plated copper alloy input costs fluctuate with commodity markets, compressing margin on fixed-price utility contracts.
Strategic Opportunities
- Retrofit-ready modular architectures:Aging North American substations require busbar configurations that accommodate legacy footprint constraints without full replacement.
- Solid-state switchgear convergence:Insulated gate bipolar transistor modules paired with vacuum interruption enable microsecond-level fault current limitation for microgrid applications.
- Digital twin commissioning tools:Integrated simulation platforms reduce field installation cycles and differentiate vendor positioning in European utility tenders.
Industry Challenges
- Arc-flash containment engineering shortage:Specialized enclosure design expertise for IEC 62271-200 internal fault withstand ratings concentrates among limited engineering consultancies.
- Multi-standard certification timelines:Simaneous GB 3906, IEC, and IEEE validation for cross-border projects extends product launch windows by quarters.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mounted Medium Voltage Distribution Panel Market Trends and Innovations
Technology trajectories in this market center on solid-state interruption, predictive maintenance integration, and enclosure miniaturization for contaminated environments. These shifts are compressing traditional equipment lifecycles while opening premium positioning for certified alternatives.
Insulated gate bipolar transistor modules are rewriting fault protection economics by enabling sub-cycle current limitation without mechanical wear. Utilities deploying microgrids and renewable-heavy feeders are piloting these assemblies at accelerating pace. The technology is compressing the traditional vacuum interrupter replacement cycle and enabling new service revenue models around predictive thermal monitoring.
Europe's F-Gas Regulation is accelerating SF6 phase-out timelines across transmission and distribution procurement. The policy framework now constrains circuit breaker viability in coastal and contaminated environments where gas insulation previously dominated. Panel manufacturers are redirecting R&D investment toward vacuum and solid dielectric alternatives to maintain eligibility in state-owned utility tenders.
Buyer concentration among hyperscale data center operators is compressing vendor qualification cycles and unbundling after-sales service expectations. Traditional distributor channels face disintermediation as direct procurement teams in Northern Virginia and Frankfurt negotiate multi-site framework agreements. This concentration is visible most acutely in 15-27 kV rated segments where standardization across facility footprints reduces engineering customization.
Surface Mounted Medium Voltage Distribution Panel Market Segmentation
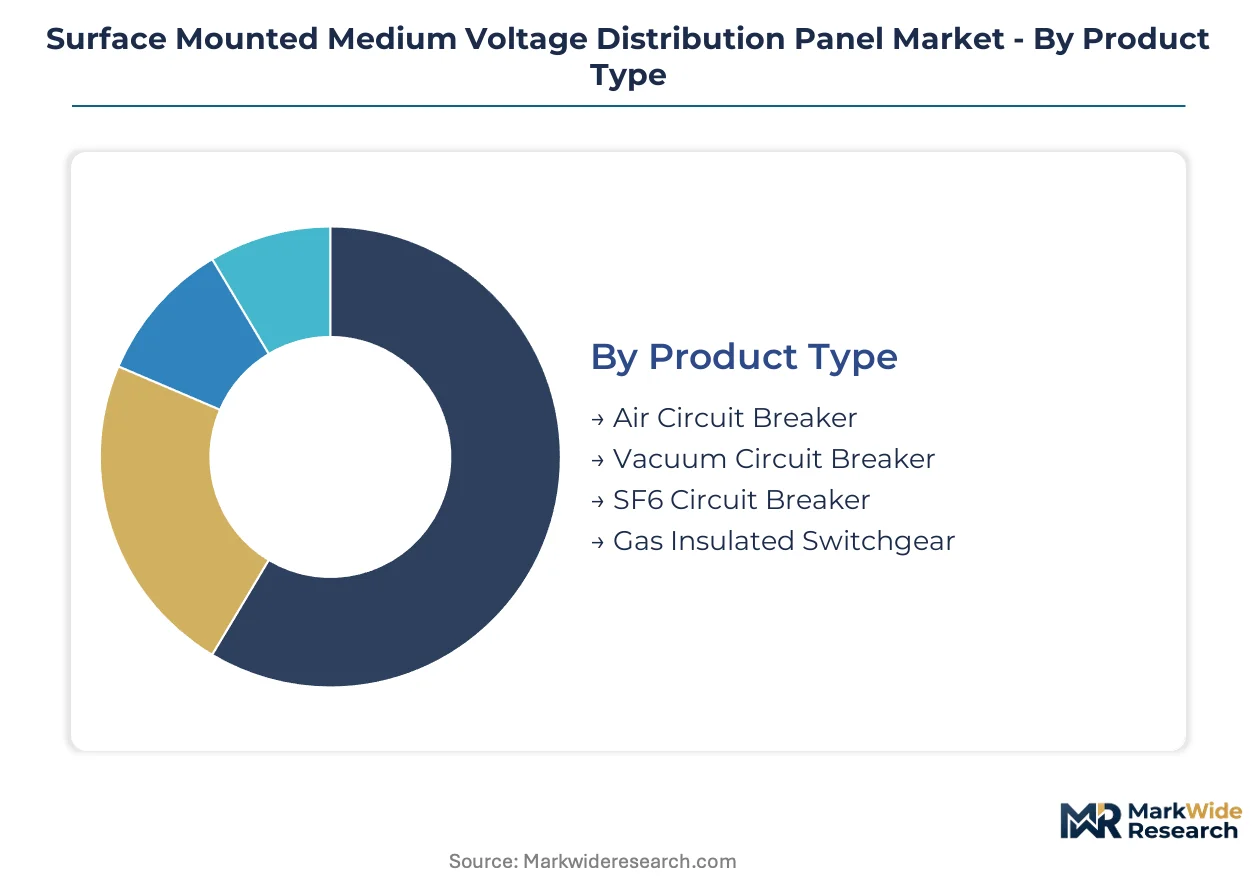
Segmentation in surface-mounted medium voltage distribution panels reveals how procurement criteria diverge across buyer archetypes. Technology choices, enclosure specifications, and certification requirements fragment demand patterns in ways that reshape vendor positioning and channel economics.
Product Type:
Buyers differentiate primarily by maintenance burden tolerance and environmental operating constraints, with capital availability and footprint restrictions driving technology selection.
- Vacuum Circuit Breaker:Ceramic-metal sealed vacuum bottles eliminate greenhouse gas insulation and compress maintenance intervals to decade-scale cycles. Data center operators in Northern Virginia and Frankfurt specify these assemblies for hyperscale substations where downtime costs dwarf capital premiums.
- Gas Insulated Switchgear:Sulfur hexafluoride or alternative gas insulation enables compact footprint in coastal and contaminated environments where space constraints override cost sensitivity. European F-Gas Regulation phase-down timelines are redirecting utility capital toward SF6-free alternatives, compressing near-term demand.
- Air Circuit Breaker:Open-air arc quenching suits indoor installations with controlled environments and maintenance access.
- SF6 Circuit Breaker:Legacy installed base in transmission-heavy utilities faces replacement pressure from environmental compliance frameworks.
Volume sits with vacuum circuit breakers; growth tilts toward gas insulated switchgear as contamination-resistant designs gain certification.
Technology:
Investment intensity separates adopters, with solid-state architectures commanding premium positioning against mature electromechanical alternatives.
- Insulated Gate Bipolar Transistor:Solid-state modules enable microsecond-level fault current limitation without mechanical wear. Microgrid developers and renewable-heavy utilities pilot these assemblies for sub-cycle protection where traditional interruption speeds prove inadequate.
- Vacuum Interruption:Mature ceramic-metal seal technology dominates installed base economics through minimal maintenance and elimination of gas handling. China's state grid tenders specify these for eastern coastal substation automation projects under National Energy Administration mandates.
- Solid Dielectric:Epoxy resin insulation eliminates gas dependency entirely for environmentally constrained procurement.
- Thyristor Controlled Reactor:Reactive power compensation integrates with switching functions in specialized transmission applications.
Revenue concentrates with vacuum interruption; steepest expansion trajectory belongs to insulated gate bipolar transistor as solid-state switchgear scales from pilot to deployment.
Application:
Project scale and grid integration complexity segment buyers, with renewable interconnection requirements forcing technology upgrades across utility fleets.
- Substation Automation:IEC 61850-compliant panels with integrated protection, metering, and remote control serve centralized grid management. Eastern Chinese provinces deploy these for state grid modernization under procurement mandates that privilege certified domestic manufacturers.
- Renewable Integration:Bi-directional power flow and fault ride-through capabilities accommodate solar and wind farm interconnection. European utilities specify these for offshore wind collector substations where environmental compliance constrains technology choice.
- Power Generation:Generator switchgear and unit auxiliary transformers require specialized arc containment ratings.
- Electrical Distribution:Standardized feeder panels serve industrial and commercial load centers with conventional protection schemes.
Deployment volume favors substation automation; expansion tilts toward renewable integration as interconnection queues lengthen and grid codes tighten.
End User:
Procurement sophistication and qualification velocity separate buyer categories, with hyperscale operators compressing vendor cycles against utility bureaucracy.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt negotiate multi-site framework agreements that bypass traditional distributor channels. Standardized 15-27 kV specifications across facility footprints reduce engineering customization and accelerate procurement velocity.
- Utilities:State-owned and investor-owned grid operators enforce multi-standard certification requirements—GB 3906, IEC 62271, IEEE C37—that extend product launch timelines. China's National Energy Administration restricts tender eligibility to type-tested assemblies.
- Manufacturing Plants:Industrial electrification projects specify panels for captive substations with process-critical reliability requirements.
- Commercial Complexes:Real estate developers prioritize first-cost minimization and code-minimum compliance in distributed installations.
Contract value concentrates with utilities; procurement velocity and margin expansion tilt toward data centers as direct buyer concentration reshapes channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern coastal provinces and Northern Virginia's data center corridor, with European utilities accelerating procurement ahead of F-Gas Regulation deadlines. Regulatory divergence across IEC, IEEE, and GB standards fragments certification pathways while creating distinct procurement zones.
United States
Hyperscale data center operators in Northern Virginia drive procurement of 15-27 kV surface-mounted panels for multi-hundred-megawatt substations. IEEE C37.20.2 and C37.98 standards govern arc-flash containment and seismic certification requirements. The Pacific Northwest sees utility deployments for renewable integration as offshore wind interconnection queues lengthen.
Germany
Frankfurt's data center cluster generates concentrated demand for IEC 62271-200 certified assemblies with vacuum interruption technology. The F-Gas Regulation phase-down redirects utility capital toward SF6-free alternatives ahead of 2030 deadlines. Industrial zones in Bavaria deploy panels for manufacturing electrification under grid modernization programs.
China
Eastern coastal provinces accelerate panel deployment for state grid modernization and renewable integration projects. GB 3906 type-testing protocols restrict tender eligibility to certified domestic and qualified foreign manufacturers. Jiangsu and Zhejiang industrial corridors see substation automation procurement under National Energy Administration mandates.
India
State electricity boards in Maharashtra and Gujarat procure surface-mounted panels for urban distribution network upgrades. Central Electricity Authority regulations enforce seismic and short-circuit withstand testing for utility tenders. The Delhi-Mumbai Industrial Corridor drives captive substation installations for manufacturing zone electrification.
Japan
Tokyo Electric Power and regional utilities specify compact gas-insulated switchgear for coastal substations facing space constraints. METI efficiency standards accelerate replacement of aging air-insulated installations. Osaka-Kobe industrial zones deploy vacuum interruption panels for semiconductor fabrication facility upgrades.
Surface Mounted Medium Voltage Distribution Panel Market Competitive Landscape
Backward integration into vacuum interrupter supply dominates the current landscape as ceramic-metal seal lead times extend across qualified suppliers. The vendor base concentrates around three tiers: integrated electrical conglomerates with captive component production, regional specialists with certification depth in single geographies, and emerging solid-state technology developers. Strategic differentiation pivots on digital twin commissioning capabilities and modular retrofit architectures. M&A activity targets vacuum bottle manufacturers while capacity expansion concentrates in China and Eastern Europe.
Within the integrated conglomerate tier, ABB and Schneider Electric exemplify archetypes built on vertical control over critical subsystems. Siemens anchors the European utility positioning through simulation-driven commissioning platforms. Among Asia-Pacific specialists, Mitsubishi Electric and Fuji Electric occupy positions defined by seismic certification depth and compact design heritage for space-constrained installations. Larsen & Toubro represents the regional champion model with India-specific regulatory navigation capabilities.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| General Electric |
| Mitsubishi Electric |
| Larsen & Toubro |
| Fuji Electric |
| Hyosung Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Europe's F-Gas Regulation phase-down gates qualified supply access for SF6-dependent manufacturers while concentrating premium-tier pricing power among vacuum interrupter specialists with captive ceramic-metal seal production. Buyers seeking IEC 62271-200 certified assemblies face elongated procurement cycles as vertically integrated incumbents capture allocation priority.
Pricing Analysis
Volume concentrates with standard vacuum circuit breaker configurations while margin accrues to solid-state IGBT modules and gas-insulated switchgear for contaminated environments. Three-tier pricing structure across premium certified, standard type-tested, and economy-grade assemblies reflects certification depth and seismic rating differentiation. Cost compression in the standard tier intensifies because copper busbar commodity volatility and fixed-price utility contract structures squeeze fabricator margins. Data center operators in Northern Virginia exhibit lowest price sensitivity due to downtime cost exposure, whereas commercial complex developers prioritize first-cost minimization above lifecycle economics.
Supply Chain Analysis
Ceramic-metal seal supply rests on Japanese and German specialty manufacturers with qualified vacuum interrupter heritage, while copper alloy processing concentrates in China and Chile. Critical inputs include tin-plated copper busbar, epoxy resin solid dielectric compounds, and silicon-controlled rectifier semiconductor substrates. Single-source vulnerability in vacuum bottle assembly creates procurement risk as lead time extensions cascade through European utility project schedules. Distribution runs through direct manufacturer relationships for hyperscale data center frameworks and electrical distributor networks for industrial and commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive vacuum interrupter production determines delivery reliability and margin defense against commodity input volatility.
For Market Incumbents: Anchor competitive position through backward integration into vacuum bottle manufacturing or long-term ceramic-metal seal offtake agreements with Japanese suppliers. Schneider Electric's captive production model exemplifies this defensive posture. Invest in simultaneous GB 3906, IEC 62271, and IEEE C37 certification to compress cross-border product launch windows against emerging solid-state switchgear substitutes. For New Entrants and Emerging Players: Engineering consultancies with specialized arc-flash containment expertise represent the most penetrable channel partner type for bypassing incumbent certification barriers. Target retrofit-ready modular busbar architectures in aging North American substations where legacy footprint constraints create white-space demand. Solid-state IGBT module development for microgrid applications offers technology differentiation without direct confrontation with established vacuum interrupter economies of scale. For Investors and Strategic Acquirers: Vacuum interrupter manufacturer acquisition announcements from integrated electrical conglomerates are the leading indicator that supply-side consolidation is accelerating and independent component suppliers face margin compression. Long-term viability favors specialists with digital twin commissioning capabilities or seismic certification depth in high-risk zones. Watch F-Gas Regulation enforcement intensity as the signal for SF6-free technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive ceramic-metal seal supply secures delivery commitments for European utility contracts against qualified supplier allocation constraints. |
| Multi-Standard Certification Investment | Simultaneous GB 3906, IEC 62271, and IEEE C37 validation compresses product launch windows for cross-border state grid tenders. |
| Digital Twin Commissioning Platform Development | Siemens-integrated simulation tools reduce field installation cycles and differentiate vendor positioning in European utility procurement. |
| Solid-State IGBT Module R&D Scale-Up | Microsecond-level fault current limitation enables new service revenue models around predictive thermal monitoring for microgrid developers. |
| Retrofit-Ready Modular Busbar Architecture | Eaton's flexible configurations accommodate legacy footprint constraints in aging North American substations without full replacement. |
Research Methodology
Multi-period observation of hyperscale data center procurement velocity, vacuum interrupter lead time trends, and state grid tender award patterns anchored the trend analysis, supplemented by interviews with utility planning officers, EPC contractors, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation against SEC 10-K filings, customs and trade data, National Energy Administration procurement disclosures, and IEC certification registry records. Bottom-up segment sizing triangulated against top-down market envelope estimates from electrical infrastructure capex tracking.
Input-output matrix framing connected vacuum interrupter production capacity, copper alloy price indices, and certification timeline data to panel shipment forecasts across the analysis window. Segmentation dimensions modeled include interruption technology, enclosure insulation type, application function, end-user category, and regional regulatory cluster. CAGRs derived from regression analysis of historical installation data against projected electrification investment trajectories. Forecast inputs incorporated data center power density specifications and renewable interconnection queue lengths as demand-side drivers.
Caveats apply where F-Gas Regulation enforcement intensity, ceramic-metal seal supply disruption, or seismic certification requirement expansion could materially shift the outlook. Forecasts reflect assumptions about utility capital commitment continuity and hyperscale facility development schedules. A small set of named triggers—vacuum interrupter manufacturer M&A activity, GB 3906 protocol amendments, and solid-state switchgear pilot-to-deployment conversion rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.