
 Static VAR Compensator (SVC) Market | 2026-2036
Static VAR Compensator (SVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Static VAR Compensator (SVC) Market Analytics
The capability gap between integrated manufacturers and component assemblers is collapsing as thyristor sourcing costs equalize. ABB Ltd. leverages captive semiconductor fabrication to sustain margin structures that pure-system integrators cannot match. Siemens AG anchors European utility procurement through localized engineering centers. NR Electric Co. Ltd. dominates Chinese state-grid tenders by bundling SVC hardware with proprietary control software.
A Static VAR Compensator is a power-electronics device that injects or absorbs reactive volt-amperes to stabilize grid voltage, typically employing thyristor-controlled reactors and switched capacitor banks rated from tens to hundreds of megavars. Thyristor-Based SVC retains the largest installed base among product types due to decades of field-proven reliability in high-voltage transmission. Modular Multilevel Converter architectures are displacing conventional topologies in renewable energy integration projects where harmonic performance requirements exceed legacy specifications. Data center end users represent a concentrated margin pool because uptime guarantees command premium pricing for dynamic response capability.
IEC 61954 compliance mandates govern European SVC certification, while China's GB/T 15576 standards dictate domestic product testing protocols. India's CEA grid-code amendments now require renewable developers to install dynamic reactive compensation at interconnection points. Stakeholders must monitor how semiconductor supply constraints affect thyristor lead times relative to project commissioning schedules.
Market Dynamics
The transition from thyristor-based SVCs to Modular Multilevel Converter architectures is compressing incumbent margins while opening procurement to new semiconductor suppliers. Grid operators now prioritize harmonic performance over field-proven reliability, forcing equipment vendors to requalify control platforms.
Growth Catalysts
- India's CEA grid-code amendments:Renewable developers must install dynamic reactive compensation at interconnection points, creating mandatory demand for SVC hardware.
- Data center uptime guarantees:Colocation operators now specify sub-cycle voltage response in procurement contracts, commanding premium pricing for dynamic capability.
- Silicon carbide semiconductors:Wider bandgap devices reduce switching losses in high-power converters, enabling compact SVC designs for space-constrained substations.
Market Restraints
- Thyristor supply concentration:Discrete semiconductor fabrication concentrates in East Asian foundries, exposing project timelines to single-source vulnerability.
- IEC 61954 certification friction:European type-testing protocols require 18-24 month validation cycles, delaying product launches relative to faster domestic Chinese GB/T 15576 routes.
- Modular STATCOM substitution:Voltage-source converter alternatives offer superior reactive power control bandwidth, capturing greenfield transmission projects.
Strategic Opportunities
- Offshore wind grid integration:HVDC converter stations require coordinated reactive compensation, opening SVC-plus-synchronous condenser bundled offerings.
- US Inflation Reduction Act manufacturing credits:Domestic content requirements for grid infrastructure incentivize localized SVC assembly capacity.
- Digital twin convergence:Real-time thermal modeling of thyristor junction temperatures enables predictive maintenance contracts with utility asset managers.
Industry Challenges
- Power electronics control firmware expertise:SVC vendors compete for embedded systems engineers capable of implementing IEEE 1303-compliant closed-loop algorithms.
- Legacy SCADA integration complexity:Brownfield substations operate proprietary communication protocols, requiring custom gateway development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static VAR Compensator (SVC) Market |
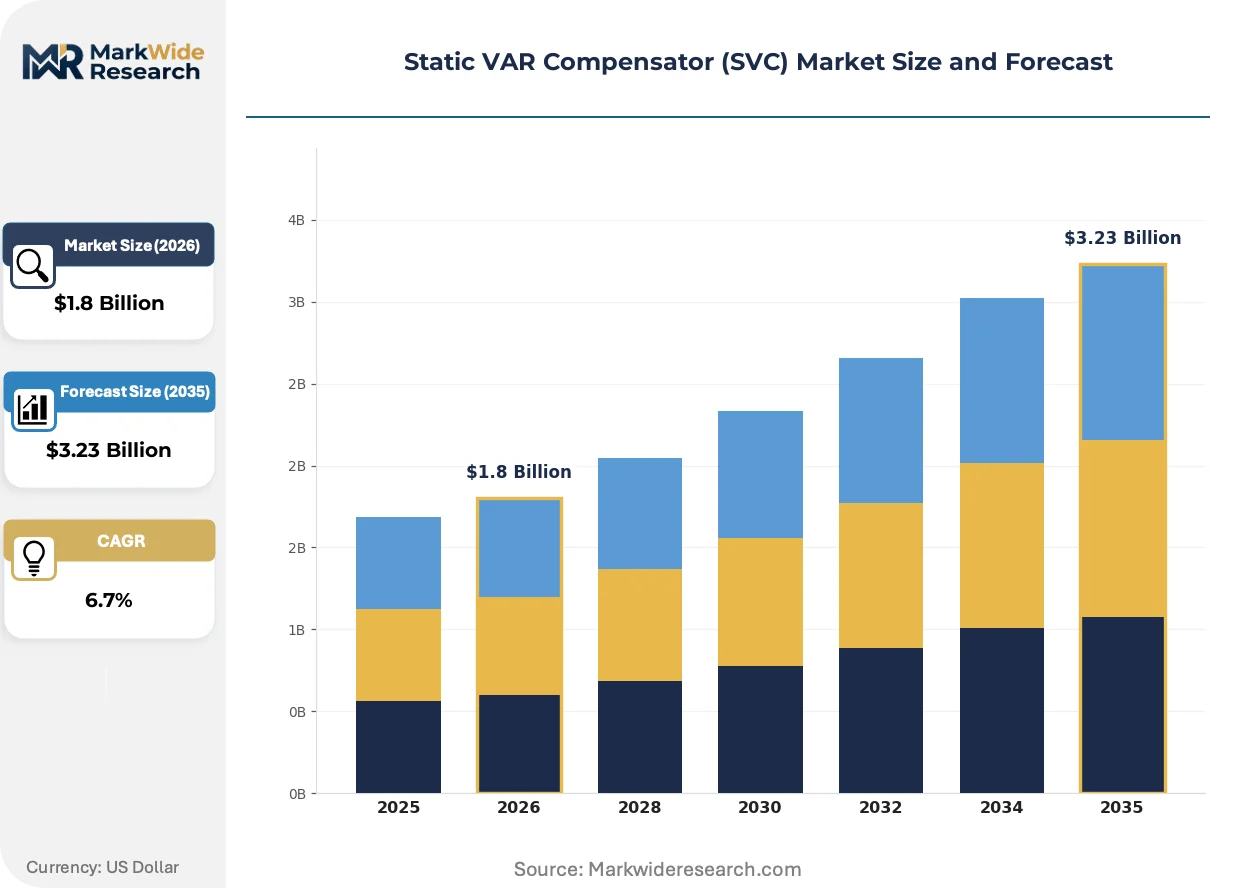
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thyristor-Based SVC, Capacitor-Based SVC, Modular Multilevel Converter, Others End User: Utilities, Industrial Manufacturing, Renewable Energy, Data Centers Installation Type: Indoor, Outdoor, Onshore, Offshore Control System: Static Control, Dynamic Control, Hybrid Control, Others |
| Companies Covered | ABB Ltd., Siemens AG, General Electric, Mitsubishi Electric Corporation, Toshiba Corporation, Hitachi Energy, Eaton Corporation, Hyosung Corporation, NR Electric Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static VAR Compensator (SVC) Market Evolving Landscape
Semiconductor material transitions and control software unbundling are fragmenting the traditional integrated SVC vendor model. Procurement patterns now favor component-level sourcing over turnkey system contracts.
Modular Multilevel Converter architectures are displacing conventional thyristor-controlled reactor banks in renewable integration projects. Offshore wind developers in the North Sea specify MMC-based STATCOMs for their superior harmonic performance under variable generation profiles. This displacement compresses the addressable market for legacy SVC topologies in greenfield installations.
China's GB/T 15576 standards now mandate dynamic response testing under unbalanced voltage conditions, exceeding IEC 61954 requirements. Domestic manufacturers must validate equipment across asymmetric fault scenarios before state-grid tender eligibility. European vendors seeking Chinese market access face parallel certification tracks with divergent test sequences.
Utility procurement teams now unbundle control software licenses from hardware supply contracts. German transmission system operators separately negotiate multi-year maintenance agreements for SVC control platforms. This unbundling exposes pure-hardware vendors to margin pressure while rewarding firms with proprietary algorithm IP.
Static VAR Compensator (SVC) Market Segmentation
SVC procurement patterns diverge sharply across product architectures and end-use applications. Regulatory mandates in power grids and data center uptime requirements create distinct demand profiles that reshape vendor positioning.
Product Type:
IEC 61954 and IEEE 1303 impose divergent testing protocols on thyristor versus converter-based architectures, fragmenting certification pathways.
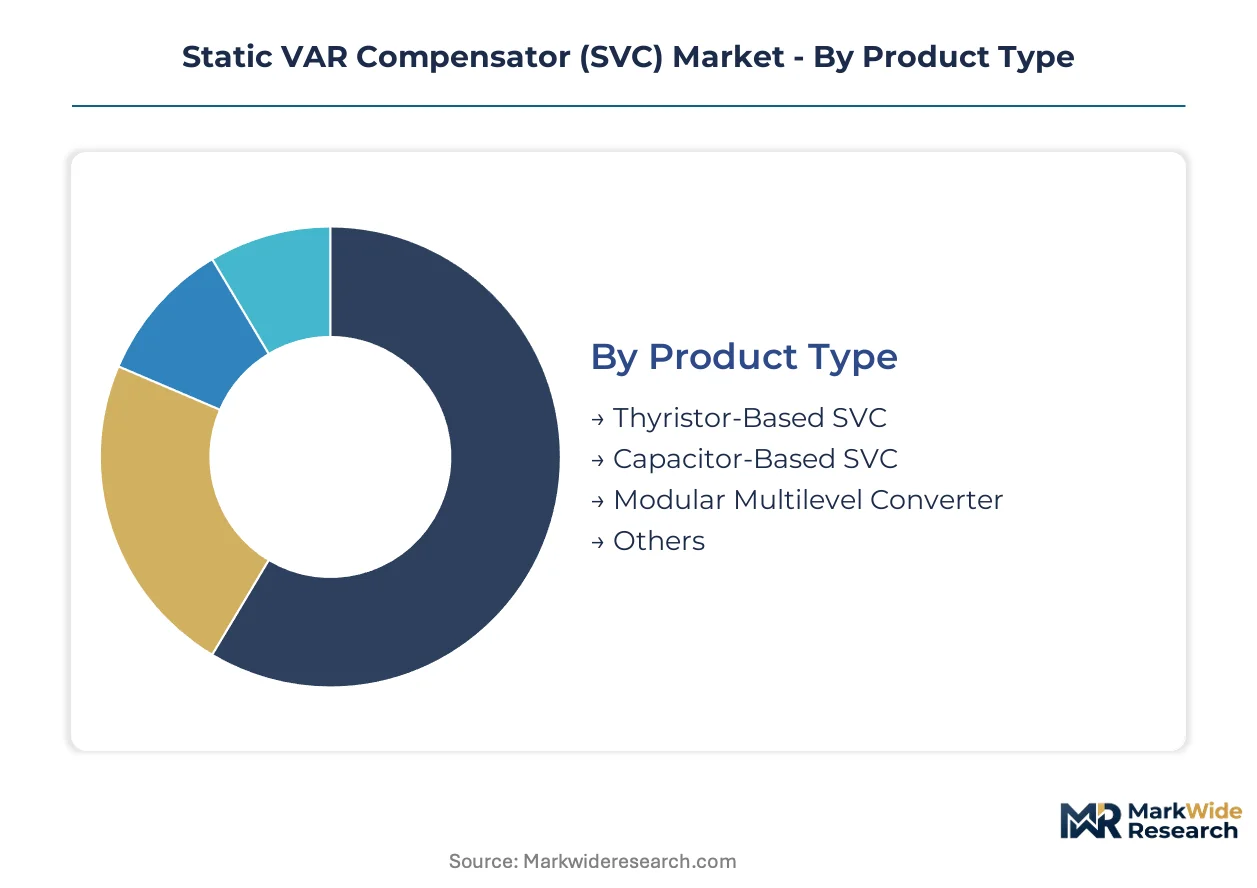
- Thyristor-Based SVC:Silicon-controlled rectifier stacks switch reactor and capacitor banks to inject or absorb reactive power in discrete steps. European transmission operators specify these for 400 kV backbone reinforcement due to decades of field-proven reliability under IEEE 1303 compliance regimes.
- Modular Multilevel Converter:Cascaded half-bridge cells synthesize near-sinusoidal voltage waveforms with minimal harmonic distortion. Offshore wind developers in the North Sea favor this topology for HVDC converter station coordination where harmonic performance exceeds legacy SVC specifications.
- Capacitor-Based SVC:Mechanically switched capacitor banks provide stepped reactive compensation for distribution voltage support.
- Others:Saturated reactor designs serve niche applications in steel mill arc furnace flicker mitigation.
Thyristor-Based SVC handles the majority of installed throughput; Modular Multilevel Converter is gaining share fastest in renewable integration tenders.
End User:
Customer procurement authority concentrates in state-owned transmission operators and hyperscale data center operators with divergent technical specifications.
- Utilities:National grid operators deploy SVC hardware at transmission substations to manage voltage collapse risks during contingency events. China's State Grid Corporation bundles SVC procurement with synchronous condenser packages for regional voltage stability.
- Data Centers:Colocation providers specify sub-cycle voltage response guarantees in SLA contracts, commanding premium pricing for dynamic reactive capability. Frankfurt and Amsterdam clusters drive European demand.
- Renewable Energy:Wind and solar developers face mandatory dynamic reactive compensation requirements at interconnection points.
- Industrial Manufacturing:Steel and cement plants install SVC systems to mitigate power quality disturbances from large motor loads.
Utilities absorb the largest equipment volumes; Data Centers expand most quickly on premium-margin dynamic response contracts.
Installation Type:
Environmental protection ratings and seismic compliance requirements split procurement between enclosed and open-air configurations.
- Outdoor:Weatherproof thyristor valve halls and capacitor racks withstand temperature cycling at transmission substations. Indian utilities favor outdoor SVC installations for lower civil infrastructure costs in high-temperature climates.
- Indoor:Climate-controlled enclosures protect semiconductor junctions in corrosive coastal environments. German North Sea offshore converter stations specify indoor SVC containment for salt spray protection.
- Onshore:Ground-mounted installations at existing substation sites dominate brownfield deployments.
- Offshore:Platform-mounted reactive compensation serves wind farm collector systems and HVDC links.
Outdoor configurations handle the majority of project throughput; Offshore installations are climbing the fastest on North Sea wind development.
Control System:
Software licensing unbundling from hardware supply contracts restructures vendor revenue models across control architectures.
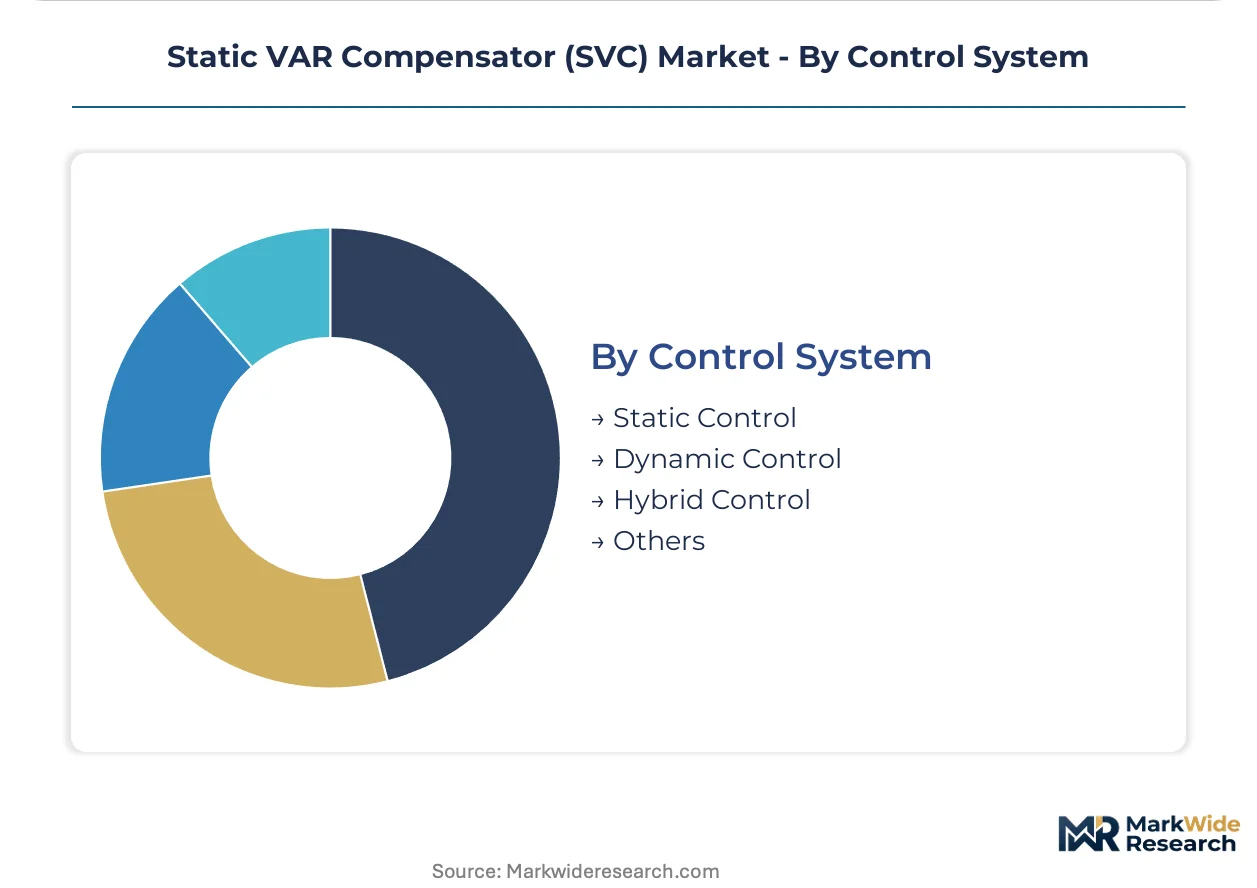
- Dynamic Control:Real-time closed-loop algorithms adjust reactive output within milliseconds of voltage deviation detection. Data center operators in Northern Virginia mandate dynamic control for sub-cycle response guarantees.
- Hybrid Control:Combines steady-state optimization with transient response modes for grid code compliance. Indian renewable developers adopt hybrid architectures to satisfy CEA requirements while minimizing switching losses.
- Static Control:Fixed setpoint operation provides basic voltage support without continuous adjustment.
- Others:Adaptive control schemes with machine learning-based parameter tuning serve experimental deployments.
Dynamic Control commands the largest installed base; Hybrid Control is expanding fastest on renewable interconnection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among procurement teams varies sharply by geography. Indian utilities prioritize lowest capital expenditure bids, while German transmission operators accept 40-60% cost premiums for IEC 61954-certified equipment with predictive maintenance packages.
China
State Grid Corporation tenders drive volume concentration in ultra-high voltage corridors. GB/T 15576 mandates dynamic response testing under unbalanced voltage conditions that exceed European requirements. Yangtze River Delta manufacturers cluster in Suzhou and Changzhou, supplying thyristor valve stacks for domestic and export markets.
India
CEA grid-code amendments create mandatory demand at renewable interconnection points. Central Electricity Authority enforcement accelerated after 2023 voltage collapse events in Rajasthan and Karnataka. Gujarat and Tamil Nadu host the fastest project pipelines, with Adani Green Energy and Tata Power procuring SVC hardware for solar parks.
Germany
Transmission system operators TenneT and 50Hertz specify sub-cycle response guarantees for North Sea offshore wind integration. IEC 61954 certification requires 18-24 month validation cycles at KEMA or CESI laboratories. Hamburg and Bremerhaven converter stations deploy indoor SVC containment for salt spray protection.
United States
FERC Order 2023 compliance deadlines accelerate reactive compensation procurement across ISO territories. Inflation Reduction Act manufacturing credits incentivize domestic assembly capacity in Texas and Ohio. ERCOT's interconnection queue backlog in West Texas drives concentrated demand for dynamic voltage support at solar and storage projects.
Brazil
National Electric Energy Agency reliability standards mandate voltage stability investments in the North-Southeast transmission corridor. Eletrobras privatization opened procurement to international vendors previously excluded from state tenders. Belo Monte and Madeira River hydro complexes require coordinated SVC deployment for long-distance power transfer.
Static VAR Compensator (SVC) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SVC market. Integrated manufacturers with captive semiconductor fabrication command premium positioning, while pure-system integrators compete on project execution speed and localized engineering support. Three archetypes dominate: vertically integrated industrial conglomerates, regional specialists with state-grid relationships, and power-electronics component suppliers extending into systems integration. Competitive moves concentrate on backward integration into thyristor sourcing and unbundling of software maintenance contracts from hardware supply.
Among European-based industrial conglomerates, ABB Ltd. and Siemens AG exemplify the integrated archetype with in-house semiconductor capabilities. NR Electric Co. Ltd. represents the regional specialist model, anchoring Chinese state-grid procurement through bundled hardware-software offerings. These three occupy distinct competitive positions without direct overlap in core tender markets.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| General Electric |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Hitachi Energy |
| Eaton Corporation |
| Hyosung Corporation |
| NR Electric Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Chinese thyristor foundries lock in semiconductor supply access while anchoring price visibility for European and Indian system integrators facing volatile raw material markets. These arrangements transfer inventory risk upstream but constrain procurement flexibility when GB/T 15576 certification timelines slip.
Pricing Analysis
Software maintenance agreements now drive lifetime value, with German transmission operators paying 40-60% premiums for multi-year predictive maintenance bundled with IEC 61954-certified hardware. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance tiers from basic warranty coverage. Pricing pressure stems from MMC-based STATCOM substitution in renewable tenders, compressing margins on legacy thyristor designs. Indian utilities exhibit highest price sensitivity, prioritizing lowest capital expenditure bids over lifecycle service commitments.
Supply Chain Analysis
Strategic stockpiling of silicon-controlled rectifier stacks dominates procurement strategy among European vendors buffering against East Asian foundry lead time volatility. Thyristor fabrication concentrates in China, South Korea, and Japan, drawing from high-purity silicon wafers, ceramic housing materials, and specialized heat sink alloys. Single-source vulnerability in discrete semiconductor fabrication exposes project timelines to regional production disruptions. Distribution runs through EPC contractors and direct utility procurement channels with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators and national transmission utilities, fragmenting vendor pricing leverage as procurement teams unbundle software licenses from hardware supply.
For Market Incumbents: Secure captive semiconductor fabrication capacity or exclusive foundry partnerships to defend margin structures against pure-system integrators. Invest in IEC 61954 certification fast-track programs to compress 18-24 month validation cycles. Prioritize predictive maintenance algorithm IP development as control software unbundling accelerates. For New Entrants and Emerging Players: GB/T 15576 certification fast-track partnerships with Yangtze River Delta testing laboratories enable state-grid tender eligibility within compressed timelines. Target Indian renewable developers facing mandatory CEA compliance deadlines with hybrid control architectures minimizing switching losses. Pursue white-label control software licensing to EPC contractors seeking differentiated procurement offerings. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated industrial conglomerates with in-house thyristor capabilities and proprietary algorithm IP. Long-term viability hinges on semiconductor supply chain control and software maintenance recurring revenue. Watch MMC-based STATCOM penetration rates in North Sea offshore wind tenders as inflection indicator for legacy SVC addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thyristor Sourcing | Captive semiconductor fabrication insulates margin structures from East Asian foundry concentration. |
| Software License Unbundling | Multi-year maintenance agreements with German TSOs create recurring revenue independent of hardware cycles. |
| GB/T 15576 Certification Fast-Track | Accelerated validation at Suzhou testing centers unlocks Chinese state-grid tender participation. |
| Predictive Maintenance Platform Development | Real-time thermal modeling of thyristor junction temperatures enables utility asset management contracts. |
| Offshore Wind Bundled Offerings | SVC-plus-synchronous condenser packages address HVDC converter station coordination requirements in North Sea projects. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, EPC contractors, grid operators, and semiconductor procurement specialists and refined through secondary validation. Bottom-up project pipeline analysis triangulated with top-down regulatory mandate tracking across CEA, IEC, and FERC jurisdictions. Secondary sources included FERC Order 2023 filings, IEC 61954 test protocols, CEA grid-code amendments, and EPC contractor project databases.
Variance decomposition across product architecture, end-use application, and control system dimensions structured the analytical framework throughout the forecast period. CAGRs were derived from installed base growth rates and replacement cycle timing across thyristor-based and MMC-based segments. Forecast inputs incorporated semiconductor supply lead time volatility and renewable interconnection queue backlogs.
Decision-makers should treat outputs as directional under assumptions of sustained grid modernization investment and stable semiconductor supply; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding regulatory enforcement timelines and technology substitution rates. Revision becomes warranted when MMC-based STATCOM cost parity crosses thresholds in high-voltage transmission applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Batteries for Semiconductor Market
Power Systems
Telecom Battery Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Power Electronics Market
Power Systems
Micro-Inverter Market
Power Systems
AC DC Power Adapter Market
Power Systems
EV Power Module Market
Power Systems
Global DC Power Supply Module Market
Power Systems
South America Battery Management System Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Vehicle Inverter Market
Power Systems
Central Battery Systems Market
Power Systems
Generator Circuit Breaker Market