
 Three Phase Micro Inverters Market | 2026-2036
Three Phase Micro Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Three Phase Micro Inverters Market Insights
The installer channel for three-phase micro inverters is fragmenting as regional distributors compete with direct-to-project procurement platforms. Enphase Energy leverages its installer certification programs to sustain brand loyalty among commercial integrators. SMA Solar Technology AG anchors European project pipelines through its service network density. Growatt New Energy competes aggressively on price-performance ratios in emerging solar markets.
Three-phase micro inverters convert direct current from photovoltaic strings into grid-synchronized alternating current across three voltage phases, typically handling power ratings from 1 kW to 5 kW per unit with maximum power point tracking efficiency exceeding 99%. These devices serve commercial and industrial installations where three-phase grid connection is mandatory and string-level monitoring prevents cascading system failures. Grid-tied installations dominate volume shipments while hybrid configurations capture expanding margin pools as battery attachment rates rise. The commercial end-user segment leads absolute demand, though agricultural deployments on irrigation-intensive farms represent the fastest-growing application niche.
FCC Part 15 emissions compliance governs electromagnetic interference limits for units sold into the United States, while EU CE marking under the Low Voltage Directive and Electromagnetic Compatibility Directive governs market access across member states. India's CEA technical standards for grid-connectivity and the BIS certification mandate shape product qualification timelines for suppliers targeting that market. Stakeholders must monitor evolving grid code harmonization between national regulators and the interoperability implications of smart inverter functionality mandates.
Market Dynamics
Commercial rooftop solar developers are consolidating procurement through direct-to-project platforms, bypassing traditional distributor layers and compressing channel margins across the three-phase micro inverter supply base.
Growth Catalysts
- IEEE 1547 interconnection standards:Tightened grid response requirements in the United States are mandating advanced inverter functionality that only three-phase micro inverters can deliver at string level.
- Utility-scale solar pipelines:India's renewable energy targets are accelerating demand for modular, monitorable AC conversion at commercial and industrial installations.
- Battery attachment rate expansion:Hybrid configurations with integrated storage are capturing premium margin pools as agricultural irrigation farms adopt solar-plus-storage systems.
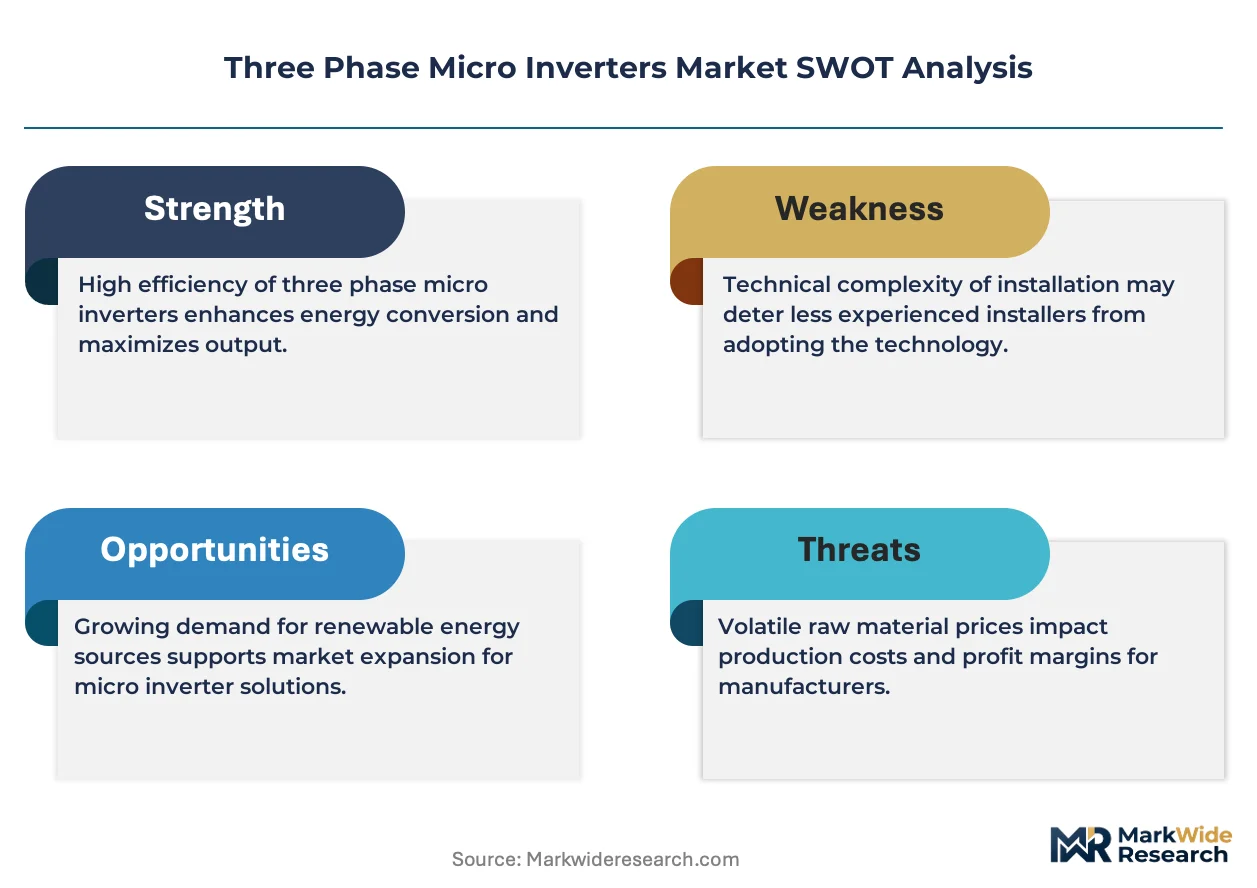
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor sourcing remains concentrated among East Asian foundries, exposing inverter assemblers to input cost volatility and allocation constraints.
- CE marking complexity:EU Low Voltage Directive and Electromagnetic Compatibility Directive compliance timelines extend product qualification cycles by six to nine months for non-European manufacturers.
- String inverter substitution:Centralized string architectures with module-level power electronics are capturing cost-sensitive commercial segments below 500 kW system capacity.
Strategic Opportunities
- Australian commercial solar acceleration:The country's CEC accreditation requirements favor three-phase micro inverters for systems above 30 kW, creating a qualified supplier bottleneck that early movers can exploit.
- Smart inverter functionality mandates:Grid code harmonization between German BNetzA and regional network operators is requiring reactive power support and ride-through capabilities that micro inverter architectures natively provide.
- Direct-to-integrator digital platforms:Procurement marketplaces are disintermediating distributors and enabling manufacturers to capture service revenue through remote monitoring subscriptions.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for maximum power point tracking algorithm development and thermal management design is concentrated among a handful of regional technology clusters.
- Multi-jurisdiction certification burden:Simultaneous FCC Part 15, CE marking, and BIS compliance requires parallel testing streams that strain smaller manufacturers' quality assurance bandwidth.
- Legacy string system retrofit integration:Three-phase micro inverter replacements for aging central inverter infrastructure face DC bus voltage mismatches and communication protocol incompatibilities with existing monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Phase Micro Inverters Market |
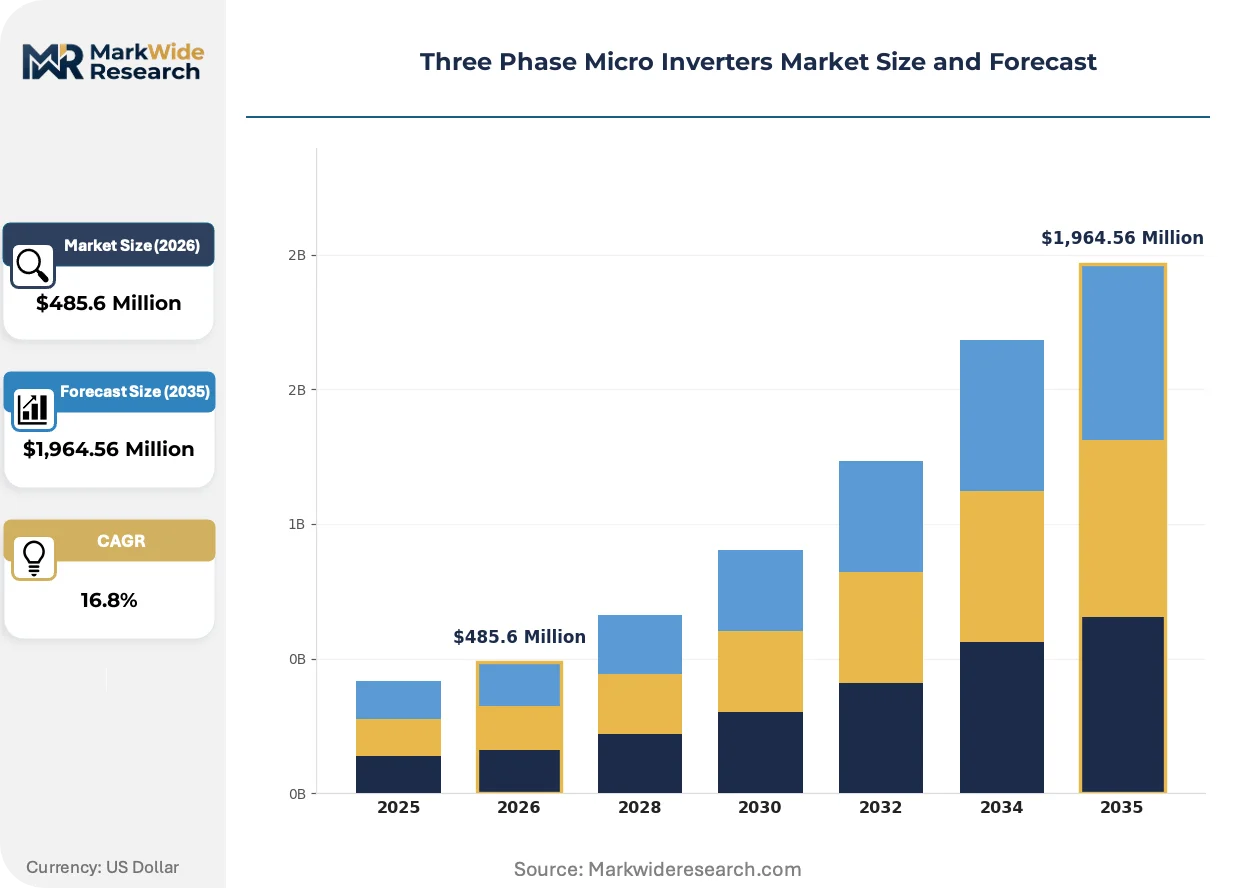
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,964.56 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Smart Inverter End User: Residential, Commercial, Industrial, Agricultural Technology: Power Electronics, Pulse Width Modulation, Digital Signal Processing, AC Coupling Installation Type: Roof Mount, Ground Mount, Building Integrated, Others |
| Companies Covered | Enphase Energy, Altenergy Power System, Darfon Electronics, Growatt New Energy, Chilicon Power, Hoymiles, Siemens, SMA Solar Technology AG, Ningbo Deye Inverter Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Phase Micro Inverters Market Trends and Innovations
Power conversion architectures are fragmenting as module-level electronics converge with storage integration, forcing manufacturers to recalibrate R&D roadmaps around hybrid functionality rather than pure efficiency metrics.
Silicon carbide MOSFETs are replacing traditional IGBT switches in three-phase micro inverter designs, enabling switching frequencies above 50 kHz that shrink magnetic component volume by 40%. Commercial integrators in Germany and Australia are specifying these units for space-constrained rooftop installations. This semiconductor transition is hybridizing inverter product lines, collapsing distinctions between premium and standard tiers as wide-bandgap devices become baseline.
EU grid codes under the F-Gas Regulation are phasing out sulfur hexafluoride insulation in medium-voltage equipment, indirectly pressuring low-voltage inverter manufacturers to demonstrate compatibility with SF6-free switchgear interfaces. Industrial project developers in the Netherlands and Denmark are now requiring environmental product declarations alongside technical specifications. The commercial segment is responding by accelerating supply chain audits and material traceability documentation.
Installer certification programs are becoming the primary loyalty mechanism as product differentiation narrows on efficiency and warranty terms. Enphase's training accreditation and SMA's service network density are locking commercial integrators into single-vendor relationships that resist price-based switching. This channel consolidation is most pronounced in California and Bavaria, where permitting authorities recognize only pre-approved installer credentials for commercial system approvals.
Three Phase Micro Inverters Market Segmentation
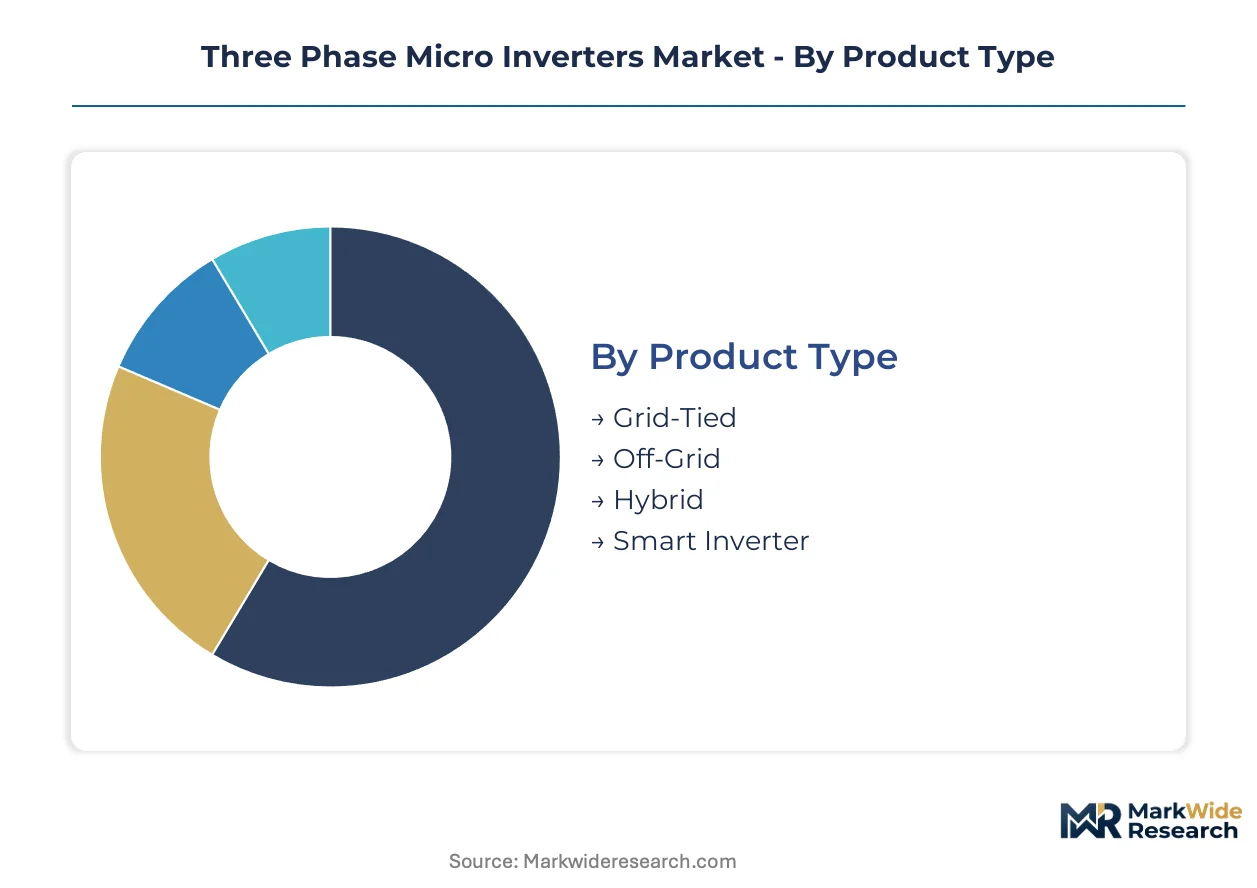
Three-phase micro inverter purchasing decisions cascade through multiple technical and commercial dimensions. Installers, project developers, and EPC contractors each weight these segments differently when specifying equipment for commercial and industrial solar deployments.
Product Type:
Mature grid-tied architectures dominate current procurement volumes while emerging hybrid configurations capture expanding margin pools as storage attachment rates climb.
- Grid-Tied:These units convert DC photovoltaic output directly to grid-synchronized AC without integrated storage capability. Commercial rooftop developers in Germany and Australia specify these for pure solar installations where battery economics remain unfavorable. IEEE 1547 compliance requirements in the United States are tightening response specifications that favor advanced grid-tied architectures with ride-through functionality.
- Hybrid:Integrated DC-coupled or AC-coupled battery interfaces enable solar-plus-storage operation from a single enclosure. Agricultural irrigation farms across India and Australia are adopting these units to shift load profiles and reduce peak demand charges. The semiconductor transition to silicon carbide MOSFETs is collapsing cost premiums between hybrid and standard configurations.
- Off-Grid:Standalone units with integrated charge controllers serve remote industrial sites and agricultural pumping stations beyond utility infrastructure.
- Smart Inverter:Grid-supportive functionality including volt-var optimization and frequency-watt response addresses evolving network operator requirements in jurisdictions with high renewable penetration.
Grid-Tied retains volume leadership; Hybrid holds the steepest expansion curve.
End User:
Cost tier stratification separates premium-specified commercial installations from price-sensitive agricultural deployments.
- Commercial:Office buildings, retail centers, and logistics facilities constitute the largest absolute demand segment. Project developers in California and Bavaria prioritize module-level monitoring and rapid shutdown compliance that three-phase micro inverters natively provide. Procurement is consolidating through direct-to-project platforms that bypass traditional distributor markups.
- Agricultural:Irrigation-intensive farms and cold storage operations represent the fastest-growing application niche. Australian cotton growers and Indian horticulture operations are deploying solar-plus-storage configurations to manage pumping loads and refrigeration cycles. CEC accreditation requirements favor three-phase micro inverters for systems above 30 kW.
- Industrial:Manufacturing facilities and processing plants demand high availability and string-level fault isolation to prevent production interruptions.
- Residential:Large estate homes and multi-unit dwellings with three-phase service connections represent a smaller volume segment with distinct certification requirements.
Commercial dominates absolute procurement; Agricultural is climbing the fastest.
Technology:
Volume concentration centers on established power electronics architectures while emerging digital control methods reshape competitive differentiation.
- Power Electronics:IGBT and silicon carbide switching circuits form the core conversion topology. East Asian foundry concentration for these semiconductors exposes assemblers to allocation constraints and input cost volatility.
- Digital Signal Processing:Advanced MPPT algorithms and grid synchronization routines execute on dedicated microcontrollers. Specialized firmware engineering talent clusters in Germany, California, and Taiwan.
- Pulse Width Modulation:Switching frequency selection balances magnetic component size against electromagnetic compatibility compliance with FCC Part 15 and CE marking requirements.
- AC Coupling:Battery integration architectures that retrofit existing solar installations without DC bus reconfiguration.
Power Electronics retains volume leadership; Digital Signal Processing holds the steepest expansion curve.
Installation Type:
Application context determines mounting architecture selection with distinct supply chain and labor implications.
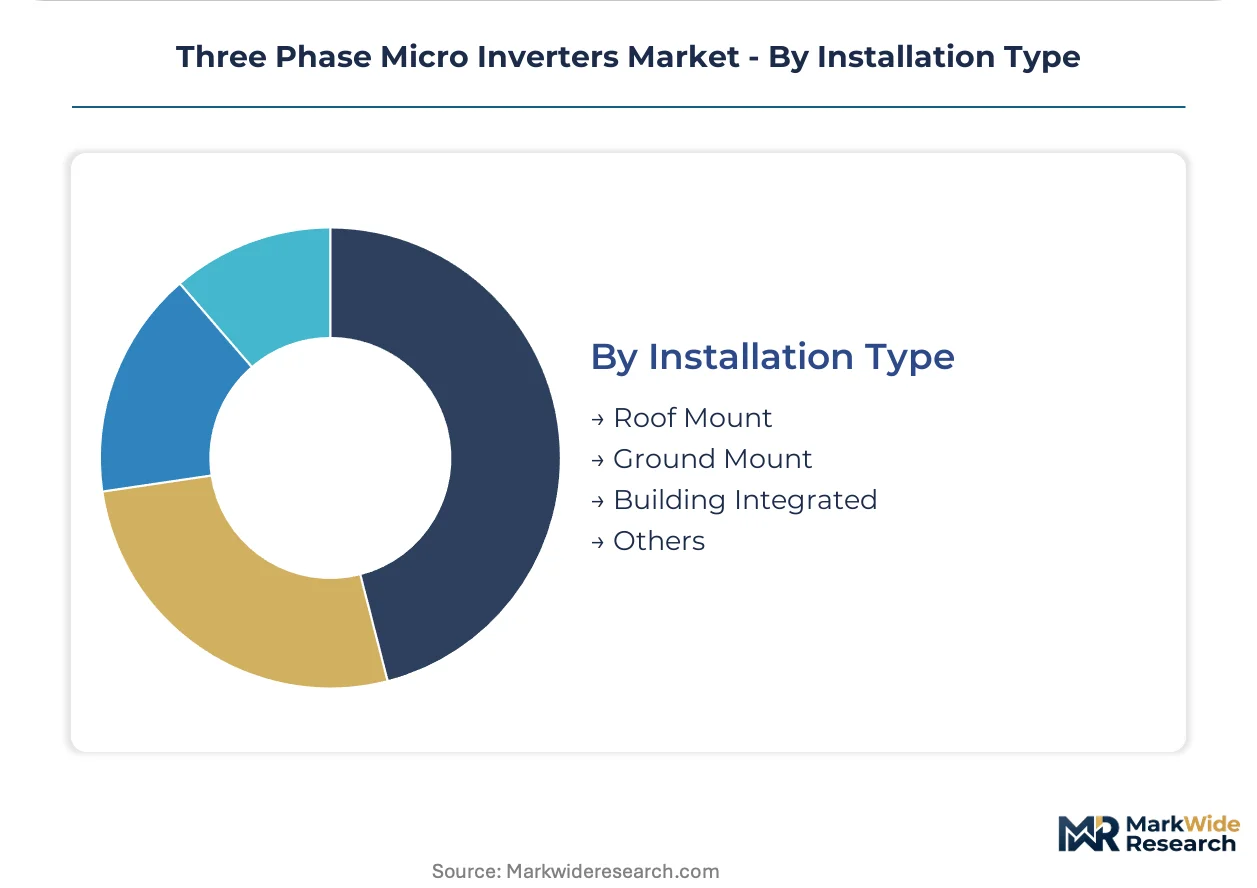
- Roof Mount:Commercial and industrial building rooftops constitute the primary deployment surface. Space-constrained installations in dense urban markets favor compact silicon carbide-based units with reduced magnetic component volume.
- Ground Mount:Utility-scale and agricultural solar arrays on open land. German BNetzA grid codes and Australian CEC requirements shape equipment specification for these larger systems.
- Building Integrated:Facade and canopy installations where aesthetic and structural integration requirements override pure cost optimization.
- Others:Carport canopies, floating solar platforms, and specialized agricultural structures.
Roof Mount retains volume leadership; Ground Mount holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-California grid interconnect underwrites United States demand for three-phase micro inverters, while the Australian Energy Market Operator's transmission upgrades anchor Asia-Pacific procurement volumes.
United States
Commercial rooftop developers in California and Texas are consolidating procurement through direct-to-project platforms. IEEE 1547 interconnection standards mandate advanced grid response functionality that three-phase micro inverters deliver at string level. The Los Angeles Basin industrial corridor sees concentrated deployment for logistics facility solar arrays.
Germany
BNetzA grid codes require reactive power support and ride-through capabilities that favor micro inverter architectures. The F-Gas Regulation pressures compatibility with SF6-free switchgear interfaces. Bavaria's manufacturing belt hosts dense service networks locking commercial integrators into single-vendor relationships.
India
Utility-scale solar pipelines accelerate demand for modular AC conversion at commercial and industrial installations. CEA technical standards for grid-connectivity and BIS certification shape product qualification timelines. Gujarat's industrial zones concentrate agricultural irrigation farm deployments adopting solar-plus-storage configurations.
Australia
CEC accreditation requirements favor three-phase micro inverters for systems above 30 kW, creating qualified supplier bottlenecks. The National Electricity Market transmission infrastructure supports commercial solar acceleration. Queensland's cotton growing regions represent the fastest-growing agricultural application niche.
Three Phase Micro Inverters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power semiconductor sourcing. The installer channel fragments as regional distributors compete with direct-to-project procurement platforms. Three strategic archetypes dominate: certification-program operators anchoring installer loyalty, service-network dense European anchors, and price-performance competitors in emerging markets. Dominant competitive moves include installer certification program expansion and direct-to-integrator digital platform deployment.
Among California-based platform integrators, Enphase Energy exemplifies the certification-program archetype through installer accreditation investments. SMA Solar Technology AG represents the service-network dense European model with project pipeline anchoring. Growatt New Energy occupies the price-performance specialist position in emerging solar markets. These three companies illustrate the competitive positioning spectrum without exhausting the vendor base.
| Leading Market Players |
|---|
| Enphase Energy |
| Altenergy Power System |
| Darfon Electronics |
| Growatt New Energy |
| Chilicon Power |
| Hoymiles |
| Siemens |
| SMA Solar Technology AG |
| Ningbo Deye Inverter Technology |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian power semiconductor foundries is compressing input costs for inverter assemblers while simultaneously eroding supplier pricing power across all tier levels. This utilization dynamic forces manufacturers to absorb margin pressure or accelerate silicon carbide transitions to justify premium positioning.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales service bundling. Pricing pressure stems from string inverter substitution in sub-500 kW commercial segments, where centralized architectures undercut micro inverter proposals on upfront capital. Agricultural buyers exhibit highest price sensitivity, while commercial developers in California and Bavaria prioritize module-level monitoring compliance over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for Taiwanese and South Korean foundry relationships, easing working capital strain for inverter assemblers. Silicon carbide substrates and IGBT modules draw from concentrated East Asian sources, exposing procurement to single-source vulnerability during allocation cycles. Distribution runs through direct-to-project platforms that disintermediate traditional distributor layers, compressing channel margins while accelerating fulfillment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
String inverter substitution with module-level power electronics poses the most credible displacement threat, requiring incumbents to articulate monitoring and rapid shutdown compliance as non-negotiable value drivers.
For Market Incumbents: Entrench installer certification programs as switching-cost barriers against price-based competition from emerging Asian manufacturers. Deepen backward integration into silicon carbide sourcing to secure semiconductor allocation during supply crunches. Anchor service network density in Bavaria and California where permitting authorities recognize pre-approved installer credentials. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, as IEEE 1547-equivalent standards remain nascent and local integrators lack established vendor relationships. Agricultural irrigation farms in Gujarat and Queensland offer white-space expansion with solar-plus-storage configurations. Pursue CEC accreditation early to qualify for Australian systems above 30 kW. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid inverter sub-segments as silicon carbide MOSFETs collapse cost premiums against standard configurations. Acquisition targets should demonstrate firmware engineering clusters in Germany, California, or Taiwan with proprietary MPPT algorithm portfolios. Monitor battery attachment rate trajectories in Australian cotton regions as inflection indicators for storage-integrated product viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Transition | Enables 50 kHz switching frequencies that shrink magnetic component volume by 40% for space-constrained rooftops. |
| Installer Certification Expansion | Locks commercial integrators into single-vendor relationships resistant to price-based switching in California and Bavaria. |
| Direct-to-Project Platform Deployment | Disintermediates distributor markups while capturing recurring service revenue through remote monitoring subscriptions. |
| CEC Accreditation Investment | Creates qualified supplier bottlenecks for Australian commercial systems above 30 kW under Clean Energy Council requirements. |
| Smart Inverter Functionality Integration | Addresses German BNetzA reactive power support mandates that favor micro inverter architectures natively. |
Research Methodology
A standing panel of EPC contractors, commercial project developers, utility interconnection officers, and agricultural solar integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from IEEE standards documentation, CEA technical regulations, CEC accreditation databases, and customs trade records for power semiconductor imports. Bottom-up unit shipment estimates triangulated against top-down capacity deployment projections from national renewable energy agencies.
Scenario-bracketing framed demand trajectories across grid-tied, hybrid, off-grid, and smart inverter product categories, with end-user segmentation spanning commercial, agricultural, industrial, and residential tiers. CAGRs derived from fitted growth curves calibrated to historical installation data and policy target trajectories. Key inputs included battery attachment rate assumptions for agricultural segments and silicon carbide cost decline curves affecting hybrid configuration economics.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance availability or trade policy shifts impacting semiconductor tariffs would shift the trajectory. Forecasts reflect documented assumptions regarding IEEE 1547 implementation timelines and EU F-Gas Regulation enforcement stringency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
South America Battery Management System Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Global Gan Power Device Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Global Inverter Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Global Data Center Transformer Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Global Frequency Converter Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Power Diode Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Global Power Discrete and Modules Market