
 Space DC-DC Converters Market | 2026-2036
Space DC-DC Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Space DC-DC Converters Market Insights
The widening performance gap between radiation-hardened premium units and standard-grade commodity converters is repositioning procurement strategies across the space power electronics supply chain. Texas Instruments Incorporated leverages its vertically integrated fabrication footprint to sustain cost advantages in high-volume isolated converter programs. Vicor Corporation specializes in high-density modular architectures that dominate missions requiring minimal mass and volume budgets.
Space DC-DC converters are power conditioning devices that transform and regulate voltage levels across spacecraft electrical buses, typically operating at efficiencies exceeding 90 percent while withstanding total ionizing dose environments measured in kilorads. Their primary purpose is to deliver stable, noise-isolated power to sensitive avionics, propulsion controls, and communication payloads under extreme thermal cycling and vacuum conditions. Isolated converters occupy the largest share of current satellite system procurement due to their essential role in preventing ground loop failures and single-event latchup propagation. Pulse width modulation technology leads in launch vehicle applications where proven heritage and straightforward qualification paths reduce mission risk, while resonant converter architectures are gaining traction in space probe designs that demand higher switching frequencies to shrink magnetic component mass.
Defense Contractors face stringent qualification mandates from NASA's EEE-INST-002 specification and the European Space Agency's ECSS-Q-ST-60-02C standard, both of which dictate radiation hardness assurance testing protocols that extend development cycles and elevate non-recurring engineering costs. The Federal Aviation Administration's evolving commercial space launch licensing framework is reshaping how Commercial Space Firms certify power electronics for reusable launch platforms. Stakeholders must monitor how emerging wide-bandgap semiconductor qualification databases from NASA's Jet Propulsion Laboratory influence future derating requirements and supplier selection criteria.
Market Dynamics
Gallium nitride switching technology is compressing converter mass budgets while forcing incumbent silicon suppliers to accelerate radiation-hardened qualification timelines for next-generation satellite constellations.
Growth Catalysts
- LEO Constellation Deployment:Commercial space firms are procuring radiation-hardened power electronics at volumes previously reserved for defense programs, creating economies of scale in isolated converter manufacturing.
- NASA EEE-INST-002:The agency's updated parts management specification is streamlining qualification pathways for wide-bandgap semiconductors, reducing non-recurring engineering cycles for new entrants.
- Reusable Launch Platforms:The FAA's evolving commercial space launch licensing framework is certifying power electronics for flight-proven vehicles, expanding addressable demand beyond expendable systems.
Market Restraints
- Radiation-Hardened Substrate Costs:Silicon-on-insulator and silicon carbide wafers command premiums exceeding standard commercial grades by an order of magnitude, constraining price-competitive positioning.
- Domestic Fabrication Concentration:Trusted foundry capacity for space-qualified semiconductors clusters in the United States, exposing programs to single-source geopolitical risk.
- Total Ionizing Dose Limitations:Standard-grade gallium nitride devices face degradation thresholds below deep-space mission requirements, blocking adoption for outer planetary probes.
Strategic Opportunities
- Cislunar Infrastructure:NASA's Artemis program and commercial lunar lander initiatives are creating first-mover positions for high-efficiency resonant converters operating beyond geostationary orbit.
- On-Orbit Servicing:Satellite life-extension vehicles require modular power architectures that accommodate unknown legacy electrical bus configurations, favoring programmable digital control platforms.
- European Space Agency Partnership Frameworks:ESA's Boost! program and commercial cargo initiative are opening procurement channels for non-European converter suppliers meeting ECSS-Q-ST-60-02C standards.
Industry Challenges
- Radiation Effects Engineering Talent:The specialized knowledge base for single-event upset modeling and hardness assurance testing is concentrated among retiring defense-sector specialists, constraining program staffing.
- Heritage System Integration:New wide-bandgap designs must interface with legacy satellite electrical buses specified decades ago, requiring custom isolation architectures that erode mass and efficiency advantages.
- Qualification Database Gaps:NASA's Jet Propulsion Laboratory maintains limited radiation test data for emerging gallium nitride process nodes, forcing conservative derating that undermines performance claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space DC-DC Converters Market |
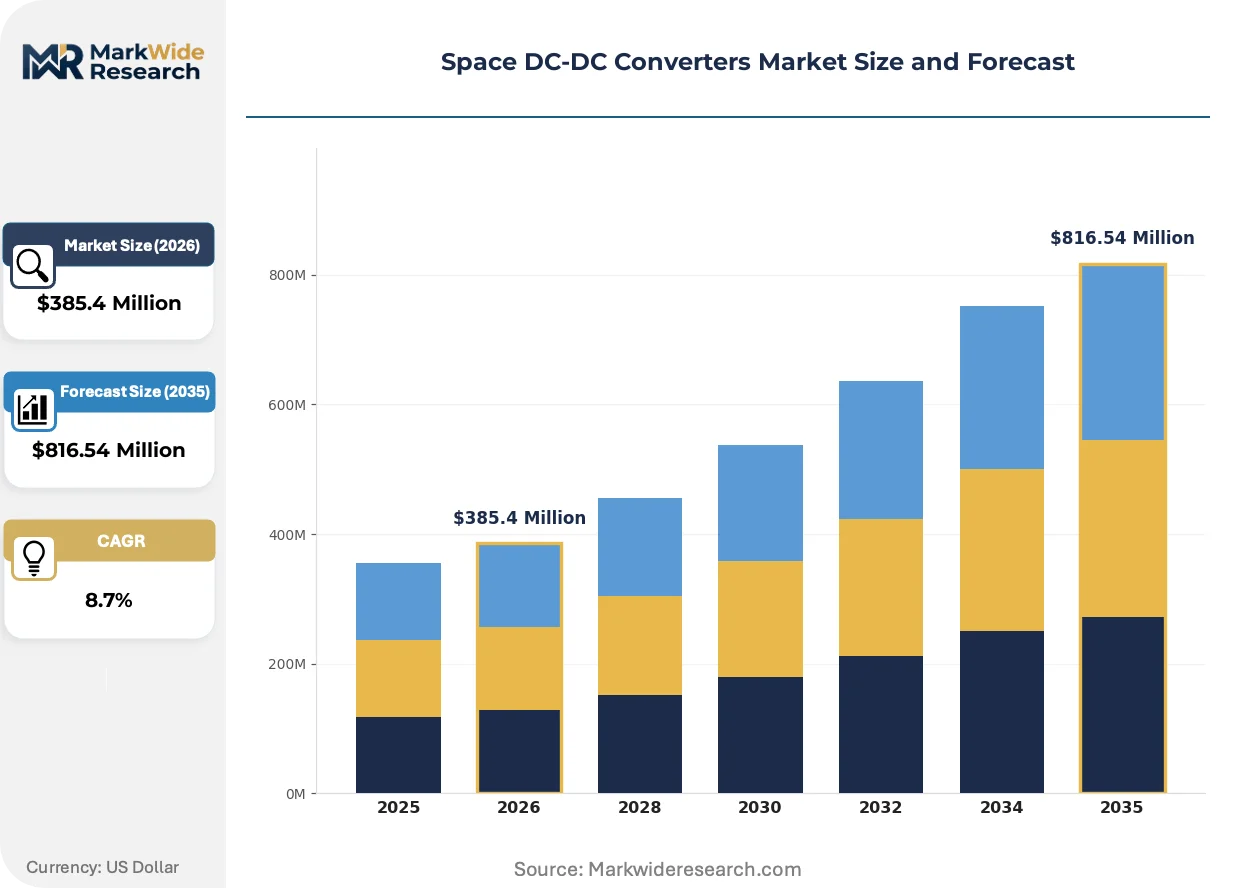
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated Converters, Non-Isolated Converters, Modular Converters, Switching Converters Technology: Pulse Width Modulation, Resonant Converters, Linear Regulators, Switched Capacitor Application: Satellite Systems, Launch Vehicles, Space Probes, Space Stations End User: Space Agencies, Defense Contractors, Commercial Space Firms, Research Institutions |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics, Infineon Technologies AG, Crane Aerospace and Electronics, Vicor Corporation, Thales Group, Advanced Energy, Airbus Group SE, Astronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space DC-DC Converters Market Trends and Innovations
Power electronics architectures are bifurcating between heritage-proven pulse width modulation systems and experimental resonant topologies optimized for megaconstellation economics.
Resonant converter architectures employing zero-voltage switching are expanding into small satellite platforms where magnetic component mass reduction outweighs heritage risk tolerance. Constellation operators are adopting these designs for initial deployment tranches, accepting shorter operational lifetimes in exchange for launch cost savings. The technology is expanding into the sub-500 watt segment previously dominated by flyback converters, compressing supplier margins on established product lines.
The European Space Agency's updated ECSS-Q-ST-60-02C standard is mandating enhanced single-event latchup screening for all switching power supplies on crewed missions. This regulatory revision is forcing converter manufacturers to redesign control ICs with redundant shutdown circuitry, extending development timelines by 12-18 months. Deep-space probe programs are absorbing these costs while commercial LEO operators are deferring compliance to subsequent design iterations.
Prime contractors are unbundling power subsystem procurement from satellite platform integration, creating direct commercial relationships between converter suppliers and constellation operators. This disintermediation is displacing traditional tiered supply arrangements where platform manufacturers specified approved vendor lists. The shift is most visible in the United States, where SpaceX and Amazon's Project Kuiper are negotiating volume contracts directly with radiation-hardened power electronics specialists.
Space DC-DC Converters Market Segmentation
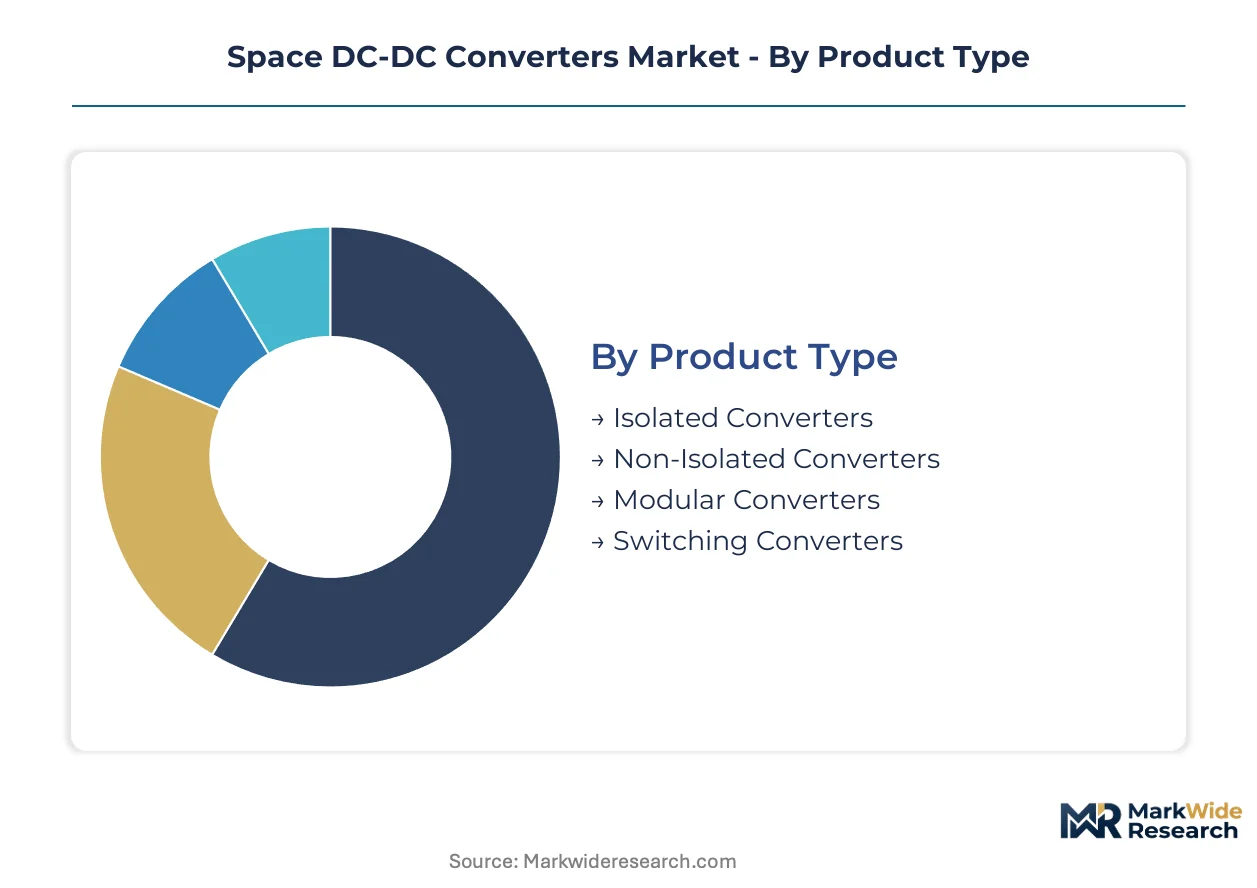
Segmentation in the Space DC-DC Converters Market reveals how procurement priorities diverge across mission profiles. Radiation hardness requirements, mass constraints, and qualification heritage drive distinct purchasing behaviors that suppliers must address through specialized product architectures.
Product Type:
Buyers differentiate primarily by electrical isolation requirements and integration complexity rather than unit cost.
- Isolated Converters:These units incorporate galvanic isolation barriers that prevent ground loop failures and single-event latchup propagation across spacecraft electrical buses. NASA and SpaceX anchor procurement volumes in the United States, where constellation deployment schedules demand qualified suppliers with proven heritage.
- Modular Converters:Vicor Corporation's high-density brick architectures exemplify this segment, enabling rapid reconfiguration across multiple bus voltages without custom redesign. Commercial space firms in the United States favor these for iterative satellite generations where electrical specifications evolve between launches.
- Non-Isolated Converters:Point-of-load regulators serving distributed power architectures on compact CubeSat platforms.
- Switching Converters:General-purpose buck-boost topologies for secondary voltage rails in avionics subsystems.
Isolated converters lead volumes today; modular converters are gaining share fastest.
Technology:
Technology selection tracks mission risk tolerance against switching frequency and efficiency targets.
- Pulse Width Modulation:Heritage-proven fixed-frequency architectures dominate launch vehicle applications where straightforward qualification paths reduce mission risk. Defense contractors in the United States specify these for programs requiring traceable test data under NASA's EEE-INST-002 specification.
- Resonant Converters:Zero-voltage switching topologies shrink magnetic component mass through elevated switching frequencies. European Space Agency probe programs and commercial LEO operators accept shorter operational lifetimes to capture launch cost savings from reduced payload mass.
- Linear Regulators:Low-noise solutions for sensitive analog instrumentation on deep-space missions.
- Switched Capacitor:Charge-pump architectures eliminating magnetic elements in radiation-tolerant digital power management.
Pulse width modulation retains the largest installed base; resonant topologies show the steepest expansion trajectory.
Application:
Application segmentation reflects fundamental differences in operating duration, radiation environment, and thermal cycling severity.
- Satellite Systems:Constellation operators procure isolated converters at volumes previously reserved for defense programs, creating manufacturing economies of scale. The United States concentrates demand through SpaceX's Starlink and Amazon's Project Kuiper procurement.
- Launch Vehicles:Reusable platforms require power electronics certified under the FAA's evolving commercial space launch licensing framework. Texas Instruments leverages vertically integrated fabrication to sustain cost advantages in these high-volume isolated converter programs.
- Space Probes:Outer planetary missions demand total ionizing dose tolerance exceeding standard-grade gallium nitride capabilities.
- Space Stations:Crewed platforms require enhanced single-event latchup screening under ECSS-Q-ST-60-02C revisions.
Satellite systems dominate current procurement; launch vehicles are expanding most quickly.
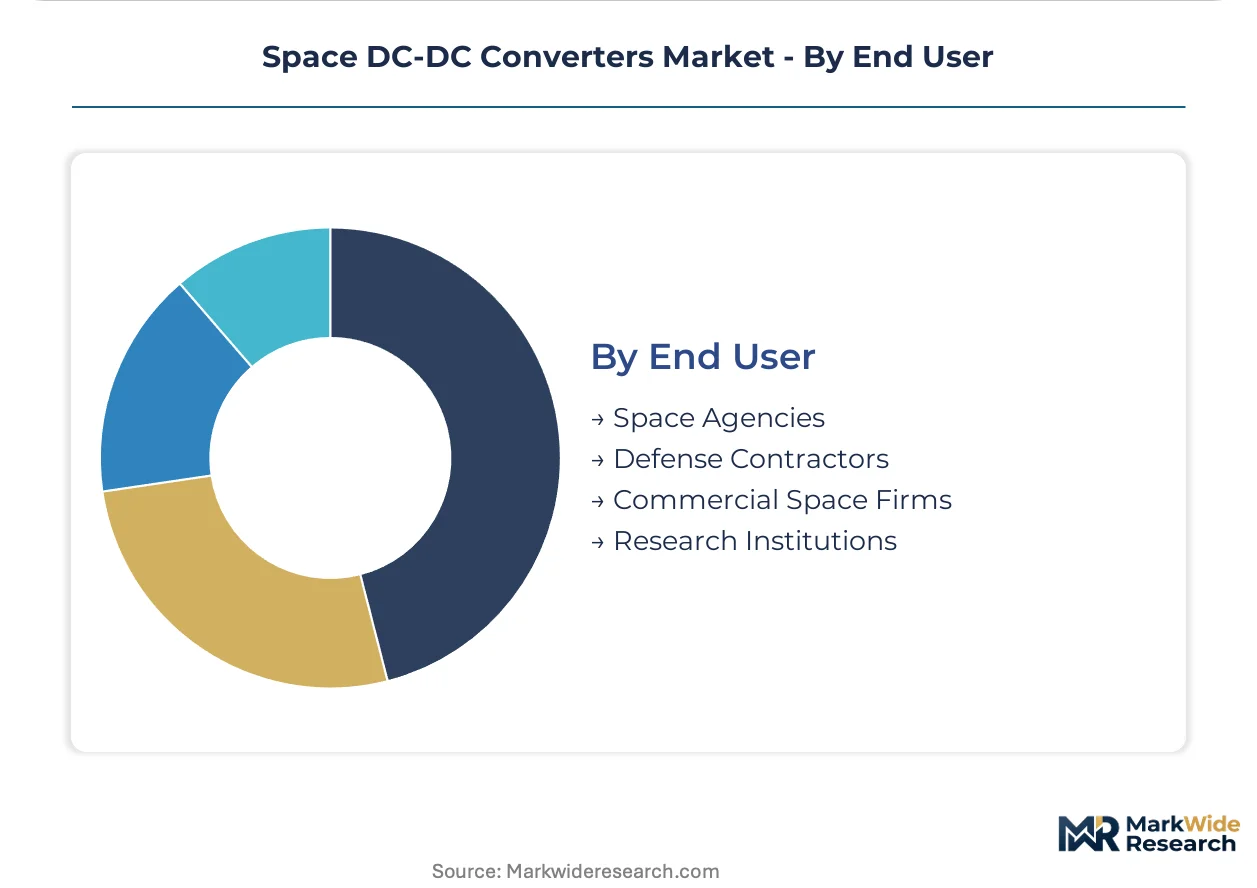
End User:
End user categories separate procurement based on qualification stringency, volume scale, and supplier relationship models.
- Commercial Space Firms:SpaceX and Amazon negotiate volume contracts directly with radiation-hardened power electronics specialists, displacing traditional tiered supply arrangements. These buyers prioritize mass reduction and launch cost savings over maximum operational lifetime.
- Defense Contractors:Northrop Grumman and Lockheed Martin face stringent NASA EEE-INST-002 and ECSS-Q-ST-60-02C mandates that extend development cycles and elevate non-recurring engineering costs. Their procurement emphasizes traceable radiation hardness assurance testing.
- Space Agencies:NASA and ESA anchor demand for deep-space qualified products with extended operational lifetimes.
- Research Institutions:University-led CubeSat programs driving demand for commercial-off-the-shelf converter evaluation.
Defense contractors maintain the largest qualified supplier relationships; commercial space firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces all other nations in space DC-DC converter procurement volume, though France and Germany maintain critical positions in European qualification standards and radiation-hardened semiconductor fabrication.
United States
NASA's Artemis program and SpaceX's Starlink constellation drive procurement of isolated converters at defense-scale volumes. The FAA's commercial space launch licensing framework certifies power electronics for reusable platforms, expanding addressable demand beyond expendable systems. Houston and Los Angeles anchor the largest concentration of prime contractors negotiating direct supplier relationships.
France
Thales Group and Airbus Defence and Space anchor demand for ECSS-Q-ST-60-02C qualified converters across European probe and crewed missions. The country's national space regulator enforces stringent single-event latchup screening mandates that extend development cycles. Toulouse hosts the densest cluster of satellite platform integrators sourcing radiation-hardened power electronics.
Germany
Infineon Technologies AG drives silicon carbide and gallium nitride substrate development for next-generation switching applications. The country's standards body influences derating requirements for wide-bandgap semiconductors across ESA member programs. Bavaria concentrates trusted foundry capacity for space-qualified wafers, exposing programs to single-source geopolitical risk.
Japan
JAXA's deep-space probe programs demand total ionizing dose tolerance exceeding standard-grade gallium nitride capabilities. METI coordinates public-private partnerships to accelerate radiation-hardened qualification timelines for domestic semiconductor suppliers. Nagoya and Tokyo host the primary clusters of precision magnetic component manufacturers serving resonant converter architectures.
United Kingdom
Surrey Satellite Technology and Airbus Defence and Space UK procure modular converters for iterative small satellite generations. The UK Space Agency's regulatory framework aligns with ECSS standards while permitting faster commercial qualification paths for LEO operators. Harwell and Stevenage concentrate payload integrators requiring programmable digital control platforms for on-orbit servicing missions.
Space DC-DC Converters Market Competitive Landscape
Top-tier vendors anchor radiation-hardened qualification heritage, while mid-tier specialists compete on mass reduction and switching frequency performance. The vendor base stratifies across three tiers: defense-heritage primes with NASA EEE-INST-002 traceability, commercial space-focused suppliers optimizing for constellation economics, and emerging wide-bandgap semiconductor specialists. Two dominant competitive moves define current positioning: backward integration into captive wafer fabrication to secure trusted foundry access, and strategic partnerships with constellation operators to disintermediate traditional platform manufacturer procurement channels.
Within the defense-heritage tier, Texas Instruments Incorporated and STMicroelectronics exemplify vertically integrated fabrication strategies that sustain cost advantages in high-volume programs. Vicor Corporation occupies a position among modular architecture specialists, representing the density-optimized approach that dominates missions with minimal mass and volume budgets. These three anchors illustrate how supplier selection criteria diverge between heritage-risk-averse defense contractors and mass-constrained commercial operators.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics |
| Infineon Technologies AG |
| Crane Aerospace and Electronics |
| Vicor Corporation |
| Thales Group |
| Advanced Energy |
| Airbus Group SE |
| Astronics Corporation |
| Others |
Pricing and Supply Chain Analysis
NASA's EEE-INST-002 radiation hardness specification gates qualified supply access and anchors premium-tier pricing power for defense-heritage converters, while commercial LEO operators without crewed mission mandates capture standard-grade alternatives at compressed margins.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for radiation-hardened converters as SpaceX and Amazon's Project Kuiper negotiate volume contracts directly with suppliers. Three-tier pricing structure across radiation-hardened premium, mission-assured standard, and commercial-off-the-shelf economy levels separates defense contractors prioritizing traceable qualification from constellation operators optimizing launch cost. Cost compression in the standard tier is intensifying because gallium nitride switching technology displaces silicon incumbent pricing. Commercial space firms exhibit highest price sensitivity; defense contractors absorb premium tiers for heritage assurance.
Supply Chain Analysis
Freight costs for space-qualified semiconductor substrates remain secondary to foundry access premiums, with logistics concentrated on secure transport of silicon-on-insulator and silicon carbide wafers from fabrication to qualification facilities. Supply concentrates in the United States, Germany, and France, where trusted foundry capacity clusters for radiation-hardened processing. Raw material dependencies center on gallium nitride epitaxy, precision magnetic cores, and ceramic substrate materials. Single-source vulnerability pervades domestic fabrication concentration for space-grade semiconductors. Distribution runs through prime contractor procurement channels and increasingly direct constellation operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States defense-heritage qualification costs and European commercial fast-track pathways under ESA's evolving ECSS frameworks.
For Market Incumbents: Acquire radiation test database assets from NASA's Jet Propulsion Laboratory and ESA qualification archives to accelerate wide-bandgap semiconductor derating timelines. Consolidate backward integration into captive silicon carbide substrate production before gallium nitride capacity shortages constrain output. Defend against modular converter specialists by embedding digital programmability into isolated converter architectures. For New Entrants and Emerging Players: Launch via direct commercial relationships with constellation operators disintermediating traditional platform manufacturer procurement channels. Target the sub-500 watt resonant converter segment where magnetic component mass reduction outweighs heritage risk tolerance for LEO operators. Pursue ESA Boost! program partnership frameworks as the fastest qualification pathway for non-European suppliers. For Investors and Strategic Acquirers: Roll-up economics work for radiation-hardened power electronics specialists because qualification database scarcity and retiring defense-sector engineering talent concentrate value in acquired expertise. Long-term viability centers on wide-bandgap semiconductor transition completion and cislunar infrastructure positioning. Watch NASA Artemis program procurement acceleration as the inflection signal for deep-space converter demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Fabrication | Captive gallium nitride epitaxy capacity secures supply for SpaceX and defense prime contracts. |
| Resonant Converter Architecture Development | Zero-voltage switching topologies capture Amazon Project Kuiper mass-constrained procurement. |
| ECSS-Q-ST-60-02C Certification Investment | European crewed mission qualification opens ESA Boost! program supplier channels. |
| Digital Programmable Control Platform Launch | Reconfigurable architectures address on-orbit servicing satellite life-extension vehicle demand. |
| Radiation Test Database Partnership | NASA JPL collaboration accelerates gallium nitride derating for deep-space probe adoption. |
Research Methodology
Direct dialogue with satellite power subsystem engineers, constellation procurement directors, radiation effects specialists, and defense prime contractor supply chain managers grounded qualitative assessment, combined with secondary validation against NASA EEE-INST-002 specification documents, ESA ECSS standards, FAA commercial space launch licensing records, and semiconductor foundry capacity disclosures. Bottom-up unit demand modeling triangulated against top-down addressable market sizing.
Segment-level outputs across isolated, modular, and non-isolated converter architectures; pulse width modulation and resonant switching technologies; satellite systems, launch vehicle, and space probe applications; and commercial space firm, defense contractor, and space agency end users were generated over the projection horizon. CAGRs derived from volume trajectory analysis incorporating LEO constellation deployment schedules, Artemis program procurement timelines, and wide-bandgap semiconductor adoption curves.
Several conditions sit outside the modeled scope, including geopolitical disruption to trusted foundry access, unanticipated radiation hardness failures in gallium nitride process nodes, and regulatory acceleration of commercial crewed mission standards. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
AC Voltage Transducer Market
Power Systems
Central Battery Systems Market
Power Systems
Shunt Capacitor Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Battery Racks Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Global Gan Power Device Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Battery Charge Controller Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Generator Circuit Breaker Market