
 Silicon-Controlled Rectifier (SCR) Market | 2026-2036
Silicon-Controlled Rectifier (SCR) Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon-Controlled Rectifier (SCR) Market Analytics
The premium-commodity split in SCR supply is shifting as high-reliability phase-control devices for traction and grid applications command widening margin premiums over standard consumer-grade dimmers. Infineon Technologies leverages its SiC-adjacent R&D pipeline to sustain technology leadership in high-voltage industrial segments. WeEn Semiconductor anchors its position through captive wafer capacity and dominant share in Chinese appliance motor-control supply chains. Vishay competes aggressively on cost in mature light-control applications where price sensitivity limits differentiation.
A silicon-controlled rectifier is a four-layer p-n-p-n semiconductor switching device that gates current flow through a control electrode, typically handling 600V to 6.5kV blocking voltages and currents from fractions of an ampere to thousands of amperes depending on wafer geometry and packaging. Its primary industrial purpose is precise power modulation in AC circuits, enabling phase-angle control for motor speed regulation, heating element management, and inverter bridge commutation. Phase control products occupy the largest revenue pool due to entrenched industrial motor-drive demand, while microcontroller-based technology segments are expanding fastest as digital gate drivers displace analog triggering in precision heating and renewable energy conversion systems. Voltage regulators retain stable but slower growth, constrained by maturity in legacy automotive alternator applications.
China's MIIT enforces GB standards for power semiconductor reliability that shape domestic procurement specifications and create compliance barriers for non-certified imports. The EU F-Gas Regulation and REACH chemical restrictions indirectly elevate SCR demand by accelerating electric heating and heat-pump deployments that rely on solid-state power control. India's BIS certification mandates for industrial electrical equipment are tightening product entry requirements across South Asian project markets. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving efficiency standards redirect procurement toward digitally controlled, higher-voltage-rated devices.
Market Dynamics
China's MIIT-enforced GB standards for power semiconductor reliability are forcing a bifurcation between certified domestic supply and import-restricted project markets, concentrating procurement authority in East Asian manufacturing clusters that control inverter and motor-drive production.
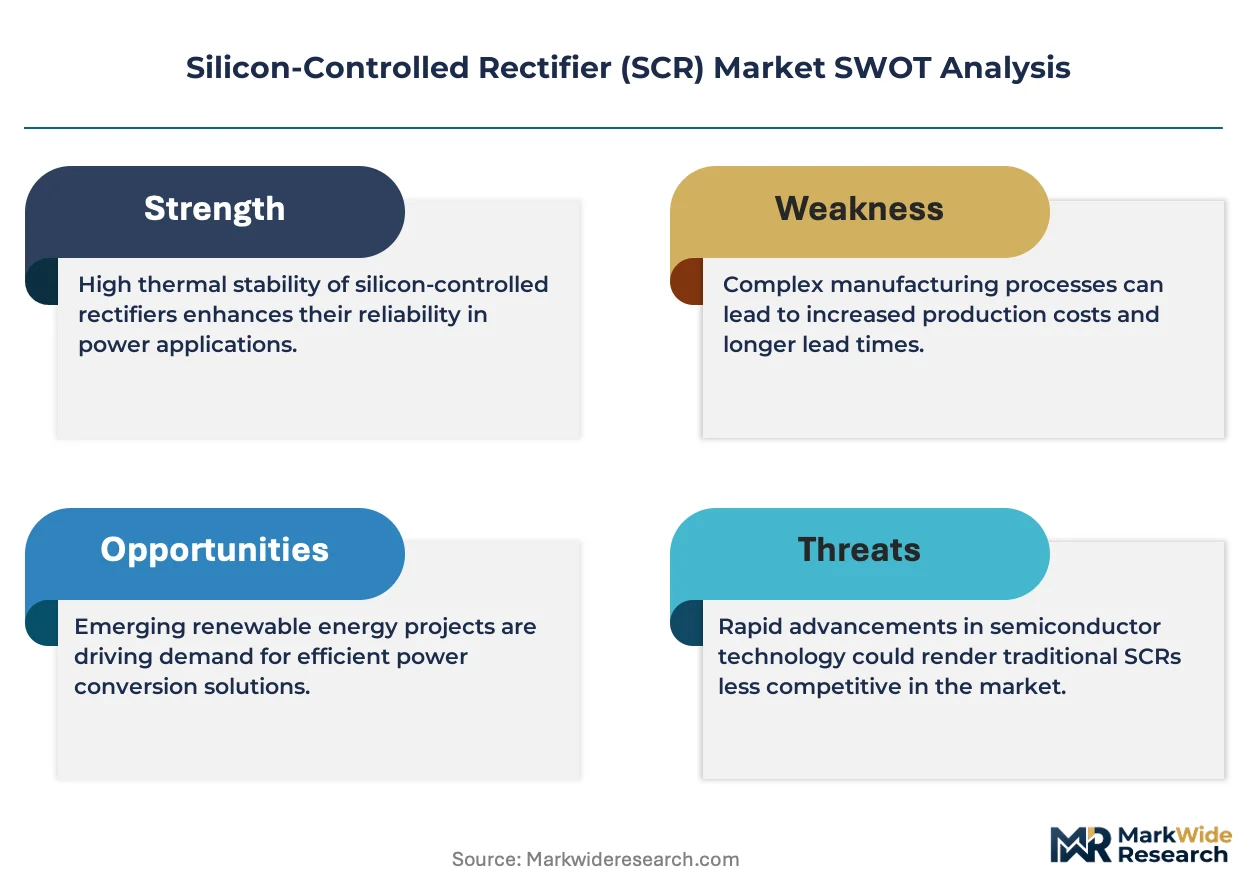
Growth Catalysts
- Industrial motor-drive retrofit cycles:Aging factory equipment across China's Pearl River Delta and South Korea's Gyeonggi Province requires phase-control upgrades to meet stricter efficiency mandates.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases accelerate electric heat-pump deployments that depend on solid-state power modulation for compressor control.
- Silicon carbide R&D spillover:Adjacent wide-bandgap semiconductor development is improving gate-driver precision for high-voltage SCR applications in traction systems.
Market Restraints
- Raw silicon wafer cost volatility:Polysilicon price swings from Xinjiang-based ingot production constrain margin stability for standard-grade phase-control devices.
- Supply concentration in East Asian foundries:Captive wafer capacity at Chinese and South Korean integrated manufacturers limits second-source availability for European project contractors.
- IGBT substitution in medium-voltage motor drives:Insulated-gate bipolar transistors are capturing share in variable-frequency applications above 400V where SCRs previously dominated.
Strategic Opportunities
- India's BIS certification pipeline:Tightening industrial electrical equipment standards create first-mover advantage for suppliers establishing certified local testing partnerships.
- Digital gate-driver convergence:Microcontroller-based triggering architectures enable precision heating applications that analog systems cannot serve.
- Carbon-border adjustment preparation:EU importers are pre-qualifying higher-efficiency SCR variants to avoid future tariff exposure on carbon-intensive electromechanical alternatives.
Industry Challenges
- Legacy analog design expertise scarcity:Semiconductor engineering programs emphasize digital IC development, shrinking the talent pool for discrete power device optimization.
- Multi-standard certification timelines:Simultaneous GB, BIS, and IEC qualification requirements extend product launch cycles by 8-14 months for cross-border suppliers.
- System integration complexity:Digital gate drivers require firmware compatibility testing with existing PLC architectures in retrofitted industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon-Controlled Rectifier (SCR) Market |
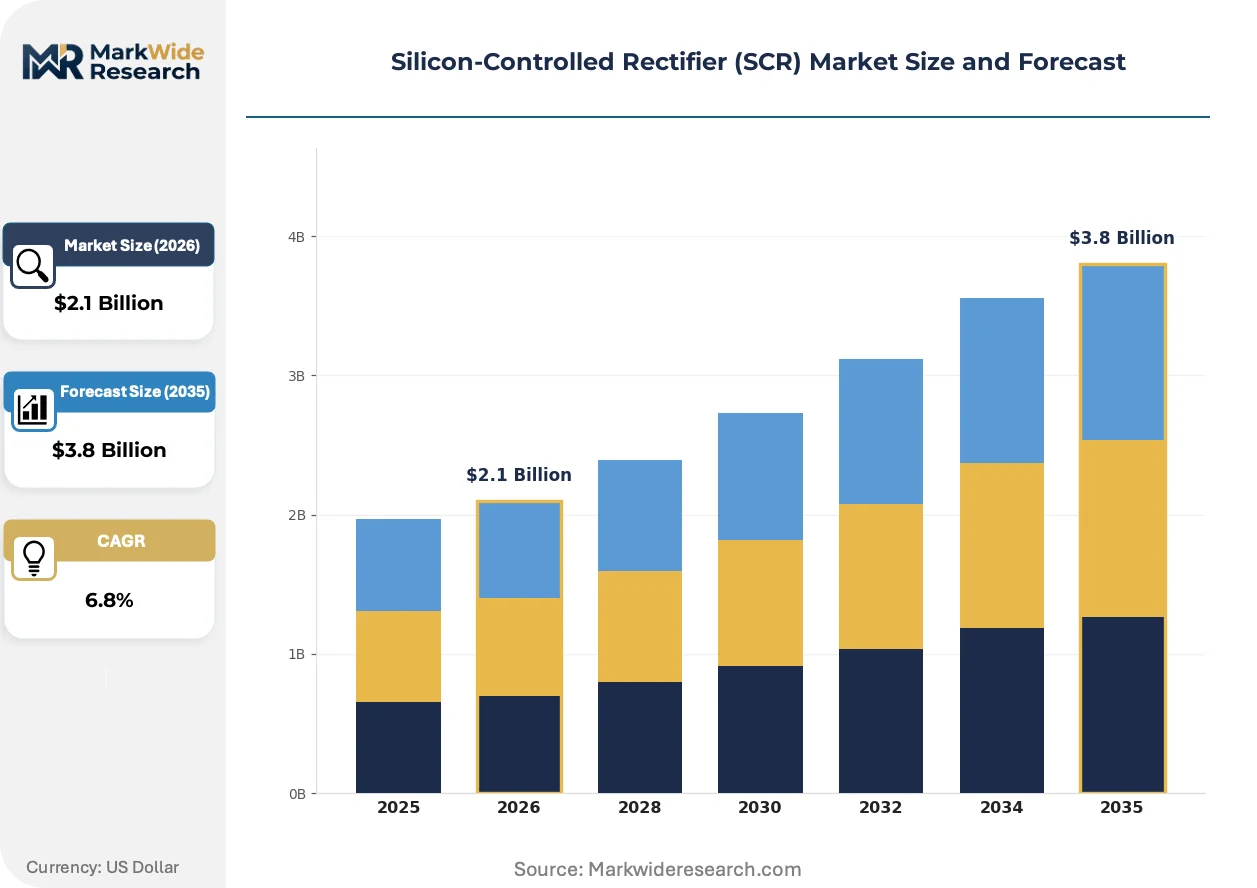
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phase Control, Dimmers, Inverters, Voltage Regulators End User: Industrial, Automotive, Consumer Electronics, Renewable Energy Application: Power Management, Motor Control, Light Control, Heating Systems Technology: Analog Control, Digital Control, Microcontroller-Based, Hybrid Systems |
| Companies Covered | Vishay, Microchip Technology, STMicroelectronics, Semikron, IXYS, Infineon Technologies, WeEn Semiconductor, Crydom, Littelfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon-Controlled Rectifier (SCR) Market Evolving Landscape
Power semiconductor architecture is absorbing digital control methods that were previously confined to signal-processing applications, compressing the performance gap between discrete analog switches and intelligent power modules.
Silicon carbide-adjacent R&D is absorbing engineering resources from traditional silicon device teams, redirecting talent toward hybrid Si-SiC module development. Traction inverter manufacturers in Germany and Japan are pilot-testing these configurations for 3.3kV rail applications. The structural consequence is that pure-silicon SCR development is concentrating in cost-optimized appliance and lighting segments where voltage ratings stay below 800V.
China's MIIT is tightening GB/T reliability standards for power semiconductors used in grid-tied inverters, mandating extended temperature cycling tests that disqualify consumer-grade packaging. Domestic module assemblers in Shenzhen and Xi'an are redesigning thermal interfaces to meet these specifications. European importers face compliance barriers unless they establish local certification partnerships or accept 6-9 month qualification delays.
Factory procurement departments are consolidating phase-control device purchasing through direct foundry relationships, bypassing traditional distribution channels for high-volume motor-drive contracts. This disintermediation is most visible in South Korea's Gyeonggi semiconductor cluster, where inverter OEMs negotiate wafer-level supply agreements. Distributors are responding by unbundling technical support services and charging separate fees for application engineering that was previously subsidized by product margins.
Silicon-Controlled Rectifier (SCR) Market Segmentation
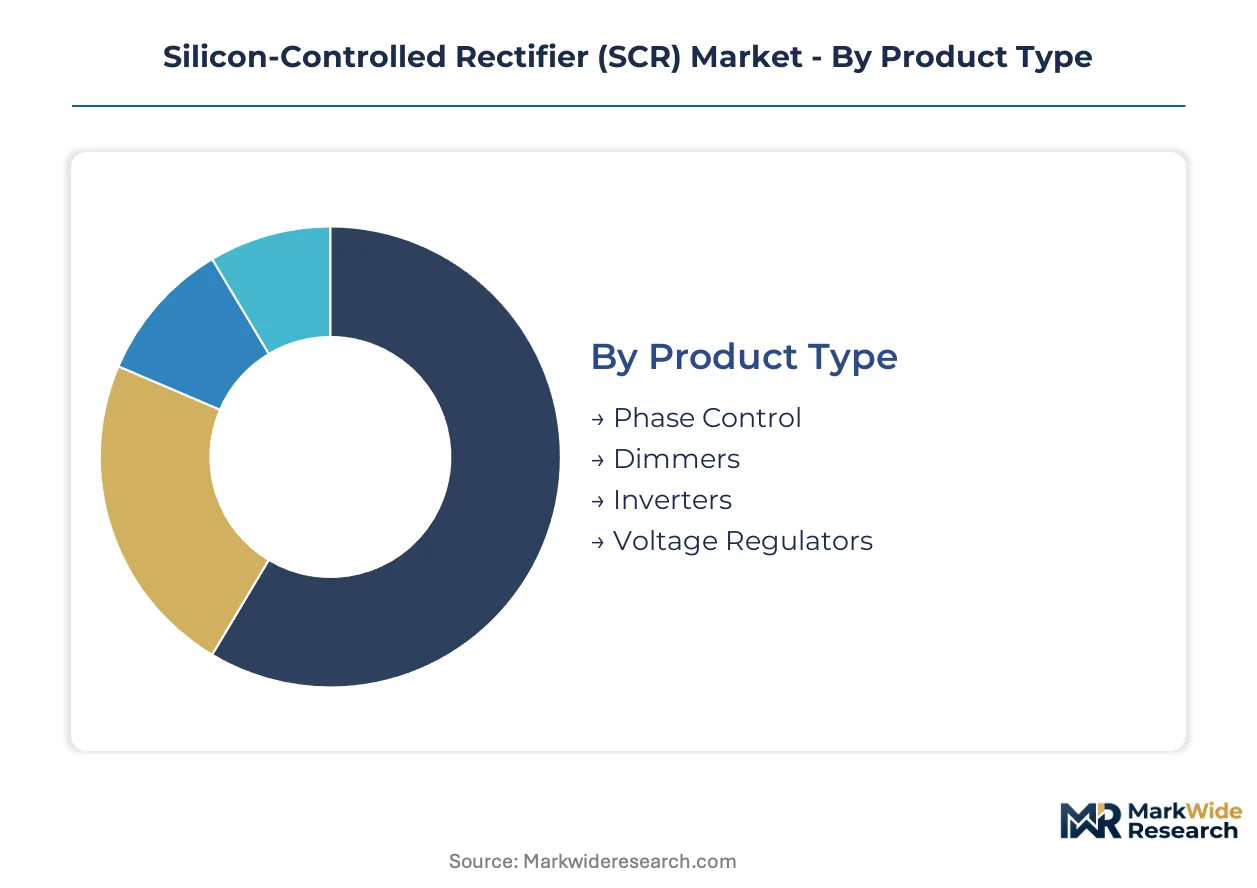
SCR procurement patterns diverge sharply across certification regimes, with GB-rated industrial devices commanding margin premiums over consumer-grade alternatives. Phase-control specifications for traction systems face MIIT-mandated thermal cycling tests that analog dimmer products never encounter. Segmentation strategy must align product roadmaps with the specific approval burdens each end-use imposes.
Product Type:
GB standards from China's MIIT and IEC qualifications impose tiered certification burdens that segment pricing and sourcing strategies across product categories.
- Phase Control:Four-layer p-n-p-n devices handling 600V to 6.5kV blocking voltages enable precise AC power modulation for industrial motor speed regulation. Demand concentrates in Shenzhen and Seoul manufacturing clusters where inverter OEMs retrofit aging factory equipment to meet China's dual carbon efficiency mandates.
- Inverters:Bridge commutation-grade SCRs with extended temperature cycling qualifications serve grid-tied renewable energy conversion systems. Procurement from European project contractors faces 6-9 month delays unless suppliers establish local certification partnerships with Xi'an or Shenzhen module assemblers.
- Dimmers:Standard-grade devices below 800V serve mature lighting control applications with minimal regulatory overhead.
- Voltage Regulators:Legacy automotive alternator applications face slow growth as electrification shifts vehicle electrical architectures.
Phase Control sits at the top of the volume ranking, with Inverters climbing the fastest.
End User:
Customer-type concentration determines margin structure, with captive foundry relationships in East Asian manufacturing clusters displacing traditional distribution channels.
- Industrial:Motor-drive OEMs in South Korea's Gyeonggi Province negotiate direct wafer-level supply agreements for phase-control devices. These procurement patterns bypass distributors and compress margins for standard-grade products while sustaining premiums for high-reliability traction specifications.
- Renewable Energy:Grid-tied inverter manufacturers require GB/T-qualified thermal interface designs that domestic Chinese assemblers in Xi'an now specialize in producing. European importers pre-qualify higher-efficiency variants to avoid future carbon-border tariff exposure.
- Automotive:Traction inverter pilots in Germany and Japan test hybrid Si-SiC modules for 3.3kV rail applications.
- Consumer Electronics:Appliance motor-control supply chains in China favor cost-optimized devices from captive wafer capacity.
Industrial commands the largest revenue pool, with Renewable Energy expanding most rapidly.
Application:
Functional use cases map directly to voltage rating requirements and corresponding certification complexity.
- Power Management:Solid-state switching applications replacing electromechanical relays under China's stricter industrial efficiency mandates. Phase-angle control circuits in factory automation require MIIT-compliant reliability testing that consumer applications bypass entirely.
- Motor Control:Variable-frequency drives above 400V face IGBT substitution pressure, compressing SCR addressable market in medium-voltage segments. Below 400V, digital gate drivers displace analog triggering in precision applications.
- Heating Systems:Electric heat-pump compressor modulation benefits from EU F-Gas Regulation restrictions on fluorinated greenhouse gases.
- Light Control:Mature residential and commercial dimming applications with price-sensitive procurement through traditional distribution.
Power Management leads by installed base, with Heating Systems gaining share fastest.
Technology:
Control architecture selection determines firmware compatibility requirements and talent acquisition strategies for engineering teams.
- Microcontroller-Based:Digital triggering architectures enable precision heating and renewable energy conversion applications that analog systems cannot serve. These systems require PLC firmware compatibility testing in retrofitted industrial facilities, extending integration timelines.
- Digital Control:Gate-driver precision improvements from adjacent silicon carbide R&D pipelines benefit high-voltage traction applications. Engineering talent scarcity for discrete power optimization constrains development velocity.
- Analog Control:Legacy triggering circuits face shrinking engineering program emphasis and declining talent pools.
- Hybrid Systems:Si-SiC module configurations piloted for 3.3kV rail traction inverters absorb R&D resources from pure-silicon development.
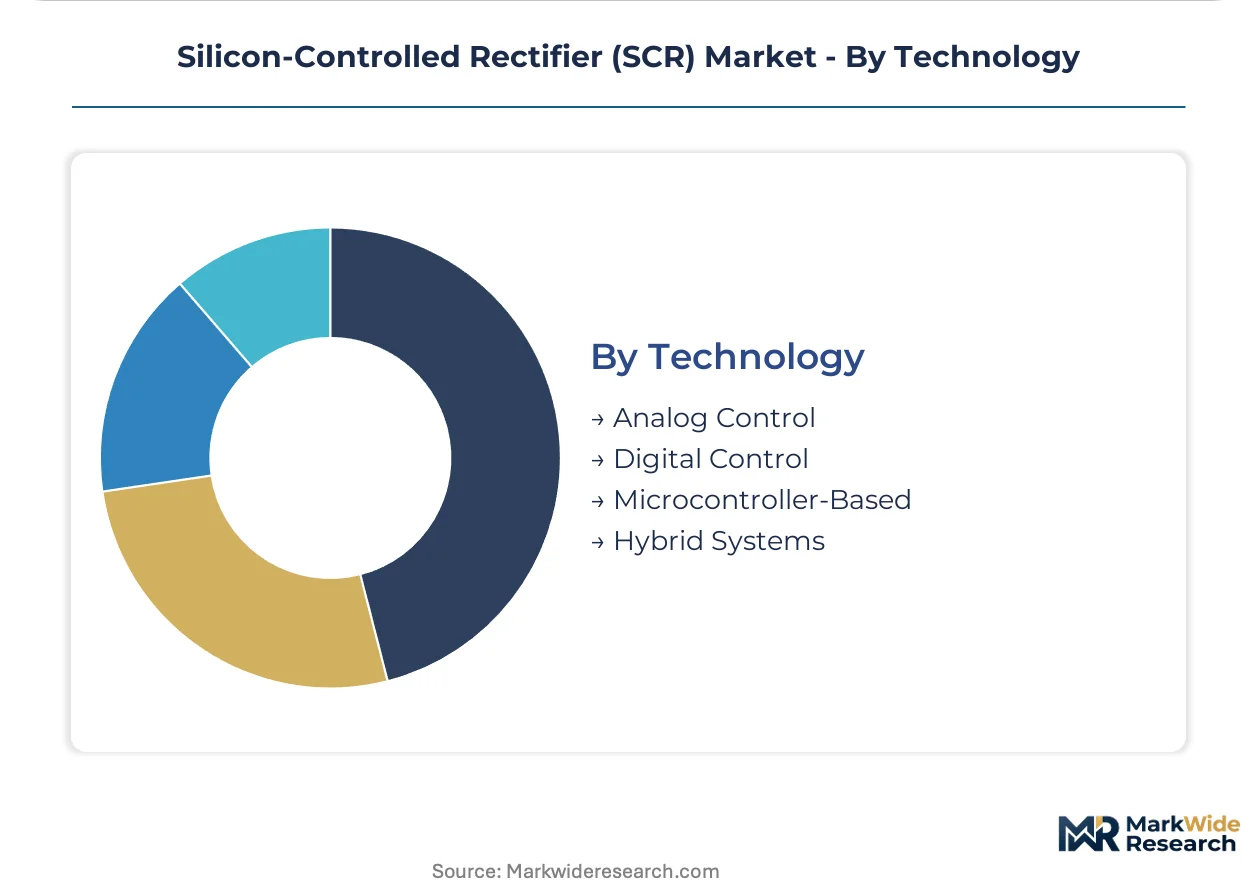
Microcontroller-Based holds the largest current share, with Digital Control advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools for discrete power device design concentrate in East Asian manufacturing clusters and select European industrial regions. These workforce concentrations anchor procurement authority for high-voltage phase-control applications.
China
MIIT-enforced GB/T reliability standards for grid-tied inverters mandate extended temperature cycling tests that reshape domestic supply chains. Shenzhen and Xi'an module assemblers redesign thermal interfaces to capture certified procurement flows. Pearl River Delta factories retrofit aging motor-drive equipment under dual carbon efficiency mandates, concentrating demand for phase-control devices.
South Korea
Gyeonggi Province inverter OEMs negotiate direct wafer-level supply agreements that bypass traditional distribution channels. The country's industrial efficiency regulations accelerate replacement of electromechanical relays with solid-state switching in factory automation. Seoul-area manufacturing clusters dominate procurement for renewable energy conversion systems.
Germany
Traction inverter manufacturers pilot-test hybrid Si-SiC module configurations for 3.3kV rail applications. EU F-Gas Regulation restrictions on fluorinated greenhouse gases accelerate electric heat-pump deployments requiring precise compressor power modulation. Bavarian and Baden-Württemberg industrial regions absorb adjacent wide-bandgap semiconductor R&D spillover.
India
BIS certification mandates for industrial electrical equipment tighten product entry requirements across South Asian project markets. Maharashtra and Gujarat manufacturing corridors require qualified local testing partnerships to avoid extended qualification timelines. Domestic appliance motor-control supply chains favor cost-optimized devices from established certification pipelines.
Japan
METI-supported R&D programs redirect engineering talent toward hybrid silicon-carbide development for next-generation traction systems. Kansai and Chubu industrial regions maintain specialized expertise in high-voltage discrete power device optimization. Automotive electrification shifts vehicle electrical architectures away from legacy voltage regulator applications.
Silicon-Controlled Rectifier (SCR) Market Competitive Landscape
Top-tier vendors anchor premium-grade phase-control and traction applications, while commodity-grade suppliers compete on cost in mature lighting and appliance segments. The vendor base stratifies across three tiers: integrated manufacturers with captive wafer capacity, fabless specialists leveraging foundry partnerships, and distributors unbundling technical support services. Two dominant competitive moves define current positioning: direct foundry relationships that disintermediate traditional channels, and certification partnerships that accelerate market access in regulated jurisdictions.
Among European-integrated manufacturers, Infineon Technologies and STMicroelectronics exemplify the premium-tier archetype through SiC-adjacent R&D pipelines and high-voltage industrial segment focus. WeEn Semiconductor anchors the captive-capacity tier with dominant positioning in Chinese appliance motor-control supply chains. These three companies represent distinct strategic postures: technology leadership through adjacent wide-bandgap development, scale-driven cost optimization through backward integration into wafer supply, and regional market capture through compliance-first certification strategies.
| Leading Market Players |
|---|
| Vishay |
| Microchip Technology |
| STMicroelectronics |
| Semikron |
| IXYS |
| Infineon Technologies |
| WeEn Semiconductor |
| Crydom |
| Littelfuse |
| Others |
Value Network & Pricing Analysis
Digital gate-driver convergence in phase-control applications is compressing analog design margins while concentrating procurement authority among East Asian inverter OEMs with direct foundry relationships. This technology transition simultaneously elevates firmware-integration costs for premium-tier devices and erodes price premiums for legacy analog variants.
Pricing Analysis
Bundled application engineering services are unbundling from product margins as distributors charge separate fees for technical support previously subsidized by hardware sales. Pricing stratifies across MIIT-certified industrial, IEC-qualified renewable energy, and unregulated consumer tiers. Cost compression in standard-grade dimmer segments stems from WeEn Semiconductor's captive wafer capacity in Chinese appliance supply chains. Consumer lighting applications exhibit highest price sensitivity, while traction-grade phase-control devices for rail systems command sustained premiums due to thermal cycling qualification barriers.
Supply Chain Analysis
Refurbishment flows for industrial motor-drive equipment concentrate secondary demand in China's Pearl River Delta, where factory retrofit cycles extend effective device lifecycles. Raw polysilicon supply draws from Xinjiang-based ingot production, with packaging materials and ceramic substrates sourced from Japanese and German specialty suppliers. Single-source vulnerability pervades high-voltage wafer fabrication, where South Korean and Chinese integrated manufacturers control captive capacity. Distribution runs through direct foundry relationships for high-volume contracts, with residual channel volume flowing via technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCR market represents a late-cycle quality story where procurement is concentrating toward GB-certified industrial specifications under China's dual carbon efficiency mandates.
For Market Incumbents: Deploy backward integration into ceramic substrate supply to secure thermal interface material availability against IGBT substitution pressure in medium-voltage motor drives. Deepen certification partnerships with Xi'an module assemblers to compress MIIT qualification timelines from nine months toward six. Channel control through direct wafer-level agreements with Gyeonggi Province inverter OEMs sustains margin premiums against distributor disintermediation. For New Entrants and Emerging Players: Launch via certified local testing partnerships in Maharashtra and Gujarat manufacturing corridors to capture India's BIS-mandated industrial equipment procurement. White-space targets include microcontroller-based triggering architectures for precision heating applications where analog talent scarcity constrains incumbent development velocity. The most penetrable segment is digital gate-driver modules for sub-400V motor control, where PLC firmware compatibility requirements deter commodity suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless specialists with foundry partnerships in trailing-edge silicon nodes, overlooked amid SiC R&D enthusiasm. Long-term viability hinges on hybrid Si-SiC module development capabilities for 3.3kV traction systems. The acquisition target archetype combines analog design expertise with established GB certification pipelines. Monitor EU carbon-border adjustment mechanism implementation timelines as inflection indicators for higher-efficiency device procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Partnership | Establishes accelerated market access for grid-tied inverter applications in Shenzhen and Xi'an clusters. |
| Backward Integration into Ceramic Substrates | Secures thermal interface supply for high-reliability phase-control devices amid packaging material constraints. |
| Digital Gate-Driver Platform Launch | Captures precision heating and renewable energy conversion applications beyond analog triggering capabilities. |
| Hybrid Si-SiC Module Development | Positions for 3.3kV rail traction pilots in Germany and Japan while absorbing adjacent wide-bandgap R&D spillover. |
| Direct Foundry Relationship Consolidation | Bypasses distributor disintermediation in South Korea's Gyeonggi semiconductor manufacturing cluster. |
Research Methodology
Direct dialogue with inverter OEM procurement directors, phase-control device design engineers, power semiconductor distribution channel managers, and MIIT certification laboratory technical leads grounded the qualitative foundation. Secondary validation drew from SEC 10-K filings of listed semiconductor manufacturers, China customs trade data for power semiconductor imports, IEC standard revision documentation, and EU F-Gas Regulation implementation reports. Bottom-up and top-down triangulation cross-checked wafer-level supply estimates against end-use equipment production forecasts.
Bottom-up modeling aggregated phase-control, inverter bridge, dimmer, and voltage regulator segment volumes across industrial motor-drive, renewable energy conversion, automotive traction, and appliance control end-uses. Top-down constraints incorporated polysilicon supply availability and captive wafer capacity utilization rates at integrated manufacturers. CAGRs derived from segment-level growth differentials across the analysis window, with technology transition curves for digital gate-driver adoption calibrated against PLC firmware integration timelines in retrofitted facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU carbon-border adjustment implementation or sudden polysilicon supply disruptions from Xinjiang production regions. Practitioners should monitor MIIT GB/T reliability standard revision schedules and IGBT price-performance trajectories in 400V-800V motor-drive applications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
AC Voltage Transducer Market
Power Systems
Synchronous Condenser Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Central Battery Systems Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Power Electronics Market
Power Systems
Batteries for Semiconductor Market
Power Systems
Digital Inverter Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Charge Controller System Market
Power Systems
Global Fault Current Limiter Market