
 Power Electronics Equipment Cooling System Market | 2026-2036
Power Electronics Equipment Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Power Electronics Equipment Cooling System Market Analysis
Buyer concentration among hyperscale data center operators is consolidating procurement volumes for high-capacity cooling infrastructure. ABB anchors its position through integrated power and thermal management portfolios across European industrial sites. Schneider Electric SE leverages software-defined cooling controls to differentiate in colocation facilities. Delta Electronics Inc. dominates liquid-cooled server rack deployments with manufacturing scale in Taiwan and mainland China.
Power electronics equipment cooling systems manage thermal dissipation for semiconductor devices, converters, and inverters using forced air, liquid loops, or phase-change materials to maintain junction temperatures below rated thresholds. Liquid-cooled systems are capturing margin pools as silicon carbide and gallium nitride devices push heat fluxes beyond air-cooled limits. Active cooling technology leads installed base volumes while hybrid cooling architectures are growing fastest in automotive inverter applications. Thermoelectric systems occupy niche roles in aerospace and defense where vibration tolerance outweighs efficiency penalties.
The EPA enforces refrigerant phase-down schedules under AIM Act provisions that constrain hydrofluorocarbon use in cooling equipment sold into US markets. REACH and RoHS frameworks in Europe restrict hazardous substances in heat exchanger coatings and solder materials, reshaping supplier qualification requirements. ISO 9001 and IEC thermal management standards govern product certification pathways across multiple jurisdictions. Stakeholders must monitor how refrigerant chemistry transitions and wide-bandgap semiconductor diffusion will redefine cooling system specifications and serviceable market boundaries.
Market Dynamics
The transition from silicon to silicon carbide and gallium nitride semiconductors is forcing a fundamental recalibration of thermal management specifications across power electronics applications. Heat flux densities now exceed the practical limits of conventional air-cooled architectures, creating structural pressure for liquid-cooled system adoption.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating migration toward liquid-cooled and dielectric fluid alternatives in European data center and industrial inverter deployments.
- EV inverter manufacturing:Automotive electrification programs in China are scaling production lines that specify liquid-cooled thermal management for 800V traction inverters and onboard chargers.
- Silicon carbide diffusion:Wide-bandgap semiconductors operating at higher switching frequencies and temperatures are rendering legacy air-cooled designs thermally inadequate for next-generation power conversion equipment.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger raw material costs fluctuate with commodity cycles, compressing margins for system integrators locked into fixed-price infrastructure contracts.
- Taiwan manufacturing concentration:Liquid-cooled cold plate and manifold supply chains cluster around Hsinchu and Taichung, exposing procurement continuity to single-source geographic risk.
- Refrigerant chemistry lock-in:Existing installed bases of vapor-compression equipment face stranded asset risk as EPA AIM Act phase-down schedules constrain hydrofluorocarbon service and recharge availability.
Strategic Opportunities
- India data center buildout:Hyperscale facility construction in Mumbai, Chennai, and Hyderabad is specifying liquid-cooled racks ahead of density thresholds, creating first-mover positioning for thermal system suppliers.
- Battery energy storage integration:Grid-scale BESS projects combining power conversion with thermal management present bundled system opportunities for cooling vendors with electrical packaging capabilities.
- US Inflation Reduction Act:Domestic content incentives for clean energy manufacturing are pulling cooling system production toward North American assembly to qualify for tax credit stacking.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Specialized expertise in two-phase heat transfer and dielectric fluid chemistry concentrates in aerospace and semiconductor equipment sectors, constraining supplier scaling.
- ISO 9001 and IEC thermal management certification timelines:Multi-jurisdiction qualification pathways extend product launch cycles and delay revenue recognition for new cooling system architectures.
- Legacy air-cooled infrastructure retrofit complexity:Data center operators face structural constraints integrating liquid-cooled manifolds into existing raised-floor environments designed for perimeter cooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Electronics Equipment Cooling System Market |
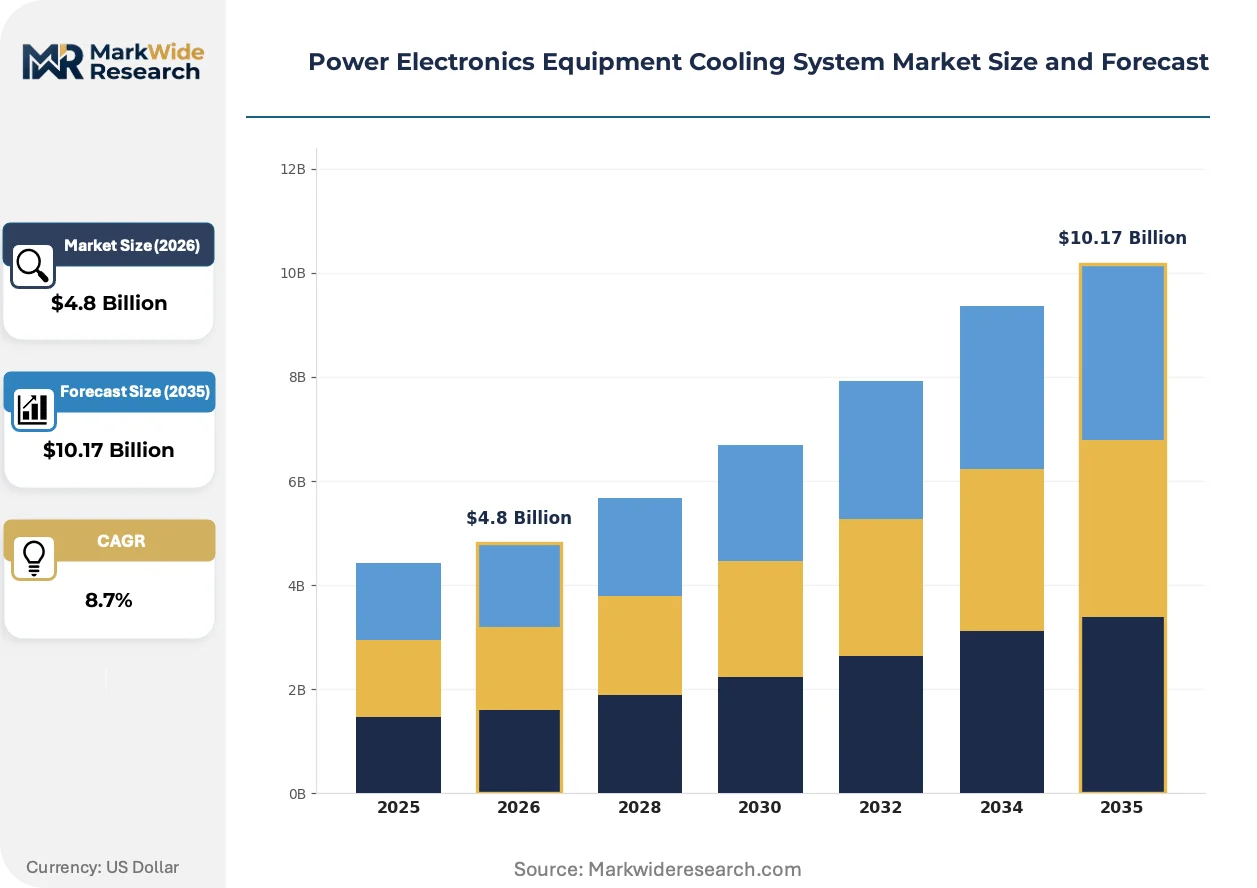
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled Systems, Liquid-Cooled Systems, Thermoelectric Systems, Phase Change Material Systems Technology: Active Cooling, Passive Cooling, Hybrid Cooling, Enhanced Heat Sink End User: Telecommunications, Data Centers, Automotive, Industrial Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Rittal GmbH & Co. KG, Aavid Thermalloy, ABB, Emerson Electric Co., Eaton Corporation, Schneider Electric SE, Advanced Cooling Technologies Inc., Delta Electronics Inc., Vertiv Group Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Electronics Equipment Cooling System Market Emerging Trajectories
Cooling system architectures are converging with power electronics packaging in ways that blur traditional boundaries between thermal management and electrical interconnection functions.
Immersion cooling using engineered dielectric fluids is rewriting the relationship between semiconductor junction temperature and system reliability. Hyperscale data center operators in Singapore and the Netherlands are piloting single-phase and two-phase immersion tanks for GPU clusters and high-density storage arrays. This technology is compressing the total cost of ownership gap between air-cooled and liquid-cooled infrastructure by eliminating chillers and reducing mechanical complexity.
EPA enforcement of AIM Act hydrofluorocarbon phase-down schedules is constraining refrigerant availability for vapor-compression cooling equipment sold into US markets. Industrial facility operators face accelerated replacement cycles for existing chiller plants as service refrigerant stocks deplete and reclamation costs escalate. The commercial data center segment is responding fastest, with colocation providers specifying refrigerant-free liquid-cooled designs for new construction to avoid compliance exposure.
Hyperscale procurement teams are unbundling thermal management from server OEM supply agreements and contracting directly with cooling system specialists. This disintermediation pattern concentrates volume leverage with buyers who specify performance metrics rather than component brands. The shift is most visible in Northern Virginia and Frankfurt, where multi-hundred-megawatt facility programs issue separate RFPs for electrical infrastructure, mechanical systems, and IT equipment.
Power Electronics Equipment Cooling System Market Segmentation
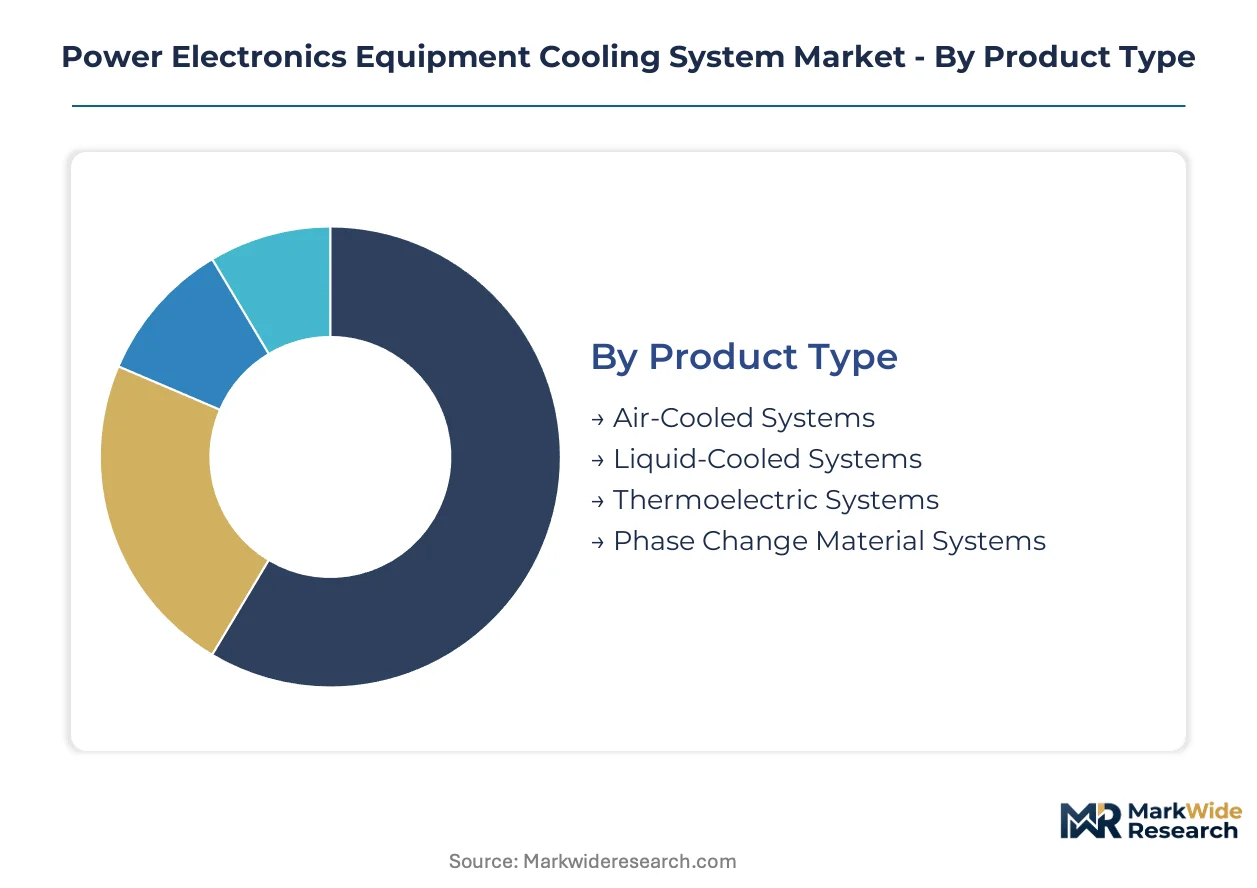
Power electronics cooling systems fragment across thermal physics, deployment context, and customer procurement patterns. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Air-cooled systems dominate installed base volumes while liquid-cooled alternatives capture expanding premium pools.
- Liquid-Cooled Systems:Circulate dielectric fluids or water-glycol mixtures through cold plates bonded directly to IGBT and SiC modules. Data center operators in Northern Virginia and Frankfurt specify these for racks exceeding 30kW density thresholds.
- Air-Cooled Systems:Deploy finned heat sinks with forced convection from axial or centrifugal blowers. Industrial motor drive installations across Germany and Japan retain these for legacy compatibility and maintenance simplicity.
- Thermoelectric Systems:Exploit Peltier junctions for precise temperature control in aerospace avionics where vibration tolerance outweighs coefficient-of-performance penalties.
- Phase Change Material Systems:Absorb transient thermal spikes through latent heat absorption in battery energy storage enclosures.
Today's leader: Liquid-Cooled Systems. Tomorrow's challenger: Phase Change Material Systems.
Technology:
Active versus passive architectures split procurement decisions between operational expenditure sensitivity and capital cost constraints.
- Active Cooling:Powers pumps, fans, or compressors to force heat transfer fluid motion. EV traction inverters from Chinese OEMs specify active liquid loops for 800V platforms operating above 200°C junction temperatures.
- Hybrid Cooling:Combines passive heat spreading with active fluid circulation triggered by thermal thresholds. Automotive onboard chargers in South Korea adopt these to balance efficiency and packaging volume.
- Passive Cooling:Relies on conduction and natural convection without moving parts. Telecommunications base stations in rural India deploy these for grid-independent reliability.
- Enhanced Heat Sink:Integrates vapor chambers or heat pipes into aluminum extrusions for improved conduction spreading. Industrial servo drives specify these where fan noise restrictions apply.
Active Cooling commands current procurement volumes. Hybrid Cooling is gaining share fastest in automotive electrification programs.
End User:
Customer concentration patterns concentrate bargaining power with hyperscale operators while automotive qualification timelines stretch supplier resources.
- Data Centers:Hyperscale and colocation operators unbundle thermal management from server procurement. Singapore and Netherlands facilities pilot immersion cooling for GPU clusters exceeding 50kW per rack.
- Automotive:Traction inverter and onboard charger manufacturing scales in China drive liquid-cooled system demand. 800V platform proliferation renders air-cooled designs thermally inadequate.
- Telecommunications:5G macro and small cell deployments specify compact thermal management for remote radio units. Edge computing nodes add incremental cooling load requirements.
- Industrial:Motor drives, welding equipment, and induction heating systems span air-cooled and liquid-cooled specifications. REACH compliance reshapes heat exchanger coating qualifications for European installations.
Data Centers anchor near-term revenue concentration. Automotive presents the steepest expansion trajectory through electrification program scaling.
Installation:
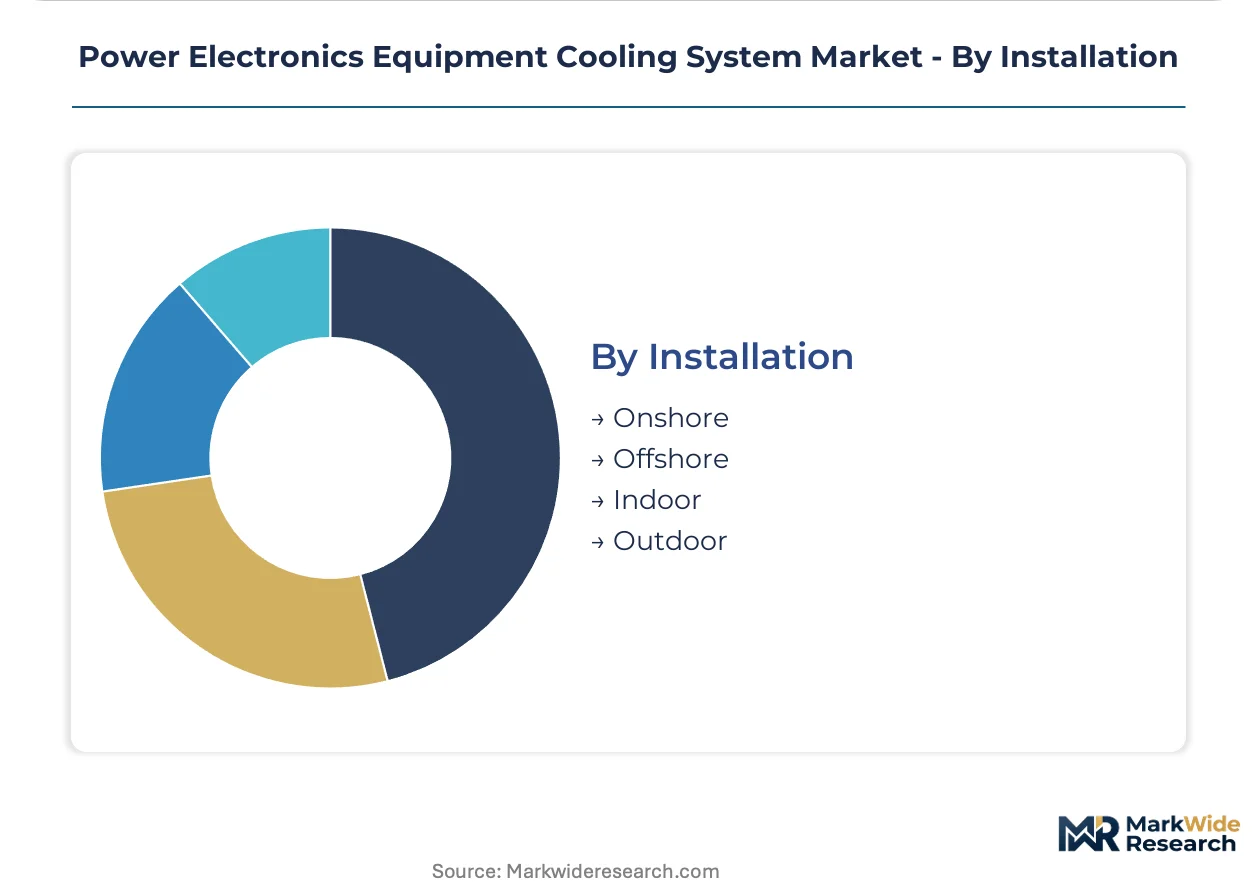
Environmental exposure and accessibility constraints dictate reliability engineering priorities and service contract structures.
- Indoor:Climate-controlled environments permit standard fan and pump specifications. Colocation facilities in Mumbai and Chennai specify these for controlled atmosphere reliability.
- Outdoor:Exposure to temperature extremes, humidity, and particulate contamination demands sealed enclosures and corrosion-resistant coatings. Telecommunications infrastructure across Australia deploys these for remote site survivability.
- Onshore:Ground-based industrial and utility installations with maintenance crew accessibility. Battery energy storage projects in Texas specify these for grid stabilization services.
- Offshore:Marine and subsea environments impose pressure vessel and galvanic isolation requirements. Offshore wind converter platforms in the North Sea demand specialized corrosion protection.
Indoor installations retain volume concentration. Outdoor specifications are climbing fastest with edge infrastructure and telecommunications densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal-fluid engineering talent concentrates in Taiwan's Hsinchu Science Park, Germany's industrial belt, and California's Silicon Valley corridor, anchoring regional competitive advantages in cooling system design and manufacturing.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives liquid-cooled rack procurement. EPA AIM Act enforcement constrains hydrofluorocarbon refrigerant availability for existing chiller infrastructure. Austin and Phoenix facility expansions specify refrigerant-free designs to preempt compliance exposure.
China
Domestic EV inverter manufacturing scales in Shenzhen and Shanghai, pulling demand for 800V-compatible liquid cooling loops. MIIT dual carbon goals accelerate phase-out of high-GWP refrigerants in industrial equipment. Hefei and Xi'an battery energy storage clusters integrate power conversion with thermal management bundling.
Germany
Industrial motor drive and welding equipment manufacturers specify REACH-compliant heat exchanger coatings for European installations. EU F-Gas Regulation tightens hydrofluorocarbon phase-down schedules through 2030. Bavarian automotive suppliers prototype hybrid cooling architectures for next-generation traction inverters.
India
Hyperscale facility construction in Mumbai, Chennai, and Hyderabad specifies liquid-cooled racks ahead of density thresholds. BIS certification requirements reshape supplier qualification timelines for imported thermal management equipment. Telangana's data center policy incentives attract cooling system specialists establishing local assembly.
Japan
Telecommunications infrastructure densification for 5G edge computing creates compact thermal management demand. METI efficiency standards push adoption of advanced heat pipe and vapor chamber technologies. Osaka-area industrial electronics manufacturers retain air-cooled specifications for legacy compatibility.
Power Electronics Equipment Cooling System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base clusters around three strategic archetypes: integrated electrical-thermal platform providers, component-scale cold plate and manifold fabricators, and software-defined cooling control developers. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for hyperscale procurement consolidation.
Among diversified industrial conglomerates, ABB and Schneider Electric SE occupy positions spanning integrated power and thermal management portfolios. Delta Electronics Inc. exemplifies the scale-driven specialist archetype with concentrated manufacturing presence in Taiwan and mainland China. These three anchors represent distinct competitive vectors: platform breadth, software differentiation, and manufacturing scale.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Aavid Thermalloy |
| ABB |
| Emerson Electric Co. |
| Eaton Corporation |
| Schneider Electric SE |
| Advanced Cooling Technologies Inc. |
| Delta Electronics Inc. |
| Vertiv Group Corp |
| Others |
Supply Flow & Price Mechanics
Thermal-fluid engineering talent clustering in Taiwan's Hsinchu Science Park and Germany's industrial belt feeds labor-cost differentials that widen pricing spreads between premium liquid-cooled systems and commodity air-cooled alternatives. Buyers in Northern Virginia and Frankfurt data center markets absorb these tier premiums for SiC-compatible cold plates, while industrial motor drive operators in Japan and India select standardized heat sink extrusions to compress procurement outlays.
Pricing Analysis
The bundled-versus-unbundled service split is reshaping contract structures as hyperscale operators separate thermal management procurement from server OEM agreements. Project-based pricing dominates liquid-cooled rack deployments with customization premiums for dielectric fluid chemistry and manifold geometry, while transactional per-unit pricing persists for air-cooled heat sinks in legacy industrial applications. Price differentiation hinges on ISO 9001 certification tier and volume scale commitments, with cost compression in standard-grade cold plates intensifying due to Taiwanese manufacturing scale. Data center operators exhibit the sharpest price sensitivity, whereas aerospace and defense buyers prioritize vibration tolerance over unit economics.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns for dielectric fluid and cold plate inventory positioning near hyperscale construction clusters. Manufacturing concentrates in Taiwan, mainland China, and Germany, with Hsinchu and Taichung cold plate fabricators drawing from copper and aluminum feedstock cycles that amplify margin volatility. Supply chain risk centers on single-source geographic concentration for liquid-cooled manifold production, compounded by EPA AIM Act refrigerant restrictions stranding vapor-compression component inventories. Distribution runs through direct contracting with cooling system specialists rather than server OEM intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power Electronics Equipment Cooling System Market reads as a late-cycle quality story, with EV inverter manufacturing and hyperscale data center density thresholds pulling procurement toward premium liquid-cooled specifications over commodity air-cooled alternatives.
For Market Incumbents: To counter disintermediation by hyperscale procurement teams unbundling thermal management from server OEM agreements, ABB and Schneider Electric SE should deepen software-defined cooling control integration with electrical infrastructure platforms. Delta Electronics Inc. can defend margin position by adding captive cold plate production capacity in Hsinchu to offset Taiwan supply concentration risk and accelerate ISO 9001 certification timelines for next-generation dielectric fluid architectures. For New Entrants and Emerging Players: Two-phase immersion cooling technology offers the most penetrable wedge for specialist entrants targeting Singapore and Netherlands GPU cluster pilots exceeding 50kW rack densities. White-space concentration sits in battery energy storage system thermal management bundling for Texas and Hefei grid-scale projects, with go-to-market traction achievable through EPC contractor partnerships rather than direct utility sales cycles. For Investors and Strategic Acquirers: Industrial conglomerates with power electronics portfolios are the most active acquirer in this space, seeking thermal management capabilities to complete integrated platform offerings. Acquisition targets should display REACH-compliant coating expertise and two-phase heat transfer engineering depth. The signal to watch is EPA enforcement acceleration on AIM Act hydrofluorocarbon phase-down schedules, which would compress replacement cycles for stranded vapor-compression assets and revalue refrigerant-free liquid-cooled specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Plate Manufacturing | Taiwanese suppliers secure copper supply chains against commodity volatility from Chilean mining output. |
| Dielectric Fluid Chemistry R&D Partnership | Collaboration with chemical specialists accelerates REACH-compliant formulations for European data center deployments. |
| Software-Defined Cooling Control Platform | Schneider Electric SE leverages predictive algorithms to differentiate colocation facility energy efficiency metrics. |
| Geographic Manufacturing Expansion | North American assembly qualification for US Inflation Reduction Act domestic content incentives. |
| Immersion Cooling Pilot Deployment | Hyperscale operators in Singapore validate two-phase systems for GPU clusters exceeding air-cooled thermal limits. |
Methodological Framework
Bottom-up data center and automotive inverter modeling reconciled against top-down cooling system production tracking forms the analytical core of this study. Primary interviews with thermal management procurement directors at hyperscale operators, EV platform engineers at Chinese OEMs, and plant managers at German industrial motor drive manufacturers combined with secondary validation from EPA AIM Act filings, EU F-Gas Regulation implementation reports, and MIIT dual carbon policy disclosures. SEC 10-K thermal management segment disclosures and Taiwan Stock Exchange cold plate supplier revenue filings anchored supply-side triangulation against demand-side facility construction databases.
Input-output matrices mapped heat flux density requirements from SiC and GaN semiconductor diffusion against installed cooling system capacity across active, hybrid, and passive technology tiers. Segmentation dimensions spanned product type, cooling technology, end-use vertical, and installation environment, with regional production cluster and regulatory framework overlays. CAGRs were derived from slope-intercept analysis of historical procurement volumes and elasticity-adjusted adoption curves for liquid-cooled alternatives. Forecast inputs incorporated EV 800V platform rollout schedules and hyperscale rack density threshold crossing points.
The model holds under steady EPA enforcement of AIM Act schedules and continued EU F-Gas Regulation tightening; deviation in refrigerant chemistry transition timelines or wide-bandgap semiconductor diffusion rates would shift serviceable market boundaries. Forecasts reflect documented assumptions on labor cost trajectories in Taiwan and commodity price bands for copper and aluminum. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Charge Controller System Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Traction Inverter Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Electrical and Automation System Market
Power Systems
Low Voltage AC Drive Market
Power Systems
North America Micro Inverter Market
Power Systems
South America Battery Management System Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Global Rugged Power Supply Market
Power Systems
USB Power Adapters Market