
 Japan Vacuum Pressure Impregnated (VPI) Transformer Market | 2026-2036
Japan Vacuum Pressure Impregnated (VPI) Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Vacuum Pressure Impregnated (VPI) Transformer Market Insights
Kansai industrial belt capacity expansion is rewriting procurement dynamics for Japanese VPI transformer buyers. Fuji Electric leverages its Osaka-based insulation systems expertise to anchor domestic utility contracts. Toshiba Energy Systems sustains R&D intensity across epoxy resin formulations for rail traction applications. Hitachi Energy competes through integrated digital monitoring packages bundled with medium-capacity distribution units.
Vacuum Pressure Impregnated transformers undergo resin vacuum-infusion into wound insulation under controlled pressure cycles, achieving void-free dielectric structures rated for thermal class F or H operation. These units serve critical applications where fire safety, moisture resistance, and compact footprint override oil-filled alternatives. Distribution transformers occupy the largest volume position due to METI-mandated efficiency upgrades across prefectural grids, while epoxy resin insulation commands premium positioning against polyester alternatives in coastal humidity-exposed installations. Renewable energy end users represent the fastest-expanding demand pool as solar and wind farm interconnection specifications harden.
METI efficiency standards, JIS C 4304 product specifications, and Fire Service Act installation codes collectively shape Japanese VPI transformer design requirements and market access conditions. METI's Top Runner program tightens no-load loss ceilings every review cycle, forcing manufacturers toward advanced core materials and optimized winding geometries. Stakeholders must monitor pending revisions to grid interconnection codes for distributed generation, as these will determine capacity sizing and insulation class specifications for the next equipment replacement wave.
Market Dynamics
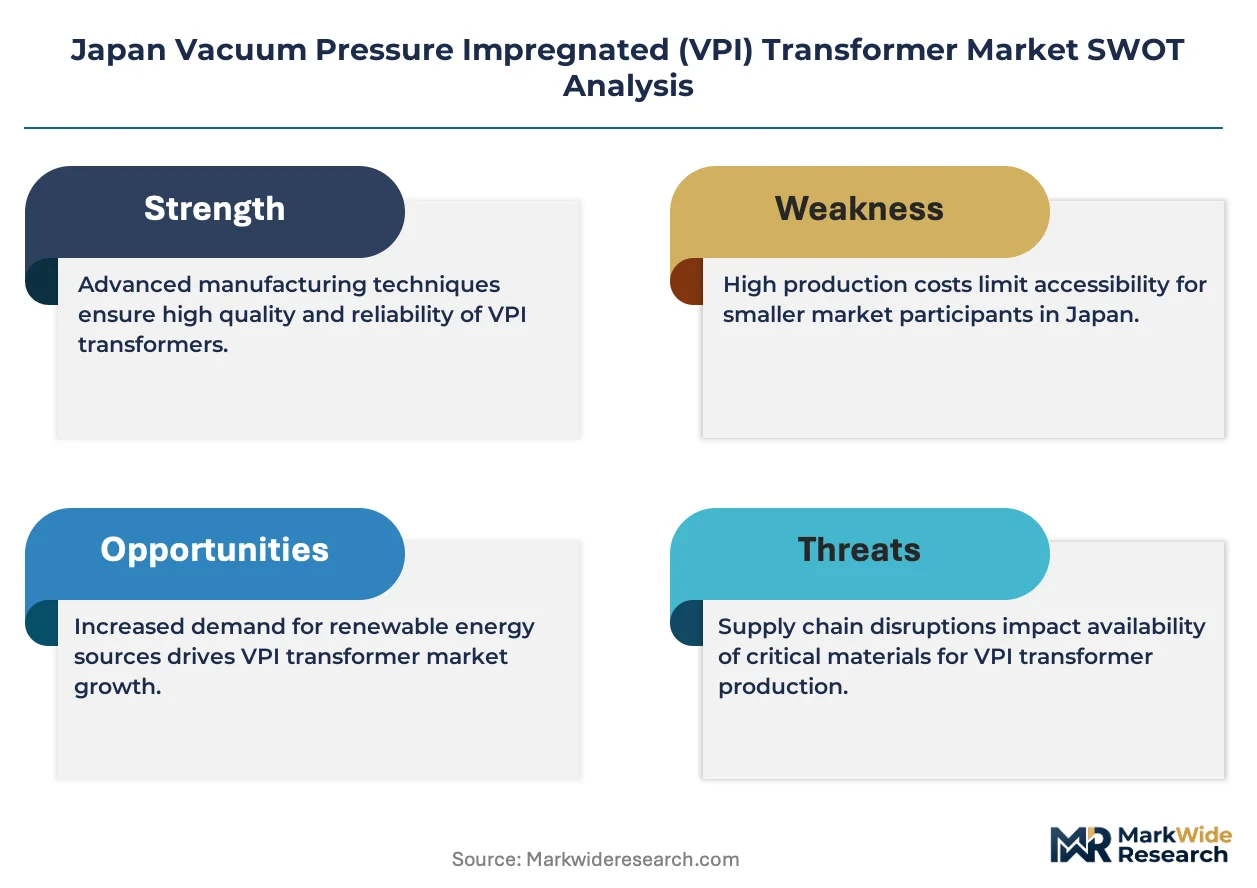
METI's Top Runner efficiency mandates are compressing replacement cycles for distribution-class equipment while forcing manufacturers toward advanced core materials and optimized winding geometries.
Growth Catalysts
- Kanto corridor railway electrification:Medium-capacity VPI units are seeing expanded procurement as rail traction networks upgrade insulation systems for higher thermal class operation.
- JIS C 4304 efficiency standards:Distribution transformer replacement waves are accelerating as prefectural grids face tightening no-load loss ceilings under METI review cycles.
- Epoxy resin formulation advances:Coastal humidity-exposed installations are driving premium positioning against polyester alternatives in Osaka-Kobe manufacturing clusters.
Market Restraints
- Silicon steel core material volatility:Grain-oriented electrical steel prices fluctuate with global supply constraints, compressing margin structures for medium-capacity units.
- Fire Service Act installation codes:Compliance timelines for indoor VPI deployments create project delays in commercial building retrofits.
- Oil-filled transformer residual demand:Cost-sensitive municipal utilities in rural prefectures continue specifying conventional liquid-immersed alternatives for outdoor substations.
Strategic Opportunities
- Kyushu renewable energy interconnection:Solar and wind farm specifications are hardening for distributed generation grid codes, creating capacity sizing demand for next replacement waves.
- Digital monitoring convergence:Integrated sensor packages bundled with distribution units are opening service revenue streams beyond hardware sales.
- PLI scheme alignment:Industrial automation customers in the Kansai belt are qualifying VPI suppliers for efficiency-linked procurement preferences.
Industry Challenges
- Epoxy resin curing technician scarcity:Vacuum-infusion process expertise concentrates among aging workforces in Osaka-based insulation specialists.
- Grid code revision uncertainty:Pending METI distributed generation interconnection updates are freezing capital commitment timelines for utility procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Vacuum Pressure Impregnated (VPI) Transformer Market |
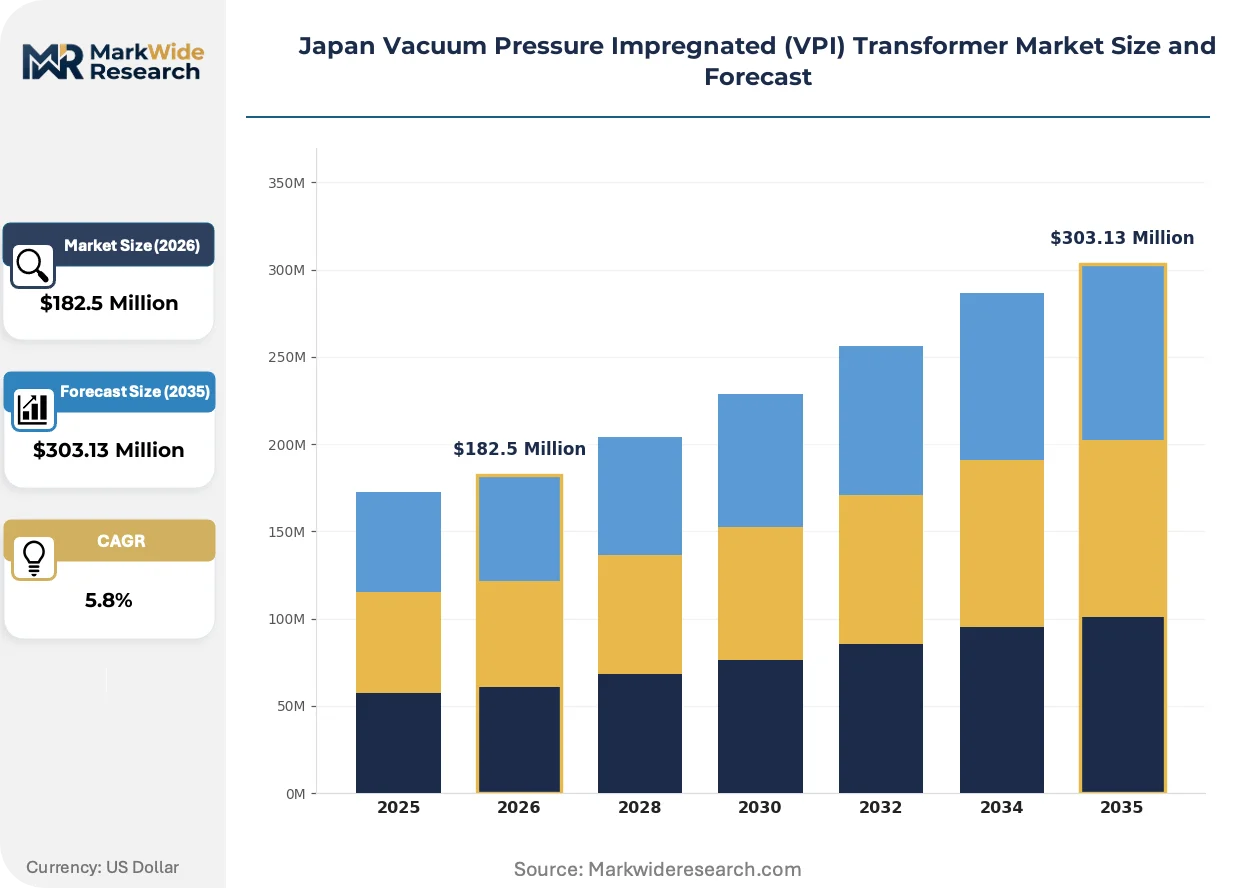
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $303.13 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transformer Type: Distribution, Power, Instrument, Special Purpose Insulation Material: Polyester, Epoxy Resin, Silicone, Others End User: Utilities, Manufacturing, Renewable Energy, Transportation Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Fuji Electric, Toshiba Energy Systems, Hitachi Energy, ABB, Siemens Energy, GE, Schneider Electric, Eaton, CG Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Vacuum Pressure Impregnated (VPI) Transformer Market Trends and Innovations
Resin formulation science and embedded diagnostics are converging to redefine performance benchmarks for Japanese distribution infrastructure. Equipment buyers now specify thermal class and monitoring capability as bundled requirements.
Epoxy-anhydride resin systems with nano-filler additives are hybridizing conventional insulation structures, delivering enhanced partial discharge resistance for coastal installations. Railway operators in the Kanto corridor are specifying these formulations for traction substation retrofits. The technology is hybridizing procurement specifications across medium-capacity segments previously dominated by standard epoxy grades.
METI's pending revisions to grid interconnection codes for distributed generation are tightening insulation class requirements for solar farm tie-in transformers. Manufacturers must recertify product lines under accelerated JIS C 4304 amendment schedules. Distribution-class equipment serving Kyushu renewable zones faces the most immediate compliance recalibration.
Buyer preference for lifecycle service contracts is displacing transactional equipment-only purchasing in prefectural utility procurement. Integrated digital monitoring packages now feature in majority of Osaka-Kobe cluster tenders. Railway electrification projects in the Kanto corridor exhibit the most pronounced shift toward performance-guaranteed supply agreements.
Japan Vacuum Pressure Impregnated (VPI) Transformer Market Segmentation
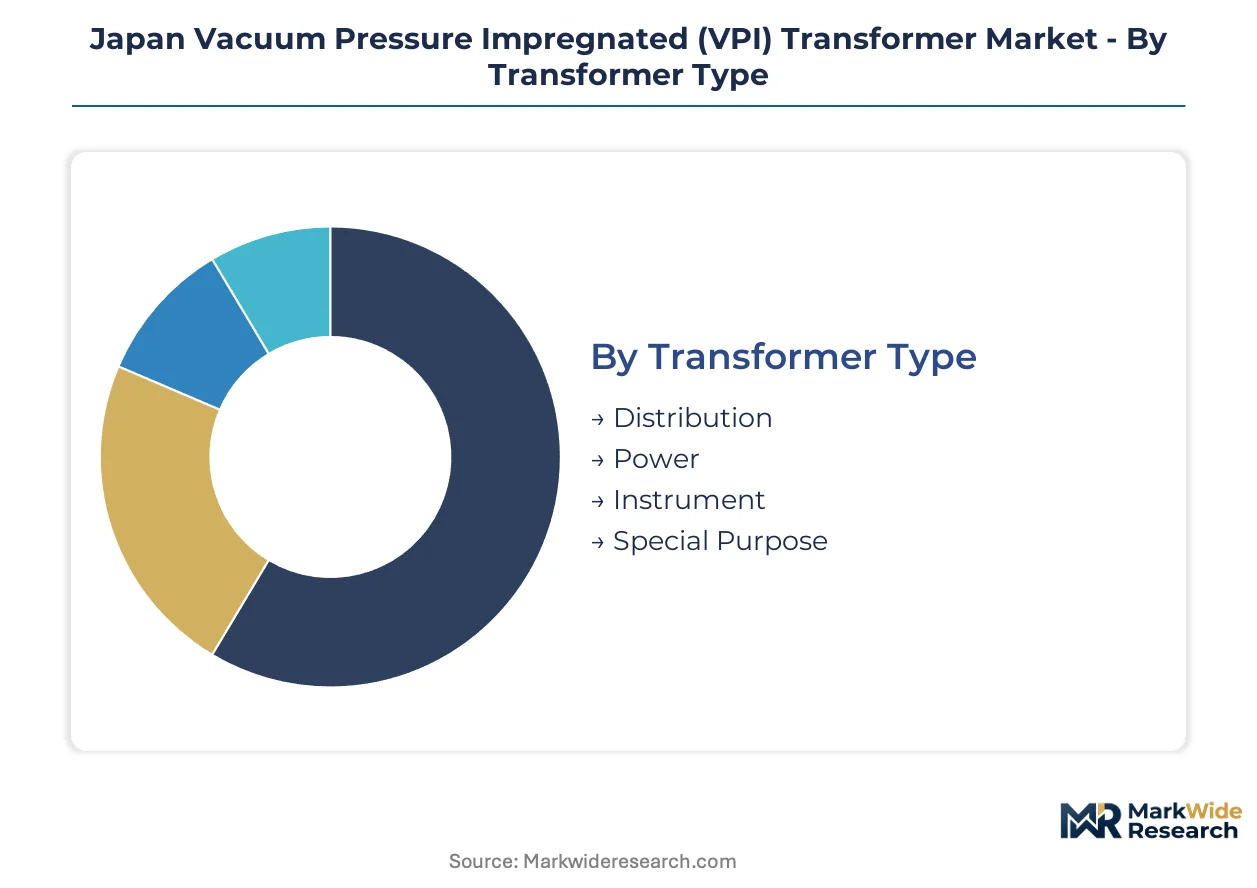
VPI transformer procurement cycles vary dramatically across application types, with rail electrification projects demanding rapid replacement schedules while utility distribution assets operate on decade-long depreciation timelines. Segment-specific technical requirements drive divergent supplier qualification paths and margin structures across the Japanese market.
Transformer Type:
Distribution transformers turn over fastest due to METI-mandated efficiency upgrade cycles, while power transformers and special-purpose units exhibit extended replacement timelines tied to infrastructure depreciation schedules.
- Distribution:These units handle voltage step-down for prefectural grid networks, with dry-type resin insulation replacing oil-filled alternatives in urban substations. METI Top Runner compliance deadlines in Kanto and Kansai prefectures are compressing procurement timelines for municipal utilities.
- Power:Bulk electricity transmission interfaces require higher kVA ratings with reinforced insulation systems. Replacement concentrates in industrial zone interconnects where manufacturing load growth necessitates capacity expansion.
- Instrument:Metering and protection applications demand precise ratio accuracy in compact footprints. Demand clusters in smart grid retrofit projects across Osaka-Kobe manufacturing corridors.
- Special Purpose:Custom winding configurations serve traction substations and test bench applications. Railway electrification specifications in the Kanto corridor dominate order flow.
Distribution dominates installed base. Special Purpose is where expansion concentrates.
Insulation Material:
Material selection stratifies across cost-performance tiers, with premium formulations commanding substantial price premiums in coastal humidity-exposed installations.
- Epoxy Resin:Vacuum-infusion achieves void-free dielectric structures rated for thermal class F or H operation. Osaka-based manufacturers anchor supply for rail traction and renewable interconnection specifications where moisture resistance overrides cost considerations.
- Polyester:Lower-cost thermosetting resins serve indoor commercial installations with controlled environmental exposure. Standard-grade distribution units in inland prefectures specify this material for budget-constrained municipal procurement.
- Silicone:Elastomeric insulation systems deliver extreme temperature cycling tolerance for outdoor substations in Hokkaido and northern Honshu climatic zones.
- Others:Hybrid and experimental formulations including nano-filled epoxy-anhydride systems target partial discharge resistance in next-generation traction applications.
Epoxy Resin captures premium positioning. Polyester retains volume leadership in cost-sensitive segments.
End User:
Customer type determines specification stringency, with transportation and renewable energy buyers imposing thermal class and monitoring requirements that exceed utility baseline standards.
- Utilities:Prefectural grid operators procure standardized distribution units under JIS C 4304 specifications. METI efficiency mandates drive replacement waves across aging rural infrastructure.
- Manufacturing:Industrial automation facilities in the Kansai belt specify medium-capacity units with integrated power quality monitoring. PLI scheme alignment is qualifying preferred supplier relationships.
- Renewable Energy:Solar and wind farm developers face hardening grid interconnection codes for distributed generation tie-in transformers. Kyushu renewable zones exhibit steepest expansion trajectory for insulation class H specifications.
- Transportation:Railway operators in the Kanto corridor specify traction substation units with enhanced thermal cycling tolerance. Performance-guaranteed supply agreements are displacing transactional purchasing.
Utilities dominate installed base. Renewable Energy is where expansion concentrates.
Capacity:
Unit scale correlates with application criticality, where larger capacities justify premium resin formulations and embedded diagnostic packages.
- Medium:Rail traction and industrial substation applications concentrate procurement in this segment. Kanto corridor electrification projects specify these units for thermal class F or H operation with compact footprint requirements.
- Small:Commercial building and light industrial applications specify lower-kVA units for indoor installation under Fire Service Act compliance timelines.
- Large:Bulk power distribution and manufacturing campus substations require higher thermal mass designs with extended overload tolerance.
- Extra Large:Grid interconnection and heavy industrial applications specify custom-engineered units with multi-year lead times and dedicated project engineering.
Medium capacity dominates current procurement. Extra Large is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokaido Shinkansen corridor underwrites Kanto's primacy in rail electrification infrastructure, while the Kansai industrial belt anchors manufacturing demand for medium-capacity distribution units.
Kanto
Railway electrification projects along the Tokyo-Osaka corridor drive procurement of thermal class F and H VPI units for traction substations. METI Top Runner efficiency mandates compress replacement cycles for aging distribution infrastructure across Tokyo, Kanagawa, and Chiba prefectures. Manufacturing clusters in Yokohama and Kawasaki specify integrated digital monitoring packages for industrial automation loads.
Kansai
Osaka-Kobe manufacturing corridors generate concentrated demand for epoxy resin insulation systems serving humidity-exposed coastal installations. JIS C 4304 product specifications govern prefectural grid procurement across Osaka, Hyogo, and Kyoto prefectures. Fuji Electric leverages its Osaka-based insulation expertise to anchor utility contracts in this industrial heartland.
Kyushu
Solar and wind farm interconnection specifications harden grid code requirements for distributed generation tie-in transformers. Pending METI revisions to distributed generation codes freeze capital commitment timelines for renewable developers in Fukuoka and Kumamoto prefectures. Regional utilities recalibrate insulation class specifications ahead of compliance deadlines.
Chubu
Nagoya automotive and machinery manufacturing complexes specify medium-capacity units with power quality monitoring for sensitive production lines. Fire Service Act installation codes create project delays for indoor VPI deployments in commercial building retrofits across Aichi prefecture. Industrial automation customers qualify suppliers under efficiency-linked procurement preferences.
Hokkaido
Severe climatic conditions drive specification of silicone insulation systems with extreme temperature cycling tolerance for outdoor substations. Rural municipal utilities in cost-sensitive prefectures continue specifying oil-filled alternatives despite efficiency disadvantages. Grid infrastructure investment lags behind Honshu corridors due to lower population density and load growth.
Japan Vacuum Pressure Impregnated (VPI) Transformer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in insulation materials and core laminations. The vendor base stratifies across three tiers: domestic electrical equipment conglomerates with full vertical scope, regional specialists in resin formulation and vacuum-infusion processes, and multinational industrial technology groups with global service networks. Dominant competitive moves include backward integration into grain-oriented electrical steel supply and technology licensing agreements for nano-filled epoxy-anhydride formulations.
Among domestic electrical equipment groups, Fuji Electric, Toshiba Energy Systems, and Hitachi Energy occupy positions spanning distribution through traction applications. Fuji Electric exemplifies the Osaka-based insulation specialist archetype with concentrated expertise in vacuum-infusion processes. Toshiba Energy Systems represents the diversified industrial technology conglomerate model with integrated digital monitoring capabilities. Hitachi Energy sits within the multinational platform tier bundling sensor packages with medium-capacity units for service revenue expansion.
| Leading Market Players |
|---|
| Fuji Electric |
| Toshiba Energy Systems |
| Hitachi Energy |
| ABB |
| Siemens Energy |
| GE |
| Schneider Electric |
| Eaton |
| CG Power |
| Others |
Pricing and Supply Chain Analysis
Grain-oriented electrical steel price volatility determines both three-tier pricing spreads across premium epoxy resin, standard polyester, and economy-grade silicone insulation systems, and the geographic clustering of vacuum-infusion expertise in Osaka-based manufacturing corridors. METI efficiency mandates compress margin structures for medium-capacity units while forcing buyers toward thermal class H specifications that lock in premium resin formulations.
Pricing Analysis
Volume-discount tiering separates railway electrification procurement in the Kanto corridor from prefectural utility distribution contracts and commercial building retrofit specifications. Price differentiation rests on JIS C 4304 certification grade and integrated digital monitoring bundling. Cost compression in standard-grade polyester units is intensifying because silicon steel core material volatility feeds through to transformer OEMs. Municipal utilities in rural prefectures exhibit highest price sensitivity; railway operators with performance-guaranteed supply agreements show lowest.
Supply Chain Analysis
Upstream feedstock for epoxy-anhydride resin systems draws from petrochemical complexes in South Korea and Japan, with nano-filler additives sourcing from specialized German chemical suppliers. Core lamination material hinges on grain-oriented electrical steel from Nippon Steel's domestic mills and selective imports. Single-source vulnerability concentrates in vacuum-infusion process equipment where Osaka-based specialists control technical know-how. Distribution runs through direct OEM contracts for rail and utility segments, with regional distributors serving commercial building retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against oil-filled transformer residual demand in cost-sensitive rural prefectures, where municipal procurement teams continue specifying conventional liquid-immersed alternatives despite METI efficiency disadvantages.
For Market Incumbents: Build captive resin formulation expertise to deepen moats against polyester substitution in inland prefectures. Anchor utility contracts through backward integration into grain-oriented electrical steel supply. Defend against emerging Korean epoxy compound suppliers by accelerating JIS C 4304 recertification timelines ahead of METI review cycles. For New Entrants and Emerging Players: Kyushu renewable energy zones offer underpenetrated white space where distributed generation grid code revisions freeze incumbent capital commitments. Target solar farm developers with insulation class H units pre-certified to pending METI interconnection standards. Enter through digital monitoring service bundling rather than hardware-only positioning. For Investors and Strategic Acquirers: The market sits at a regulatory tightening phase that favors vertically integrated resin specialists with captive vacuum-infusion capabilities. Long-term viability hinges on exposure to railway electrification and renewable interconnection replacement waves rather than saturated distribution utility segments. Watch for METI distributed generation code finalization as the inflection signal triggering utility procurement release.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Nippon Steel partnerships insulate margin structures against grain-oriented electrical steel price volatility. |
| Nano-Filled Epoxy Formulation Licensing | German chemical supplier agreements enable partial discharge resistance for coastal traction substations. |
| Digital Monitoring Platform Integration | Sensor package bundling opens recurring service revenue beyond transactional transformer sales. |
| Osaka-Kobe Manufacturing Footprint Expansion | Proximity to Fuji Electric and Toshiba Energy Systems anchors access to aging vacuum-infusion technician pools. |
| JIS C 4304 Recertification Acceleration | Pre-positioning for METI Top Runner amendments captures replacement wave timing in Kanto and Kansai prefectures. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with transformer OEM procurement directors, railway electrification project engineers, prefectural utility planning officers, and epoxy resin formulation specialists; and secondary validation through METI regulatory filings, JIS C 4304 amendment schedules, Japan Electrical Manufacturers' Association production statistics, and customs data on grain-oriented electrical steel imports. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Forecast inputs considered transformer type segmentation by distribution, power, instrument, and special-purpose categories; insulation material tiers spanning epoxy resin, polyester, silicone, and nano-filled hybrid formulations; and end-user demand patterns across utilities, manufacturing, renewable energy, and transportation. CAGRs derived from replacement cycle compression under METI efficiency mandates and capacity expansion trajectories in Kyushu renewable zones. Modeled variables included thermal class specification shifts and digital monitoring adoption curves.
Practitioners should monitor METI distributed generation interconnection code finalization and grain-oriented electrical steel tariff adjustments for early signals of forecast revision. Material shifts in JIS C 4304 amendment scope or Osaka-based vacuum-infusion technician availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Electronics Market
Power Systems
HVDC Converters Market
Power Systems
PV Micro Inverters Market
Power Systems
Grid Tie Inverter Market
Power Systems
Flyback Transformer Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Global Synchronous Motor Market
Power Systems
Power Supply and Charger Market
Power Systems
Solid State Power Controller Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Power Amplifier Modules Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Train Auxiliary Rectifier Market