
 Pulse Width Modulation Controllers Market | 2026-2036
Pulse Width Modulation Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Width Modulation Controllers Market Analytics
The gap between automotive-grade PWM controllers and commodity consumer electronics variants is recalibrating procurement criteria across the supply base. ON Semiconductor leverages its vertical integration into silicon carbide substrates to sustain pricing power in EV traction inverter applications. Texas Instruments competes through dense analog control IP portfolios that anchor design wins in industrial motor drives. Infineon Technology dominates automotive safety-critical segments with AEC-Q100 qualified synchronous buck architectures.
Pulse width modulation controllers regulate power delivery by varying duty cycle ratios in switching circuits, typically operating at frequencies from tens of kilohertz to several megahertz depending on load requirements. These devices manage voltage conversion efficiency in power supply systems, motor drives, LED drivers, and battery management subsystems across end equipment. Synchronous buck converters lead unit shipments due to proliferation in computing and telecom infrastructure, while digital control technology captures expanding margin pools as firmware-upgradable architectures displace fixed-function analog alternatives in automotive and renewable energy applications. Mixed signal control occupies a mature middle tier where established industrial equipment OEMs prioritize proven reliability over algorithmic flexibility.
The US DOE enforces minimum efficiency standards under the External Power Supply International Efficiency Marking Protocol, while the EU Ecodesign Directive mandates standby power limits that force controller redesigns in consumer electronics and industrial equipment. China's GB standards for power conversion efficiency, administered by the Standardization Administration, create domestic market access barriers for non-compliant imports. Stakeholders must monitor how impending carbon border adjustments in Europe and North America reshape cost structures for controllers manufactured in regions with divergent energy intensity regulations.
Market Dynamics
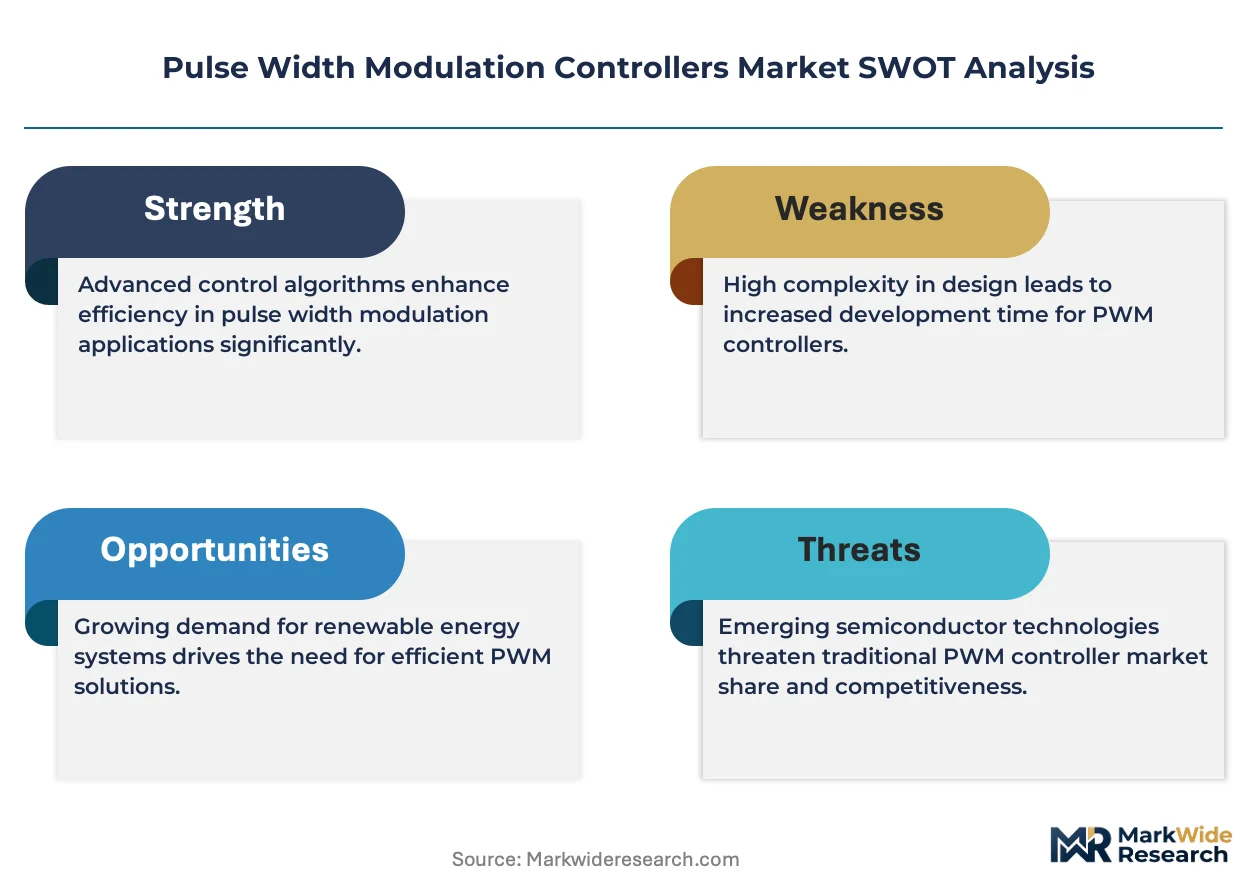
Digital control architectures are displacing fixed-function analog PWM controllers across automotive and renewable energy applications, compressing design cycles while expanding firmware-upgradable margin pools for power conversion equipment suppliers.
Growth Catalysts
- EU Ecodesign Directive:Standby power limits for external power supplies force controller redesigns, accelerating replacement demand in consumer electronics and industrial equipment supply chains.
- Silicon carbide substrate proliferation:Wide-bandgap semiconductors enable higher switching frequencies, expanding addressable load ranges for traction inverters and solar converters.
- China domestic fab scaling:Local semiconductor manufacturing for EV and solar inverter supply chains concentrates procurement volumes within vertically integrated national production networks.
Market Restraints
- Raw material concentration:Silicon carbide wafer supply concentrates among limited substrate manufacturers, creating input cost volatility and allocation risk for controller fabricators.
- AEC-Q100 certification timelines:Automotive safety-critical qualification cycles extend 18-24 months, gating market entry for new synchronous buck architectures.
- Digital controller IP complexity:Firmware development requirements escalate engineering headcount costs, disadvantaging smaller analog-centric suppliers.
Strategic Opportunities
- India power infrastructure:Grid modernization and renewable integration targets create unmet demand for industrial motor drive controllers in manufacturing clusters.
- Battery management subsystem convergence:Integration of PWM control with cell balancing and thermal management algorithms opens unified platform architectures.
- US DOE efficiency standard tightening:Minimum performance threshold escalation under the External Power Supply International Efficiency Marking Protocol mandates controller upgrades across import portfolios.
Industry Challenges
- Mixed-signal design talent scarcity:Shortage of engineers proficient in both analog power stage design and digital control algorithm development constrains product roadmap velocity.
- Legacy equipment interoperability:Backward compatibility requirements with existing motor drive and power supply installations complicate firmware-only upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Width Modulation Controllers Market |
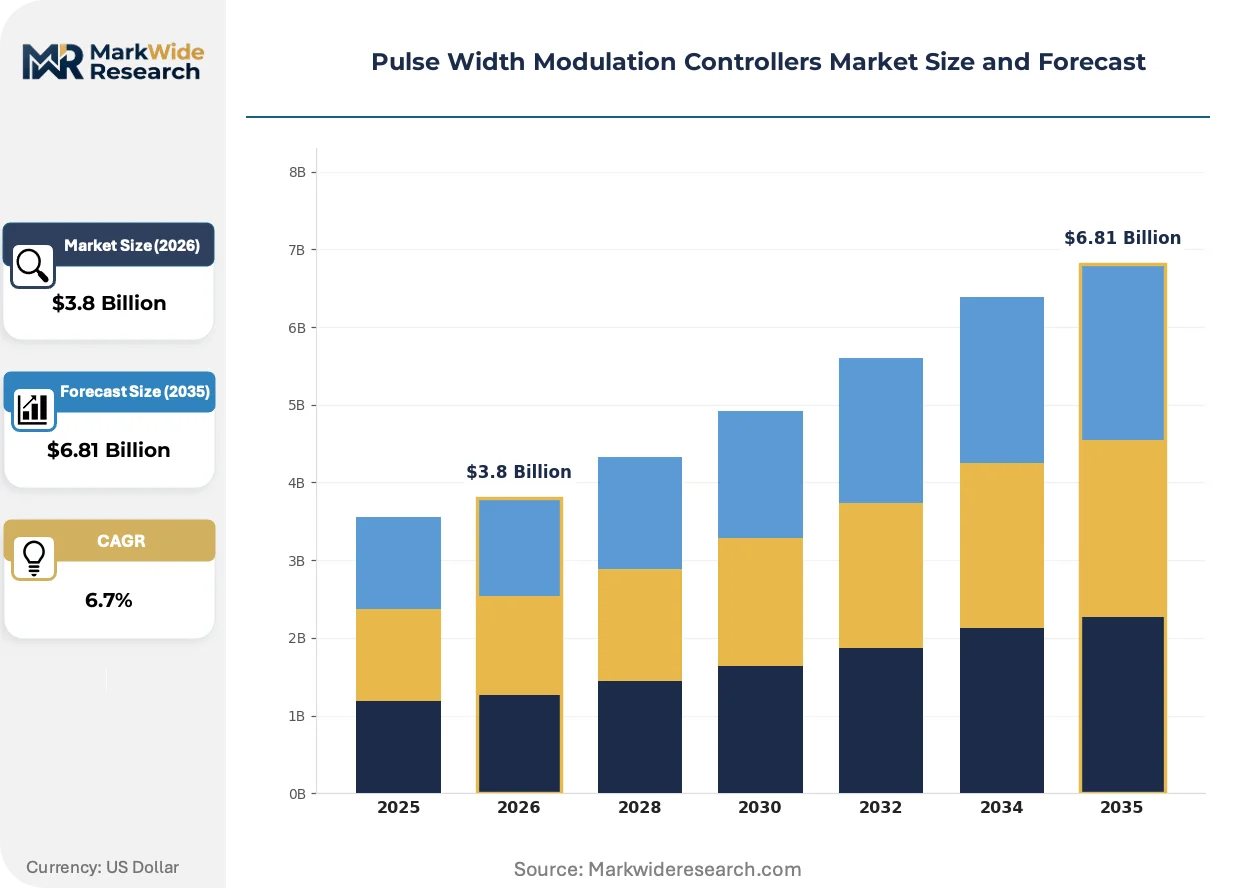
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Controllers, Synchronous Buck Converters, Boost Converters, H-Bridge Controllers End User: Consumer Electronics, Automotive Applications, Industrial Equipment, Telecommunications Technology: Analog Control, Digital Control, Mixed Signal Control, Firmware-Based Application: Power Supply Systems, Motor Drives, LED Drivers, Battery Management |
| Companies Covered | ON Semiconductor, Maxim Integrated, Analog Devices, Vishay, Infineon Technology, Texas Instruments, Microchip Technology, Diodes Incorporated, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Width Modulation Controllers Market Evolving Landscape
Power conversion architecture is pivoting from hardware-defined to software-defined control loops, enabling runtime parameter adjustment without physical component changes.
GaN-on-silicon power stages are rewriting switching frequency ceilings in compact adapters and telecom rectifiers. Computing and telecom infrastructure OEMs now specify controllers supporting 2-5 MHz operation for magnetic component miniaturization. This compression of passive component sizing is rewriting bill-of-material economics across high-density power supply categories.
China's GB standards for power conversion efficiency, administered by the Standardization Administration, create domestic market access barriers for non-compliant imports. Foreign controller suppliers must redesign feedback networks and standby circuits to meet these thresholds. Industrial equipment OEMs serving Chinese manufacturing clusters now dual-source qualified and non-qualified variants to manage compliance risk.
Consolidated procurement by EV powertrain manufacturers is compressing supplier qualification cycles and elevating volume-commitment requirements. Tier 1 automotive suppliers now mandate firmware update capabilities and predictive maintenance telemetry as standard deliverables. This specification escalation is most visible in Germany and China, where EV production volumes concentrate among vertically integrated platform manufacturers.
Pulse Width Modulation Controllers Market Segmentation
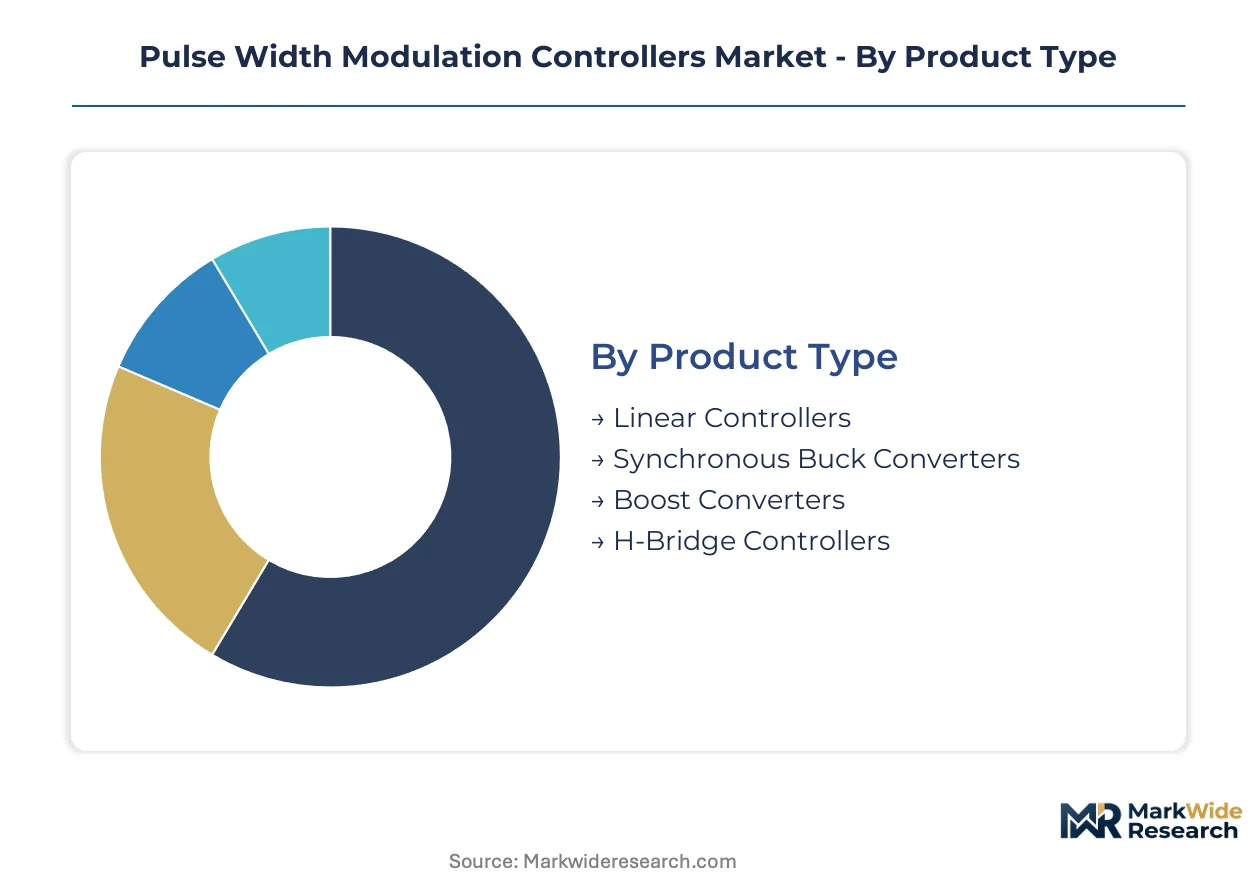
Pulse width modulation controllers serve fundamentally different power conversion needs across voltage ranges, load dynamics, and control precision requirements. Segmentation reveals where design complexity concentrates and which procurement criteria separate commodity from premium tiers.
Product Type:
Buyer selection hinges on efficiency targets and switching frequency requirements for specific load profiles.
- Synchronous Buck Converters:These architectures replace diode rectification with active MOSFET switches to cut conduction losses in step-down applications. Computing and telecom infrastructure OEMs in Taiwan and South Korea specify these for 2-5 MHz operation enabling magnetic miniaturization.
- Linear Controllers:Continuous conduction mode operation without switching noise suits precision analog subsystems in medical instrumentation and audio equipment. German and Japanese industrial OEMs specify these for sub-millivolt ripple requirements in sensor power rails.
- Boost Converters:Step-up voltage transformation for battery-powered portable electronics and automotive start-stop systems.
- H-Bridge Controllers:Bidirectional current flow management for DC motor drives and inverter stages in robotics.
Synchronous buck converters lead on scale; digital-ready variants in this category lead on momentum.
End User:
Volume concentration and margin structure diverge sharply across customer procurement patterns.
- Automotive Applications:AEC-Q100 qualification mandates 18-24 month certification cycles for traction inverters, battery management systems, and LED headlamp drivers. EV powertrain manufacturers in Germany and China now require firmware update capabilities as standard deliverables.
- Consumer Electronics:External power supply controllers face EU Ecodesign Directive standby power limits and US DOE International Efficiency Marking Protocol thresholds. Adapter OEMs in Shenzhen and Dongguan redesign feedback networks annually to meet tightening minimum performance standards.
- Industrial Equipment:Motor drive controllers for manufacturing automation prioritize proven reliability over algorithmic flexibility.
- Telecommunications:Rectifier and base station power supplies demand high-density conversion with 48V bus compatibility.
Automotive commands premium pricing; consumer electronics drives unit volume.
Technology:
Control architecture selection determines firmware flexibility, BOM cost, and engineering headcount requirements.
- Digital Control:Firmware-upgradable loops enable runtime parameter adjustment without physical component changes. Renewable energy inverter manufacturers and EV powertrain suppliers specify these for predictive maintenance telemetry and grid compliance updates.
- Analog Control:Fixed-function implementations with sub-microsecond loop response suit cost-sensitive high-volume applications. Legacy industrial motor drive installations in the US Midwest and European manufacturing clusters specify these for backward compatibility.
- Mixed Signal Control:Hybrid architectures balancing deterministic analog power stages with digital supervision.
- Firmware-Based:Software-defined control loops with full programmability for adaptive load response.
Analog control retains volume leadership; digital control gains share fastest in automotive and solar segments.
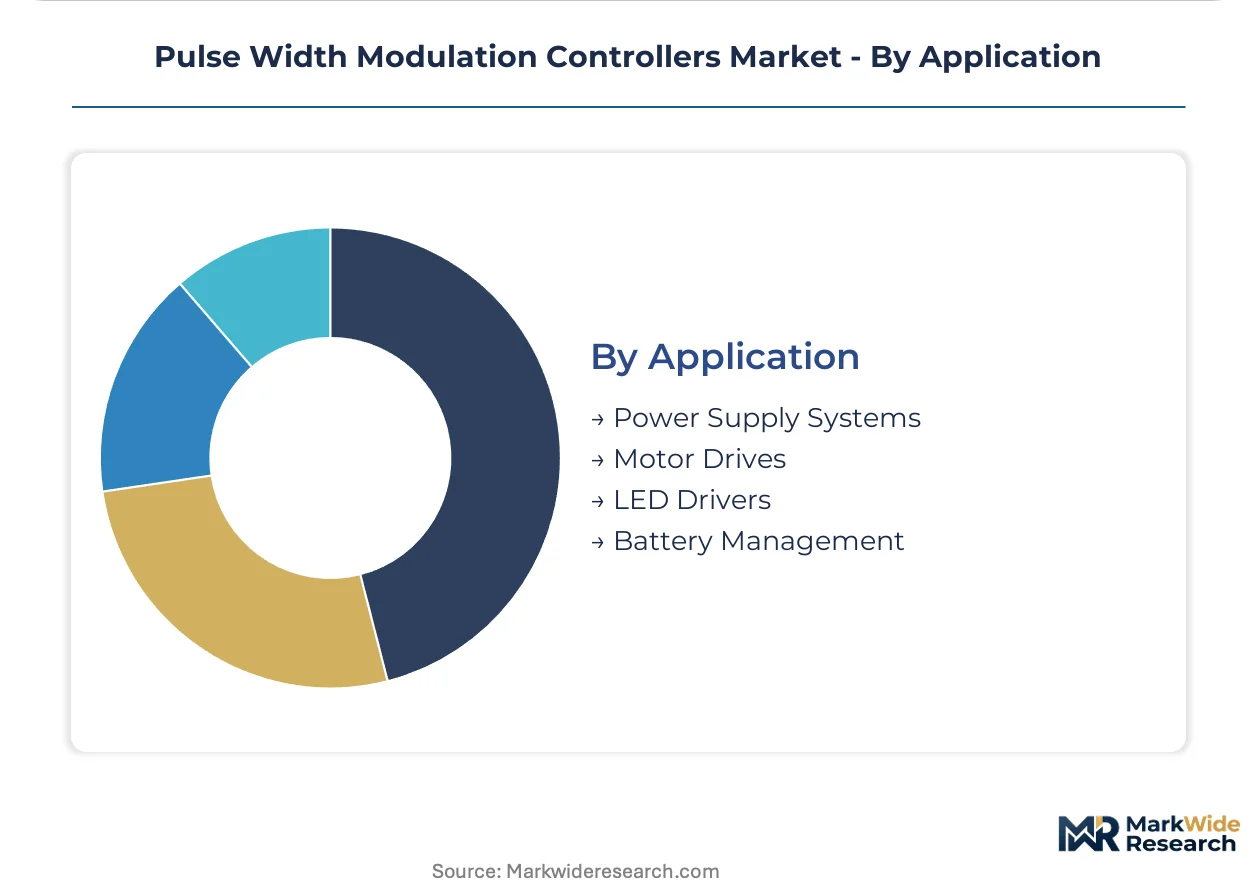
Application:
Functional integration requirements determine whether discrete controllers or subsystem-consolidated architectures prevail.
- Battery Management:Cell balancing, thermal monitoring, and charge control integration is concentrating procurement around unified platform architectures. EV battery pack manufacturers specify controllers with embedded state-of-charge algorithms.
- Power Supply Systems:AC-DC and DC-DC conversion for computing, telecom, and consumer devices spans adapter through rack-scale implementations. Efficiency regulations in California, the European Union, and China force controller redesigns across import portfolios.
- Motor Drives:Variable frequency control for industrial automation and appliance compressors.
- LED Drivers:Current regulation for solid-state lighting with dimming interface support.
Power supply systems dominate unit shipments; battery management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volumes for EV traction inverters while Germany enforces the strictest automotive qualification protocols, creating divergent competitive requirements across the two largest demand centers.
China
Domestic semiconductor fabs in Shanghai and Wuxi scale controller production for local EV and solar inverter supply chains. The Standardization Administration enforces GB standards for power conversion efficiency that create market access barriers for non-compliant imports. Shenzhen and Dongguan manufacturing clusters drive annual feedback network redesigns to meet tightening standby power thresholds.
Germany
EV powertrain manufacturers in Stuttgart and Munich mandate firmware update capabilities and predictive maintenance telemetry as standard deliverables. The KBA enforces AEC-Q100 qualification timelines that extend 18-24 months for safety-critical synchronous buck architectures. Bavarian industrial OEMs specify linear controllers for sub-millivolt ripple requirements in precision sensor power rails.
United States
Computing and telecom infrastructure OEMs specify synchronous buck converters for 2-5 MHz operation enabling magnetic component miniaturization. The DOE enforces minimum efficiency standards under the External Power Supply International Efficiency Marking Protocol. Midwest manufacturing clusters prioritize analog control for backward compatibility with legacy motor drive installations.
South Korea
Seoul-based computing and telecom OEMs drive specifications for high-density conversion with 48V bus compatibility. The MFDS coordinates with industrial regulators on medical instrumentation power requirements. Busan-Ulsan manufacturing clusters concentrate procurement for industrial motor drive controllers serving shipbuilding and heavy equipment sectors.
Japan
Tokyo and Osaka industrial OEMs specify mixed-signal control architectures balancing deterministic analog power stages with digital supervision. METI administers JIS standards for power conversion efficiency in consumer electronics and industrial equipment. Nagoya automotive suppliers concentrate design wins for safety-critical LED headlamp driver applications.
Pulse Width Modulation Controllers Market Competitive Landscape
Top-tier vendors anchor automotive and industrial segments, while mid-tier specialists occupy firmware-upgradable digital control niches. The vendor base stratifies across three tiers: integrated semiconductor conglomerates with captive silicon carbide substrate supply, analog-centric portfolios with dense control IP, and emerging digital specialists targeting renewable energy inverters. Competitive positioning depends on AEC-Q100 certification depth, switching frequency ceilings, and backward integration into wide-bandgap materials. M&A activity concentrates on digital control algorithm assets, while capacity expansion targets 300mm silicon carbide wafer supply.
Among integrated semiconductor conglomerates, ON Semiconductor, Texas Instruments, and Infineon Technology occupy positions representing distinct competitive archetypes. ON Semiconductor exemplifies backward integration into substrate supply for pricing power in EV traction applications. Texas Instruments anchors industrial motor drive design wins through analog control IP density. Infineon Technology sits within the automotive safety-critical tier through AEC-Q100 qualified synchronous buck architectures.
| Leading Market Players |
|---|
| ON Semiconductor |
| Maxim Integrated |
| Analog Devices |
| Vishay |
| Infineon Technology |
| Texas Instruments |
| Microchip Technology |
| Diodes Incorporated |
| STMicroelectronics |
| Others |
Value Network & Pricing Analysis
The EU Ecodesign Directive's standby power limits gate qualified supply access for premium-tier PWM controllers, compressing margins on non-compliant variants while elevating pricing power for AEC-Q100 certified architectures serving German and Chinese EV manufacturers.
Pricing Analysis
Capacity additions in China's domestic semiconductor fabs are reshaping price floors for commodity-grade controllers, forcing analog-centric suppliers toward firmware-upgradable digital variants. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer electronics tiers separates AEC-Q100 synchronous buck architectures from generic adapter controllers. Pricing pressure stems from silicon carbide wafer allocation bottlenecks concentrated among limited substrate manufacturers. Consumer electronics OEMs in Shenzhen manufacturing clusters exhibit highest price sensitivity, while German automotive Tier 1 suppliers accept premium positioning for predictive maintenance telemetry capabilities.
Supply Chain Analysis
End-of-life controller refurbishment flows remain underdeveloped, though EU battery regulations are mandating design-for-disclosure documentation that will reshape reverse logistics. Taiwan, South Korea, and China concentrate front-end wafer fabrication for power management ICs, while Malaysia and Vietnam host backend assembly and test operations. Silicon carbide substrates, gallium nitride epitaxy, and AEC-Q100 certification capacity represent critical input dependencies. Single-source vulnerability concentrates in 300mm silicon carbide wafer supply from Wolfspeed and Coherent. Distribution runs through authorized distributors serving industrial OEMs and direct allocation agreements with EV powertrain manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pulse Width Modulation Controllers Market functions as a regulatory compounder where tightening efficiency standards under the US DOE International Efficiency Marking Protocol and EU Ecodesign Directive generate replacement demand cycles independent of underlying volume growth.
For Market Incumbents: Acquire digital control algorithm IP assets to anchor firmware-upgradable platform architectures before analog-centric competitors close capability gaps. Deepen backward integration into silicon carbide substrate supply to defend margin position against raw material cost volatility from Wolfspeed and Coherent allocation constraints. Prioritize AEC-Q100 certification pipeline investments to maintain automotive safety-critical segment access against emerging Chinese domestic suppliers. For New Entrants and Emerging Players: The 40-60% price-point gap between automotive-qualified and consumer-grade controllers creates entry space for industrial-grade digital variants with programmable loops. Target India's grid modernization and renewable integration targets for industrial motor drive controller deployments where established German and Japanese suppliers lack localized service infrastructure. Pursue battery management subsystem convergence opportunities by integrating PWM control with cell balancing algorithms for EV pack manufacturers seeking unified platform architectures. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier digital control specialists because automotive qualification timelines extend 18-24 months, creating durable competitive moats around certified product portfolios. Target firms with embedded firmware capabilities and existing AEC-Q100 synchronous buck architectures rather than analog-only legacy portfolios. Monitor silicon carbide substrate allocation announcements as inflection indicators for controller margin compression or expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive wafer supply insulates ON Semiconductor and Infineon from allocation volatility in EV traction applications. |
| Firmware-Upgradable Architecture Development | Texas Instruments' digital control IP density anchors design wins in renewable energy inverter deployments. |
| AEC-Q100 Certification Pipeline Expansion | Extended qualification timelines gate automotive safety-critical segments against commodity controller imports. |
| India Manufacturing Cluster Localization | Grid modernization targets create unmet demand for industrial motor drive controllers beyond German-Japanese incumbents. |
| Battery Management Subsystem Convergence | Unified platform architectures integrating cell balancing with PWM control capture EV pack manufacturer procurement. |
Research Methodology
Coverage spans China, Germany, the United States, South Korea, and Japan, with primary inputs from each regional cluster combining structured interviews with power electronics procurement managers at EV powertrain manufacturers, analog design engineers at industrial motor drive OEMs, and semiconductor distribution channel partners. Secondary validation draws from SEC 10-K filings, Standardization Administration GB standard publications, KBA type-approval databases, and DOE efficiency compliance registries. Bottom-up shipment estimates by product type and end-use application triangulate against top-down semiconductor industry revenue aggregates.
Granularity-level modeling distinguishes synchronous buck, linear, boost, and H-bridge controller architectures across automotive, consumer electronics, industrial equipment, and telecommunications end-use segments. Technology-tier segmentation captures digital, analog, mixed-signal, and firmware-based control implementations. CAGRs derive from regression analysis of historical procurement patterns against regulatory milestone calendars and wide-bandgap semiconductor penetration curves. Forecast inputs include EV production volume trajectories, solar inverter deployment pipelines, and efficiency standard tightening schedules across California, the European Union, and China.
Caveats apply where silicon carbide substrate allocation disruptions, AEC-Q100 certification backlog extensions, or carbon border adjustment implementations could materially shift the outlook for regional cost competitiveness. Forecasts reflect documented assumptions regarding wide-bandgap semiconductor price erosion rates and digital control firmware development cost curves. Periodic stress-testing of base assumptions against actual procurement volume reports and qualification timeline updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Amplifier Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
North America USB Retimer Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Resonators Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Microcontroller Socket Market
Electronic Components
United States MLCC Market
Electronic Components
USB Charger Market
Electronic Components
Pneumatic Components Market