
 Additively Manufactured Lattice Structure Mechanical Test Systems Market | 2026-2036
Additively Manufactured Lattice Structure Mechanical Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Additively Manufactured Lattice Structure Mechanical Test Systems Market Insights
German metrology equipment producers is decoupling from legacy mechanical testing supply chains. Instron leverages its electromechanical actuator expertise to serve aerospace qualification labs. ZwickRoell anchors its position through German calibration standards and lattice-specific grip designs. MTS Systems competes with servo-hydraulic platforms tailored for high-cycle fatigue of titanium lattices.
Additively manufactured lattice structure mechanical test systems comprise instrumentation that applies controlled mechanical loads to periodic cellular architectures produced by powder bed fusion or directed energy deposition, measuring force-displacement response through ISO 6892-compliant extensometry to validate stiffness and yield strength for weight-optimized components. Universal testing machines dominate current installations for static compression of strut-based geometries, while fatigue testing systems capture expanding margin pools as qualification cycles lengthen for flight-critical applications. Electromechanical technology leads in academic settings, whereas servo-hydraulic platforms occupy aerospace OEM certification workflows demanding kilohertz data acquisition rates.
ASTM F42, ISO/ASTM 52900, and FAA airworthiness directives collectively shape validation protocols that equipment vendors must embed in control software and reporting templates. The EU AI Act and Machinery Directive add compliance layers for automated defect detection during in-situ mechanical characterization. Stakeholders must monitor how regulator convergence on strain-rate sensitivity standards for lattice materials alters capital equipment specifications and service contract structures.
Market Dynamics
ASTM F42 qualification protocols are compressing equipment procurement cycles as aerospace OEMs demand pre-certified testing platforms for flight-critical lattice components.
Growth Catalysts
- EU AI Act compliance mandates:Automated defect detection requirements for in-situ mechanical characterization are forcing test system upgrades across German aerospace certification labs.
- Titanium lattice fatigue qualification:Aerospace propulsion manufacturers are extending test cycles for high-cycle validation of powder bed fusion strut geometries.
- Fraunhofer validation protocols:German industrial consortia are standardizing architected material characterization methods that propagate through European supply chains.
Market Restraints
- High-purity titanium powder cost volatility:Feedstock price swings compress margins for lattice test coupon production and repeat qualification runs.
- Servo-hydraulic actuator supply concentration:Precision hydraulic component manufacturing clusters in Germany and Japan create single-source vulnerabilities.
- ISO/ASTM 52900 standardization gaps:Incomplete strain-rate sensitivity definitions delay mutual recognition agreements between FAA and EASA certification pathways.
Strategic Opportunities
- Directed energy deposition expansion:Large-format lattice structures for satellite bus components require adapted grip designs and extended stroke actuators.
- India PLI scheme for aerospace:Domestic additive manufacturing incentives are creating demand for localized mechanical test infrastructure.
- Digital twin convergence:Real-time sensor fusion between physical testing and predictive lattice deformation models compresses design iteration cycles.
Industry Challenges
- Extensometry calibration expertise scarcity:ISO 6892-compliant strain measurement for cellular architectures requires specialized technicians rarely found outside German metrology institutes.
- Multi-axis load frame integration complexity:Synchronizing biaxial compression-torsion sequences with high-speed data acquisition demands custom control software development.
- FAA airworthiness directive compliance timelines:Extended qualification documentation reviews delay revenue recognition on aerospace OEM contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additively Manufactured Lattice Structure Mechanical Test Systems Market |
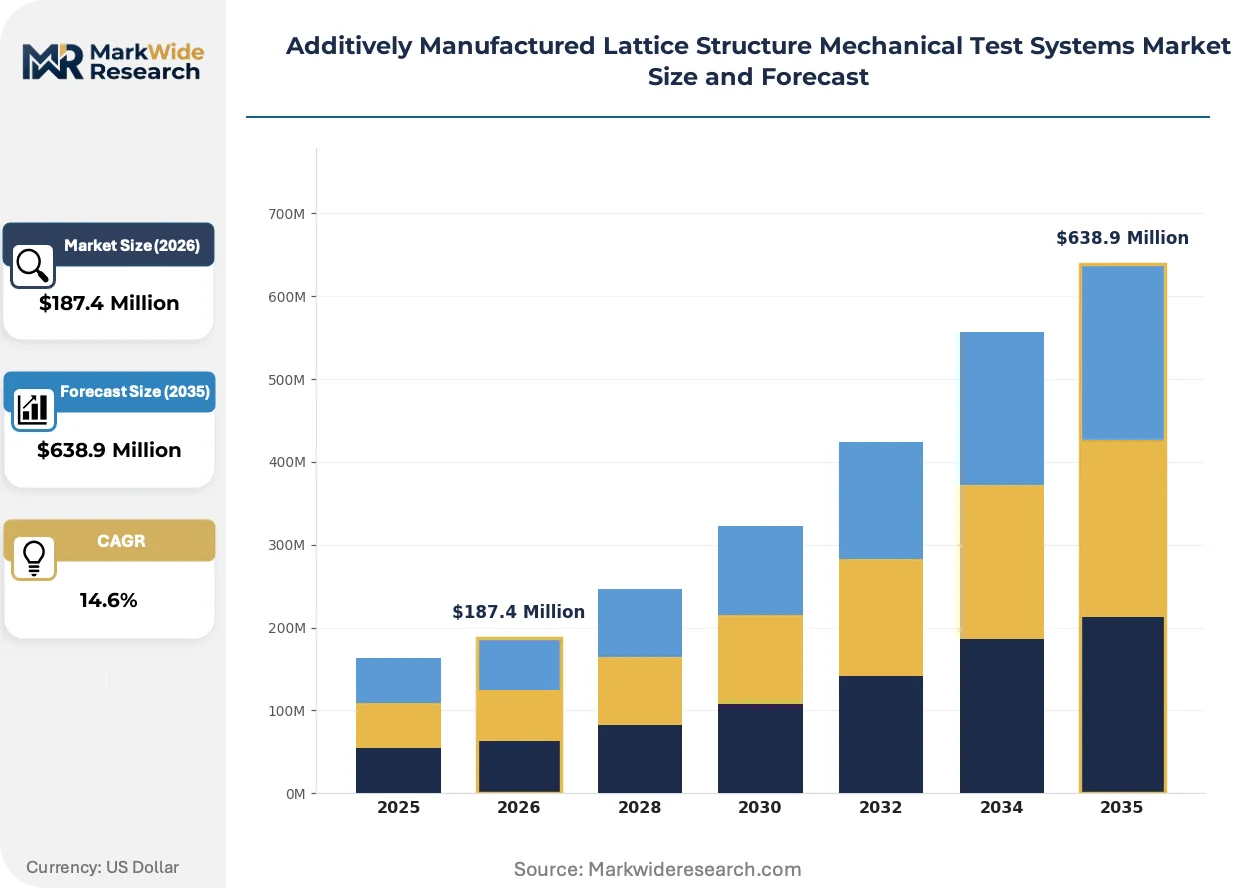
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Testing Machines, Fatigue Testing Systems, Hardness Testers, Impact Testers, Tensile Testing Devices Technology: Digital Load Cells, Servo-Hydraulic, Electromechanical, Pneumatic, Computer-Controlled, Digital Extensometers Application: Material Strength Analysis, Structural Integrity Assessment, Fatigue Life Evaluation, Deformation Behavior Study, Load Response Characterization End User: Research Laboratories, Aerospace OEMs, Automotive Tier-1 Suppliers, Academic Institutions, Composite Manufacturers |
| Companies Covered | Instron, ZwickRoell, Shimadzu, MTS Systems, TA Instruments, Hegewald & Peschke, AMETEK, Keysight Technologies, Torontech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additively Manufactured Lattice Structure Mechanical Test Systems Market Trends and Innovations
Digital thread integration is collapsing the boundary between design optimization and physical validation for architected materials.
Modular electromechanical load frames with swappable grip interfaces are decentralizing mechanical testing from centralized metrology labs toward satellite production facilities. SpaceX and Rocket Lab are embedding compact universal testing machines directly into launch vehicle manufacturing cells. This topology eliminates shipping delays for titanium lattice qualification coupons and compresses non-conformance response times from weeks to hours.
REACH substance restrictions on hexavalent chromium coatings are forcing grip surface treatment substitutions for corrosion-resistant lattice contact points. PVD ceramic coatings and diamond-like carbon films are displacing traditional electroplated finishes in European test equipment specifications. German calibration laboratories are validating these alternative surface engineering approaches under Machinery Directive conformity assessment procedures.
Buyer consolidation among tier-one aerospace contractors is compressing vendor qualification timelines and unbundling after-sales service contracts. Lockheed Martin and Northrop Grumman are demanding discrete pricing for installation, training, and maintenance rather than bundled lifecycle agreements. This shift is most visible in US Southwest defense corridors where prime contractors operate captive additive manufacturing centers with dedicated mechanical test cells.
Additively Manufactured Lattice Structure Mechanical Test Systems Market Segmentation
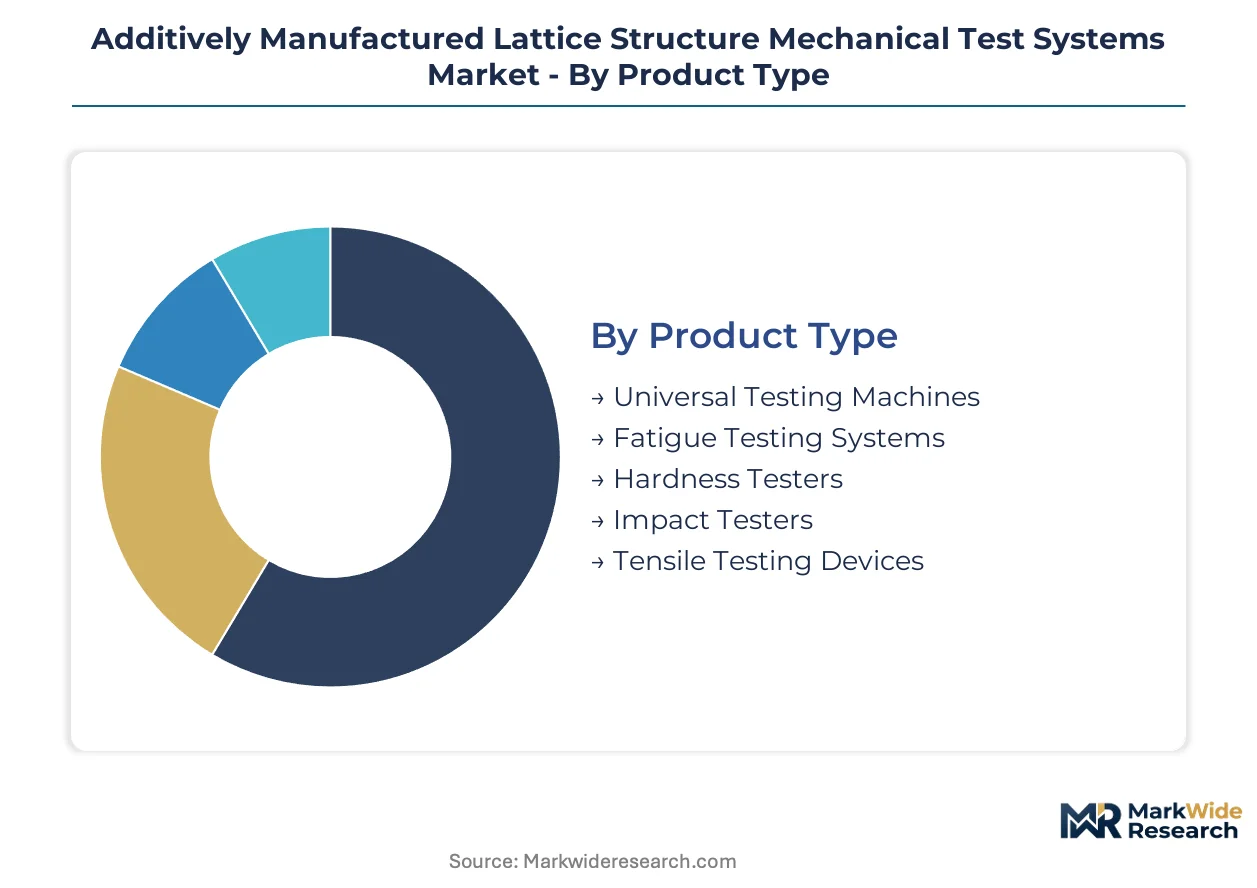
Segmentation in lattice structure testing equipment reflects divergent certification burdens across aerospace, automotive, and research verticals. Each product category and technology type carries distinct regulatory attachment points that shape procurement specifications and vendor qualification timelines.
Product Type:
Universal testing machines carry FAA airworthiness directive compliance obligations for static compression validation, while fatigue systems trigger extended EASA mutual recognition protocols for high-cycle titanium qualification.
- Universal Testing Machines:Electromechanical platforms dominate static compression workflows for strut-based geometries. German aerospace certification labs concentrate procurement here for ISO 6892-compliant stiffness validation of powder bed fusion components.
- Fatigue Testing Systems:Servo-hydraulic architectures enable kilohertz data acquisition for propulsion lattice qualification. Aerospace OEMs in the US Southwest defense corridor are extending test cycles for flight-critical titanium strut geometries under FAA oversight.
- Hardness Testers:Indentation-based characterization supports rapid coupon screening at satellite production facilities.
- Impact Testers:Drop-weight configurations validate energy absorption in crash-optimized automotive lattice structures.
- Tensile Testing Devices:Compact units embed directly into launch vehicle manufacturing cells for real-time non-conformance response.
Leading the category by volume: Universal Testing Machines. Expanding most quickly: Fatigue Testing Systems.
Technology:
Technology selection hinges on data acquisition rate requirements and the regulatory body's preferred measurement traceability chain.
- Digital Load Cells:Strain-gauge-based force measurement provides NIST-traceable calibration paths for aerospace OEM acceptance criteria. Fraunhofer institutes specify these for German industrial consortia validation protocols.
- Servo-Hydraulic:Precision hydraulic actuators deliver the frequency response needed for high-cycle fatigue of directed energy deposition lattices. Manufacturing concentration in Germany and Japan creates supply vulnerability.
- Electromechanical:Ball-screw actuation suits academic settings with moderate throughput requirements.
- Pneumatic:Compressed-air drives enable cleanroom-compatible testing for satellite bus component qualification.
- Computer-Controlled:Integrated software platforms embed ASTM F42 reporting templates for automated compliance documentation.
- Digital Extensometers:Non-contact strain measurement addresses cellular architecture compliance challenges under EU Machinery Directive conformity assessment.
Highest certification burden: Servo-Hydraulic. Fastest technology refresh cycle: Digital Extensometers.
Application:
Application segmentation maps directly to qualification stage and the corresponding regulatory documentation depth.
- Material Strength Analysis:Yield strength and stiffness characterization forms the foundation of ASTM F42 qualification protocols. Research laboratories in Germany anchor demand for ISO 6892-compliant extensometry.
- Structural Integrity Assessment:Non-destructive evaluation of defect populations under load triggers EU AI Act automated detection mandates for in-situ mechanical characterization.
- Fatigue Life Evaluation:High-cycle validation for flight-critical applications demands extended test protocols under FAA airworthiness directives.
- Deformation Behavior Study:Digital twin convergence compresses design iteration cycles through real-time sensor fusion.
- Load Response Characterization:Multi-axis sequences synchronize biaxial compression-torsion with high-speed data acquisition.
Deepest regulatory attachment: Fatigue Life Evaluation. Steepest expansion trajectory: Structural Integrity Assessment.
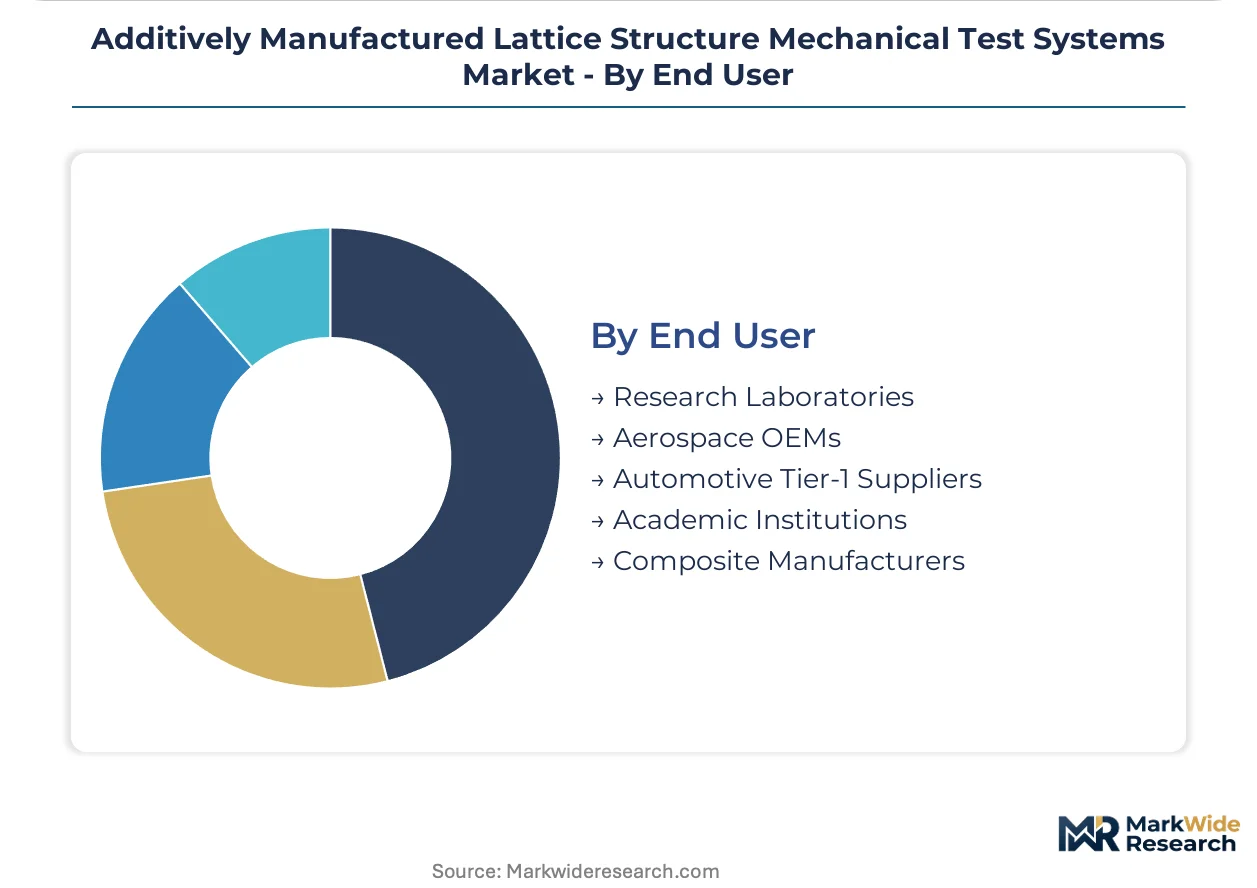
End User:
End-user type determines procurement centralization versus distributed testing topology and the associated service contract structure.
- Research Laboratories:Fraunhofer institutes and German metrology centers drive validation protocol standardization that propagates through European supply chains. Electromechanical platforms dominate these installations.
- Aerospace OEMs:Lockheed Martin and Northrop Grumman operate captive additive manufacturing centers with dedicated test cells, unbundling after-sales service contracts into discrete pricing for installation, training, and maintenance.
- Automotive Tier-1 Suppliers:Crash-optimized lattice adoption drives hardness and impact testing demand for lightweight structural components.
- Academic Institutions:Budget constraints favor modular electromechanical load frames with swappable grip interfaces.
- Composite Manufacturers:Satellite bus component producers require adapted grip designs and extended stroke actuators for large-format lattice structures.
Category volume leader: Research Laboratories. Gaining share fastest: Aerospace OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium powder production clusters in Germany's Ruhr region anchor European qualification workflows for flight-critical lattice components. Aerospace OEMs source feedstock from this corridor to supply mechanical test coupon programs across multiple jurisdictions.
United States
Aerospace propulsion manufacturers in the US Southwest defense corridor extend high-cycle fatigue validation for powder bed fusion strut geometries. FAA airworthiness directives compress equipment procurement timelines for captive additive manufacturing centers. Lockheed Martin and Northrop Grumman operate dedicated test cells in California and Texas with discrete service contract unbundling.
Germany
Fraunhofer institutes and industrial consortia standardize architected material characterization methods that propagate through European supply chains. EU AI Act automated defect detection mandates force test system upgrades across Bavarian and Baden-Württemberg certification labs. Stuttgart and Munich anchor metrology equipment production decoupled from legacy mechanical testing supply chains.
Japan
Precision hydraulic actuator manufacturing concentrates in Osaka and Nagoya industrial zones, creating supply vulnerability for servo-hydraulic fatigue platforms. METI standards alignment with ASTM F42 protocols enables Japanese aerospace tier-1 suppliers to access US and European OEM qualification workflows. JIS-compliant calibration chains support domestic lattice research programs.
India
PLI scheme incentives for domestic additive manufacturing create demand for localized mechanical test infrastructure in Karnataka and Telangana. Bangalore and Hyderabad host emerging satellite production facilities requiring adapted grip designs for large-format lattice structures. BIS standards development lags ASTM F42 adoption, delaying mutual recognition with FAA certification pathways.
United Kingdom
Research laboratories in the Midlands and Southeast anchor electromechanical platform demand for ISO 6892-compliant stiffness validation. UK Space Agency funding for satellite bus component programs drives extended stroke actuator requirements. REACH substance restrictions on hexavalent chromium coatings force grip surface treatment substitutions in British test equipment specifications.
Additively Manufactured Lattice Structure Mechanical Test Systems Market Competitive Landscape
Global majors compete with regional champions across calibration standard authority and grip design specialization. The vendor base stratifies into three tiers: precision metrology incumbents with embedded aerospace relationships, mid-scale electromechanical specialists serving academic markets, and emerging Asian fabricators competing on modular platform cost. Two dominant competitive moves define current positioning: technology licensing partnerships to embed ASTM F42 compliance templates, and backward integration into digital extensometry sensor production.
Among German precision metrology incumbents, ZwickRoell and Hegewald & Peschke exemplify the calibration-anchored archetype, leveraging domestic standards authority to propagate grip designs through European aerospace supply chains. Instron occupies a position representing the electromechanical technology vector, while MTS Systems anchors the servo-hydraulic tier for high-frequency fatigue applications. Shimadzu exemplifies the Asian specialist archetype competing on modular platform accessibility for research laboratory procurement.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| Shimadzu |
| MTS Systems |
| TA Instruments |
| Hegewald & Peschke |
| AMETEK |
| Keysight Technologies |
| Torontech |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up precision metrology specialists anchor pricing discipline through captive calibration service revenues and long-term aerospace OEM service contracts. Their consolidated grip on German standards authority enables premium positioning for ASTM F42-compliant platforms while compressing margin pools for unbundled hardware-only transactions.
Pricing Analysis
Warranty and service bundling separates aerospace OEM procurement from academic laboratory purchasing, with flight-critical qualification workflows commanding integrated lifecycle agreements. Three-tier pricing structure across premium certification-grade, standard industrial, and economy research-tier levels reflects ASTM F42 compliance depth and data acquisition rate specifications. Cost compression in economy-tier electromechanical platforms intensifies as modular Asian fabricators displace legacy European suppliers. Academic institutions exhibit highest price sensitivity due to budget constraints and grant-funded procurement cycles, whereas aerospace OEMs prioritize qualification speed over unit economics.
Supply Chain Analysis
Certification and qualification gating concentrates precision hydraulic actuator manufacturing in Germany and Japan, creating single-source vulnerabilities for servo-hydraulic fatigue platforms. High-purity titanium powder feedstock draws from German Ruhr region production clusters, while strain-gauge load cells and digital extensometry sensors source from Japanese and US semiconductor fabrication networks. Commodity price volatility in aerospace-grade titanium powder compresses test coupon production margins. Distribution runs through direct OEM relationships for flight-critical applications and regional distributor networks for research laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as digital extensometry and real-time sensor fusion displace legacy contact-based strain measurement systems. Electromechanical platforms with embedded compliance software are capturing share from hydraulic architectures in mid-cycle qualification workflows.
For Market Incumbents: Extend ASTM F42 template licensing partnerships to software-agnostic platform providers, preventing modular competitors from embedding compliance documentation. Deepen backward integration into digital extensometry sensor production to defend margin position against Asian component suppliers. Lockheed Martin and Northrop Grumman unbundling of service contracts threatens recurring revenue streams; respond with discrete pricing transparency for installation, training, and maintenance.
For New Entrants and Emerging Players: Direct-to-research-laboratory digital channels enable bypass of German calibration authority gatekeeping for economy-tier electromechanical platforms. Target Indian PLI scheme beneficiaries in Karnataka and Telangana satellite production corridors, where localized mechanical test infrastructure demand outpaces established vendor qualification timelines. White-space exists in compact tensile testing devices for launch vehicle manufacturing cell embedding, following SpaceX and Rocket Lab topology decentralization.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale electromechanical specialists with modular platform architectures and existing academic distribution relationships in US Midwest and UK Midlands research clusters. Long-term viability hinges on digital twin convergence capability and sensor fusion software development. The signal to monitor is FAA-EASA mutual recognition agreement progress on strain-rate sensitivity standards, which would trigger capital equipment refresh cycles across aerospace OEM certification labs.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F42 Compliance Template Licensing | Software embedding with aerospace OEM control systems accelerates vendor qualification timelines. |
| Backward Integration into Digital Extensometry | In-house sensor production captures margin pools from Japanese semiconductor suppliers. |
| Modular Platform Geographic Expansion | Compact electromechanical units penetrate Indian PLI scheme satellite production facilities. |
| Service Contract Unbundling Response | Discrete pricing for installation, training, and maintenance aligns with Lockheed Martin procurement shifts. |
| Digital Twin Convergence Development | Real-time sensor fusion with predictive lattice deformation models compresses design iteration cycles. |
Research Methodology
SEC filings from precision metrology equipment manufacturers, FAA airworthiness directive documentation, and German Fraunhofer institute validation protocol publications formed the secondary backbone for market sizing and competitive positioning. Primary interviews with test system procurement managers at aerospace OEMs, calibration laboratory directors, additive manufacturing center engineers, and university research facility managers combined with secondary validation through ASTM F42 committee meeting records and ISO/ASTM 52900 standard development drafts. Bottom-up equipment installation counts triangulated against top-down aerospace R&D expenditure allocation trends.
Historical trendline analysis of electromechanical and servo-hydraulic platform shipments across product type, technology, application, and end-user segmentation dimensions informed projection modeling. CAGRs were derived from regression analysis of qualification cycle extension patterns and regulatory compliance burden intensification. Industry-specific forecast inputs incorporated titanium lattice fatigue test protocol lengthening under FAA oversight and EU AI Act automated defect detection mandate implementation timelines.
The model holds under continued ASTM F42 protocol refinement and stable aerospace OEM R&D budgets; deviation in FAA-EASA mutual recognition timelines or titanium powder supply disruption would shift equipment procurement trajectories. Forecasts reflect assumptions regarding regulatory convergence pace and digital twin technology adoption rates across qualification workflows. A model refresh is warranted upon material change in strain-rate sensitivity standard harmonization or PLI scheme incentive restructuring in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Global Conductivity Meters Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Force Gauge Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Metrology and Inspection Equipment Market