
 Thyristor Market | 2026-2036
Thyristor Market Size, Share, and Industry Trends Forecast 2026-2036
Thyristor Market Analysis
Modular packaging of thyristor subassemblies is rebalancing procurement patterns across power electronics buyers. Infineon Technologies AG leverages captive silicon foundry capacity to dominate insulated-gate bipolar thyristor hybrids. Mitsubishi Electric Corporation anchors Japanese HVDC infrastructure with proprietary gate-commutated designs. ON Semiconductor Corporation specializes in automotive-grade thyristor modules for traction inverter systems.
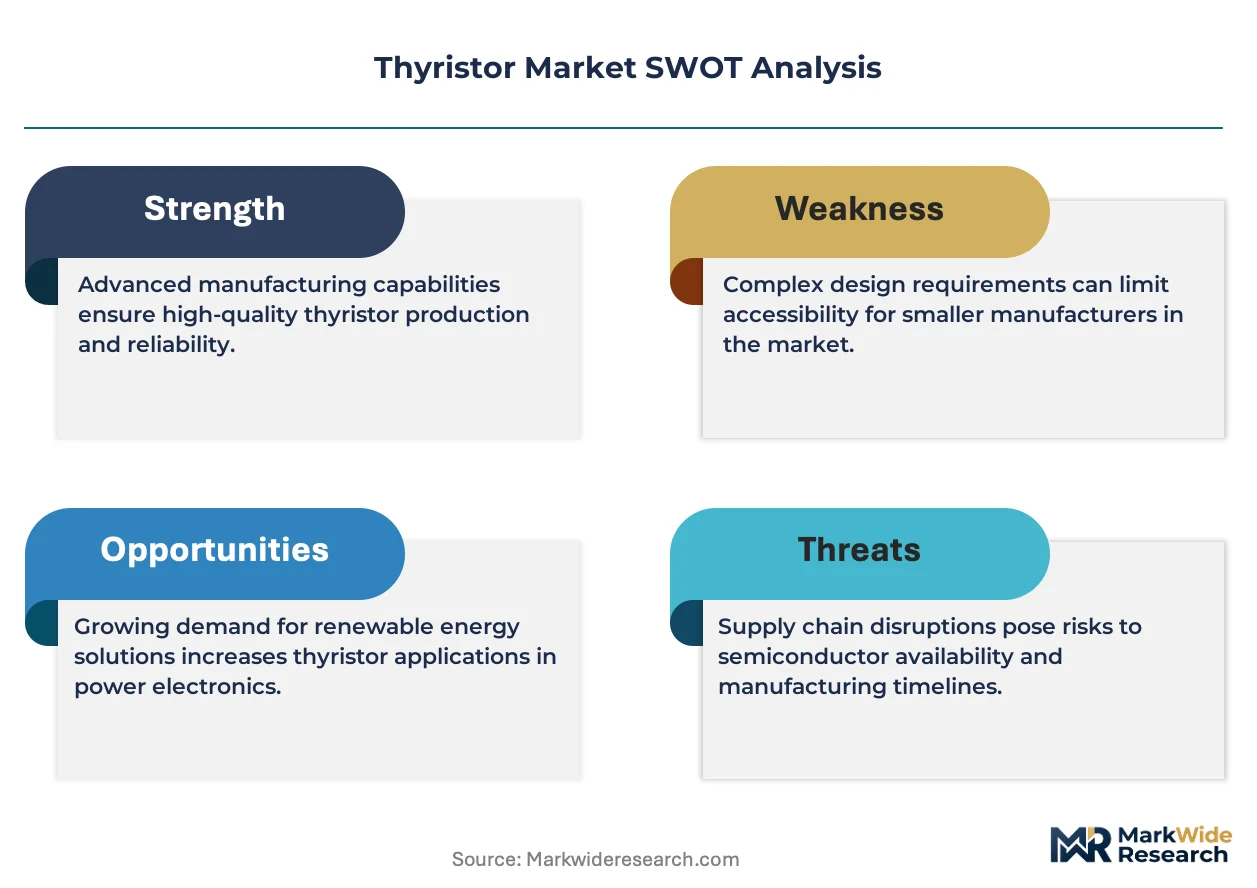
A thyristor is a four-layer semiconductor device with alternating P-type and N-type doping, triggered into conduction by a gate pulse and latching until current falls below a holding threshold; its primary purpose is controlling high-power AC and DC circuits in industrial and grid-scale applications. Silicon thyristor variants retain the largest installed base across power utilities, though integrated gate commutated thyristors capture margin pools in medium-voltage motor drives where fast switching reduces thermal losses. Voltage regulation applications mature alongside legacy grid infrastructure, while power switching segments expand with renewable inverter deployments requiring bidirectional fault protection.
FCC electromagnetic interference rules in the US constrain thyristor switching frequencies in consumer-facing equipment, while EU REACH substance restrictions govern semiconductor-grade silicon and dopant chemistries. India's BIS certification mandates thermal cycling tests for panel-mounted industrial thyristors, creating compliance barriers for unqualified imports. Stakeholders must track gate-oxide reliability standards and wide-bandgap material substitution timelines to preserve technology positioning.
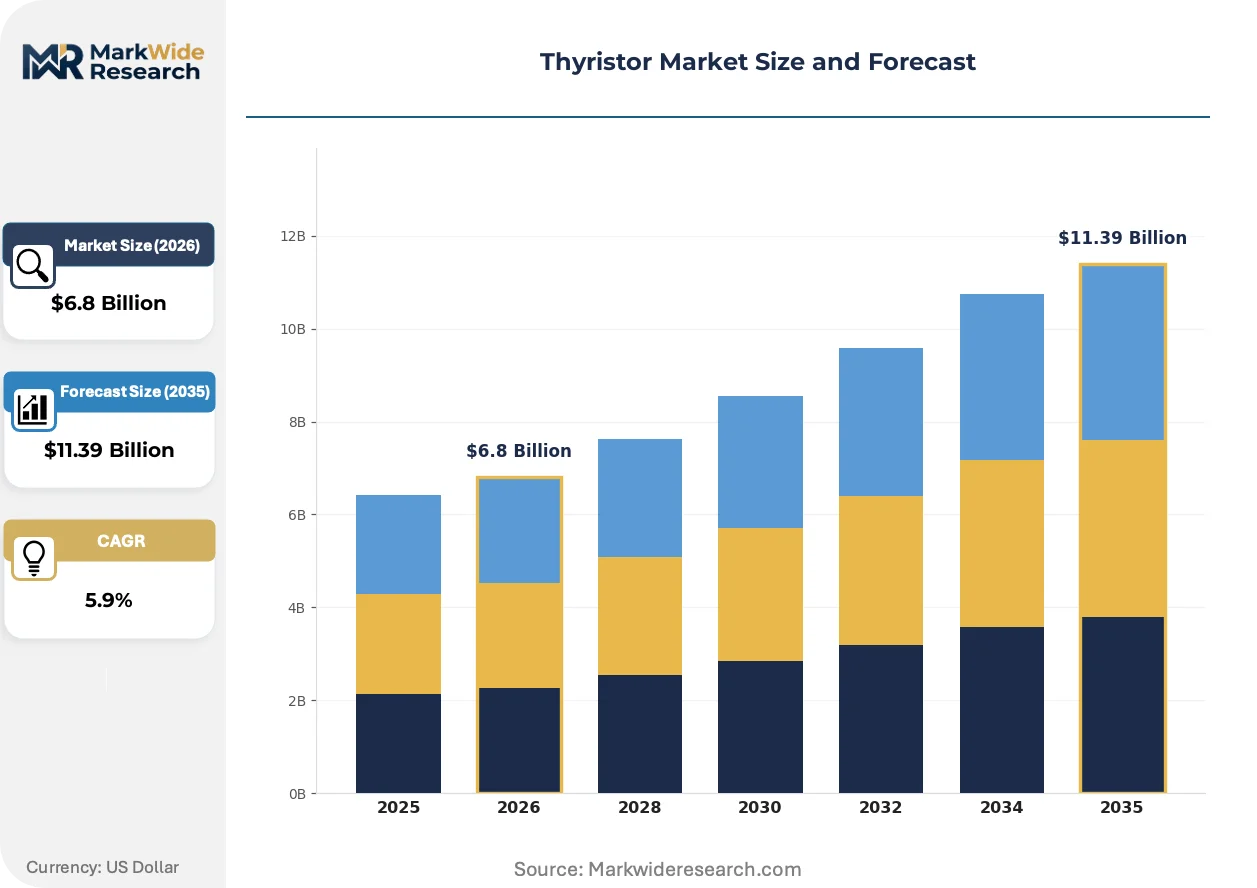
Market Dynamics
Silicon carbide hybrid thyristor architectures are compressing thermal management costs while MIIT efficiency mandates in China force incumbent suppliers to redirect R&D budgets away from legacy silicon platforms.
Growth Catalysts
- HVDC Transmission Buildouts:Power utilities across Asia-Pacific are expanding procurement for high-voltage direct current systems, with India's transmission upgrade programs and renewable integration projects concentrating demand.
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology regulations are redirecting supplier R&D budgets toward silicon carbide hybrid designs and away from legacy platforms.
- Gate-Commutated Thyristor Adoption:Integrated gate commutated thyristors capture margin pools in medium-voltage motor drives where fast switching reduces thermal losses.
Market Restraints
- Silicon Carbide Substrate Costs:Wide-bandgap material substrates command premium pricing that compresses margins for hybrid thyristor manufacturers.
- Foundry Concentration Risk:Captive silicon foundry capacity concentrates among a limited supplier base, creating bottlenecks for insulated-gate bipolar thyristor hybrids.
- FCC Switching Frequency Limits:US Federal Communications Commission electromagnetic interference rules constrain thyristor switching frequencies in consumer-facing equipment.
Strategic Opportunities
- India Transmission Modernization:State-owned power utilities are accelerating panel-mounted industrial thyristor procurement under BIS certification mandates that create compliance barriers for unqualified imports.
- Automotive Traction Inverters:Electric vehicle manufacturers are specifying automotive-grade thyristor modules for traction inverter systems requiring bidirectional fault protection.
- EU REACH Substance Compliance:Semiconductor-grade silicon and dopant chemistry restrictions under European Chemicals Agency frameworks favor suppliers with pre-qualified material supply chains.
Industry Challenges
- Gate-Oxide Reliability Certification:Extended thermal cycling test timelines under India's BIS standards delay product qualification for panel-mounted industrial applications.
- Wide-Bandgap Integration Complexity:Hybrid silicon carbide designs require reconfigured thermal interfaces and packaging architectures that strain legacy manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyristor Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Thyristor, Gate Turn-Off Thyristor, Integrated Gate Commutated Thyristor, Programmable Unidirectional Thyristor End User: Power Utilities, Automotive, Industrial Equipment, Consumer Electronics Application: Motor Control, Light Dimmer, Voltage Regulation, Power Switching Installation: Panel Mounted, PCB Mounted, Module, In-Line |
| Companies Covered | Infineon Technologies AG, ON Semiconductor Corporation, STMicroelectronics N.V., ABB Ltd., Fuji Electric Co. Ltd., Mitsubishi Electric Corporation, Siemens AG, Vishay Intertechnology Inc., SEMIKRON International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyristor Market Emerging Trajectories
Material substitution timelines and packaging modularity are compressing traditional product lifecycles while regulatory chemistry restrictions reshape supplier qualification requirements.
Silicon carbide hybrid thyristor designs combine wide-bandgap substrates with conventional silicon control layers to slash thermal resistance in high-power switching applications. Power utilities and renewable inverter OEMs are adopting these hybrids at accelerating pace for HVDC converter stations and grid-scale storage interfaces. This material convergence is electrifying competitive positioning among semiconductor suppliers with captive substrate supply.
EU REACH substance restrictions governing semiconductor-grade silicon and dopant chemistries are forcing foundry customers to requalify material supply chains. Industrial consequence includes extended certification timelines and supplier consolidation around pre-qualified chemistry providers. Thyristor manufacturers serving European industrial motor drive markets are responding by backward integrating into dopant material sourcing.
Modular packaging of thyristor subassemblies is fragmenting traditional integrated module procurement. Power electronics buyers are unbundling gate driver circuits from power semiconductor stacks and sourcing through specialized subassembly distributors. This procurement pattern change is most visible in German and Japanese industrial automation markets where maintenance-driven replacement cycles favor field-serviceable component architectures.
Thyristor Market Segmentation
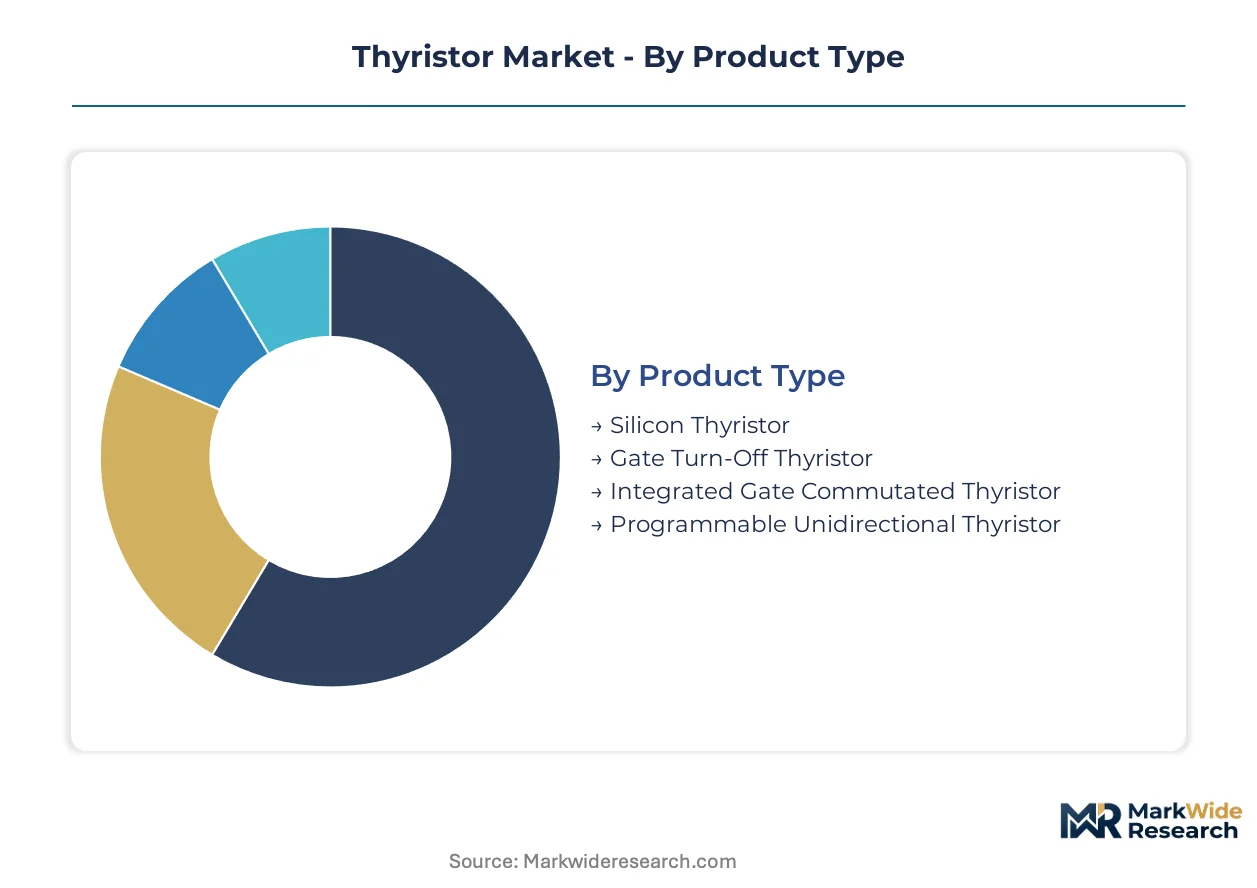
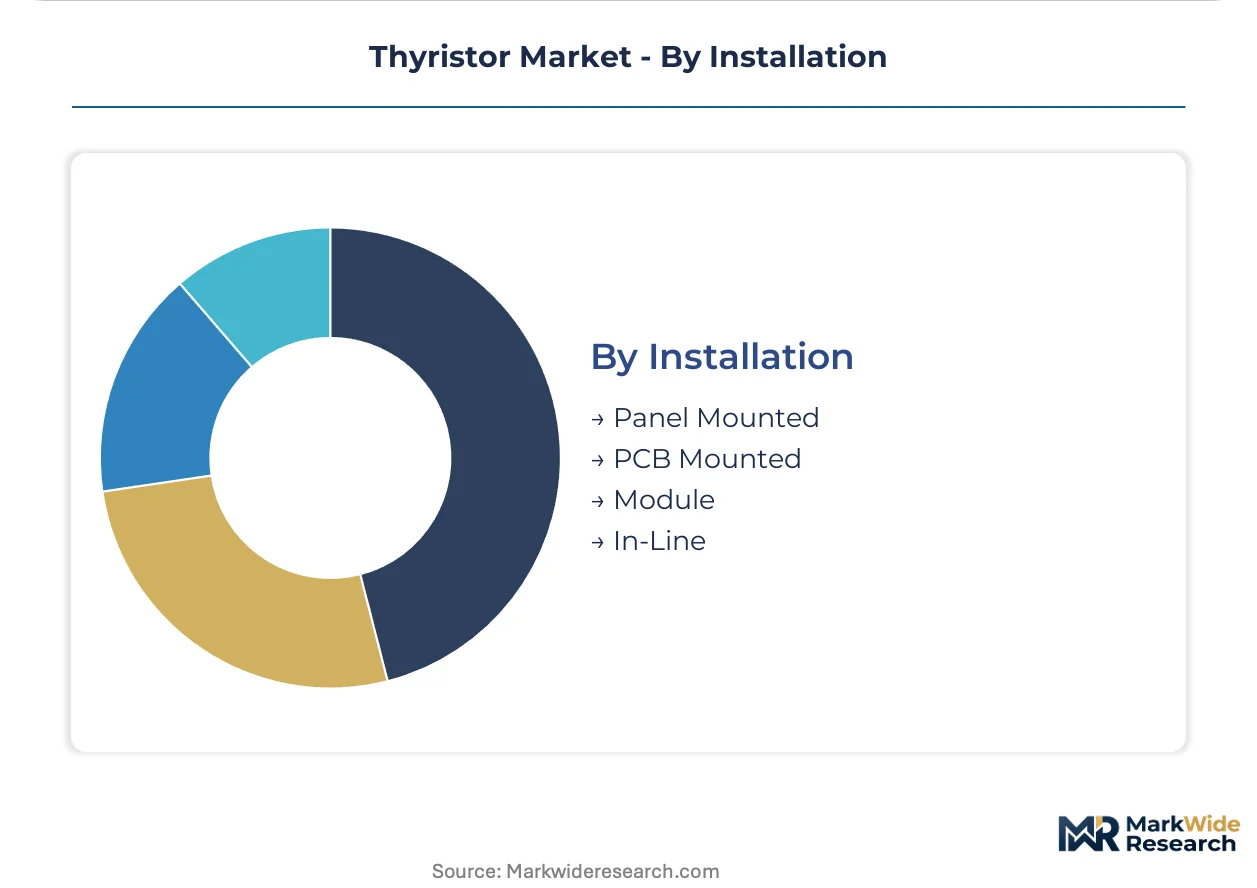
Thyristor procurement patterns fragment sharply across product architectures and installation formats. Buyers unbundle gate driver circuits from power stacks in industrial automation markets. Voltage regulation and motor control applications demand divergent switching speed specifications.
Product Type:
Supply concentration in silicon foundry capacity tilts competitive positioning toward suppliers with captive wafer production.
- Silicon Thyristor:Four-layer semiconductor with alternating P-type and N-type doping triggered by gate pulse and latching until current drops below holding threshold. Power utilities across India and China specify these for HVDC transmission infrastructure under BIS and MIIT certification regimes.
- Integrated Gate Commutated Thyristor:Combines fast switching capability with high blocking voltage for medium-voltage motor drives. Demand concentrates in German and Japanese industrial automation where reduced thermal losses justify premium procurement.
- Gate Turn-Off Thyristor:Permits current interruption via negative gate pulse without commutation circuit.
- Programmable Unidirectional Thyristor:Features adjustable trigger characteristics for specialized protection circuits.
Today's leader: Silicon Thyristor. Tomorrow's challenger: Integrated Gate Commutated Thyristor.
End User:
Cost tier stratification separates automotive-grade qualification requirements from industrial equipment procurement cycles.
- Power Utilities:Grid-scale HVDC converter stations and transmission upgrade programs in India and China anchor procurement volume. State-owned utilities specify panel-mounted industrial thyristors under BIS thermal cycling mandates that screen unqualified imports.
- Automotive:Electric vehicle traction inverter systems require automotive-grade thyristor modules with bidirectional fault protection. OEMs in Germany and Japan specify these for regenerative braking and motor control subassemblies.
- Industrial Equipment:Motor drives and welding systems in German automation clusters.
- Consumer Electronics:Light dimmer and small appliance applications constrained by FCC electromagnetic interference rules on switching frequencies.
Power utilities command premium pricing for certified HVDC components. Automotive represents the steepest expansion trajectory as electrification accelerates.
Application:
Volume concentration in motor control reflects industrial automation replacement cycles across Japanese and German manufacturing bases.
- Motor Control:Variable frequency drives and traction systems require thyristors with precise phase-angle control. Demand clusters in medium-voltage industrial motor installations where fast-switching integrated gate commutated variants reduce thermal management costs.
- Power Switching:Renewable inverter deployments and grid-scale storage interfaces specify hybrid silicon carbide designs. China's MIIT efficiency mandates redirect supplier R&D toward these architectures for HVDC converter stations.
- Voltage Regulation:Legacy grid infrastructure and uninterruptible power supplies.
- Light Dimmer:Residential and commercial lighting control facing FCC frequency constraints.
Motor control holds installed base dominance. Power switching gains share fastest from renewable integration.
Installation:
Customer type divergence separates field-serviceable industrial architectures from compact consumer-facing formats.
- Panel Mounted:Industrial thyristor assemblies for power utilities and heavy equipment. India's BIS certification mandates extended thermal cycling tests that delay qualification for unqualified import suppliers.
- Module:Standardized subassemblies enabling procurement unbundling of gate drivers from power stacks. German and Japanese industrial buyers favor these for maintenance-driven replacement cycles.
- PCB Mounted:Compact surface-mount packages for consumer electronics and automotive auxiliary systems.
- In-Line:Discrete component formats for legacy equipment repair and aftermarket supply.
Module formats capture margin pools from procurement pattern fragmentation. Panel mounted defends position through regulatory certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thyristor manufacturing originated in the United States during the 1950s at General Electric's research laboratories in Schenectady, New York, where the silicon-controlled rectifier was first commercialized. German and Japanese industrial electronics sectors subsequently scaled production for heavy electrical equipment through the 1970s and 1980s. Today, procurement concentrates in Asia-Pacific transmission infrastructure and European industrial automation clusters.
China
State Grid Corporation procurement for ultra-high-voltage direct current projects drives thyristor volume demand across converter stations in Anhui and Zhejiang provinces. MIIT efficiency mandates under the 14th Five-Year Plan redirect supplier R&D budgets toward silicon carbide hybrid architectures and away from legacy silicon platforms. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou host captive silicon foundry capacity for insulated-gate bipolar thyristor hybrids.
India
Power Grid Corporation transmission upgrade programs and renewable integration projects concentrate procurement for panel-mounted industrial thyristors. BIS certification mandates thermal cycling tests that delay qualification timelines and screen unqualified import suppliers from state-owned utility tenders. Gujarat and Maharashtra industrial corridors anchor domestic assembly operations for HVDC converter components.
Germany
Siemens Energy and industrial automation OEMs specify integrated gate commutated thyristors for medium-voltage motor drives where fast switching reduces thermal losses. EU REACH substance restrictions govern semiconductor-grade silicon and dopant chemistries, favoring suppliers with pre-qualified material supply chains. Bavarian and Baden-Württemberg manufacturing clusters specialize in modular thyristor subassemblies for maintenance-driven replacement cycles.
Japan
METI-supported smart grid investments sustain demand for gate-commutated thyristor designs in HVDC interconnection projects between Honshu and Hokkaido. JIS standards govern reliability specifications for industrial thyristor modules deployed in heavy electrical equipment. Kansai region Osaka-Kobe industrial zone maintains specialized foundry capacity for high-blocking-voltage thyristor wafers.
United States
FERC interconnection standards and utility-scale renewable deployments drive procurement for power switching thyristors in grid-scale storage interfaces. FCC electromagnetic interference rules constrain switching frequencies in consumer-facing equipment, limiting addressable market scope for residential applications. Texas and California utility procurement offices specify bidirectional fault protection requirements for renewable inverter integrations.
Thyristor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-specific performance tiers. The vendor base stratifies into three concentration levels: multinational semiconductor conglomerates with captive silicon foundry capacity, specialized power electronics module assemblers, and regional distributors serving maintenance replacement cycles. Two dominant competitive moves are reshaping positioning: backward integration into dopant material sourcing to satisfy EU REACH compliance timelines, and modular unbundling of gate driver circuits from power semiconductor stacks to capture maintenance-driven procurement fragmentation.
Within the diversified semiconductor conglomerate tier, Infineon Technologies AG, Mitsubishi Electric Corporation, and ON Semiconductor Corporation exemplify divergent strategic anchoring. Infineon leverages German-based captive silicon foundry capacity to dominate insulated-gate bipolar thyristor hybrid supply. Mitsubishi Electric anchors Japanese HVDC infrastructure positioning through proprietary gate-commutated design heritage. ON Semiconductor occupies automotive-grade module specialization for electric vehicle traction inverter specifications requiring bidirectional fault protection.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| ON Semiconductor Corporation |
| STMicroelectronics N.V. |
| ABB Ltd. |
| Fuji Electric Co. Ltd. |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Vishay Intertechnology Inc. |
| SEMIKRON International GmbH |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between BIS-qualified panel-mounted thyristors and unqualified commodity imports manifests in divergent pricing power and supply chain control. Premium-tier suppliers command captive silicon foundry pricing while commodity traders face margin compression from India's thermal cycling test barriers and China's MIIT efficiency redirection.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-certified, and economy unbranded tiers anchors thyristor procurement. Price differentiation hinges on BIS/MIIT certification status and captive wafer production scale. Cost compression in silicon carbide hybrid architectures intensifies as Yangtze River Delta foundries absorb substrate premiums. Automotive OEMs exhibit lowest price sensitivity; state-owned utilities in India negotiate hardest on volume tenders.
Supply Chain Analysis
Freight cost volatility from silicon carbide substrate shipments between China, Japan, and Germany strains just-in-time delivery for HVDC converter stations. Raw material procurement draws from semiconductor-grade silicon wafers, dopant chemistries, and ceramic packaging substrates. Single-source vulnerability concentrates in Yangtze River Delta captive foundry capacity. Distribution runs through specialized power electronics distributors serving German and Japanese industrial automation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in silicon carbide hybrid architectures where thermal management cost reductions offset substrate premiums. Suppliers with backward-integrated dopant sourcing capture EU REACH compliance rents.
For Market Incumbents: Acquire captive silicon carbide substrate capacity to defend against wide-bandgap substitution threats. Deepen BIS certification pipelines for India's state-owned utility tenders. Prioritize gate-oxide reliability R&D to extend thermal cycling performance leadership. For New Entrants and Emerging Players: Launch via modular subassembly distribution partnerships in German and Japanese maintenance replacement markets. Target unbundled gate driver procurement fragmentation. Exploit white space in automotive-grade thyristor modules for electric vehicle traction inverters. For Investors and Strategic Acquirers: Consolidation pressure builds where EU REACH pre-qualified material supply chains concentrate among limited dopant chemistry providers. Five-to-ten year viability favors semiconductor conglomerates with captive foundry and substrate integration. Watch silicon carbide hybrid adoption rates in China's State Grid UHVDC projects as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dopant Sourcing | EU REACH compliance timelines favor suppliers with pre-qualified semiconductor-grade silicon chemistry supply chains. |
| Modular Subassembly Unbundling | German and Japanese industrial buyers now source gate drivers separately from power semiconductor stacks. |
| Silicon Carbide Hybrid Platform Launch | MIIT efficiency mandates in China redirect R&D budgets toward wide-bandgap thermal resistance reduction. |
| BIS Certification Pipeline Investment | India's thermal cycling test barriers screen unqualified imports from Power Grid Corporation tenders. |
| Automotive-Grade Module Specialization | Electric vehicle traction inverter specifications require bidirectional fault protection thyristor architectures. |
Methodological Framework
Bottom-up power utility procurement modeling reconciled against top-down silicon foundry capacity tracking forms the analytical core. Primary interviews with HVDC project engineers, power electronics procurement managers, semiconductor plant managers, and industrial automation maintenance directors combined with secondary validation from SEC semiconductor filings, MIIT efficiency mandate documentation, BIS certification registries, and customs trade data.
Historical trendline analysis of thyristor shipment volumes by product architecture, installation format, and end-use application anchors the projection framework. Segmentation dimensions span silicon versus hybrid material platforms, panel-mounted versus module formats, and power utility versus automotive versus industrial equipment demand. CAGRs derive from regression analysis of procurement intensity against transmission infrastructure investment cycles and electric vehicle production ramps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silicon carbide substrate supply disruptions or abrupt MIIT mandate acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Automotive Power Semiconductor Market
Power Systems
Synchrophasors Market
Power Systems
Modular Inverter Market
Power Systems
Europe Micro Inverter Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Japan Surge Protector Market
Power Systems
Power Semiconductor Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Low Voltage Drives Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Shunt Reactor Market
Power Systems
Bypass Thyristor Market
Power Systems
Automotive Inverters Market
Power Systems
Global Next Generation Power Semiconductors Market