
 South Africa Hospital Supplies Market | 2026-2036
South Africa Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Hospital Supplies Market Analytics
Subscription-based maintenance contracts for diagnostic and monitoring equipment is rebalancing how hospital supply vendors capture lifetime value from public sector buyers. Becton Dickinson leverages its regional service infrastructure to lock in multi-year consumable agreements with provincial health departments. Zans African Medical anchors its competitive position through localized distribution networks that bypass traditional import bottlenecks. Cardinal Health competes on procurement consolidation, bundling surgical supplies with inventory management software for private hospital groups.
Hospital supplies encompass instruments, equipment, consumables, and furniture used in clinical settings, typically manufactured from medical-grade polymers, stainless steel, or electronics-grade silicon and subject to sterilization validation protocols. Their primary purpose is to enable safe patient diagnosis, surgical intervention, continuous monitoring, and recovery management across acute care facilities. Consumables command the most recurring revenue pull due to per-procedure utilization patterns, while monitoring equipment carries higher upfront margins but longer replacement cycles. Surgical application demand outpaces diagnostic growth as backlog clearance from elective procedure delays continues across Gauteng and KwaZulu-Natal hospital clusters.
The South African Health Products Regulatory Authority governs medical device registration and quality standards, while the National Department of Health's centralized procurement framework reshapes how suppliers qualify for public tenders. BIS standards alignment and WHO prequalification pathways increasingly determine market access for imported equipment categories. Stakeholders must weigh NHI procurement centralization against private hospital chain consolidation when allocating capital between direct sales forces and distributor partnerships.
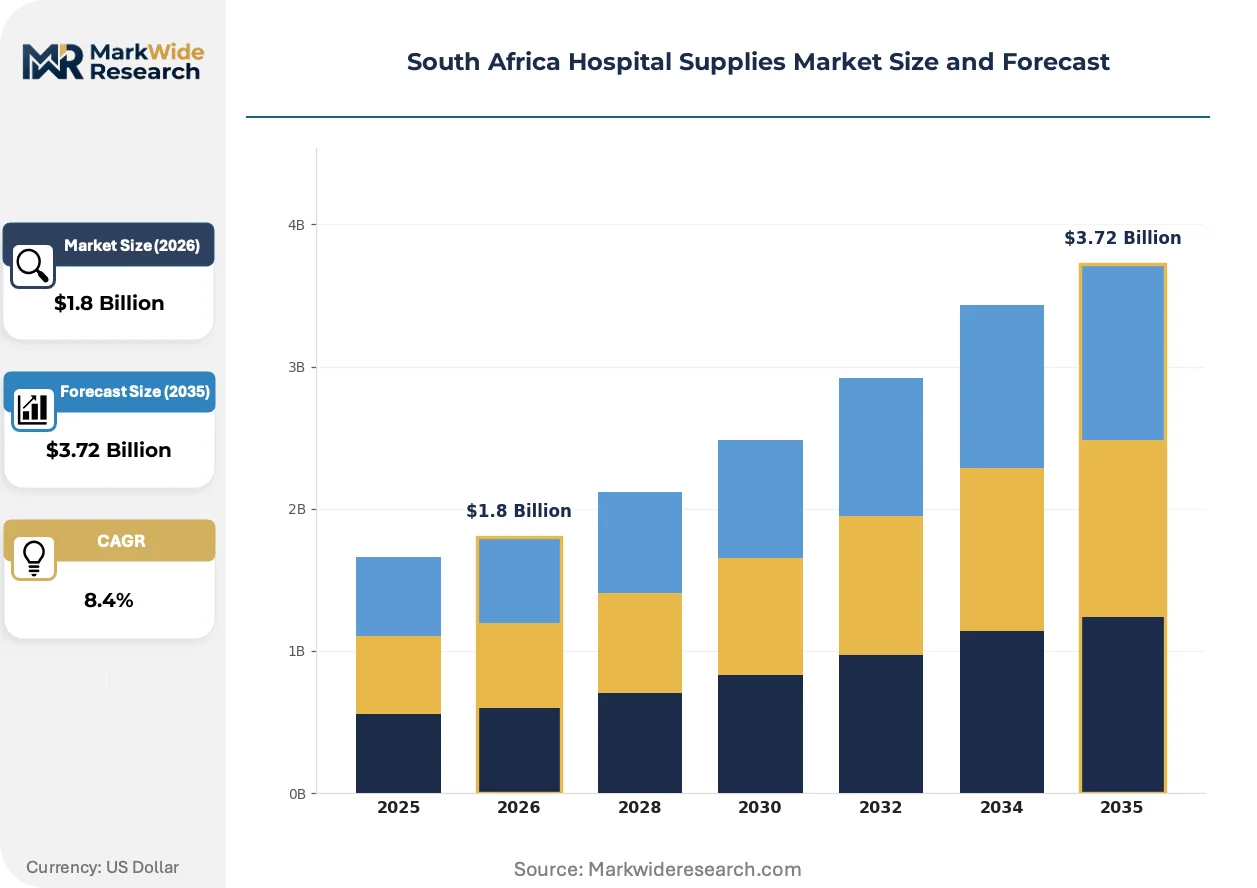
Market Dynamics
The National Health Insurance policy is consolidating public hospital procurement into centralized frameworks, fundamentally altering how suppliers qualify for tenders and locking in multi-year service contracts with provincial health departments.
Growth Catalysts
- Centralized procurement frameworks:The National Department of Health's tender consolidation is reducing transaction friction for qualified vendors and accelerating contract velocity across Gauteng and Western Cape tertiary networks.
- Elective procedure backlog clearance:Surgical consumables demand is surging as Gauteng and KwaZulu-Natal hospital clusters clear delayed procedures accumulated during healthcare system strain periods.
- Advanced sterilization technologies:Hydrogen peroxide vapor and low-temperature plasma systems are penetrating academic hospital networks, replacing legacy autoclave infrastructure in high-throughput surgical departments.
Market Restraints
- Import dependency for electronics-grade components:Patient monitoring equipment relies on silicon wafer and sensor imports subject to currency volatility and shipping bottlenecks through Durban port corridors.
- South African Health Products Regulatory Authority registration timelines:Medical device approval processes extend 18-24 months for novel equipment categories, delaying market entry for innovative suppliers.
- Reusable surgical instrument reprocessing:Stainless steel instrument sterilization and repair services are extending replacement cycles in cost-constrained public facilities, compressing consumables pull-through.
Strategic Opportunities
- Eastern Cape and Limpopo rural hospital networks:Underpenetrated secondary facilities present whitespace for portable diagnostic equipment and decentralized sterilization units as referral hub linkages strengthen.
- WHO prequalification pathway acceleration:Alignment with international quality standards is opening export corridors into neighboring SADC markets for South African-registered manufacturers.
- Subscription-based equipment maintenance:Remote monitoring and predictive service contracts are capturing lifetime value from public sector buyers previously lost to spot repair markets.
Industry Challenges
- Biomedical engineering talent scarcity:Diagnostic equipment calibration and complex device repair skills are concentrated in Johannesburg and Cape Town, leaving provincial facilities dependent on fly-in service models.
- Legacy inventory management system integration:Private hospital groups require API-compatible supply chain software that interfaces with existing ERP architectures, raising vendor qualification barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Hospital Supplies Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Equipment, Consumables, Furniture Application: Surgical, Diagnostic, Patient Care, Monitoring End User: Hospitals, Clinics, Laboratories, Nursing Homes Delivery Mode: Direct Supply, E-Procurement, Wholesalers, Distributors |
| Companies Covered | B. Braun, Becton Dickinson, Cardinal Health, 3M, Medtronic, GE Healthcare, Johnson & Johnson, Stryker, Zans African Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Hospital Supplies Market Evolving Landscape
Digital integration across sterilization workflows and procurement platforms is compressing operational cycles. Equipment vendors are embedding connectivity as a standard feature rather than premium upgrade.
RFID-enabled surgical instrument tracking is unifying sterilization documentation with operating theater scheduling systems. Tertiary facilities in Johannesburg and Cape Town are deploying these systems to reduce instrument set errors and traceability gaps. This unification is compressing liability exposure while creating data assets for predictive maintenance contracting.
The South African Health Products Regulatory Authority is tightening post-market surveillance requirements for Class III medical devices. Manufacturers must now submit adverse event reporting protocols as registration conditions. High-risk implantable device categories face the steepest compliance burden, with several international suppliers withdrawing marginal product lines rather than adapting.
Hospital procurement departments are bundling consumables with equipment service contracts to lock in predictable operational expenditures. Private hospital chains in KwaZulu-Natal and the Western Cape are leading this shift, displacing transactional spot purchasing. This restructuring favors vendors with localized technical service infrastructure over import-only distributors.
South Africa Hospital Supplies Market Segmentation
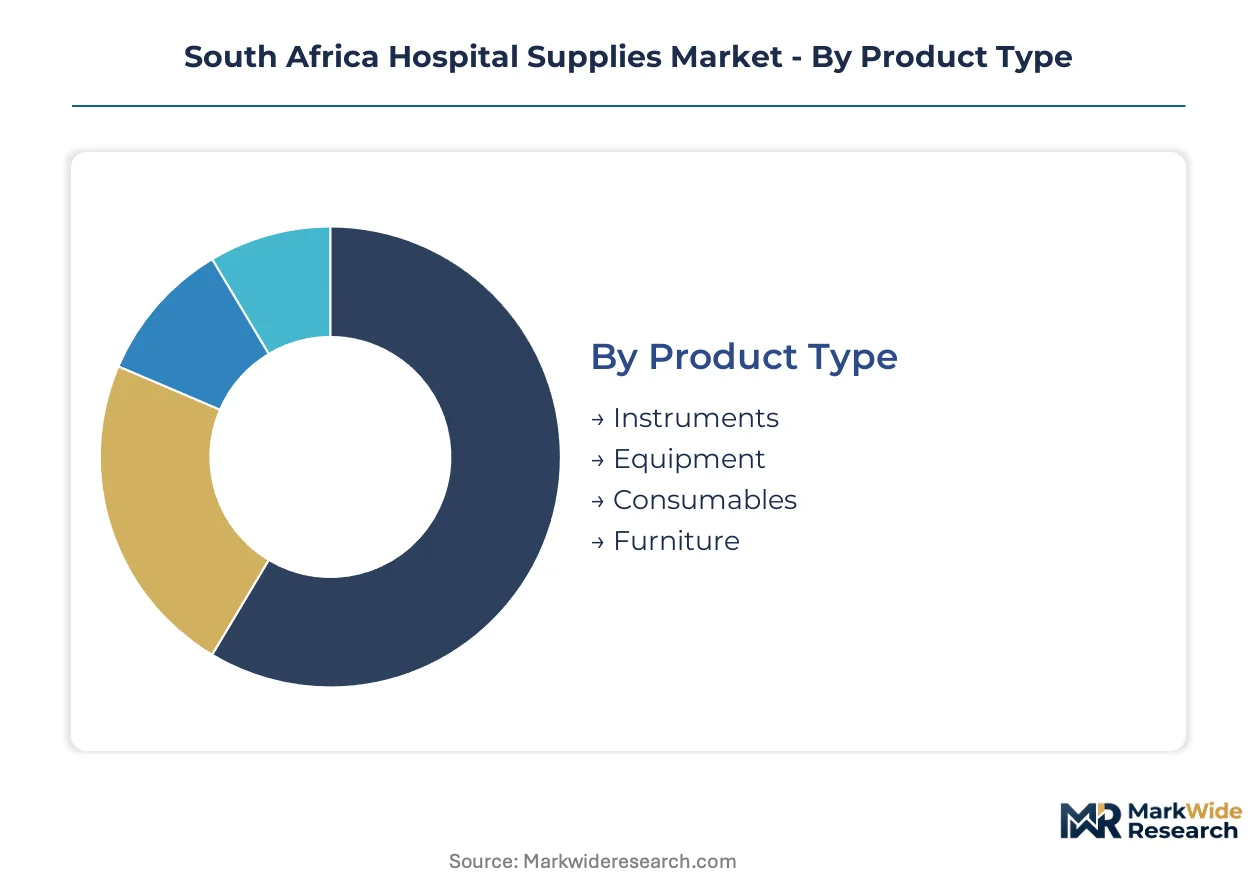
Hospital supplies segmentation in South Africa reflects divergent procurement rhythms between public sector centralization and private chain consolidation. Each dimension reveals distinct margin profiles and service intensity requirements that reshape vendor go-to-market architecture.
Product Type:
Standalone instruments and capital equipment demand dedicated technical service infrastructure, while consumables and furniture embed into recurring procurement workflows with lower touch requirements.
- Consumables:Medical-grade polymers and single-use sterile items dominate procedure volumes across Gauteng surgical theaters. Per-procedure utilization patterns generate predictable recurring revenue streams that anchor vendor cash flow stability in both public tenders and private hospital contracts.
- Equipment:Patient monitoring systems and diagnostic devices carry extended replacement cycles but command higher upfront margins. Western Cape tertiary facilities are prioritizing connectivity-enabled units that support remote calibration and predictive maintenance contracting.
- Instruments:Stainless steel surgical tools require sterilization validation and repair services that extend operational lifespans in cost-constrained Eastern Cape facilities.
- Furniture:Medical-grade seating and patient handling equipment follows hospital construction cycles with longer procurement intervals than clinical supplies.
Consumables leads volumes today; equipment is gaining share fastest through subscription-based service bundling.
Application:
Margin concentration varies sharply across clinical use cases, with surgical and monitoring applications commanding premium pricing through outcome-linked contracting.
- Surgical:Procedure-specific instrument sets and sterile drapes drive the highest consumables velocity. KwaZulu-Natal hospital clusters are clearing accumulated backlogs, compressing order-to-fulfillment timelines for vendors with localized inventory.
- Monitoring:Continuous patient surveillance equipment integrates with hospital information systems through standardized APIs. Johannesburg academic hospitals are mandating interoperability certification as a procurement gate.
- Diagnostic:Imaging consumables and laboratory reagents follow episodic disease surveillance priorities rather than steady surgical rhythms.
- Patient Care:Wound management and hygiene products serve extended-stay facilities with volume-driven pricing sensitivity.
Surgical dominates revenue concentration; monitoring is climbing the fastest as connectivity requirements reshape replacement decisions.
End User:
Customer scale determines service model economics, with hospitals demanding embedded technical support and smaller facilities accepting distributor-mediated fulfillment.
- Hospitals:Tertiary and secondary acute care facilities concentrate procurement volume and negotiate multi-year framework agreements. Provincial health departments in Gauteng and Western Cape are consolidating supplier panels to reduce transaction overhead.
- Clinics:Primary care facilities prioritize portable diagnostic equipment and decentralized supply access over capital-intensive infrastructure.
- Laboratories:Reference labs and pathology networks require specialized reagents with cold chain integrity and batch traceability documentation.
- Nursing Homes:Long-term care facilities generate steady demand for patient hygiene and mobility assistance products with lower technical service intensity.
Hospitals anchor procurement volumes today; clinics are expanding most quickly as referral hub networks extend into underpenetrated provinces.
Delivery Mode:
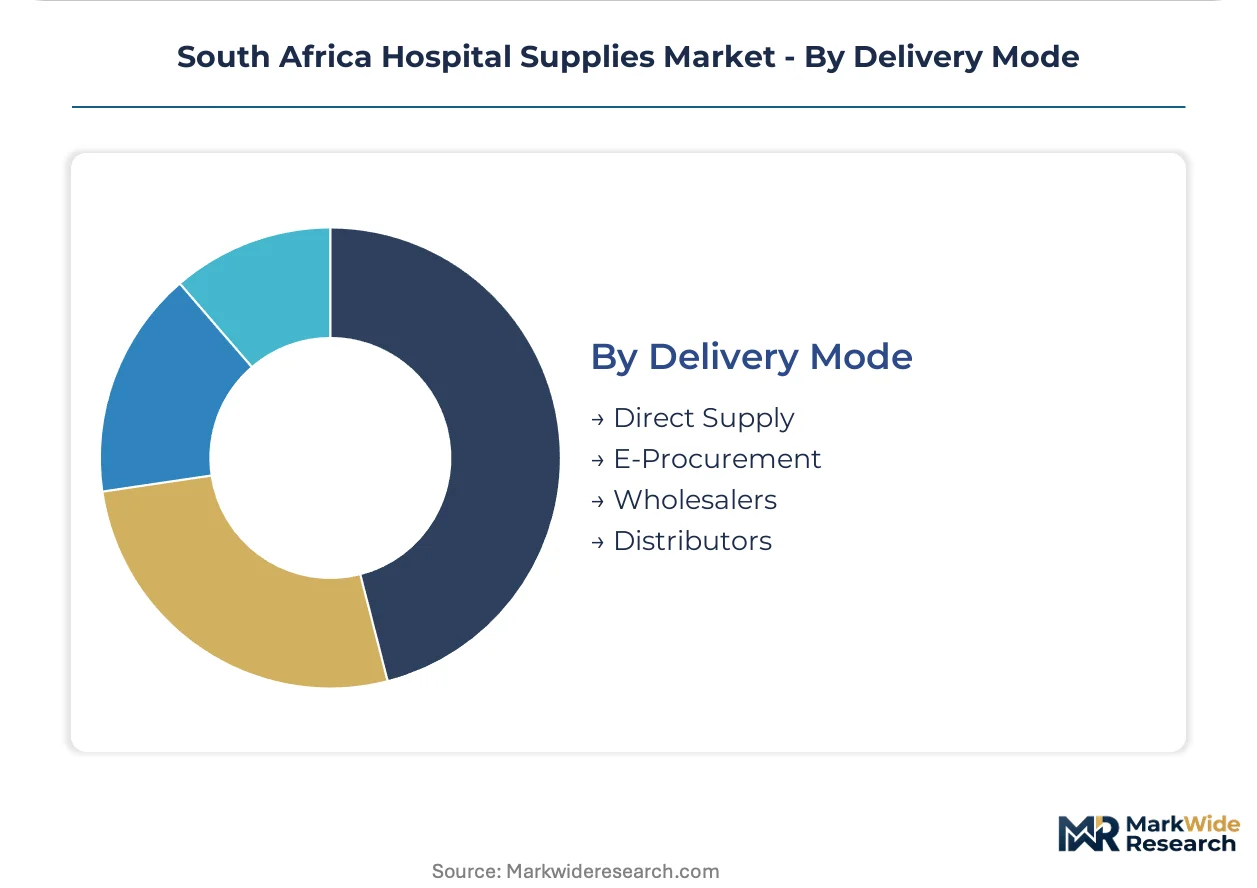
Channel structure directly shapes working capital requirements and margin capture, with direct supply and e-procurement compressing distributor layers.
- Distributors:Localized inventory and technical service capabilities bypass import bottlenecks through Durban port corridors. Zans African Medical and comparable networks anchor competitive position through provincial warehousing presence.
- E-Procurement:Centralized tender platforms are displacing spot purchasing in public sector frameworks. The National Department of Health's digital procurement infrastructure is accelerating contract velocity for qualified vendors.
- Direct Supply:Manufacturer-to-hospital relationships dominate high-value equipment categories requiring installation and calibration services.
- Wholesalers:Aggregated fulfillment serves fragmented private clinic networks with standardized consumables and reduced service bundling.
Distributors maintain volume leadership today; e-procurement is gaining share fastest as NHI centralization reshapes public sector purchasing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng's tertiary hospital networks generate procurement volumes that dwarf Limpopo's rural facilities, yet both provinces operate under the same National Health Insurance procurement framework reshaping supplier access across South Africa.
Gauteng
Johannesburg and Pretoria academic hospitals concentrate surgical consumables demand through backlog clearance programs. The National Department of Health's centralized tender system prioritizes vendors with provincial warehousing presence. Charlotte Maxeke Johannesburg Academic Hospital deploys RFID-enabled instrument tracking to unify sterilization workflows with theater scheduling.
Western Cape
Cape Town tertiary facilities lead adoption of connectivity-enabled patient monitoring equipment requiring API interoperability certification. The South African Health Products Regulatory Authority's post-market surveillance protocols tighten fastest in this province. Groote Schuur Hospital anchors hydrogen peroxide vapor sterilization deployment across high-throughput surgical departments.
KwaZulu-Natal
Durban port corridors channel import-dependent electronics-grade components for diagnostic equipment, exposing procurement to currency volatility and shipping bottlenecks. Inkosi Albert Luthuli Central Hospital clears accumulated elective procedure backlogs, compressing surgical consumables order-to-fulfillment timelines for localized inventory holders.
Eastern Cape
Rural secondary facilities present whitespace for portable diagnostic equipment as referral hub linkages strengthen toward Nelson Mandela Bay. Biomedical engineering talent scarcity forces fly-in service models for equipment calibration. Frere Hospital and Livingstone Hospital anchor public sector procurement concentration in the province's urban corridor.
Limpopo
Underpenetrated hospital networks in Polokwane and surrounding districts drive demand for decentralized sterilization units and basic surgical consumables. Provincial health department procurement lags Gauteng and Western Cape in framework agreement consolidation. Mankweng Hospital serves as the primary referral hub for advanced procedures requiring equipment service contracts.
South Africa Hospital Supplies Market Competitive Landscape
Top-tier vendors anchor multi-year framework agreements with provincial health departments, while mid-tier distributors compete on localized inventory and bypassing import bottlenecks. The market structures around three archetypes: multinational equipment manufacturers with service infrastructure, regional consumables specialists with provincial warehousing networks, and import-dependent distributors competing on spot pricing. Consolidation pressures intensify through procurement centralization under National Health Insurance policy implementation and private hospital chain bundling of supplies with inventory management software.
Among multinational manufacturers with established South African service infrastructure, Becton Dickinson and Cardinal Health exemplify vendors capturing lifetime value through subscription-based maintenance contracts and consumable bundling. Zans African Medical anchors the regional distributor archetype through localized networks that bypass traditional import bottlenecks.
| Leading Market Players |
|---|
| B. Braun |
| Becton Dickinson |
| Cardinal Health |
| 3M |
| Medtronic |
| GE Healthcare |
| Johnson & Johnson |
| Stryker |
| Zans African Medical |
| Others |
Value Network & Pricing Analysis
Provincial health department procurement consolidation under the National Health Insurance policy anchors pricing power with large-volume public tenders, compressing spot-market premiums and favoring contract-based subscription models for diagnostic equipment maintenance.
Pricing Analysis
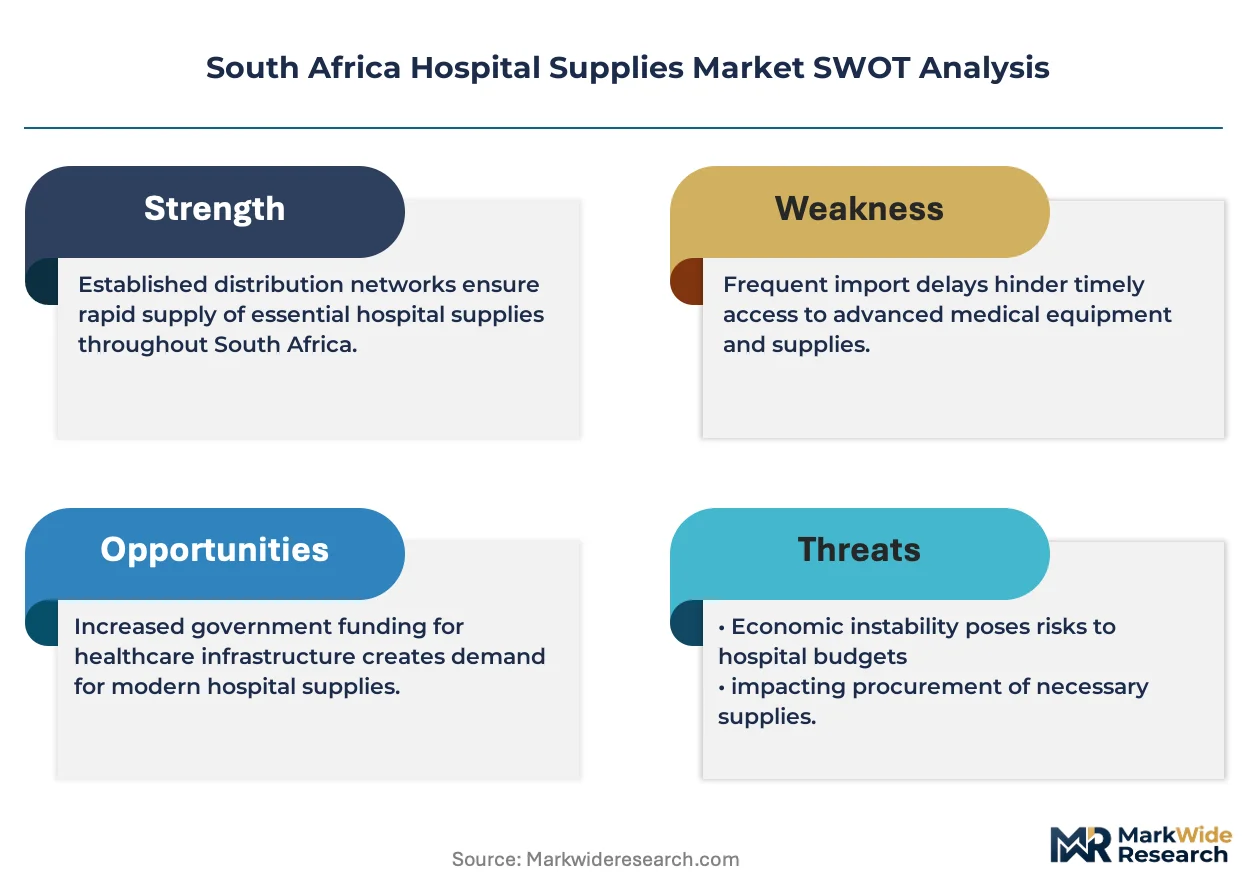
Capacity additions in domestic sterilization services are reshaping price floors for surgical consumables, as localized reprocessing competition intensifies. Three-tier pricing structure across premium connectivity-enabled, standard certified, and economy unbundled equipment tiers separates vendors by after-sales service depth. Cost compression in public sector tenders is intensifying because National Department of Health framework agreements prioritize total cost of ownership over upfront unit pricing. Private hospital groups in the Western Cape demonstrate least price sensitivity, while Eastern Cape rural facilities exhibit highest volume-driven bargaining intensity.
Supply Chain Analysis
SAHPRA registration and WHO prequalification gating concentrates import authorization among established registrants, extending lead times for novel equipment categories. Electronics-grade silicon wafers and sensor components draw from East Asian manufacturing hubs, while medical-grade polymer resin supplies rest on Middle Eastern petrochemical feedstock flows. Single-source vulnerability runs through Durban port corridor congestion, which periodically disrupts containerized diagnostic equipment arrivals. Distribution runs through provincial warehousing networks that bypass import bottlenecks via Johannesburg and Cape Town logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with tertiary hospital procurement committees mandating connectivity certification and predictive maintenance bundling as baseline qualification gates.
For Market Incumbents: To counter biomedical engineering talent scarcity concentrated in Johannesburg and Cape Town, anchor multi-year service contracts with fly-in calibration coverage for Eastern Cape and Limpopo facilities. Backward integration into regional sterilization reprocessing services captures consumables pull-through otherwise lost to third-party repair vendors. For New Entrants and Emerging Players: Distributor partnerships with Zans African Medical-type networks provide the fastest channel access to underpenetrated Limpopo and Eastern Cape secondary hospitals. Portable diagnostic equipment for rural referral hubs offers the most penetrable whitespace, as centralized procurement frameworks have not yet consolidated these facility tiers. For Investors and Strategic Acquirers: Regional consumables specialists with provincial warehousing presence are the most active acquirer targets in this space, as multinational manufacturers seek localized inventory buffers. Long-term viability hinges on NHI implementation velocity and private hospital chain consolidation pace. The signal to watch is National Department of Health tender panel announcements, which indicate framework agreement consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Pathway | Accelerates market entry for hydrogen peroxide vapor sterilization systems into Western Cape tertiary networks. |
| Provincial Warehousing Partnership | Positions consumables vendors for National Health Insurance centralized tender qualification in Gauteng and KwaZulu-Natal. |
| Connectivity Certification Investment | Meets Groote Schuur Hospital interoperability mandates for patient monitoring equipment procurement. |
| Predictive Maintenance Contracting | Captures lifetime value from public sector buyers through remote calibration and embedded service bundling. |
| WHO Prequalification Alignment | Opens SADC export corridors for South African-registered manufacturers serving neighboring health systems. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineering directors, provincial health department contract officers, and GPO framework administrators grounded qualitative insights, combined with secondary validation from SAHPRA registration databases, National Treasury tender awards, hospital procurement disclosures, and customs import records. Bottom-up facility-level demand estimation triangulated against top-down provincial health expenditure allocations.
Segmentation outputs across product type, application, end user, and delivery mode dimensions were modeled over the projection horizon, with CAGRs derived from historical expenditure trajectories and policy implementation schedules. Forecast inputs incorporated National Health Insurance rollout phasing, elective procedure backlog clearance velocity, and electronics import tariff exposure through Durban corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHI centralization pace and currency volatility effects on imported equipment landed costs. Forecasts reflect documented assumptions regarding policy implementation continuity and port logistics stability. A model refresh is warranted upon material change in National Department of Health tender panel composition or SAHPRA registration timeline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Medical Bags Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market