
 Global Unna Boot Market | 2026-2036
Global Unna Boot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unna Boot Market Foresight
Germany is rewriting the competitive map for Unna boot manufacturing as domestic producers expand calendering and textile-finishing capacity for zinc-oxide impregnated bandages. Medline Industries leverages integrated North American distribution to sustain hospital contract penetration. Smith & Nephew anchors European demand through specialized wound care portfolios. Mölnlycke Health Care differentiates via advanced foam-padding formulations that reduce skin maceration risk.
An Unna boot is a zinc-oxide–impregnated, semirigid gauze bandage that hardens upon drying to provide sustained compression for venous insufficiency and related edema conditions, typically incorporating calamine or glycerin to soothe irritated skin. The product type landscape shows elastic variants dominating hospital procurement due to standardized compression profiles, while gel-infused formats capture premium positioning in wound care clinics where moisture balance drives outcomes. Home care settings represent the fastest-growing end-user channel as post-acute discharge protocols shift therapeutic monitoring away from institutional sites.
FDA clearance pathways under 510(k) bandage classifications shape US market entry timelines, while the EU MDR and CE marking requirements enforce biocompatibility testing for prolonged skin contact. India's CDSCO and BIS textile standards govern import quality for zinc-oxide bandages entering that market. Stakeholders must monitor evolving compression-classification harmonization between ISO 13485 quality systems and national wound-care reimbursement codes to anticipate procurement specification shifts.
Market Dynamics
The EU Medical Device Regulation is tightening biocompatibility testing requirements for prolonged skin-contact bandages, forcing manufacturers to recalibrate quality systems and certification timelines across European supply chains.
Growth Catalysts
- Post-acute discharge protocols:Home care settings now absorb therapeutic monitoring previously handled in wound care clinics, expanding the addressable patient base for ambulatory compression therapy.
- ISO 13485 harmonization:Quality system alignment with national reimbursement codes is compressing procurement specification cycles and accelerating hospital contract approvals.
- Germany's wound care infrastructure:Specialized reimbursement protocols and clinical networks support uptake of advanced zinc-oxide bandaging systems in venous insufficiency treatment.
Market Restraints
- Cotton gauze input volatility:Raw material price swings for medical-grade textiles compress margin buffers for calendering operations.
- EU MDR certification friction:Extended biocompatibility documentation timelines delay product launches and tie up regulatory capital.
- Elastic compression garment substitution:Ready-to-wear alternatives threaten Unna boot positioning in standardized hospital procurement.
Strategic Opportunities
- India's import quality gap:CDSCO and BIS textile standard enforcement creates entry barriers that compliant manufacturers can exploit for premium positioning.
- Gel-infused format convergence:Moisture-balancing formulations paired with semirigid compression open wound care clinic segments resistant to commodity gauze.
- Telehealth channel integration:Remote therapeutic monitoring platforms enable direct-to-patient distribution bypassing traditional institutional procurement.
Industry Challenges
- Calendering technician scarcity:Specialized textile-finishing expertise for zinc-oxide impregnation is concentrating among aging workforce cohorts in European manufacturing clusters.
- Legacy 510(k) pathway compression:FDA clearance timelines for bandage classifications are extending as predicate device scrutiny intensifies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unna Boot Market |
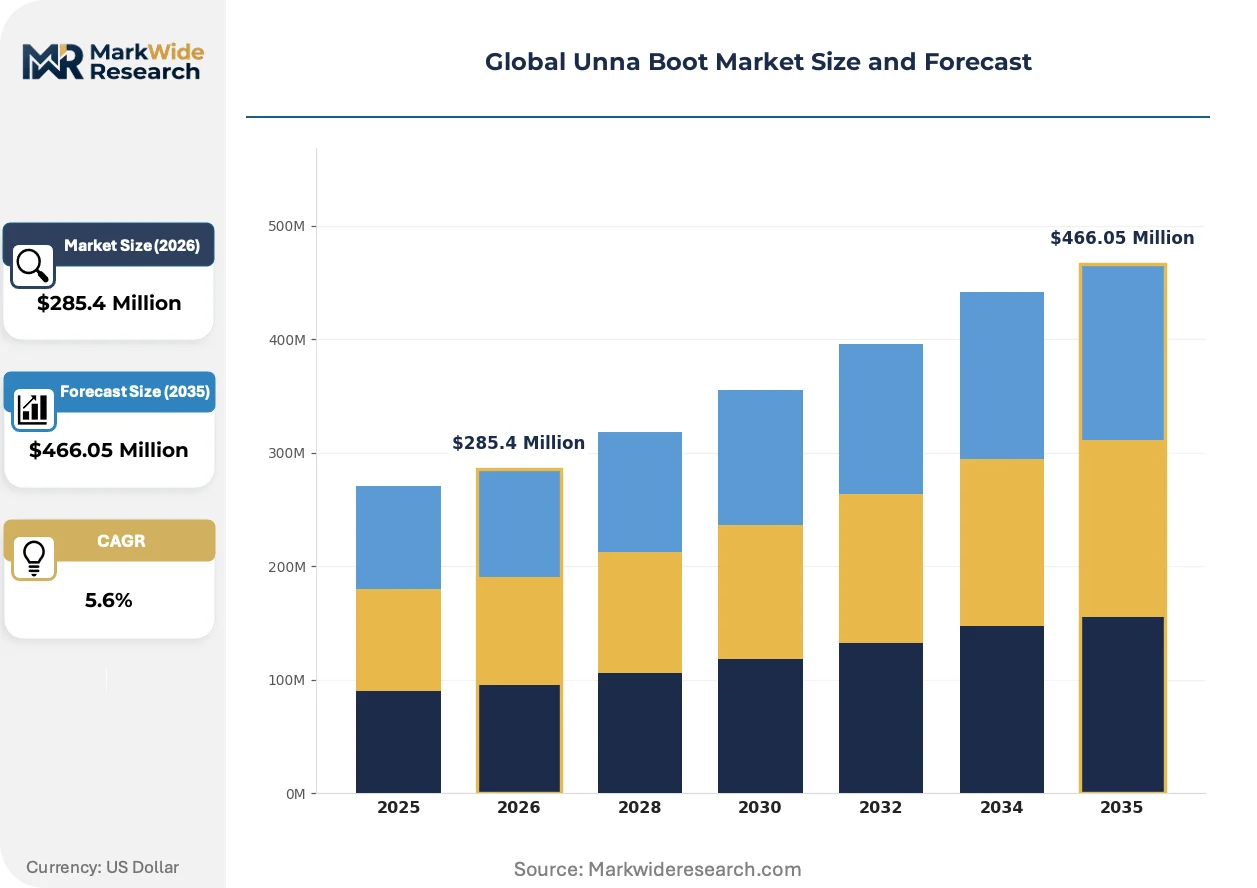
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $466.05 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic, Non-Elastic, Foam Padding, Gel Infused, Self-Adherent Application: Venous Leg Ulcers, Lymphedema, Post-Surgical Edema, Deep Vein Thrombosis, Sports Injuries End User: Hospitals, Wound Care Clinics, Orthopedic Centers, Rehabilitation Facilities, Home Care Settings Distribution Channel: Medical Distributors, Pharmacies, Online Retailers, Specialized Medical Stores, Direct Sales |
| Companies Covered | Medline Industries, Cardinal Health, Smith & Nephew, 3M, BSN Medical, Integra LifeSciences, Essity Aktiebolag, Mölnlycke Health Care, Paul Hartmann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unna Boot Market Shifts & Advancements
Digital integration is penetrating compression therapy workflows, with connected monitoring and virtual care coordination emerging as structural differentiators beyond material composition alone.
Smart bandage sensor technology is embedding moisture and pressure detection into zinc-oxide gauze substrates. Wound care clinics in Germany and the Netherlands are piloting these systems for remote edema monitoring. This capability is virtualizing the traditional in-person dressing change cycle, compressing clinical visit frequency while maintaining therapeutic oversight.
REACH chemical safety assessments are expanding scrutiny of zinc-oxide particle characterization in medical textiles. Manufacturers must now document nanoscale property thresholds to maintain CE marking validity. Gel-infused and modified-release formats face the steepest compliance cost escalations under these expanded dossier requirements.
Hospital procurement consortia are consolidating vendor panels for compression bandaging systems, favoring suppliers with integrated distribution and quality documentation. Group purchasing organizations in the US and centralized procurement frameworks in Germany are displacing fragmented single-facility contracting. This concentration is most visible in tertiary hospital networks seeking standardized compression-classification protocols across multi-site operations.
Global Unna Boot Market Segmentation
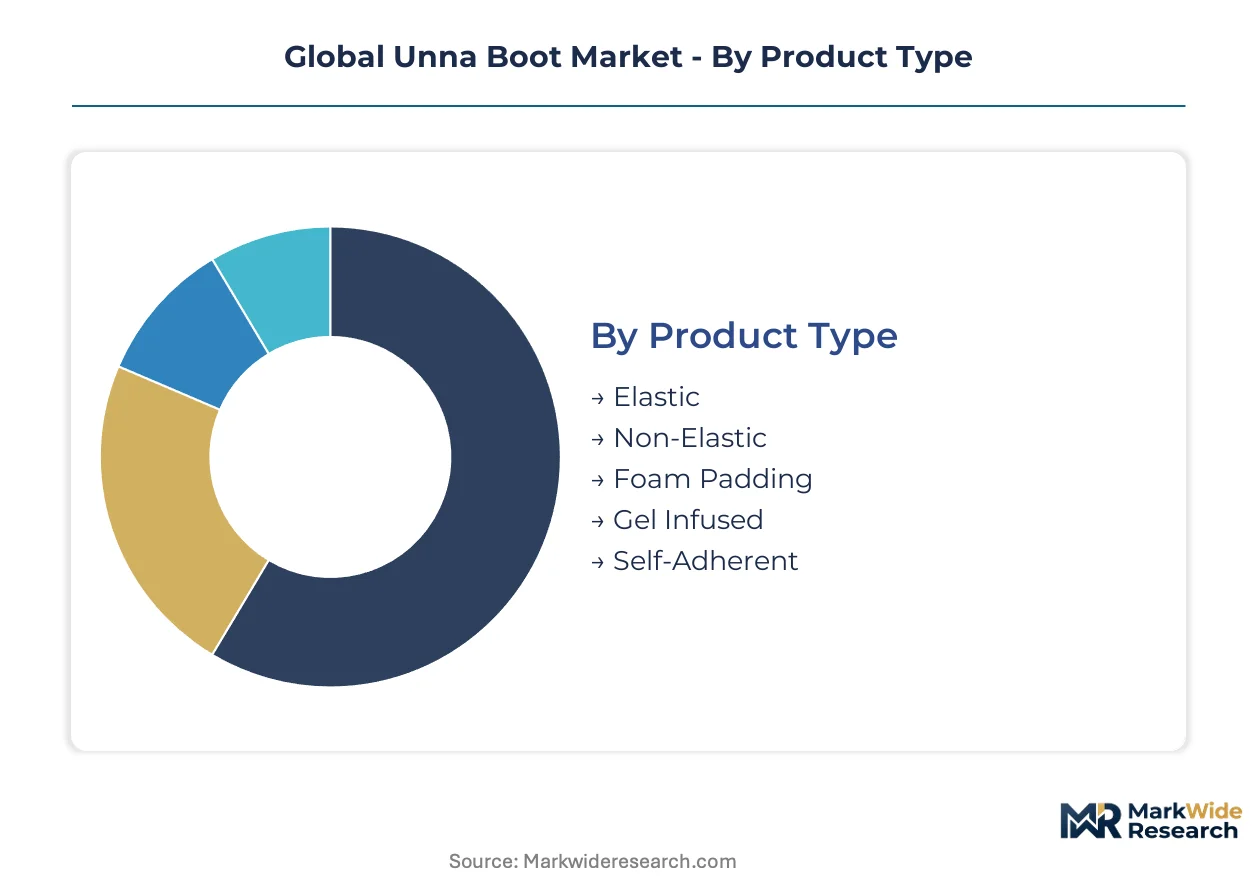
Unna boot segmentation reflects divergent clinical workflows and reimbursement environments. Product form factors, therapeutic applications, and procurement channels each carry distinct margin profiles and regulatory burdens that shape manufacturer prioritization.
Product Type:
Mature formats dominate hospital procurement, while emerging variants target outpatient and home-based protocols with differentiated moisture management.
- Elastic:Zinc-oxide impregnated gauze with calibrated stretch properties delivers standardized compression profiles for venous insufficiency protocols. Hospital procurement consortia in Germany and the US favor this segment for predictable therapeutic outcomes across multi-site operations. FDA 510(k) clearance pathways for predicate elastic bandages compress regulatory timelines relative to novel formats.
- Gel Infused:Modified-release glycerin or calamine formulations embedded in semirigid substrates reduce skin maceration risk during extended wear. Wound care clinics in the Netherlands pilot these systems for patients with fragile periwound tissue. REACH chemical safety assessments for nanoscale zinc-oxide characterization impose elevated documentation costs on European launches.
- Non-Elastic:Rigid compression systems for acute edema management with fixed pressure gradients.
- Foam Padding:Integrated cushioning layers for bony prominence protection in long-term immobilization.
- Self-Adherent:Cohesive bandage structures eliminating the need for additional securing wraps in home care applications.
Elastic formats handle the majority of throughput; gel infused variants are gaining share fastest among premium-positioned wound care clinics.
Application:
Volume concentrates in chronic conditions with established reimbursement codes, while acute and preventive indications expand the addressable patient base.
- Venous Leg Ulcers:The foundational indication for Unna boot therapy, involving sustained compression to reduce ambulatory venous pressure and promote wound edge contraction. Germany's specialized wound care infrastructure and DRG-based reimbursement protocols support advanced zinc-oxide bandaging uptake for this population. Clinical networks in North Rhine-Westphalia coordinate tertiary-to-home care handoffs that sustain extended treatment courses.
- Lymphedema:Chronic lymphatic fluid accumulation requiring graduated compression maintenance over indefinite durations. Wound care clinics in the Netherlands integrate these protocols with manual lymphatic drainage scheduling. Insurance coverage variability across US states creates geographic demand concentration where prior authorization pathways are streamlined.
- Post-Surgical Edema:Acute compression needs following orthopedic or vascular procedures with defined treatment endpoints.
- Deep Vein Thrombosis:Adjunctive compression for chronic post-thrombotic syndrome management.
- Sports Injuries:Emerging ambulatory compression for acute soft tissue trauma in athletic populations.
Venous leg ulcers absorb the dominant share of clinical volume; lymphedema applications are expanding most quickly as chronic disease recognition improves.
End User:
Institutional procurement favors standardized formats, while decentralized settings create opportunities for patient-directed product selection.
- Hospitals:Tertiary acute care facilities with centralized purchasing and formulary committees. Group purchasing organizations in the US consolidate vendor panels for compression bandaging systems, favoring suppliers with integrated distribution and quality documentation. Multi-site hospital networks seek standardized compression-classification protocols.
- Home Care Settings:Post-acute discharge destinations where therapeutic monitoring shifts away from institutional sites. Remote patient monitoring platforms enable direct-to-patient distribution bypassing traditional procurement. Medicare home health benefit coverage determines US demand concentration.
- Wound Care Clinics:Specialized outpatient facilities with protocol flexibility for advanced formulations.
- Orthopedic Centers:Procedure-focused settings with compression needs tied to surgical calendars.
- Rehabilitation Facilities:Extended care environments integrating compression into mobility restoration programs.
Hospitals command the largest procurement volumes; home care settings are climbing the fastest as discharge protocols accelerate.
Distribution Channel:
Channel selection determines margin capture and patient access constraints, with digital intermediaries disrupting traditional medical supply hierarchies.
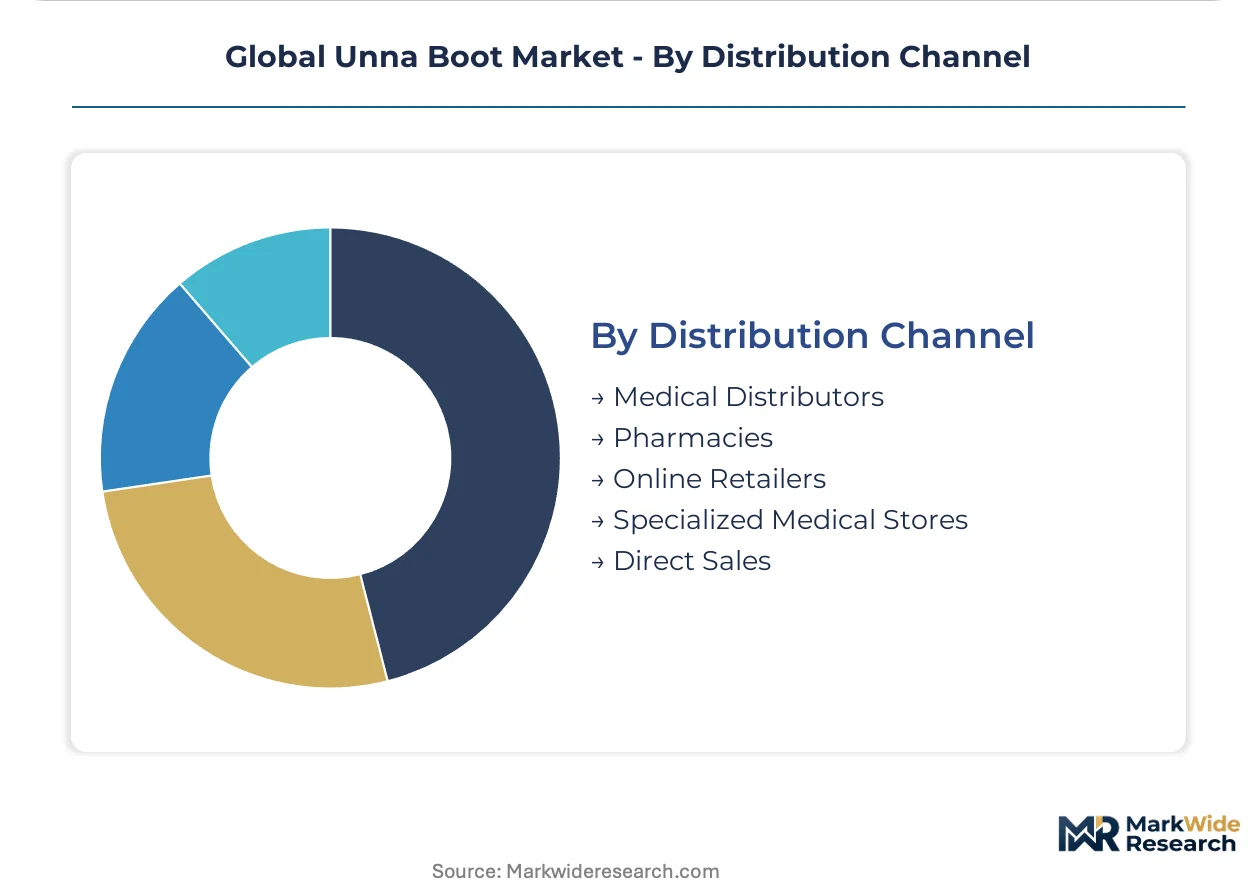
- Medical Distributors:Traditional intermediaries with field sales representation and inventory management for institutional accounts. Medline Industries leverages integrated North American distribution infrastructure to sustain hospital contract penetration. Credit terms and consignment arrangements bind long-term supplier relationships.
- Online Retailers:Direct-to-consumer platforms enabling patient-initiated purchasing outside formulary constraints. Telehealth channel integration supports remote therapeutic monitoring with product fulfillment. Amazon and specialized medical supply marketplaces compete on shipping velocity and subscription replenishment.
- Pharmacies:Community and outpatient pharmacy networks with pharmacist counseling on application technique.
- Specialized Medical Stores:Durable medical equipment suppliers with fitting services and insurance billing expertise.
- Direct Sales:Manufacturer-controlled channels for institutional contracts and patient assistance programs.
Medical distributors retain the dominant throughput position; online retailers are expanding most rapidly as patient-directed purchasing normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calendering operations for zinc-oxide impregnated bandages cluster in Germany's textile belt, while US hospital procurement consortia and India's import quality enforcement reshape demand geography. Regulatory divergence between FDA 510(k) pathways and EU MDR biocompatibility timelines fragments certification strategies across manufacturing footprints.
United States
Medicare home health benefit coverage drives post-acute discharge protocols toward ambulatory compression therapy. FDA 510(k) bandage classifications compress regulatory timelines for predicate elastic formats. Group purchasing organizations in the Midwest and Southeast consolidate vendor panels for multi-site hospital networks.
Germany
Specialized wound care infrastructure in North Rhine-Westphalia supports DRG-based reimbursement for advanced zinc-oxide bandaging. EU MDR biocompatibility testing requirements enforce nanoscale zinc-oxide documentation for CE marking validity. Calendering technicians in the Münsterland textile cluster expand capacity for semirigid gauze finishing.
India
CDSCO import quality enforcement and BIS textile standards create compliance barriers for zinc-oxide bandage entry. Domestic wound care demand concentrates in Maharashtra and Karnataka where tertiary hospital networks proliferate. Mumbai-based distributors navigate prior authorization variability across state insurance schemes.
Netherlands
Wound care clinics in Amsterdam and Utrecht pilot smart bandage sensor technology for remote edema monitoring. REACH chemical safety assessments scrutinize glycerin-modified release formulations in gel-infused substrates. Eindhoven's medical textile research corridor advances moisture-detection integration into semirigid compression systems.
Japan
PMDA quality system requirements extend review timelines for prolonged skin-contact bandages beyond Western benchmarks. Aging demographic pressure concentrates venous insufficiency patient volumes in Kanto and Kansai metropolitan corridors. Osaka-based procurement frameworks favor standardized compression-classification protocols for chronic disease management.
Global Unna Boot Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in calendering and textile-finishing operations. The vendor base organizes around three archetypes: diversified health care conglomerates with wound care divisions, pure-play compression therapy manufacturers, and regional gauze converters with zinc-oxide impregnation capabilities. Consolidation pressure emanates from hospital procurement consortia seeking integrated distribution and quality documentation. Capacity expansion in Germany's textile belt and strategic partnerships for REACH compliance dossiers constitute dominant competitive vectors.
Among diversified health care suppliers, Medline Industries, Smith & Nephew, and Mölnlycke Health Care exemplify platform-scale positioning across institutional and ambulatory channels. These entities occupy archetypal roles as procurement consolidation beneficiaries, with geographic footprints spanning North American distribution infrastructure and European specialized wound care portfolios. Their market presence anchors tiered competitive dynamics where quality system harmonization and regulatory capital access separate scalable participants from regional converters.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| Smith & Nephew |
| 3M |
| BSN Medical |
| Integra LifeSciences |
| Essity Aktiebolag |
| Mölnlycke Health Care |
| Paul Hartmann AG |
| Others |
Supply & Pricing Matrix
Calendering capacity underutilization in Germany's Münsterland textile cluster is compressing supplier margins and forcing zinc-oxide bandage manufacturers toward aggressive contract pricing to maintain volume throughput.
Pricing Analysis
EU MDR dictates the pricing tier structure across the Unna boot market, separating CE-marked premium gel-infused formats from standard elastic variants and economy-grade non-elastic systems. Price differentiation hinges on biocompatibility certification depth and nanoscale zinc-oxide documentation completeness. Cost compression in standard elastic tiers is intensifying because cotton gauze input volatility erodes margin buffers. Hospital procurement consortia exhibit highest price sensitivity, while wound care clinics prioritize moisture-management performance over unit economics.
Supply Chain Analysis
REACH chemical safety assessments limiting glycerin-modified release formulation flows are constraining gel-infused substrate sourcing from European suppliers. Manufacturing concentrates in Germany, India, and the United States, with calendering operations anchored in North Rhine-Westphalia and Maharashtra. Raw material dependencies center on medical-grade cotton gauze, zinc-oxide pharmaceutical grade, and specialized textile finishing chemicals. Single-source vulnerability pervades calendering technician expertise, which concentrates among aging workforce cohorts. Distribution runs through medical distributors with field sales representation and consignment arrangements for institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Unna boot market is recovering from pandemic-era discharge protocol disruptions as post-acute home care normalization restores ambulatory compression therapy volumes.
For Market Incumbents: Pre-empt elastic compression garment substitution by accelerating smart bandage sensor integration for remote edema monitoring capabilities. Secure calendering technician pipelines through apprenticeship partnerships in Germany's textile belt. Expand CE marking dossier investment to maintain premium positioning under REACH nanoscale characterization requirements. For New Entrants and Emerging Players: India's Maharashtra and Karnataka hospital network expansion offers the most penetrable geographic entry point for compliant zinc-oxide bandage suppliers. Target wound care clinic segments resistant to commodity gauze through gel-infused format differentiation. Leverage telehealth channel integration for direct-to-patient distribution bypassing entrenched medical distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart bandage sensor development programs as moisture-detection integration demands specialized semiconductor partnerships. Long-term viability favors platform-scale wound care suppliers with integrated distribution and regulatory capital access. Acquisition targets should demonstrate ISO 13485 harmonization with national reimbursement codes. Watch FDA 510(k) predicate device scrutiny intensity as the signal for regulatory timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Biocompatibility Dossier Expansion | REACH nanoscale documentation requirements enforce premium tier separation from commodity competitors. |
| Smart Bandage Sensor Integration | Eindhoven's medical textile research corridor advances moisture-detection capabilities for remote monitoring. |
| Calendering Capacity Expansion | Münsterland textile cluster investments address technician scarcity and underutilization pressures. |
| Telehealth Channel Partnership | Remote therapeutic monitoring platforms enable direct-to-patient distribution outside GPO contracts. |
| India CDSCO Compliance Investment | BIS textile standard adherence creates entry barriers exploitable for premium positioning in Maharashtra. |
Research Methodology
A standing panel of wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration throughout primary fieldwork. Secondary validation drew from FDA 510(k) bandage classification databases, EU MDR CE marking registries, CMS Medicare home health benefit utilization data, and hospital procurement consortium contract disclosures. Bottom-up volume estimates from end-user segmentation triangulated against top-down manufacturer capacity assessments.
Scenario-bracketing framed demand projections across elastic, gel-infused, and non-elastic product formats; venous leg ulcer, lymphedema, and post-surgical edema applications; and hospital, home care, and wound care clinic end-user channels. CAGRs derived from regression analysis against chronic disease prevalence trajectories and reimbursement code expansion patterns. Compression classification protocol harmonization between ISO 13485 systems and national wound care codes informed elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified health care conglomerates into direct-to-patient channels would shift outcomes. Material shifts in EU MDR biocompatibility documentation timelines or FDA predicate device scrutiny intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Cryogenic Vials Market