
 Catgut Sutures Market | 2026-2036
Catgut Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Catgut Sutures Market Outlook
Absorbable polymer alternatives is fragmenting traditional catgut sutures into niche veterinary and cost-sensitive surgical segments where natural collagen fibers retain price advantage. Johnson & Johnson Services leverages its Ethicon heritage to sustain hospital formulary dominance across North American academic medical centers. Medtronic anchors its suture portfolio through integrated surgical stapling bundles that reduce standalone catgut purchasing. B. Braun Melsungen AG differentiates via chromic catgut specialization for European equine and livestock veterinary channels.
Catgut sutures consist of purified collagen strands derived from sheep or goat intestine, typically treated with chromic salts to extend absorption time from 70–90 days to 90–120 days, serving primarily as ligature and wound closure material in procedures where suture removal is impractical. Absorbable catgut still commands volume leadership in veterinary orthopedics and rural surgical settings where synthetic alternatives carry premium pricing. Multifilament construction dominates general surgery applications due to superior knot security, while monofilament variants gain traction in ophthalmic microsurgery where tissue drag minimization matters. Hospitals remain the principal procurement channel, though ambulatory surgery centers are capturing outpatient hernia repair volumes that shift suture consumption to lower-cost settings.
FDA biologics oversight and the EU Medical Device Regulation impose divergent sterilization validation and traceability mandates that fragment compliance costs across Atlantic suppliers. India's CDSCO and BIS standards for surgical sutures create additional registration barriers for imported natural fiber products. ISO 10993 biocompatibility testing requirements now extend to residual chromium quantification in chromic catgut lots. Stakeholders must monitor whether synthetic absorbable price convergence erodes catgut's residual cost advantage in emerging market public health tenders.
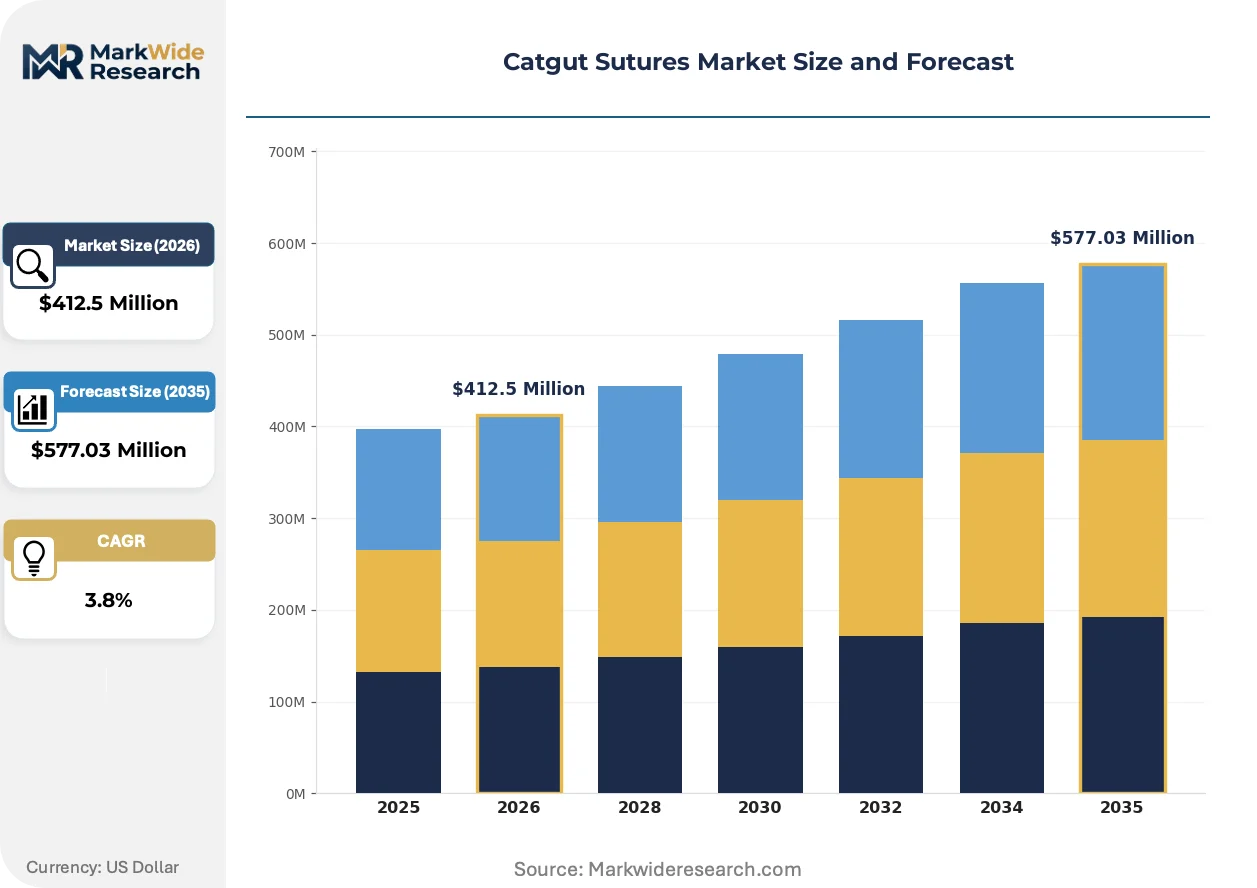
Market Dynamics
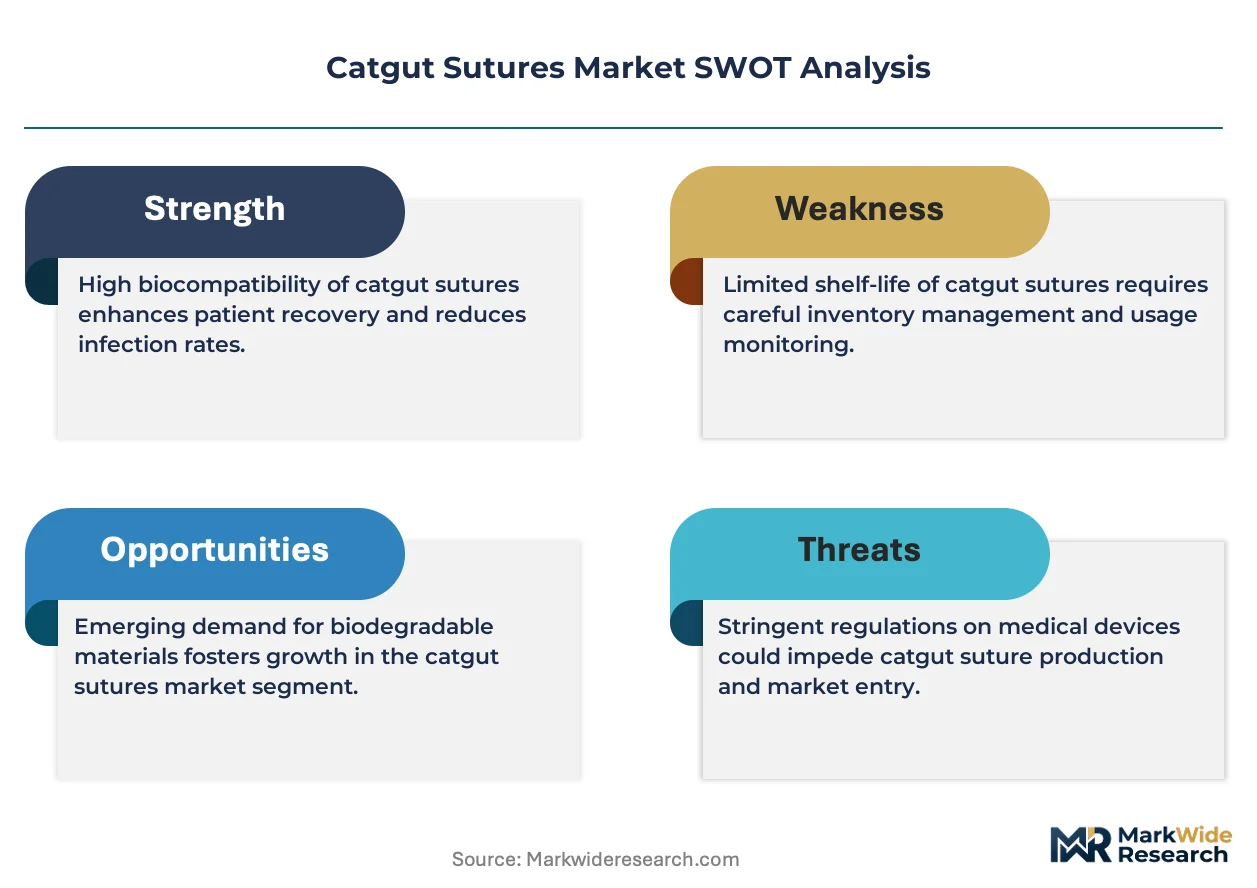
Absorbable polymer alternatives are compressing catgut into veterinary and cost-sensitive surgical niches where natural collagen fibers retain price advantage against synthetic substitutes.
Growth Catalysts
- Rural surgical demand:Public health systems in India's Maharashtra and Gujarat state clusters are scaling chromic catgut procurement for district hospital networks where synthetic sutures carry prohibitive pricing.
- Veterinary orthopedics volume:Equine and livestock surgical procedures in European veterinary channels sustain absorbable natural fiber consumption where chromic-treated collagen delivers adequate tensile strength at lower unit cost.
- EU MDR biocompatibility documentation:Tightened traceability mandates for natural fiber sutures are favoring established manufacturers with validated sterilization protocols, consolidating procurement toward compliant suppliers.
Market Restraints
- Sheep and goat intestine supply volatility:Raw material dependence on abattoir byproduct streams creates input cost instability and lot-to-lot collagen variability.
- Chromic salt residual quantification:ISO 10993 biocompatibility testing now mandates chromium level documentation, adding analytical cost burdens to each production batch.
- Synthetic absorbable convergence:Polyglactin and poliglecaprone price erosion threatens catgut's residual cost advantage in emerging market tenders.
Strategic Opportunities
- Ambulatory surgery center channel expansion:Outpatient hernia repair volumes are shifting suture consumption to lower-cost settings where catgut formulary inclusion remains viable.
- CDSCO registration pathway optimization:India's domestic manufacturers can accelerate import substitution by streamlining BIS standards compliance for natural fiber sutures.
- Ophthalmic microsurgery monofilament adoption:Reduced tissue drag variants are gaining traction in anterior segment procedures where knot security requirements moderate.
Industry Challenges
- Cross-Atlantic sterilization validation divergence:FDA biologics oversight and EU MDR impose incompatible traceability mandates that fragment compliance engineering resources.
- Residual chromium testing capability gaps:Contract laboratories face capacity constraints for ISO 10993 biocompatibility quantification, extending lot release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catgut Sutures Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $577.03 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-Absorbable, Monofilament, Multifilament Application: Orthopedic, General Surgery, Dental, Ophthalmic End User: Hospitals, Clinics, Ambulatory Surgery Centers, Veterinary Practices Material: Natural Fiber, Synthetic Fiber, Biodegradable Polymer, Metals |
| Companies Covered | Johnson & Johnson Services, Medtronic, B. Braun Melsungen AG, Smith & Nephew, Dolphin Sutures, Lotus Surgicals, Peters Surgical, DemeTech, SMB Corporation of India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catgut Sutures Market Strategic Shifts
Suture technology is bifurcating between premium synthetic absorbables and residual natural fiber applications, with regulatory documentation requirements becoming the primary axis of competitive differentiation.
Chromic catgut treatment protocols are virtualizing quality assurance workflows through automated chromium saturation monitoring and collagen denaturation tracking. Tertiary hospital laboratories in academic medical centers are adopting these inline spectroscopic systems to reduce batch-to-batch variability. The technology is virtualizing traditional manual inspection roles while compressing lot release cycle times from days to hours.
EU Medical Device Regulation biocompatibility documentation requirements are tightening traceability mandates for natural fiber sutures across all risk classes. Manufacturers must now maintain sterilization validation records spanning raw material abattoir sourcing through final packaging. Chromic catgut lots destined for European veterinary and human surgical channels face the most stringent residual chromium quantification thresholds.
Hospital formulary committees are consolidating suture suppliers around integrated surgical stapling bundles that reduce standalone catgut purchasing autonomy. Academic medical centers in North America are negotiating enterprise-wide contracts that subordinate individual surgeon preference to procurement efficiency metrics. This concentration is most visible in tertiary hospital systems where value analysis committees now override traditional department-level ordering authority.
Catgut Sutures Market Segmentation
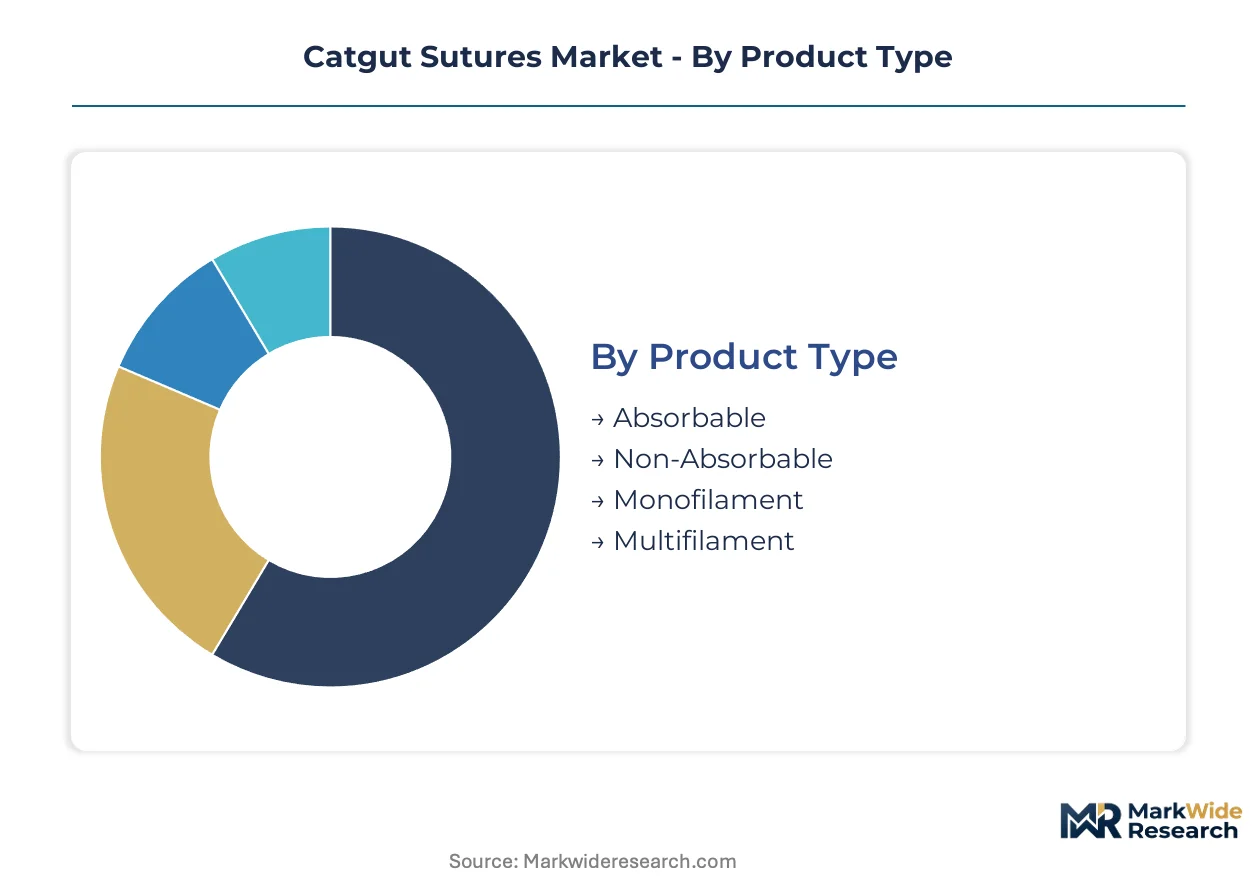
Catgut suture procurement patterns diverge sharply across clinical settings and material specifications, with natural fiber absorbables commanding distinct positions in cost-sensitive versus premium surgical workflows. Understanding these segment boundaries clarifies where chromic-treated collagen retains pricing power against synthetic substitutes.
Product Type:
Mature absorbable formats dominate hospital formulary volumes while emerging monofilament variants carve microsurgical niches.
- Absorbable:Chromic-treated collagen strands dissolve within 90–120 days, eliminating suture removal in hernia repairs and subcutaneous closures. Maharashtra and Gujarat district hospitals in India scale procurement for public health networks where synthetic alternatives carry prohibitive unit costs.
- Multifilament:Braided collagen construction delivers superior knot security in general surgery applications where tensile strength retention matters through critical wound healing phases. Tertiary hospital systems in academic medical centers specify multifilament chromic catgut for abdominal wall closures despite synthetic competition.
- Non-Absorbable:Permanent silk and polyester sutures serve cardiovascular and orthopedic tendon repair where long-term mechanical support outweighs absorption benefits.
- Monofilament:Single-strand collagen minimizes tissue drag in ophthalmic anterior segment procedures where reduced friction prevents corneal trauma.
Absorbable formats retain volume leadership across all procurement channels; monofilament variants hold the steepest expansion curve in specialized microsurgery.
Application:
Volume concentrates in high-throughput surgical departments while margin pools in precision subspecialties demanding specialized handling characteristics.
- General Surgery:Abdominal wall closures, hernia repairs, and subcutaneous tissue approximation consume the largest chromic catgut volumes. Ambulatory surgery centers capture shifting outpatient hernia volumes that sustain natural fiber formulary inclusion against bundled synthetic alternatives.
- Orthopedic:Ligament and tendon repairs in veterinary settings favor chromic catgut cost economics over synthetic absorbables. European equine surgical channels sustain demand where chromic-treated collagen delivers adequate tensile strength at lower unit cost for livestock procedures.
- Dental:Oral soft tissue closures utilize plain and chromic gut for mucosal approximation where rapid absorption eliminates patient return visits for suture removal.
- Ophthalmic:Anterior segment procedures require ultra-fine monofilament construction with minimal tissue reaction; ISO 10993 biocompatibility documentation for residual chromium quantification adds compliance burden to each production batch.
General surgery commands absolute unit volume; ophthalmic applications generate the highest per-procedure value realization.
End User:
Procurement autonomy fragments across facility types with divergent formulary control mechanisms and surgeon preference influence.
- Hospitals:Tertiary academic medical centers maintain chromic catgut on formulary for cost-conscious service lines while value analysis committees consolidate suppliers around integrated surgical stapling bundles.
- Veterinary Practices:Equine and livestock surgical channels in Europe absorb significant chromic catgut volume where B. Braun Melsungen AG specializes in veterinary-grade production with extended absorption profiles.
- Clinics:Office-based minor surgical procedures utilize plain gut for superficial closures where rapid absorption and low unit cost align with reimbursement constraints.
- Ambulatory Surgery Centers:Outpatient hernia repair volumes shift consumption to lower-cost settings where procurement efficiency metrics override individual surgeon brand preferences.
Hospitals retain volume leadership in absolute consumption; ambulatory surgery centers post the steepest procurement growth trajectory as outpatient migration accelerates.
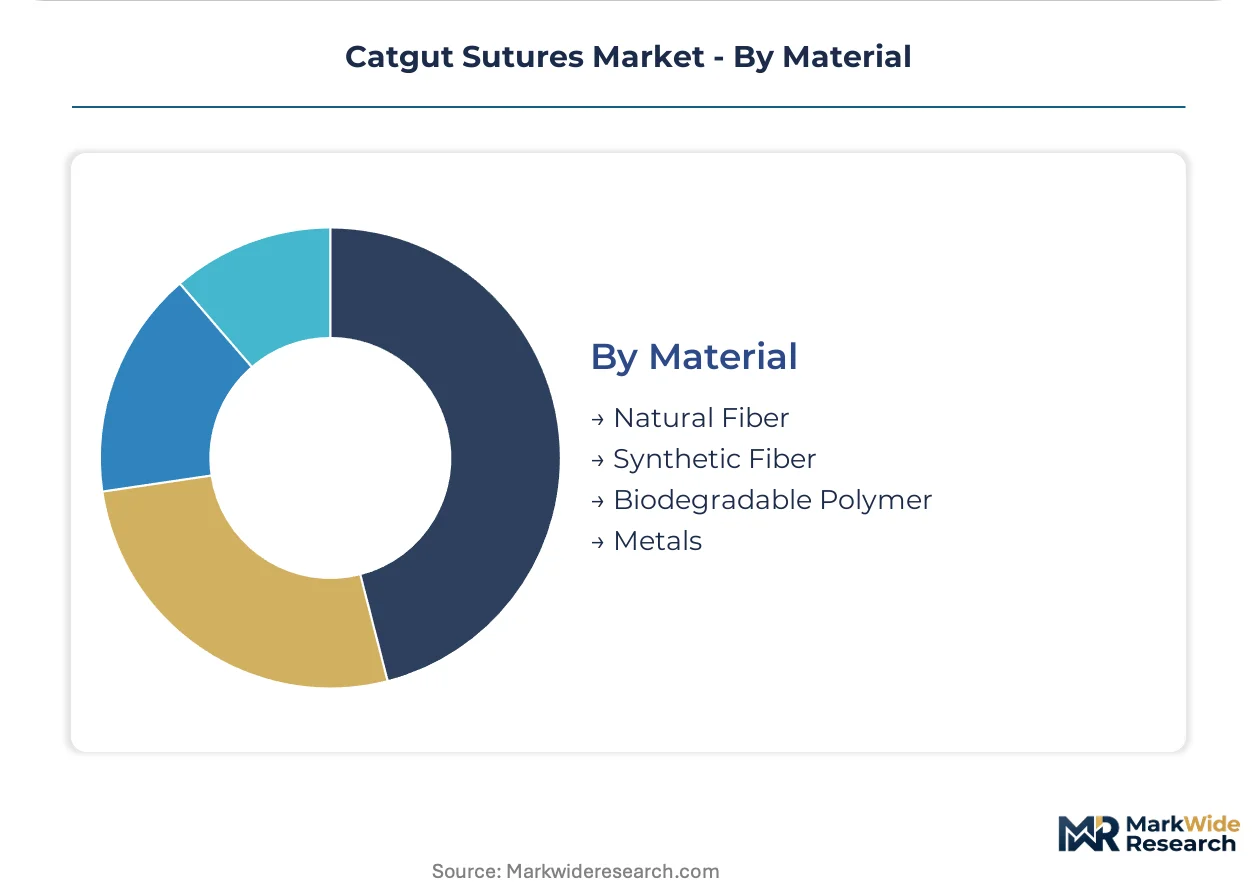
Material:
Supply concentration in abattoir-dependent natural fibers creates cost volatility that synthetic and metal alternatives exploit for contract security.
- Natural Fiber:Purified sheep and goat intestine collagen constitutes authentic catgut, with chromic salt treatment extending absorption timelines. EU MDR biocompatibility documentation mandates sterilization validation records spanning raw material abattoir sourcing through final packaging.
- Synthetic Fiber:Polyglactin and poliglecaprone alternatives erode catgut's residual cost advantage as manufacturing scale drives price convergence in emerging market tenders.
- Biodegradable Polymer:Engineered absorbables with predictable degradation kinetics target premium surgical segments where lot-to-lot variability in natural collagen creates clinical uncertainty.
- Metals:Stainless steel and titanium sutures serve permanent fixation applications in orthopedic and cardiovascular surgery outside catgut's functional domain.
Natural fiber retains volume leadership in cost-sensitive surgical and veterinary channels; biodegradable polymers gain share fastest in premium hospital systems prioritizing lot consistency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping catgut suture procurement, with India emerging as a net exporter of chromic-treated collagen strands while European markets tighten biocompatibility documentation requirements. Natural fiber suture trade flows concentrate where abattoir supply chains intersect with sterilization validation capabilities.
United States
FDA biologics oversight mandates sterilization validation records for natural fiber sutures entering hospital formulary systems. The agency's traceability requirements favor established manufacturers with validated protocols. Academic medical centers in Boston and the Research Triangle sustain chromic catgut procurement for cost-conscious service lines despite bundled synthetic alternatives.
Germany
EU MDR biocompatibility documentation tightens residual chromium quantification thresholds for natural fiber sutures. B. Braun Melsungen AG anchors veterinary-grade production from its Melsungen headquarters. The Baden-Württemberg medical technology cluster sustains specialized manufacturing for equine surgical channels across European livestock markets.
India
CDSCO and BIS standards create registration barriers that domestic manufacturers exploit for import substitution. Maharashtra and Gujarat state clusters scale chromic catgut production for export to African and Southeast Asian public health networks. Mumbai-based laboratories face capacity constraints for ISO 10993 biocompatibility testing, extending lot release timelines.
China
NMPA oversight of surgical sutures imposes sterilization validation requirements that fragment compliance engineering resources for natural fiber imports. The Yangtze River Delta medical device manufacturing corridor concentrates synthetic absorbable production that erodes catgut's residual cost advantage. Shanghai-based distributors navigate divergent traceability mandates for domestic versus export-bound chromic catgut lots.
Brazil
ANVISA registration pathways for natural fiber sutures favor suppliers with established sterilization validation documentation from US or EU regulatory precedents. São Paulo state public health tenders sustain chromic catgut procurement for district hospital networks where synthetic alternatives carry premium pricing. The Campinas medical device cluster hosts contract sterilization facilities serving regional catgut distributors.
Catgut Sutures Market Competitive Environment
On the supply side, the industry is consolidating around integrated surgical stapling bundles that reduce standalone catgut purchasing autonomy. Three strategic archetypes dominate: diversified medical technology conglomerates with hospital formulary leverage, specialized natural fiber manufacturers with veterinary channel focus, and regional fabricators serving cost-sensitive public health tenders. Competitive moves center on sterilization validation capability expansion and chromic treatment protocol standardization.
Within the diversified conglomerate tier, Johnson & Johnson Services and Medtronic exemplify scale-driven positioning through enterprise-wide hospital contracts. B. Braun Melsungen AG occupies a specialized position representing chromic catgut concentration for European veterinary channels. These three anchors illustrate how regulatory documentation capabilities and channel-specific formulary relationships determine competitive viability in natural fiber sutures.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| Medtronic |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Dolphin Sutures |
| Lotus Surgicals |
| Peters Surgical |
| DemeTech |
| SMB Corporation of India |
| Others |
Value Chain & Pricing Dynamics
Mumbai-Jawaharlal Nehru Port freight corridors transmit chromic salt and collagen processing equipment cost volatility directly into Maharashtra and Gujarat manufacturing clusters, compressing margins for export-bound natural fiber sutures while enabling price differentiation between ISO-certified premium grades and unchromicated economy tiers for domestic public health tenders.
Pricing Analysis
Next-generation automated chromium saturation monitoring systems command 40-60% price premiums over legacy manual-inspection catgut lots, while prior-generation plain gut sutures face accelerating price erosion in rural Indian district hospitals. Pricing stratifies across premium, standard, and economy tiers based on ISO 10993 biocompatibility documentation completeness and chromic treatment protocol standardization. Cost compression in economy-tier chromic catgut is intensifying because synthetic absorbable price convergence erodes natural fiber cost advantages in emerging market tenders. Veterinary practices in European livestock channels exhibit lowest price sensitivity due to formulary loyalty and regulatory entrenchment, while ambulatory surgery centers in cost-sensitive geographies demonstrate highest elasticity.
Supply Chain Analysis
Contract sterilization capacity concentrates among Mumbai-based laboratories and Campinas medical device cluster facilities serving regional distributors with ISO 11135 ethylene oxide validation. Geographic supply concentration centers on India, Germany, and Brazil for chromic-treated collagen production, with raw material streams drawing from Argentine and New Zealand abattoir networks for sheep and goat intestine supply. Single-source vulnerability pervades chromium salt procurement from South African mining operations, exposing batch-to-batch residual quantification variability. Distribution runs through hospital GPO contracts in North American academic medical centers and direct government tender channels in Indian state health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through sterilization validation documentation creates durable switching costs that protect incumbent formulary positions against synthetic substitute erosion.
For Market Incumbents: Harden chromic treatment protocol standardization through automated spectroscopic monitoring systems that compress lot release timelines from days to hours, while deepening backward integration into abattoir sourcing networks in Maharashtra and Gujarat to secure collagen supply against raw material volatility. ISO 10993 biocompatibility testing capacity expansion represents the critical lever for defending European veterinary channel dominance against emerging Indian exporters.
For New Entrants and Emerging Players: Pursue ophthalmic microsurgery monofilament segments where reduced tissue drag requirements and moderate knot security specifications create penetrable white space against established multifilament incumbents. India's CDSCO registration pathway optimization for domestic manufacturers offers the most accessible geographic entry point, with BIS standards compliance enabling import substitution in African and Southeast Asian public health networks through cost-competitive chromic catgut positioning.
For Investors and Strategic Acquirers: Specialized veterinary-grade manufacturers with validated EU MDR sterilization protocols and established equine channel relationships represent the most attractive acquisition archetype for portfolio diversification. Long-term viability hinges on whether synthetic absorbable price convergence stabilizes or accelerates, with quarterly monitoring of polyglactin and poliglecaprone tender pricing in Indian state health networks serving as the critical inflection signal for natural fiber residual cost advantage durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Chromium Saturation Monitoring Deployment | Inline spectroscopic systems reduce batch variability and compress lot release timelines for tertiary hospital laboratories. |
| EU MDR Biocompatibility Documentation Investment | Traceability mandates spanning abattoir sourcing through final packaging consolidate procurement toward compliant suppliers. |
| CDSCO Registration Pathway Optimization | Streamlined BIS standards compliance accelerates import substitution for domestic Indian manufacturers in export markets. |
| Ambulatory Surgery Center Channel Expansion | Outpatient hernia repair volumes shift suture consumption to lower-cost settings where catgut formulary inclusion remains viable. |
| Veterinary-Grade Production Specialization | European equine and livestock surgical channels sustain demand where chromic-treated collagen delivers adequate tensile strength. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, veterinary surgical supply coordinators, biomedical engineers, and GPO contracts managers; and secondary validation through FDA biologics filings, EU MDR sterilization validation records, CDSCO registration databases, and ISO 10993 biocompatibility testing protocols. Bottom-up triangulation across chromic catgut production volumes in Maharashtra and Gujarat manufacturing clusters converged with top-down assessment of absorbable suture market sizing across hospital, veterinary, and ambulatory surgery center channels.
Forecast inputs considered product type segmentation across absorbable, multifilament, and monofilament variants; application dimensions spanning general surgery, orthopedic, dental, and ophthalmic procedures; and end-user channel dynamics across tertiary hospitals, veterinary practices, and ambulatory surgery centers. CAGRs were derived through regression analysis of historical procurement patterns and projected outpatient procedural volume migration. Industry-specific inputs included chromic salt residual quantification testing capacity constraints and synthetic absorbable price convergence trajectories in emerging market public health tenders.
Macroeconomic conditions sit as an overlay; deviation in abattoir byproduct input costs, freight corridor pricing, or chromium salt commodity availability would shift the trajectory of natural fiber suture cost competitiveness. Forecasts reflect documented assumptions regarding regulatory documentation burden stability and synthetic substitute pricing elasticity. Quarterly review of EU MDR enforcement intensity, CDSCO registration processing timelines, and Indian state health tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Swab Cups Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Anti-Adhesion Barrier Gels Market