
 South America Syringe Market | 2026-2036
South America Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
South America Syringe Market Insights
Preventive maintenance contracts for autoinjector calibration and needle-safe disposal systems is repositioning how hospitals procure syringe ecosystems. Becton Dickinson and Company leverages its safety-engineered portfolio to anchor large-volume tenders across Brazilian state health networks. Terumo Corporation sustains competitive positioning through specialized insulin delivery systems for home care expansion. Nipro Corporation dominates glass prefillable syringe supply for biologic drug packaging across Andean markets.
A syringe is a cylindrical medical device fitted with a plunger and hollow needle, manufactured through precision injection molding of medical-grade polypropylene or borosilicate glass drawing, designed to deliver measured fluid doses via parenteral routes. Disposable syringes command the largest volume share due to single-use infection control protocols, while safety syringes represent the fastest structural expansion as needlestick prevention regulations harden across the continent. Plastic materials lead production economics, though glass prefillables capture premium margin pools in biologics cold chain applications.
ANVISA governs medical device registration and sterilization validation requirements in Brazil, while Argentina's national pharmaceutical regulator enforces comparable safety standards for imported syringe lots. REACH-aligned chemical safety protocols affect European-manufactured syringe imports entering Mercosur trade corridors. Stakeholders must monitor evolving prequalification standards for WHO-aligned immunization tenders and calibrate manufacturing footprints accordingly.
Market Dynamics
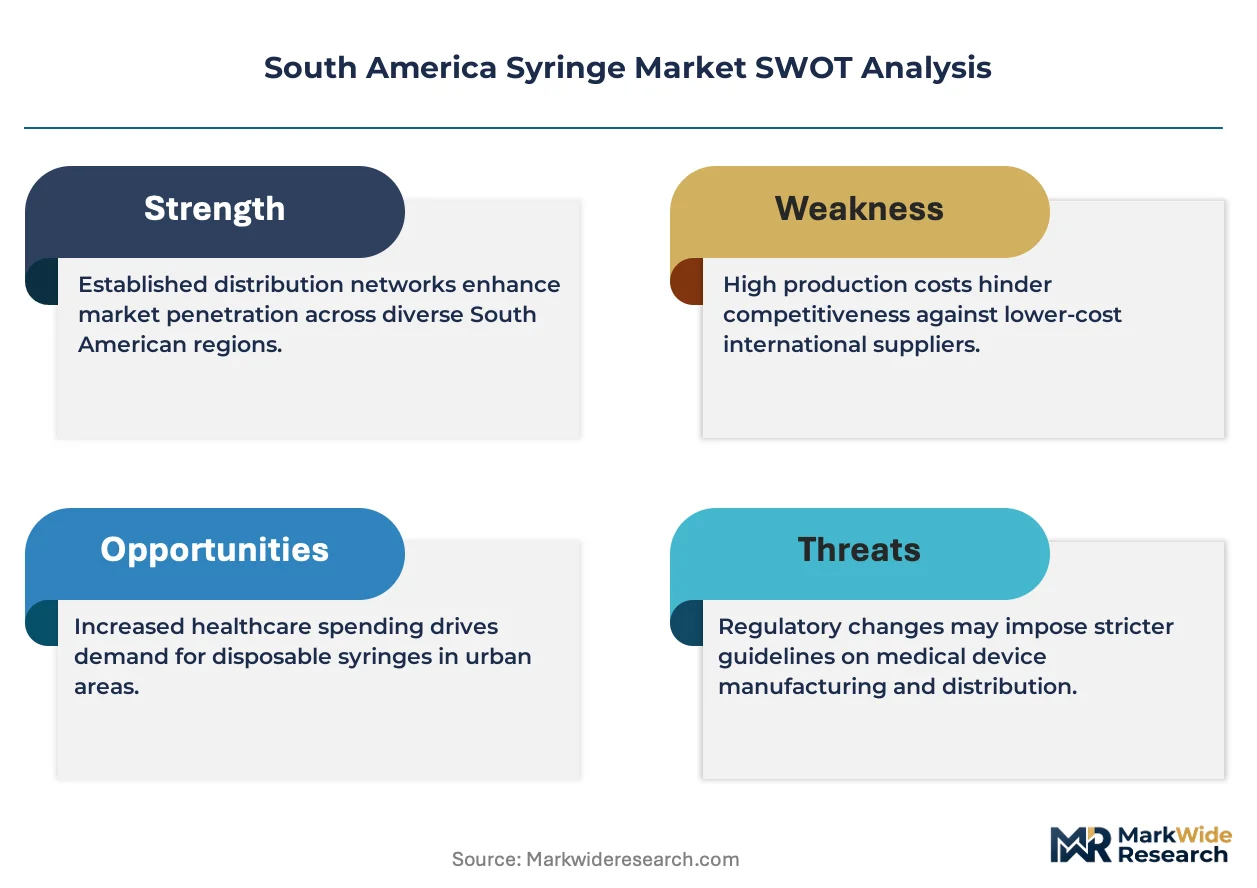
ANVISA's sterilization mandate revisions are compressing conversion timelines for safety-engineered syringes across Brazilian public health networks, forcing procurement systems to absorb premium unit costs while expanding volume commitments.
Growth Catalysts
- Vaccination Infrastructure:Brazil's expanded immunization programs are driving procurement volume commitments through state health networks. Argentine national vaccination schedules are amplifying similar demand pull through centralized tender mechanisms.
- ANVISA Sterilization Mandates:Updated medical device validation requirements are accelerating hospital conversions to single-use safety syringes. The regulatory pressure eliminates reusable alternatives from approved procurement lists.
- Biologics Cold Chain:Glass prefillable formats are capturing expanded packaging demand for temperature-sensitive biologic therapies across Andean distribution corridors.
Market Restraints
- Polypropylene Feedstock Volatility:Medical-grade resin pricing swings are compressing margin structures for disposable syringe manufacturers dependent on petrochemical supply chains.
- Import Concentration Risk:Brazilian public health networks rely heavily on Asian-manufactured safety syringe supply, exposing tender fulfillment to maritime logistics disruptions.
- Safety Mechanism Technical Limits:Retractable needle designs impose manufacturing yield penalties that constrain cost-competitive scaling for low-margin tender participation.
Strategic Opportunities
- Colombian Regional Expansion:Underpenetrated Andean procurement channels present white space for safety syringe vendors establishing localized distribution partnerships.
- Home Care Insulin Delivery:Specialized autoinjector formats for diabetes management are opening new patient-administered application segments outside hospital procurement systems.
- Preventive Maintenance Contracts:Service-based revenue models for calibration and disposal systems are creating channel innovation opportunities with large hospital networks.
Industry Challenges
- ANVISA Registration Timelines:Extended sterilization validation protocols are delaying product approval cycles and compressing competitive windows for new market entrants.
- Legacy Equipment Integration:Safety syringe formats require compatibility verification with existing infusion pump infrastructure, complicating hospital system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Syringe Market |
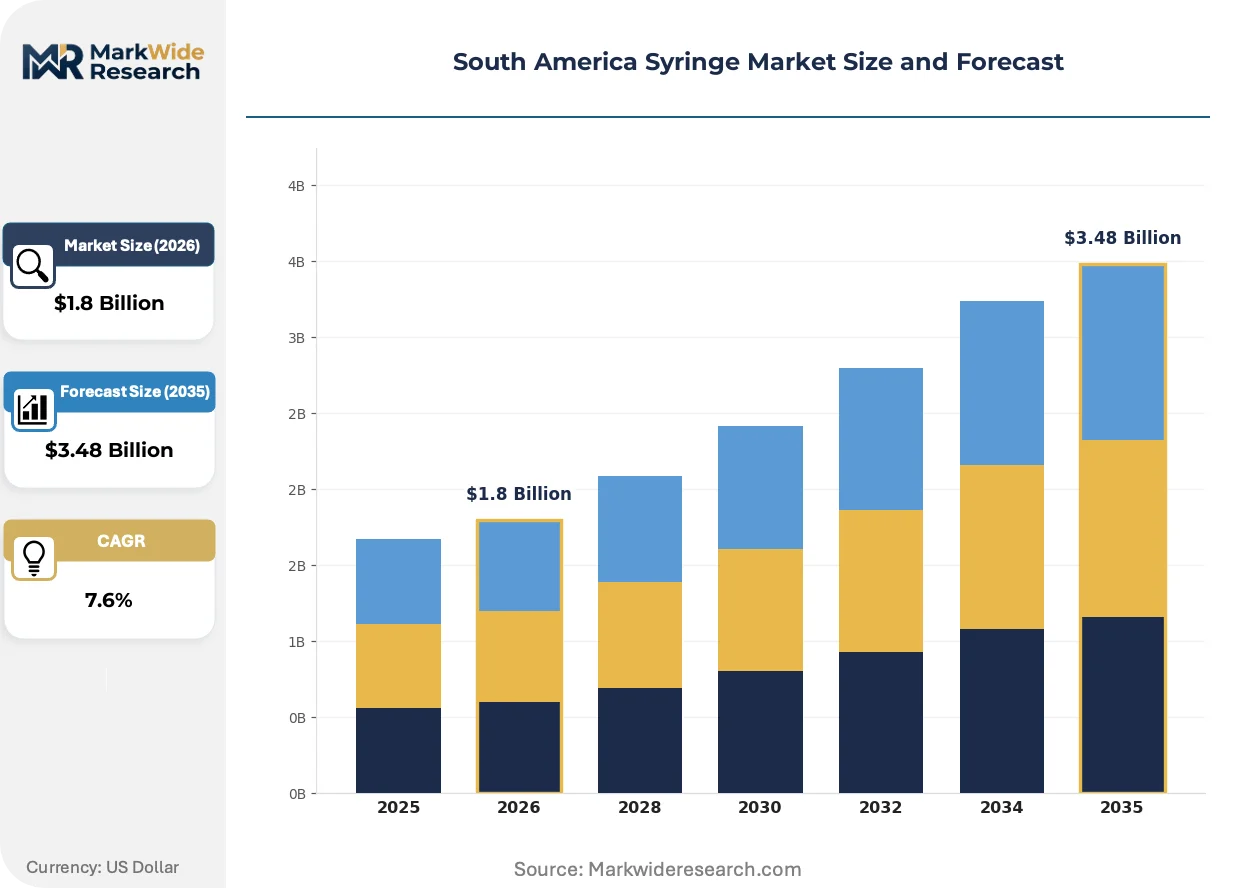
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Safety, Prefilled End User: Hospitals, Clinics, Home Care, Laboratories Material: Plastic, Glass, Rubber, Metal Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-arterial |
| Companies Covered | Becton Dickinson and Company, Terumo Corporation, Nipro Corporation, B. Braun SE, Gerresheimer AG, Medtronic, Merit Medical Systems, Inc., Cardinal Health, Hindustan Syringes & Medical Devices, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Syringe Market Trends and Innovations
Digital traceability systems are penetrating syringe manufacturing workflows, enabling lot-level authentication that aligns with evolving pharmaceutical serialization mandates across Mercosur trade corridors.
Smart safety mechanisms incorporating passive needle retraction are converging with connected health platforms that log administration events. Brazilian tertiary hospitals are piloting these integrated formats for oncology and biologic therapy tracking. The convergence is compressing traditional procurement silos between device and pharmaceutical budgets.
ANVISA's updated Good Manufacturing Practice requirements for sterile medical devices are mandating real-time environmental monitoring during injection molding operations. Manufacturers must install continuous particle detection systems and electronic batch record infrastructure. Brazilian production facilities are absorbing capital costs to maintain registration eligibility for public tenders.
Consolidated purchasing cooperatives are displacing fragmented hospital-level procurement across Argentine provincial health systems. These pooled buying structures concentrate negotiation leverage with safety syringe vendors and compress supplier margins. The behavioral shift is most visible in Buenos Aires and Córdoba health networks where cooperative membership exceeds individual hospital contracting.
South America Syringe Market Segmentation
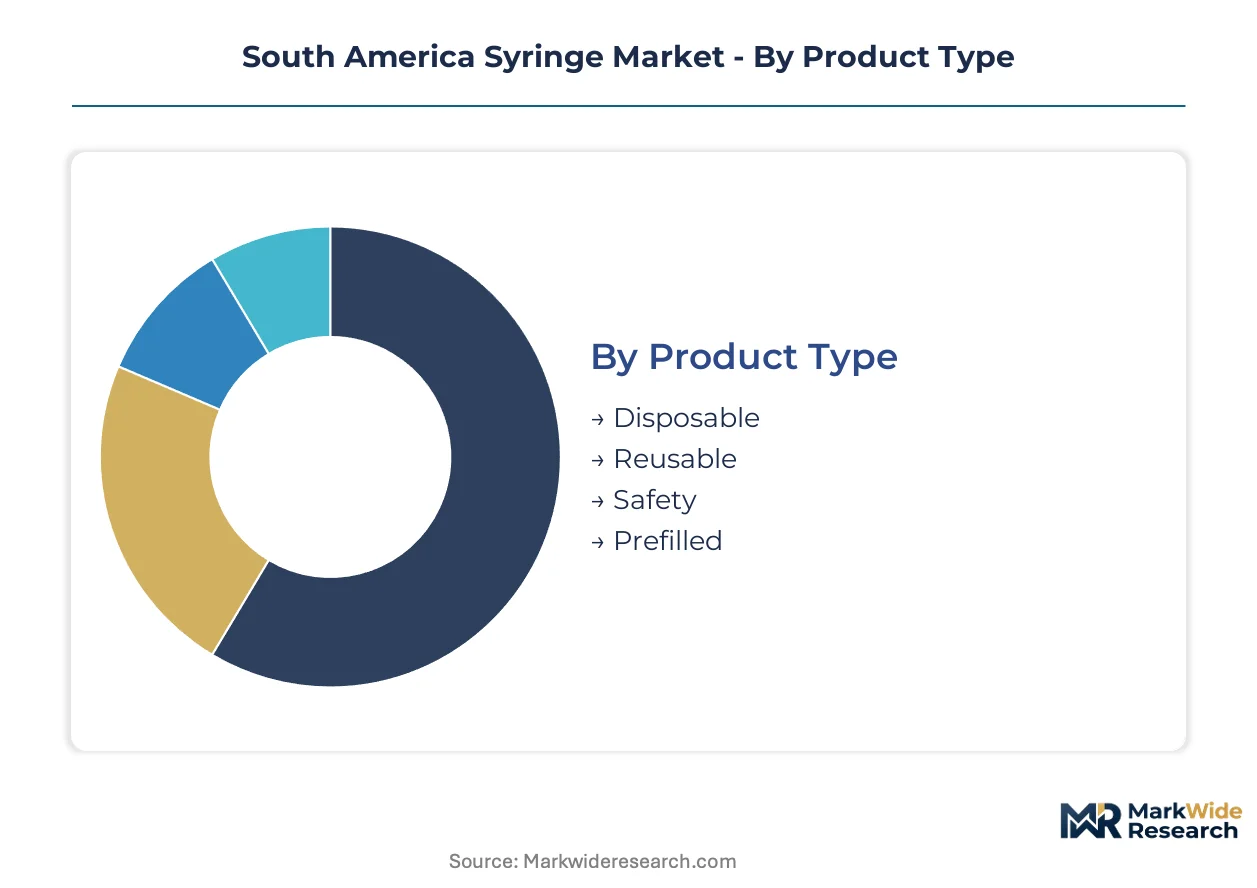
Syringe procurement across South America fragments across clinical settings, material specifications, and delivery protocols. Each segment carries distinct regulatory footprints and margin structures that shape vendor positioning.
Product Type:
Hospital procurement committees weight infection control compliance against total cost of ownership when selecting formats.
- Disposable:Single-use polypropylene devices dominate Brazilian public health tenders due to ANVISA sterilization mandates. Argentine provincial cooperatives consolidate volume commitments around this category.
- Safety:Retractable and shielded needle designs are capturing expanded share as needlestick prevention regulations harden across the continent. Brazilian state health networks now require safety-engineered formats for tender eligibility.
- Prefilled:Glass-barrel units preloaded with biologic therapies command premium positioning in Andean cold chain distribution.
- Reusable:Metal-and-glass legacy formats persist in limited veterinary and research applications where sterilization infrastructure remains captive.
Volume sits with Disposable; growth tilts toward Safety.
End User:
Channel concentration determines pricing leverage and service bundling requirements.
- Hospitals:Brazilian tertiary facilities anchor demand through consolidated purchasing cooperatives. Preventive maintenance contracts for disposal systems and calibration services are restructuring procurement relationships.
- Clinics:Outpatient vaccination centers across Argentina and Colombia drive high-frequency consumption with lower per-transaction values.
- Home Care:Insulin autoinjector adoption is expanding patient-administered delivery outside institutional settings.
- Laboratories:Research and diagnostic facilities require precision graduated formats with enhanced chemical compatibility.
Hospitals concentrate procurement volume; Home Care represents the steepest expansion trajectory.
Material:
Performance requirements and cold chain specifications dictate material selection across therapeutic categories.
- Plastic:Medical-grade polypropylene enables high-volume, low-cost production for standard disposable formats. Brazilian injection molding facilities are absorbing capital costs for ANVISA-mandated environmental monitoring systems.
- Glass:Borosilicate barrels provide chemical inertness for biologic drug packaging. Andean distribution corridors favor glass prefillables for temperature-sensitive therapies.
- Rubber:Elastomer plunger components ensure seal integrity across multiple sterilization cycles.
- Metal:Stainless steel needle cannulas and reusable frame components serve specialized industrial and research applications.
Plastic commands unit volume; Glass captures premium margin pools.
Delivery Mode:
Route specificity shapes needle gauge, barrel capacity, and safety mechanism design.
- Intramuscular:Standard immunization delivery drives bulk procurement across Brazilian national vaccination programs.
- Subcutaneous:Insulin and biologic therapies require specialized low-volume, fine-gauge formats for patient self-administration.
- Intravenous:Infusion pump compatibility requirements complicate safety syringe conversions in hospital settings.
- Intra-arterial:Specialized interventional procedures demand highest-precision graduated markings and minimal dead-space designs.
Intramuscular formats anchor public health volume; Subcutaneous applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American syringe procurement through its consolidated state health network purchasing cooperatives and concentration of tertiary hospital infrastructure.
Brazil
ANVISA sterilization mandates are compressing conversion timelines for safety-engineered formats across Minas Gerais and São Paulo state health networks. Brazil's national immunization program drives bulk disposable syringe procurement through centralized tenders. The São Paulo-Minas Gerais industrial corridor hosts injection molding facilities absorbing capital costs for real-time environmental monitoring systems.
Argentina
Provincial purchasing cooperatives in Buenos Aires and Córdoba are consolidating fragmented hospital procurement into pooled buying structures. Argentina's national pharmaceutical regulator enforces safety standards for imported syringe lots entering through Buenos Aires port. The Buenos Aires metropolitan health network concentrates negotiation leverage with safety syringe vendors.
Colombia
Underpenetrated Andean procurement channels present expansion opportunities for safety syringe vendors establishing distribution partnerships. Colombia's national health regulator maintains prequalification standards aligned with WHO immunization tender requirements. Bogotá's tertiary hospital clusters are piloting integrated smart safety mechanisms for oncology therapy tracking.
Chile
Santiago's public health system is expanding vaccination infrastructure through regional distribution centers. Chile's pharmaceutical regulatory agency enforces medical device sterilization validation comparable to ANVISA standards. The Santiago-Valparaíso corridor concentrates biologics cold chain distribution favoring glass prefillable formats.
Peru
Lima's national health insurance program is amplifying syringe procurement volumes through centralized tender mechanisms. Peru's national health authority maintains import registration requirements for medical device sterilization compliance. The Lima-Callao port cluster handles concentrated inflows of Asian-manufactured safety syringe supply.
South America Syringe Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South American syringe market. The vendor base fragments across multinational medical device conglomerates, specialized Japanese manufacturers, and regional distributors. Three archetypes dominate: safety-engineered portfolio specialists, glass prefillable format leaders, and high-volume disposable producers. Competitive moves concentrate on strategic partnerships with state health networks and localized distribution expansion.
Among the safety-engineered tier, Becton Dickinson and Company represents the consolidated multinational archetype with established Brazilian state network relationships. Terumo Corporation and Nipro Corporation exemplify specialized Japanese manufacturers competing through differentiated format portfolios. These three anchors occupy distinct positioning vectors—Becton Dickinson and Company through large-volume tender anchoring, Terumo Corporation through home care delivery specialization, and Nipro Corporation through glass prefillable supply dominance in Andean corridors.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| B. Braun SE |
| Gerresheimer AG |
| Medtronic |
| Merit Medical Systems, Inc. |
| Cardinal Health |
| Hindustan Syringes & Medical Devices |
| Others |
Pricing and Supply Chain Analysis
Safety-engineered versus standard disposable tier divergence splits procurement economics across Brazilian public health networks, with ANVISA sterilization mandates compressing conversion timelines while Asian import concentration constrains vendor pricing leverage. This bifurcation manifests in tender structures where safety syringes absorb premium unit costs against compressed margins for commodity disposables, and in supply chain configurations where maritime logistics exposure concentrates risk in low-cost manufacturing corridors.
Pricing Analysis
Margin tightening in standard disposable tiers reflects polypropylene feedstock volatility and consolidated purchasing cooperative leverage across Argentine provincial health systems. Contract-based long-term offtake dominates Brazilian state network procurement, with price differentiation driven by ANVISA certification grade and volume scale commitments. Cost-down pressure on safety-engineered formats accelerates because retractable needle manufacturing yield penalties constrain cost-competitive scaling. Hospital purchasing committees exhibit highest price sensitivity, while biologics manufacturers demonstrate lowest sensitivity for glass prefillable cold chain formats.
Supply Chain Analysis
ANVISA's domestic-content sterilization validation requirements are reshaping sourcing toward Brazilian injection molding facilities absorbing capital costs for real-time environmental monitoring systems. Manufacturing concentrates in China, India, and domestic Brazilian production corridors. Raw material dependencies center on medical-grade polypropylene resin, borosilicate glass drawing capacity, and stainless steel needle cannula supply. Single-source vulnerability persists in Asian-manufactured safety syringe components entering through Lima-Callao and Buenos Aires port clusters. Distribution runs through state health network purchasing cooperatives and consolidated provincial buying structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization validation capacity scarcity props pricing power for ANVISA-registered manufacturers, creating supply-constrained conditions where conversion timelines outpace qualified vendor availability.
For Market Incumbents: Hedge against Asian import disruption by securing captive polypropylene supply agreements or backward integration into medical-grade resin sourcing. Anchor position through preventive maintenance contract expansion for needle-safe disposal systems, defending against emerging service-based competitors. Prioritize certification investment in real-time environmental monitoring infrastructure to maintain tender eligibility under evolving ANVISA Good Manufacturing Practice requirements. For New Entrants and Emerging Players: Launch via specialized distribution partnerships targeting underpenetrated Colombian Andean procurement channels outside consolidated cooperative structures. Focus white-space capture on home care insulin autoinjector segments where patient-administered delivery escapes hospital procurement concentration. Prioritize Bogotá tertiary hospital pilot programs for smart safety mechanism integration as the most penetrable entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with glass prefillable specialists given biologics cold chain expansion across Andean corridors and premium margin capture in temperature-sensitive therapy packaging. Long-term viability favors manufacturers with ANVISA-registered Brazilian production footprints and sterilization validation infrastructure. Monitor ANVISA registration timeline compression as the critical inflection signal for competitive window availability.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Sterilization Certification Investment | Real-time environmental monitoring infrastructure secures tender eligibility for Brazilian state health networks. |
| Backward Integration into Medical-Grade Polypropylene | Captive resin supply hedges against petrochemical price volatility compressing disposable syringe margins. |
| Preventive Maintenance Contract Expansion | Service-based revenue models restructure hospital procurement relationships beyond transactional device sales. |
| Colombian Distribution Partnership Establishment | Localized Andean channel presence captures white-space expansion outside Argentine cooperative concentration. |
| Smart Safety Mechanism Pilot Deployment | Integrated oncology therapy tracking converges device and pharmaceutical budgets in tertiary hospital systems. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts managers, and ANVISA regulatory affairs specialists underwrites the qualitative findings in this analysis. Primary interviews with Brazilian state health network purchasing committees and Argentine provincial cooperative directors combined with secondary validation from ANVISA device registration databases, Mercosur trade flow records, and hospital procurement tender disclosures. Bottom-up volume triangulation against top-down market sizing anchors the analytical framework.
Comparable-period anchoring to historical immunization program procurement cycles and sterilization mandate implementation timelines structured the forecast window across the projection horizon. Segmentation modeling incorporated product type, end user channel, material specification, and delivery mode dimensions with ANVISA regulatory cluster overlays. CAGRs derived from tender volume commitments, conversion timeline assumptions, and biologics packaging demand trajectories. Forecast inputs included polypropylene resin price indices and maritime logistics disruption frequencies.
Regulatory enforcement variance, feedstock price volatility, and maritime logistics disruption are the dominant revision risks that could compress or extend conversion timelines and procurement volumes. Forecasts reflect documented assumptions regarding ANVISA registration processing speeds and cooperative purchasing consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Global Syringe Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Global IV Flush Syringe Market