
 Micro Vials Market | 2026-2036
Micro Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Vials Market Foresight
Aftermarket service revenue for container closure integrity testing and qualification support is tilting toward specialized packaging firms. Gerresheimer AG leverages its borosilicate glass furnace network to sustain premium positioning in parenteral drug containment. Schott AG anchors European supply through controlled thermal expansion tubing production for biologics. DWK Life Sciences competes across plastic and glass formats with broad laboratory and pharmaceutical channel control.
Micro vials are small-volume cylindrical containers, typically holding 0.5 to 10 milliliters, manufactured from borosilicate glass or pharmaceutical-grade polymers such as polypropylene and cyclic olefin polymer for chemical inertness and dimensional stability. They function primarily as primary packaging for injectable drugs, diagnostic reagents, and analytical samples where extractables, leachables, and seal integrity determine product safety. Glass vials retain dominance in high-value biologics where inertness and barrier properties command premium positioning, while plastic vials gain traction in point-of-care diagnostics and single-use workflows where breakage resistance and disposability reduce handling risk. Research laboratories and diagnostic centers represent the fastest-growing end-user pool as decentralized testing and contract research outsourcing expand procurement volumes.
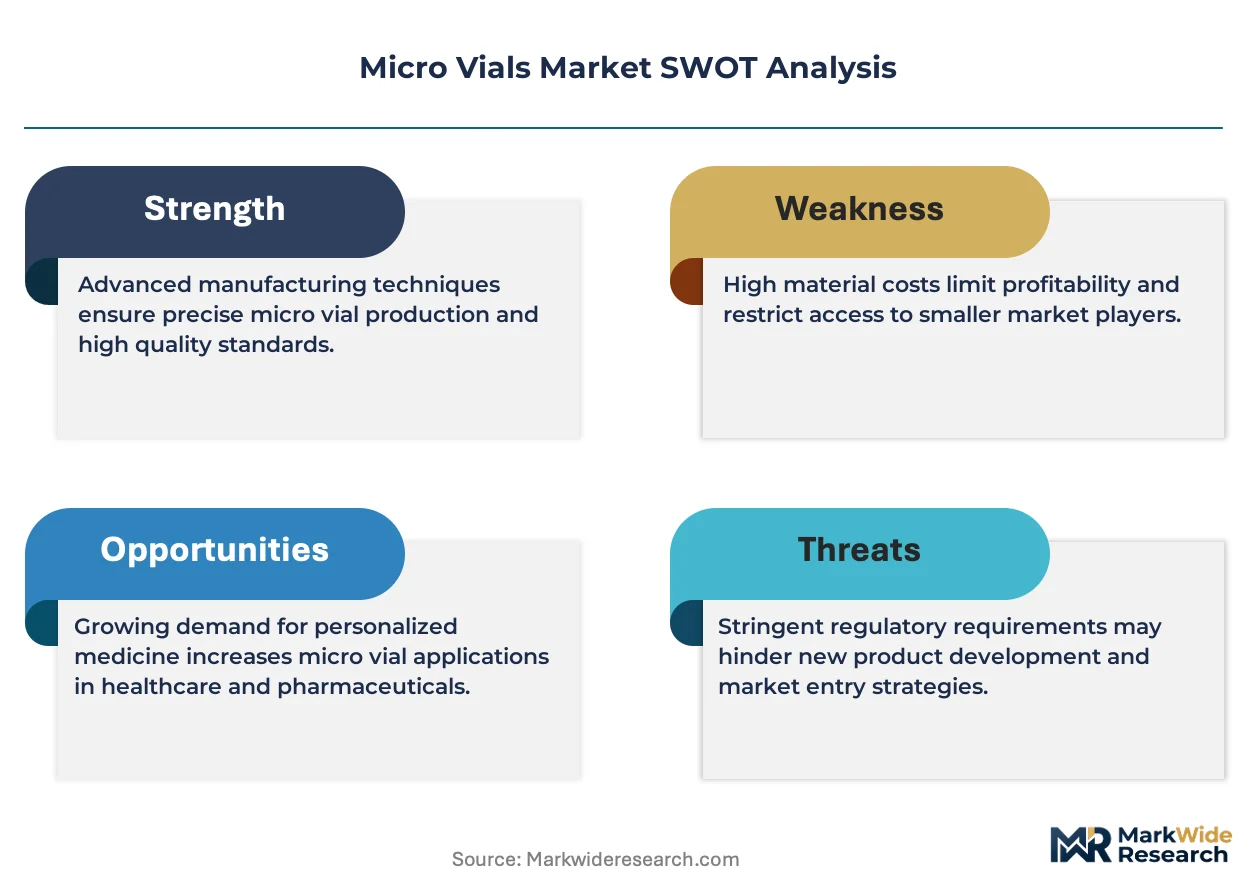
FDA container closure guidance, EU MDR Annex I general safety requirements, and USP <1207> package integrity evaluation standards collectively mandate deterministic leak detection and material qualification for sterile micro vial systems. These frameworks elevate barrier performance specifications and disqualify suppliers lacking validated testing infrastructure, compressing the approved vendor base for regulated pharmaceutical applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters to anticipate qualification burden shifts and align material selection with multi-jurisdictional filing requirements.
Market Dynamics
Container closure integrity mandates from FDA and EU MDR are compressing the qualified supplier base for sterile micro vial systems, forcing manufacturers to invest in deterministic leak detection infrastructure or exit regulated pharmaceutical channels.
Growth Catalysts
- Biopharmaceutical cold-chain expansion:Temperature-sensitive biologics require borosilicate glass micro vials with validated thermal shock resistance, pulling demand from mRNA vaccine and cell therapy manufacturers.
- EU MDR serialization mandates:Unique device identification requirements for Class III medical devices elevate traceability specifications for primary packaging, favoring suppliers with integrated printing and verification systems.
- Point-of-care diagnostic decentralization:Polypropylene micro vials gain preference in CLIA-waived testing workflows where breakage resistance and disposability reduce clinical handling risk.
Market Restraints
- Borosilicate glass furnace concentration:European and Japanese furnace networks control premium tubing supply, exposing buyers to energy cost volatility and geographic single-sourcing risk.
- Extractables qualification burden:USP <1661> and <1663> chapters require extensive chemical characterization of polymer micro vials, extending development timelines for new material entrants.
- Pre-filled syringe substitution:Ready-to-use delivery formats displace traditional vial-and-stopper systems in chronic disease administration, constraining volume growth in insulin and anticoagulant segments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's phased implementation of Good Manufacturing Practice harmonization creates demand for USP-compliant container closure systems among domestic injectable exporters.
- Cell and gene therapy workflows:Cryogenic storage requirements below minus 150 degrees Celsius favor specialized cyclic olefin polymer vials with validated seal integrity at ultra-low temperatures.
- ISO 15378 certification gap:Secondary packaging firms with primary packaging quality management systems can capture value-add qualification services from mid-tier pharmaceutical companies lacking in-house expertise.
Industry Challenges
- Container closure integrity technician scarcity:Validated vacuum decay and helium leak detection operators command premium wages, constraining testing capacity expansion at contract laboratories.
- Steam sterilization validation timelines:USP <1207> package integrity evaluation requires multiple sterilization cycles to demonstrate seal resilience, extending product qualification by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Vials Market |
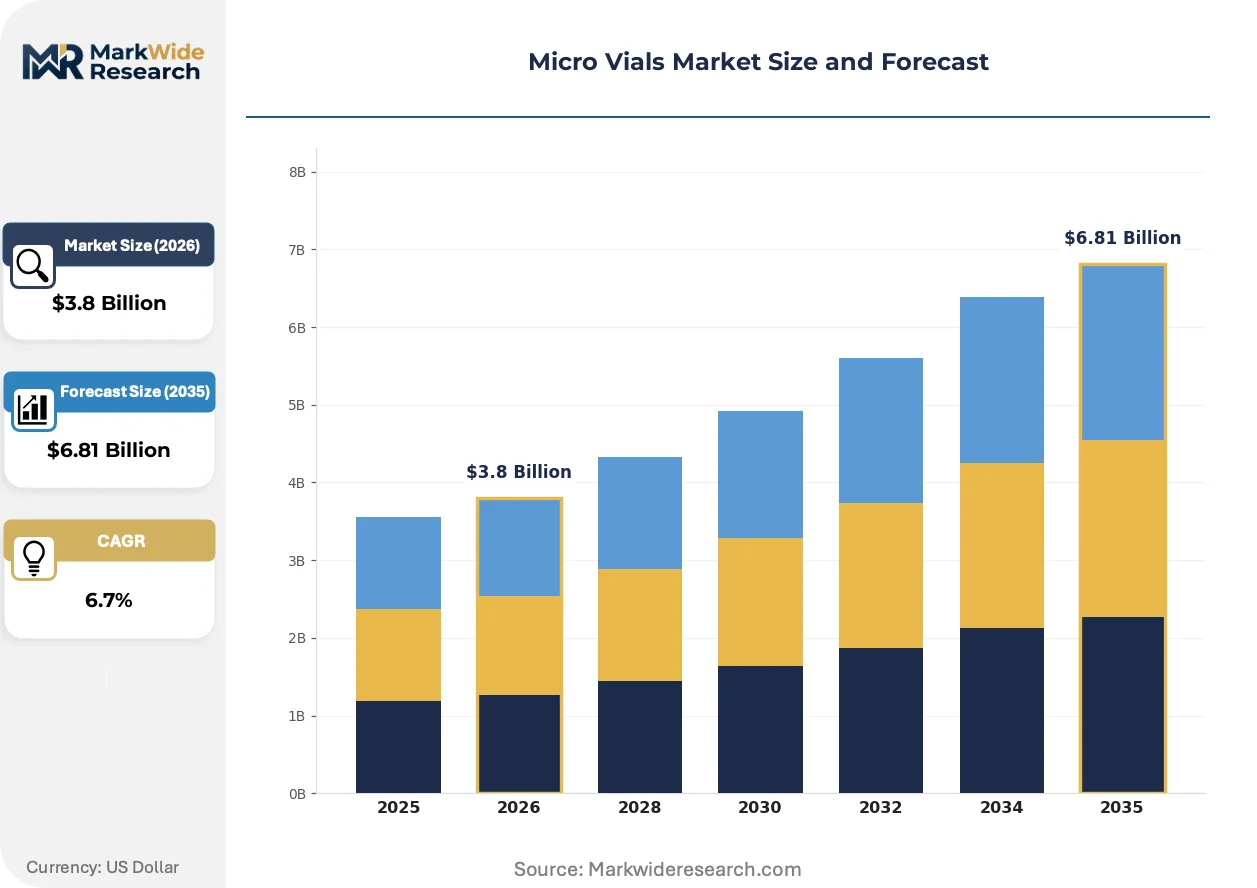
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Disposable Vials, Multi-Sample Vials End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Diagnostic Centers Material: Polypropylene, Polyethylene, Borosilicate Glass, PET Packaging Type: Bulk Packaging, Individual Packaging, Sterile Packaging, Custom Packaging |
| Companies Covered | Gerresheimer AG, Schott AG, DWK Life Sciences, Berry Global Group, Stevanato Group, SGD Pharma, Sigma-Aldrich Co. LLC, West Pharmaceutical Services, Inc., Thornton Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Vials Market Shifts & Advancements
Digital traceability and deterministic testing technologies are displacing probabilistic quality assurance methods across micro vial manufacturing, while regulatory convergence between USP, EP, and JP chapters reshapes material selection criteria.
Laser-etched serialization is digitizing unit-level traceability for borosilicate glass micro vials, enabling pharmaceutical manufacturers to meet FDA Drug Supply Chain Security Act requirements for track-and-trace interoperability. Contract packagers in Germany and the United States are retrofitting filling lines with vision systems that verify 2D Data Matrix codes at production speeds exceeding 400 units per minute. This capability is digitizing compliance infrastructure and compressing the competitive set to suppliers with integrated printing and verification platforms.
EMA's Annex I general safety requirements under EU MDR are elevating human factors engineering specifications for container closure systems, mandating torque-limited closure designs that reduce needlestick risk during reconstitution. Sterile injectable manufacturers in Ireland and Belgium are redesigning vial neck geometries to accommodate new elastomer formulations that meet both extractables limits and ergonomic handling requirements. Biologics packaging teams are responding by consolidating supplier relationships with firms holding dual USP and EP pharmacopeial compliance.
Diagnostic laboratory buyers are consolidating procurement through group purchasing organizations that bundle micro vial supply with instrument service contracts, displacing spot-market purchasing for high-throughput screening applications. Reference laboratories in Japan and the United States are negotiating multi-year agreements with packaging firms that guarantee volume commitments in exchange for dedicated production slots and priority qualification support. This concentration is most visible in nucleic acid extraction workflows where supply continuity directly determines diagnostic test availability.
Micro Vials Market Segmentation
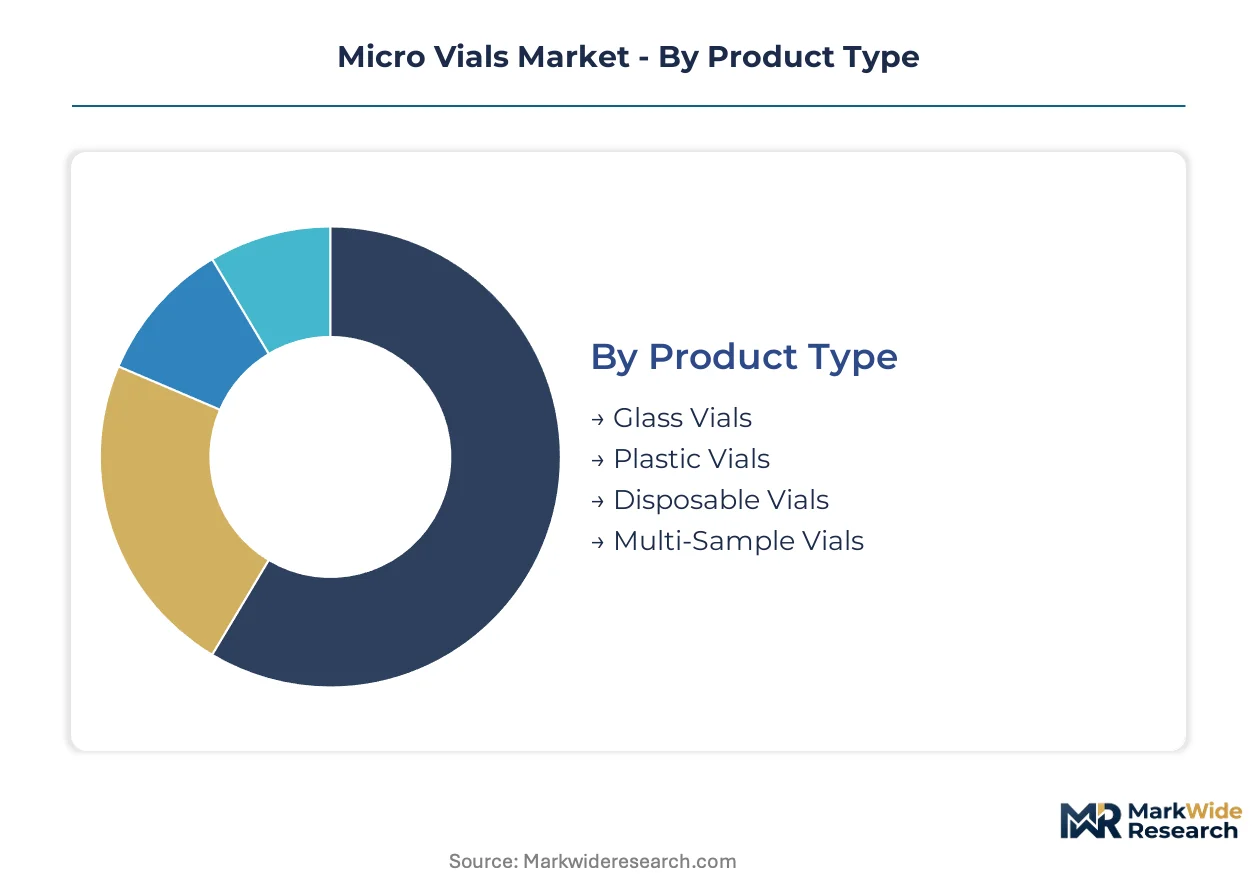
Micro vial procurement patterns diverge sharply across material grades, sterility requirements, and end-use workflows. Segmentation reveals how glass furnace capacity, polymer extractables testing, and diagnostic decentralization reshape supplier selection criteria.
Product Type:
Cost tier differentiation separates premium containment systems from commodity disposables.
- Glass Vials:Borosilicate formulations with controlled thermal expansion coefficients serve biologics requiring thermal shock resistance across cryogenic to autoclave cycles. German and Japanese furnace networks supply mRNA vaccine manufacturers facing FDA container closure guidance.
- Plastic Vials:Polypropylene and cyclic olefin polymer constructions withstand breakage in point-of-care settings. CLIA-waived testing workflows in United States diagnostic chains favor disposability over barrier performance.
- Disposable Vials:Single-use formats eliminate cross-contamination risk in cell therapy manufacturing.
- Multi-Sample Vials:Segmented internal chambers enable parallel analytical processing in high-throughput screening.
Glass vials command the established base. The steepest expansion runs through plastic vials.
End User:
Application workflow determines volume scale and qualification burden simultaneously.
- Pharmaceutical Companies:Sterile injectable manufacturers demand USP <1207> validated container closure integrity with deterministic leak detection. EU MDR serialization mandates compress approved vendor lists to suppliers with integrated printing infrastructure.
- Research Laboratories:Contract research outsourcing expands procurement volumes for non-sterile analytical grades. Academic and commercial labs in Japan prioritize dimensional consistency for automated liquid handling compatibility.
- Hospitals:Compounding pharmacies require ISO 15378 certified primary packaging for patient-specific parenteral preparations.
- Diagnostic Centers:Decentralized nucleic acid extraction workflows favor polypropylene formats with validated seal integrity at ultra-low temperatures.
Pharmaceutical companies anchor revenue concentration. Diagnostic centers are climbing the fastest.
Material:
Supply concentration and extractables qualification timelines stratify material selection.
- Polypropylene:Pharmaceutical-grade homopolymers offer chemical inertness and steam sterilization compatibility. USP <1661> extractables characterization extends development timelines for new resin grades.
- Polyethylene:Lower density formulations reduce unit cost for high-volume diagnostic applications.
- Borosilicate Glass:Type I tubing with hydrolytic resistance class HC1 retains dominance for parenteral biologics. European furnace energy costs inject volatility into pricing.
- PET:Amorphous polyester barriers suit non-sterile liquid chromatography sample containment.
Borosilicate glass holds the premium position. Polypropylene gains share fastest.
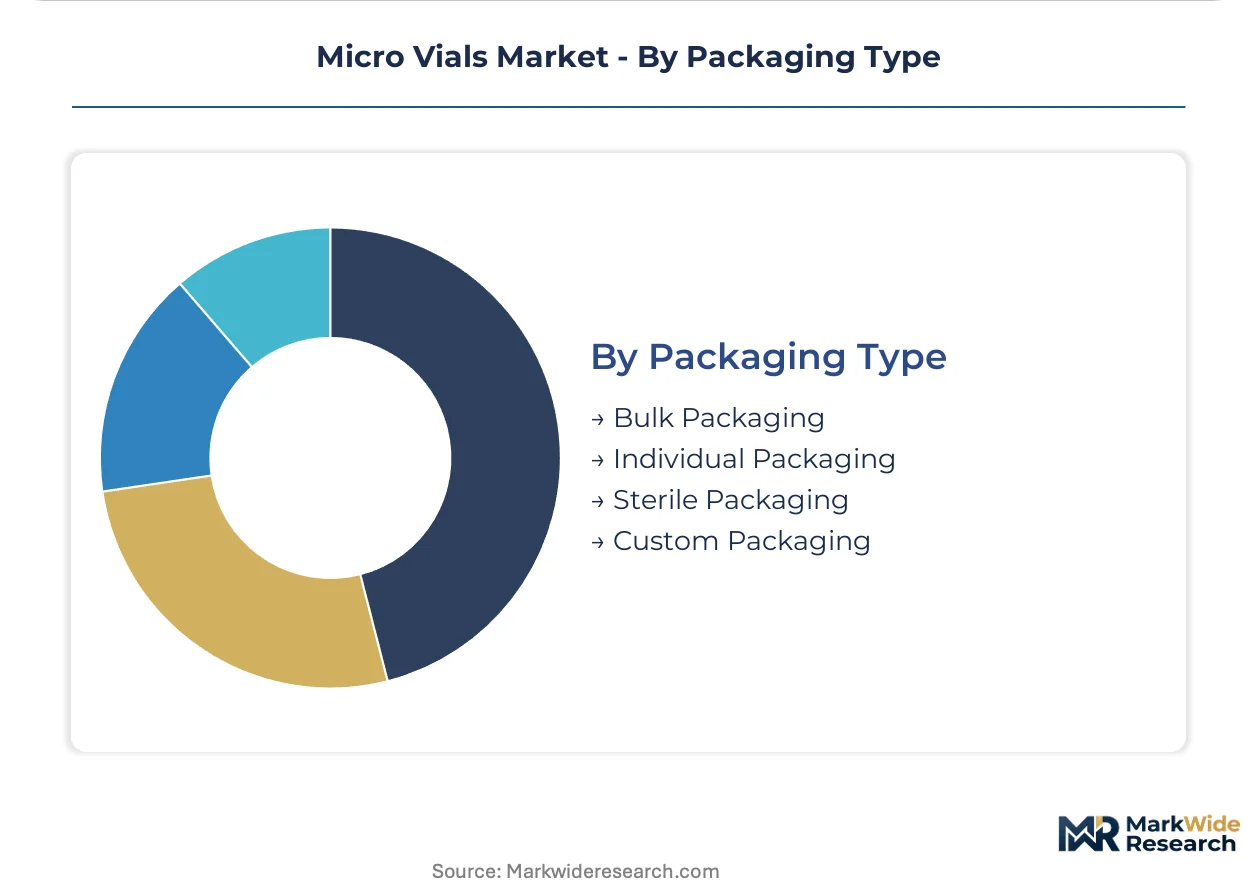
Packaging Type:
Customer type and sterility assurance level determine packaging configuration.
- Bulk Packaging:Unsterile nested trays serve contract laboratories with in-house depyrogenation capacity. Research institutions in Germany optimize total cost through high-volume procurement.
- Individual Packaging:Unit-of-use formats reduce contamination risk in aseptic processing isolators.
- Sterile Packaging:Gamma-irradiated or steam-sterilized configurations meet USP <1207> requirements for finished drug products.
- Custom Packaging:Laser-etched serialization and torque-limited closure designs address EU MDR Annex I human factors specifications.
Sterile packaging dominates regulated pharmaceutical channels. Custom packaging expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Germany and Japan favor borosilicate glass for biopharmaceutical containment, while the United States and India tilt toward polypropylene formats in diagnostic and point-of-care workflows.
Germany
Borosilicate glass furnace networks supply mRNA vaccine manufacturers with controlled thermal expansion tubing. The EU MDR Annex I general safety requirements tighten container closure integrity standards for sterile injectables. Industrial clusters in Bavaria and North Rhine-Westphalia host filling line retrofits with vision systems for 2D Data Matrix verification.
United States
Point-of-care diagnostic decentralization drives polypropylene micro vial procurement for CLIA-waived testing workflows. FDA container closure guidance mandates deterministic leak detection infrastructure for sterile drug products. Massachusetts and North Carolina biomanufacturing corridors consolidate supplier relationships with integrated printing and verification platforms.
Japan
Pharmaceutical companies demand USP-compliant borosilicate glass for parenteral biologics with validated thermal shock resistance. PMDA serialization requirements align with FDA Drug Supply Chain Security Act track-and-trace mandates. The Kanto region around Tokyo anchors nucleic acid extraction workflow supply with multi-year volume agreements.
India
Domestic injectable exporters seek USP-compliant container closure systems as CDSCO phases in Good Manufacturing Practice harmonization. Polypropylene formats gain preference in contract research outsourcing for automated liquid handling compatibility. Gujarat and Maharashtra pharmaceutical manufacturing zones expand procurement of qualified primary packaging for regulated export markets.
United Kingdom
Research laboratories prioritize dimensional consistency for high-throughput screening applications. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned serialization for Class III medical device packaging. The Golden Triangle biotech corridor between London, Cambridge, and Oxford consolidates micro vial procurement through group purchasing organizations.
Micro Vials Market Competitive Landscape
Capability concentration sits with furnace-controlled glass specialists; scale advantage sits with polymer converters with broad laboratory channel reach. The vendor base stratifies across three tiers: integrated pharmaceutical packaging conglomerates with dual pharmacopeial compliance, mid-cap specialists in cryogenic or diagnostic-grade formats, and regional distributors with ISO 15378 certification gaps. Dominant competitive moves include backward integration into borosilicate tubing production and strategic partnerships with contract packagers for integrated serialization infrastructure.
Among German-headquartered conglomerates, Gerresheimer AG and Schott AG occupy positions anchored by furnace network control and pharmacopeial qualification depth. DWK Life Sciences represents the diversified-format archetype spanning plastic and glass with broad channel presence. These three exemplify how geographic proximity to pharmaceutical manufacturing clusters shapes competitive positioning in regulated primary packaging.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| DWK Life Sciences |
| Berry Global Group |
| Stevanato Group |
| SGD Pharma |
| Sigma-Aldrich Co. LLC |
| West Pharmaceutical Services, Inc. |
| Thornton Plastics |
| Others |
Supply & Pricing Matrix
Undercapacity in European borosilicate glass furnace networks tightens pricing leverage for tubing suppliers serving mRNA vaccine manufacturers, while polypropylene converters absorb resin cost volatility through long-term offtake structures with diagnostic laboratory chains.
Pricing Analysis
Long-term offtake contracts dominate procurement for sterile pharmaceutical grades, locking in volume commitments against dedicated production slots. Three-tier pricing structure across premium borosilicate, mid-grade polymer, and economy diagnostic tiers reflects USP compliance burden and furnace energy exposure. Cost compression in standard polypropylene runs through resin index linkage and volume scale thresholds. Contract research organizations exhibit highest price sensitivity due to spot-market purchasing flexibility, while biologics manufacturers prioritize qualification continuity over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and United States pharmaceutical manufacturing corridors dominates supply chain risk planning for serialization-enabled vial formats. Borosilicate tubing production concentrates in Germany and Japan; polypropylene resin draws from Saudi Arabian and South Korean petrochemical complexes. Single-source vulnerability persists for controlled thermal expansion glass grades qualified to FDA container closure guidance. Distribution runs through direct manufacturer relationships with filling line operators, bypassing distributor markup for regulated pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container closure integrity testing infrastructure is becoming a platform layer where qualification data interoperability determines supplier stickiness, accelerated by EU MDR and FDA serialization system convergence.
For Market Incumbents: Entrench furnace network advantages through captive borosilicate tubing supply and deterministic leak detection service bundling. Pre-filled syringe substitution threatens volume in insulin and anticoagulant segments; backward integration into laser-etched serialization equipment preserves premium positioning against integrated packaging conglomerates.
For New Entrants and Emerging Players: Pursue cryogenic cyclic olefin polymer formats for cell therapy workflows below minus 150 degrees Celsius, where established glass suppliers lack validated seal integrity data. CDSCO's phased GMP harmonization in India creates the most penetrable regulatory entry point for USP-compliant polymer systems. Lead with automated liquid handling compatibility certifications to bypass incumbent channel control in contract research outsourcing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across deterministic testing infrastructure and ISO 15378 certification capabilities. Five-to-ten year viability favors mid-tier specialists with dual pharmacopeial compliance depth over pure-play distributors. Watch for container closure integrity technician wage inflation as the inflection signal for testing capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive furnace supply secures margin control against Gerresheimer and Schotts European network dominance. |
| Deterministic Leak Detection Service Launch | USP 1207 compliance infrastructure captures aftermarket revenue from mid-tier pharmaceutical manufacturers. |
| Laser-Etched Serialization Platform Deployment | FDA Drug Supply Chain Security Act interoperability requirements favor integrated printing and verification systems. |
| Cryogenic Polymer Format Development | Cell therapy storage below minus 150 degrees Celsius opens white space beyond glass thermal shock limits. |
| ISO 15378 Certification Gap Closure | Secondary packaging firms with primary packaging quality systems capture value-add qualification services. |
Research Methodology
Operator-level perspectives from sterile injectable manufacturing heads, container closure integrity testing technicians, diagnostic laboratory procurement managers, and GPO contracts directors anchored the qualitative base. Primary interview findings triangulated against FDA container closure guidance filings, EMA Annex I general safety requirement submissions, USP chapter revision dockets, and pharmaceutical manufacturer 10-K supply chain disclosures. Bottom-up volume estimates from furnace capacity utilization and polymer extrusion line counts converged with top-down pharmaceutical packaging spend analysis.
Scenario-bracketing around EU MDR implementation pace and CDSCO GMP harmonization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, sterility assurance level, end-use workflow type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves for biopharmaceutical cold-chain expansion and point-of-care diagnostic decentralization. Forecast inputs incorporated mRNA vaccine manufacturing capacity buildouts and CLIA-waived testing regulatory velocity.
Sensitivities concentrate around borosilicate furnace energy cost volatility, polymer extractables qualification timeline extensions, and pre-filled syringe substitution rates in chronic disease administration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Swab Cups Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Breast Shells Market
Medical Supplies
Global Syringe Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Pressure Redistribution Pads Market