
 Middle East and Africa Hospital Furniture Market | 2026-2036
Middle East and Africa Hospital Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hospital Furniture Market Foresight
Aftermarket service revenue is tilting toward preventive maintenance contracts and furniture lifecycle management as acute-care facilities extend capital replacement cycles. Hill-Rom Services leverages its technical service network across Gulf state hospital clusters to capture recurring revenue streams. Stiegelmeyer GmbH & Co. KG anchors its regional position through specialized bariatric and intensive care bed platforms engineered for Middle Eastern patient demographics. Skytron competes on operating room integration, supplying surgical booms and lighting systems that interface with its furniture lines.
Hospital furniture encompasses beds, tables, seating, storage, and accessory systems engineered for clinical environments, typically constructed from powder-coated steel, antimicrobial polymers, and medical-grade upholstery meeting fire-retardant and infection-control specifications. Patient beds dominate procurement budgets across public hospital tenders, while modular form factors represent the fastest-growing configuration as facilities reconfigure wards for surge capacity and specialized care zones. Metal-framed products sustain the largest material share due to durability requirements, though plastic components gain traction in pediatric and psychiatric settings where ligature resistance and weight reduction matter.
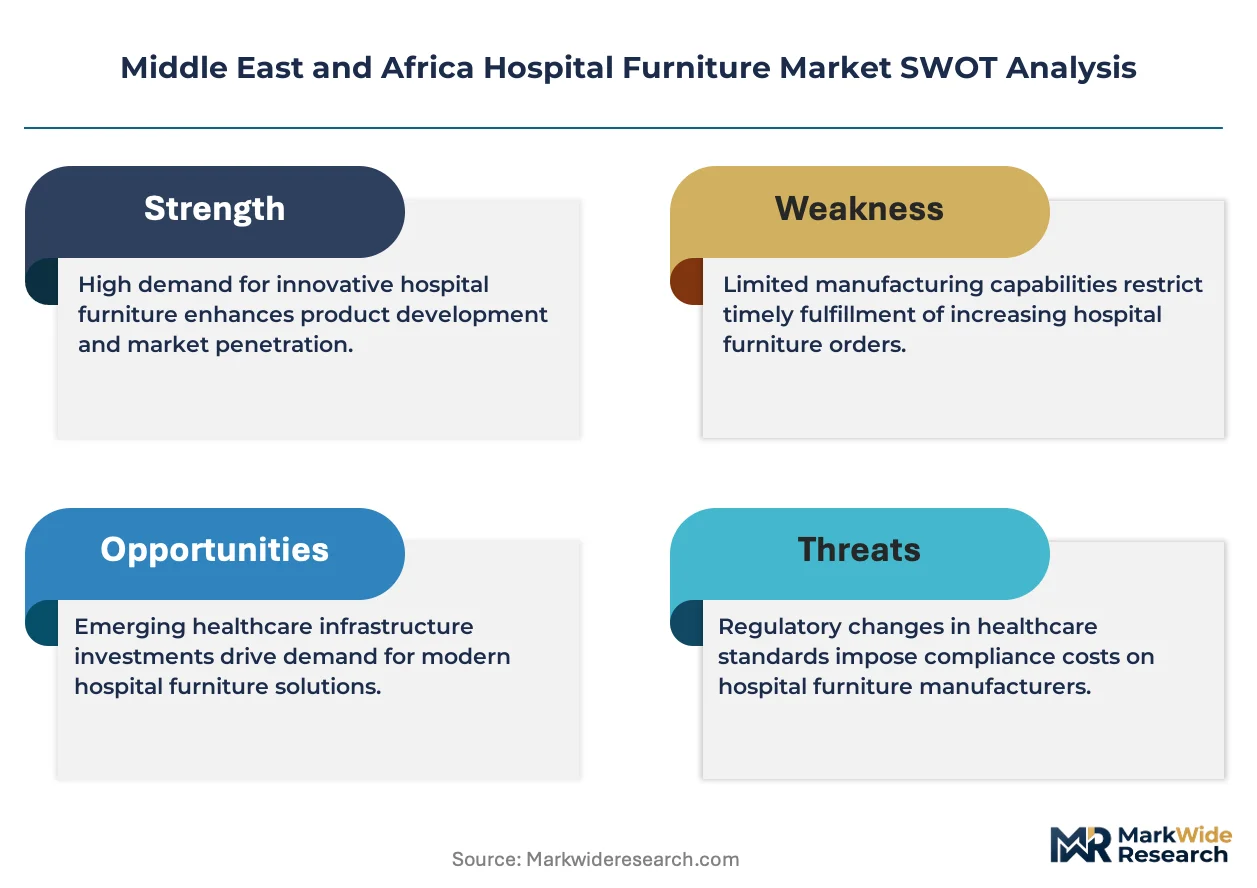
Saudi Arabia's SFDA enforces medical device registration and post-market surveillance that elevates compliance costs for imported hospital furniture. South Africa's health facility licensing framework, administered by provincial health departments, mandates specific equipment standards for accreditation that shape local procurement specifications. The UAE's Ministry of Health and Prevention (MOHAP) and Dubai Health Authority impose Joint Commission International alignment requirements that filter supplier eligibility. Stakeholders must monitor how Egypt's emerging hospital privatization program and Morocco's medical city investments redirect demand toward premium adjustable systems versus basic fixed furniture.
Market Dynamics
Private hospital chains across the Gulf Cooperation Council are consolidating procurement authority into centralized purchasing offices, compressing supplier margins while elevating technical specification requirements for motorized beds and modular ward systems.
Growth Catalysts
- SFDA Medical Device Registration:Saudi Arabia's tightened post-market surveillance creates compliance barriers that favor established suppliers with in-country technical infrastructure.
- Modular Ward Configurations:Surge-capacity requirements from Abu Dhabi Health Services Company and similar entities are accelerating replacement of fixed-position furniture with reconfigurable platforms.
- Metropolitan Healthcare Districts:South Africa's provincial health departments are channeling capital budgets toward accredited facility renovations in Gauteng and Western Cape.
Market Restraints
- Steel and Aluminum Input Volatility:Powder-coated metal frames constitute the dominant material share, exposing manufacturers to commodity price swings affecting tender competitiveness.
- Import Dependency Concentration:Domestic production capacity for medical-grade upholstery and antimicrobial polymers remains concentrated in European and East Asian supply bases.
- Joint Commission International Alignment:UAE MOHAP and Dubai Health Authority accreditation requirements extend product validation timelines for new market entrants.
Strategic Opportunities
- Egypt Hospital Privatization:The emerging public-private partnership framework redirects demand toward premium adjustable systems in Cairo and Alexandria medical zones.
- Preventive Maintenance Contracts:Acute-care facilities are extending capital replacement cycles, creating recurring revenue streams for technical service networks.
- Bariatric Bed Platforms:Specialized intensive care configurations engineered for regional patient demographics address an underserved specification tier.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Gulf state hospital clusters face shortages of technicians qualified to service motorized bed electronics and integrated nurse-call systems.
- Legacy Ward Infrastructure:Nigeria's federal teaching hospital renovation programs must integrate modular furniture with decades-old building utilities and floor-loading constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hospital Furniture Market |
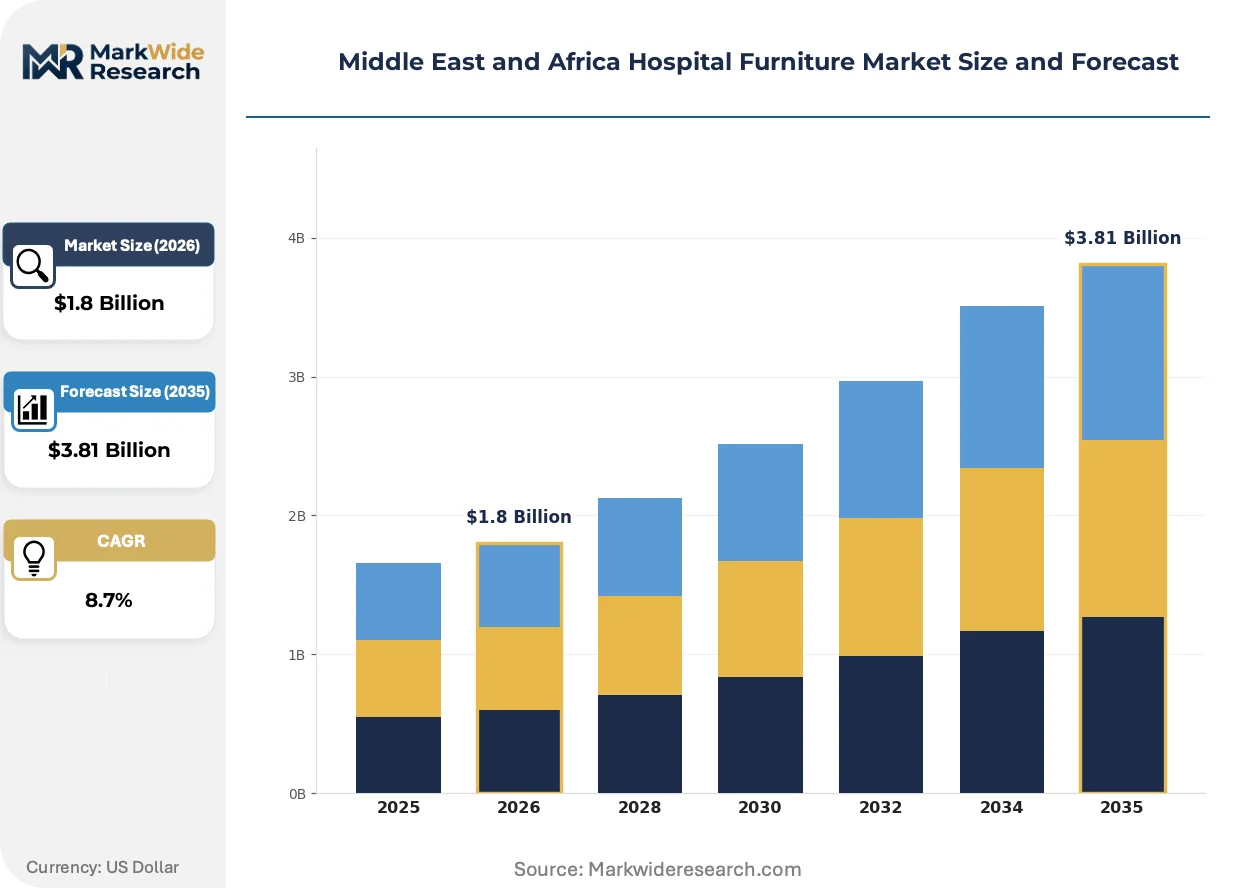
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Beds, Overbed Tables, Recliners, Wardrobes End User: Hospitals, Clinics, Long-term Care Facilities, Rehabilitation Centers Material: Wood, Metal, Plastic, Upholstery Form: Modular, Fixed, Portable, Adjustable |
| Companies Covered | OcurA, GPC Medical Ltd, Skytron, Chang Gung Medical Technology, Favero Health Projects Spa, Rolko Kohlgrüber GmbH, Hill-Rom Services, Stiegelmeyer GmbH & Co. KG, Renray, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hospital Furniture Market Shifts & Advancements
Hospital furniture specification is pivoting from discrete product procurement toward integrated clinical environment systems, with buyers prioritizing interoperability between beds, lighting booms, and patient monitoring infrastructure.
Antimicrobial polymer formulations with embedded copper-ion or silver-based biocidal properties are collapsing the distinction between surface materials and active infection-control interventions. Private hospital groups in Riyadh and Jeddah are specifying these surfaces for high-touch components in intensive care and oncology units. The technology is compressing traditional competitive positioning based on chemical coating durability alone.
SFDA's 2024 medical device registration framework mandates lifecycle traceability documentation that extends from raw material sourcing through end-of-service decommissioning. This elevates documentation burdens for imported furniture while creating competitive separation for suppliers with established Saudi technical service presence. Pediatric and psychiatric facility tenders are most affected, as ligature-resistant specifications require additional validation protocols.
Centralized procurement offices within Gulf Cooperation Council hospital chains are unbundling after-sales service from capital equipment purchase, awarding multi-year technical maintenance contracts to specialized service providers. This disintermediates traditional manufacturer-distributor relationships. The shift is most visible in Dubai and Abu Dhabi, where MOHAP-affiliated facilities now separate furniture acquisition from lifecycle management obligations.
Middle East and Africa Hospital Furniture Market Segmentation
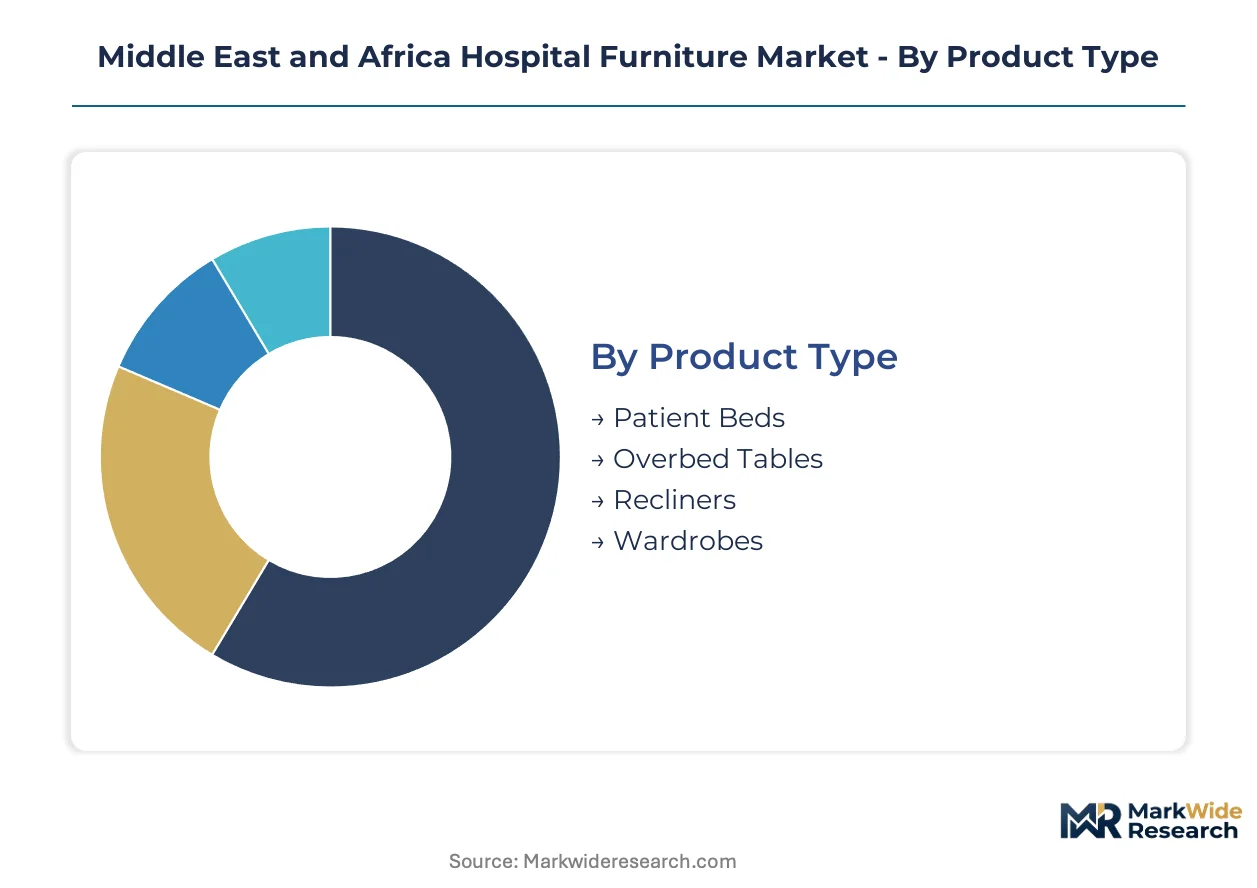
Hospital furniture procurement across the Middle East and Africa fragments across clinical setting requirements, material durability standards, and reconfiguration flexibility. Each segmentation dimension carries distinct after-sales service intensity, with motorized systems demanding multi-year technical maintenance contracts and fixed furniture requiring minimal lifecycle support.
Product Type:
After-sales service intensity varies sharply across product categories, with motorized beds generating recurring preventive maintenance revenue while static furniture relies on minimal warranty coverage.
- Patient Beds:Motorized configurations with integrated nurse-call systems and pressure-relief surfaces dominate capital procurement budgets. Saudi Arabia's SFDA registration requirements and South Africa's provincial health department tenders concentrate demand for ICU-compatible platforms with embedded electronics requiring specialized biomedical engineering support.
- Overbed Tables:Height-adjustable pneumatic or electric variants support patient feeding and clinical documentation workflows. Demand clusters in Abu Dhabi Health Services Company facilities pursuing Joint Commission International accreditation, where infection-control specifications favor antimicrobial polymer surfaces over traditional laminate.
- Recliners:Bariatric-capable patient seating with Trendelenburg positioning supports dialysis and oncology infusion centers. Cairo and Alexandria medical zones under Egypt's hospital privatization program specify premium adjustable configurations.
- Wardrobes:Modular storage systems with ligature-resistant hardware address psychiatric and pediatric facility requirements. Nigeria's federal teaching hospital renovation programs integrate these with decades-old ward infrastructure constraints.
Patient beds hold the largest share; momentum sits with overbed tables as infection-control specifications tighten.
End User:
Procurement authority concentrates differently across customer types, with Gulf hospital chains centralizing purchasing while African public facilities fragment decision-making across provincial hierarchies.
- Hospitals:Acute-care facilities in Riyadh, Jeddah, and Dubai drive specification for integrated clinical environment systems where beds interoperate with surgical booms and patient monitoring infrastructure. SFDA's lifecycle traceability documentation mandates elevate supplier qualification barriers.
- Clinics:Outpatient surgical and diagnostic centers prioritize portable and adjustable furniture for multi-purpose room utilization. Western Cape metropolitan districts in South Africa channel capital toward accredited facility renovations with space-optimized configurations.
- Long-term Care Facilities:Geriatric and palliative care settings in Morocco's medical city investments specify pressure-redistribution surfaces and fall-prevention bed rails. Preventive maintenance contracts extend capital replacement cycles.
- Rehabilitation Centers:Physical therapy and post-acute recovery facilities require bariatric platforms and standing-assist frames engineered for regional patient demographics. Demand concentrates in UAE's MOHAP-affiliated facilities separating furniture acquisition from lifecycle management.
Hospitals dominate procurement volume; rehabilitation centers are climbing the fastest as post-acute care networks expand.
Material:
Cost tier positioning separates premium antimicrobial formulations from commodity-grade alternatives, with copper-ion and silver-based biocidal polymers commanding specification premiums in high-touch intensive care applications.
- Metal:Powder-coated steel frames sustain the dominant material share due to durability requirements in high-occupancy wards. Gulf state hospital clusters face steel and aluminum input volatility affecting tender competitiveness.
- Plastic:Antimicrobial polymer components with embedded biocidal properties gain traction in pediatric and psychiatric settings where ligature resistance and weight reduction matter. Riyadh and Jeddah private hospital groups specify these for oncology units.
- Wood:Laminate-finish cabinetry and occasional-use seating appear in administrative zones and visitor areas. Domestic production capacity constraints concentrate supply in European and East Asian bases.
- Upholstery:Medical-grade fabrics meeting fire-retardant and infection-control specifications cover seating and mattress surfaces. Import dependency for antimicrobial polymers extends validation timelines for new market entrants.
Metal commands the largest installed base; plastic surfaces are gaining share fastest as active infection-control interventions displace passive chemical coatings.
Form:
Supply concentration for modular systems favors established suppliers with in-country technical infrastructure capable of supporting reconfiguration services and spare parts logistics.
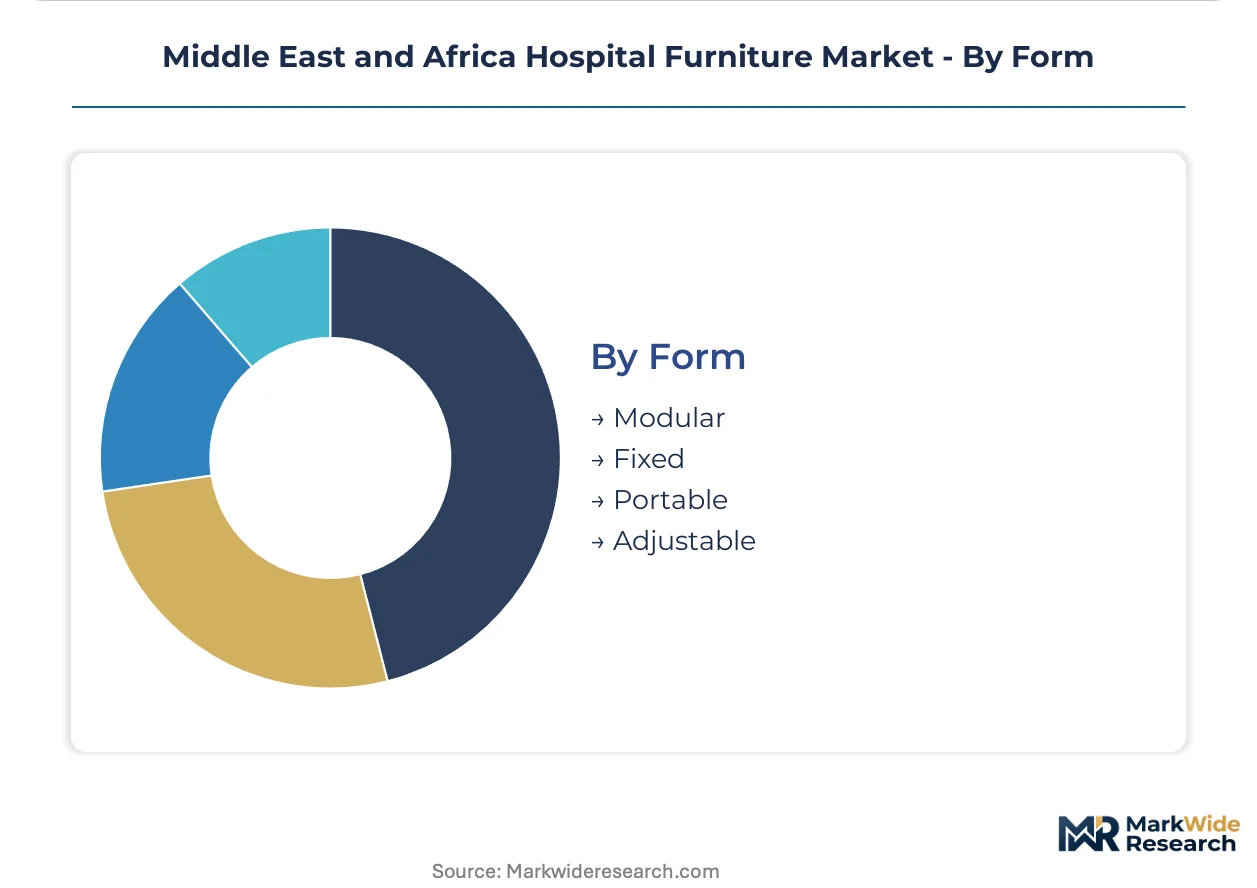
- Modular:Reconfigurable ward platforms with interchangeable panels and utility distribution systems address surge-capacity requirements from Abu Dhabi Health Services Company. These systems demand ongoing technical service networks for component replacement.
- Fixed:Traditional bolted-frame furniture persists in legacy infrastructure where floor-loading constraints and building utility interfaces limit upgrade feasibility. Nigeria's federal teaching hospitals face integration challenges with decades-old construction.
- Portable:Castor-mounted beds and equipment supports enable rapid room turnover and temporary expansion. Metropolitan healthcare districts in Gauteng prioritize flexibility for patient flow optimization.
- Adjustable:Electric and hydraulic height, backrest, and leg-rest positioning supports pressure injury prevention and clinical access. Bariatric-capable configurations engineered for Middle Eastern patient demographics address underserved specification tiers.
Fixed form retains the largest legacy installed base; modular systems show the steepest expansion trajectory as facilities reconfigure for surge capacity and specialized care zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Middle East and Africa. Gulf Cooperation Council states prioritize motorized beds with integrated electronics, while African public health systems concentrate procurement on durable metal-framed platforms for high-occupancy wards.
Saudi Arabia
SFDA medical device registration mandates lifecycle traceability documentation from raw material sourcing through decommissioning. Riyadh and Jeddah private hospital chains centralize procurement authority into single purchasing offices. These centralized buyers specify premium adjustable systems with embedded nurse-call integration for new medical city developments.
United Arab Emirates
MOHAP and Dubai Health Authority enforce Joint Commission International alignment requirements that filter supplier eligibility. Abu Dhabi Health Services Company drives surge-capacity specifications for modular ward reconfiguration. Dubai-based hospital clusters now unbundle after-sales service from capital equipment purchase, awarding separate technical maintenance contracts.
South Africa
Provincial health departments channel capital budgets toward accredited facility renovations in Gauteng and Western Cape metropolitan districts. The national health facility licensing framework mandates specific equipment standards that shape local procurement specifications. Cape Town and Johannesburg acute-care facilities extend capital replacement cycles through preventive maintenance contracts.
Egypt
The emerging hospital privatization program redirects demand toward premium adjustable systems in Cairo and Alexandria medical zones. Public-private partnership frameworks attract investment into specialized care infrastructure. Cairo-based procurement offices specify bariatric-capable platforms engineered for regional patient demographics.
Nigeria
Federal teaching hospital renovation programs drive demand for modular furniture compatible with decades-old building utilities. Lagos and Abuja procurement authorities face floor-loading constraints that limit upgrade feasibility. These legacy infrastructure challenges favor portable castor-mounted systems over fixed installations.
Middle East and Africa Hospital Furniture Market Competitive Landscape
Capability concentration sits with European specialists possessing SFDA registration infrastructure and in-country technical service networks; scale advantage sits with diversified healthcare equipment conglomerates with centralized Gulf state distribution. The vendor base separates into three strategic archetypes: premium-tier integrated system suppliers, mid-market modular specialists, and regional service-focused distributors. Consolidation pressure is accelerating through multi-year technical maintenance contract awards that disintermediate traditional manufacturer-distributor relationships. Geographic expansion into Cairo and Alexandria medical zones represents the dominant competitive move alongside portfolio diversification into antimicrobial polymer surfaces.
Within the European specialist tier, Hill-Rom Services and Stiegelmeyer GmbH & Co. KG exemplify capability concentration through established Gulf technical service presence. Hill-Rom Services occupies a position anchored by preventive maintenance contract penetration across hospital clusters. Stiegelmeyer GmbH & Co. KG represents specialized engineering for regional patient demographics. Skytron sits within the integrated systems tier, exemplifying surgical environment interoperability positioning. These three entities collectively illustrate how registration infrastructure and service network density separate sustainable competitors from transaction-focused suppliers.
| Leading Market Players |
|---|
| OcurA |
| GPC Medical Ltd |
| Skytron |
| Chang Gung Medical Technology |
| Favero Health Projects Spa |
| Rolko Kohlgrüber GmbH |
| Hill-Rom Services |
| Stiegelmeyer GmbH & Co. KG |
| Renray |
| Others |
Supply & Pricing Matrix
European manufacturing clusters around Stuttgart and Hamburg anchor powder-coated steel frame production for Gulf hospital procurement, with their capacity utilization rates directly transmitting into tender pricing power for motorized bed platforms. SFDA registration compliance costs and antimicrobial polymer input scarcity further amplify supplier leverage in premium specification tiers.
Pricing Analysis
Long-term technical maintenance contracts now dominate procurement structures across Abu Dhabi Health Services Company and Dubai Health Authority facilities, displacing bundled capital-plus-service packages. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-registered suppliers with in-country biomedical engineering networks from transaction-focused distributors. Cost compression in mid-market motorized beds is intensifying because Gulf hospital chains are consolidating purchasing authority into centralized offices. Price-sensitive public hospital tenders in Nigeria and Egypt favor fixed-frame platforms over adjustable systems, while private Riyadh and Jeddah medical cities demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Tariff exposure between European Union member states and Gulf Cooperation Council customs territories dominates landed cost variability for antimicrobial polymer components and medical-grade upholstery. Manufacturing concentration in Germany, Italy, and Poland feeds from specialty steel mills and copper-ion polymer compounders in Belgium and the Netherlands. Single-source vulnerability persists for embedded nurse-call system electronics sourced from East Asian semiconductor fabricators. Distribution runs through manufacturer-direct technical service networks in Saudi Arabia and the UAE, with regional distributors handling Nigerian and South African public sector tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Egypt's hospital privatization program and Morocco's medical city investments accelerate specification upgrades from fixed to adjustable platforms. Penetration tailwinds from modular ward reconfiguration requirements are compressing replacement timelines across Gulf Cooperation Council acute-care networks.
For Market Incumbents: Insulate recurring revenue streams by deepening preventive maintenance contract penetration before Gulf hospital chains complete procurement centralization. Lock in multi-year technical service agreements with SFDA-registered spare parts logistics. Capacity addition in Cairo and Alexandria medical zones captures Egypt's public-private partnership infrastructure buildout. For New Entrants and Emerging Players: Build out bariatric-capable platform specialization for Middle Eastern patient demographics, an underserved specification tier between standard intensive care and premium surgical configurations. Nigeria's federal teaching hospital renovation programs offer the most penetrable geography given legacy infrastructure constraints that favor portable castor-mounted systems over fixed installations. Partner with established regional distributors possessing provincial health department accreditation relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated clinical environment suppliers with surgical boom and lighting interoperability capabilities over discrete furniture manufacturers. Long-term viability across the analysis window rests on software-defined bed platforms with embedded patient monitoring integration. Acquisition targets should demonstrate established SFDA technical service infrastructure. The signal to watch is unbundling velocity of after-sales service from capital equipment purchase across Dubai and Abu Dhabi procurement offices.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Technical Service Infrastructure Buildout | Lifecycle traceability mandates elevate compliance barriers for imported furniture without Saudi-based biomedical engineering networks. |
| Antimicrobial Polymer Surface Integration | Copper-ion and silver-based biocidal formulations displace passive chemical coatings in Riyadh and Jeddah intensive care specifications. |
| Modular Ward Reconfiguration Partnership | Abu Dhabi Health Services Company surge-capacity requirements accelerate replacement of fixed-position furniture with interchangeable platforms. |
| Bariatric Platform Engineering Specialization | Cairo and Alexandria procurement offices specify configurations engineered for regional patient demographics in emerging privatization zones. |
| Preventive Maintenance Contract Unbundling | Dubai Health Authority and MOHAP-affiliated facilities now separate furniture acquisition from lifecycle management obligations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contracts, and SFDA medical device registration filings. Primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers across Riyadh, Dubai, Johannesburg, and Cairo were validated against customs records and provincial health department tender documentation. Bottom-up segment sizing triangulates against top-down healthcare infrastructure investment forecasts.
Forecast inputs include product type segmentation across motorized, fixed, and portable configurations; material tier differentiation between powder-coated steel and antimicrobial polymer surfaces; and end-user procurement authority concentration across Gulf centralized purchasing offices versus African provincial hierarchies. CAGRs were derived from installed base replacement timelines and new medical city development pipelines. Modeled variables capture SFDA registration compliance cost trajectories and steel input price volatility transmission.
Stress conditions across commodity price spikes, regulatory timeline extensions, and biomedical engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Physiotherapy Equipment Market