
 Global Non-PVC IV Bags Market | 2026-2036
Global Non-PVC IV Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-PVC IV Bags Market Foresight
Multi-source material procurement is consolidating around European and Asian polymer suppliers as manufacturers reduce PVC dependency. Baxter leverages captive film extrusion capacity to secure polyethylene supply chains for flexible IV bags. Fresenius Kabi anchors its position through integrated parenteral nutrition portfolios that bundle non-PVC containers with drug formulations. B. Braun Melsungen AG dominates German hospital contracting through direct distribution networks and DIN-standard compliance.
Non-PVC IV bags are intravenous fluid containers manufactured from polyethylene, polypropylene, or ethylene vinyl acetate films, typically heat-sealed under cleanroom conditions to eliminate plasticizer leaching during drug administration. These containers serve acute care settings where phthalate-free delivery protects patient populations from endocrine-disrupting compound exposure. Single chamber bags in polyethylene sustain the largest volume share due to compatibility with standard electrolyte solutions and established sterilization protocols. Double chamber bags represent the fastest-expanding product form as lyophilized drug reconstitution workflows expand in oncology and critical care. Hospitals command the dominant end-user position, though home healthcare providers are gaining share through ambulatory infusion programs.
FDA guidance on DEHP-free medical devices and the European MDR's heightened biocompatibility testing reshape product development timelines and certification costs for bag manufacturers. REACH restrictions on classified substances and EPA manufacturing emissions standards further elevate compliance burdens for polymer processors serving medical device markets. Stakeholders must monitor evolving pharmacopeial monographs and state-level hospital procurement mandates to anticipate specification shifts before tender cycles close.
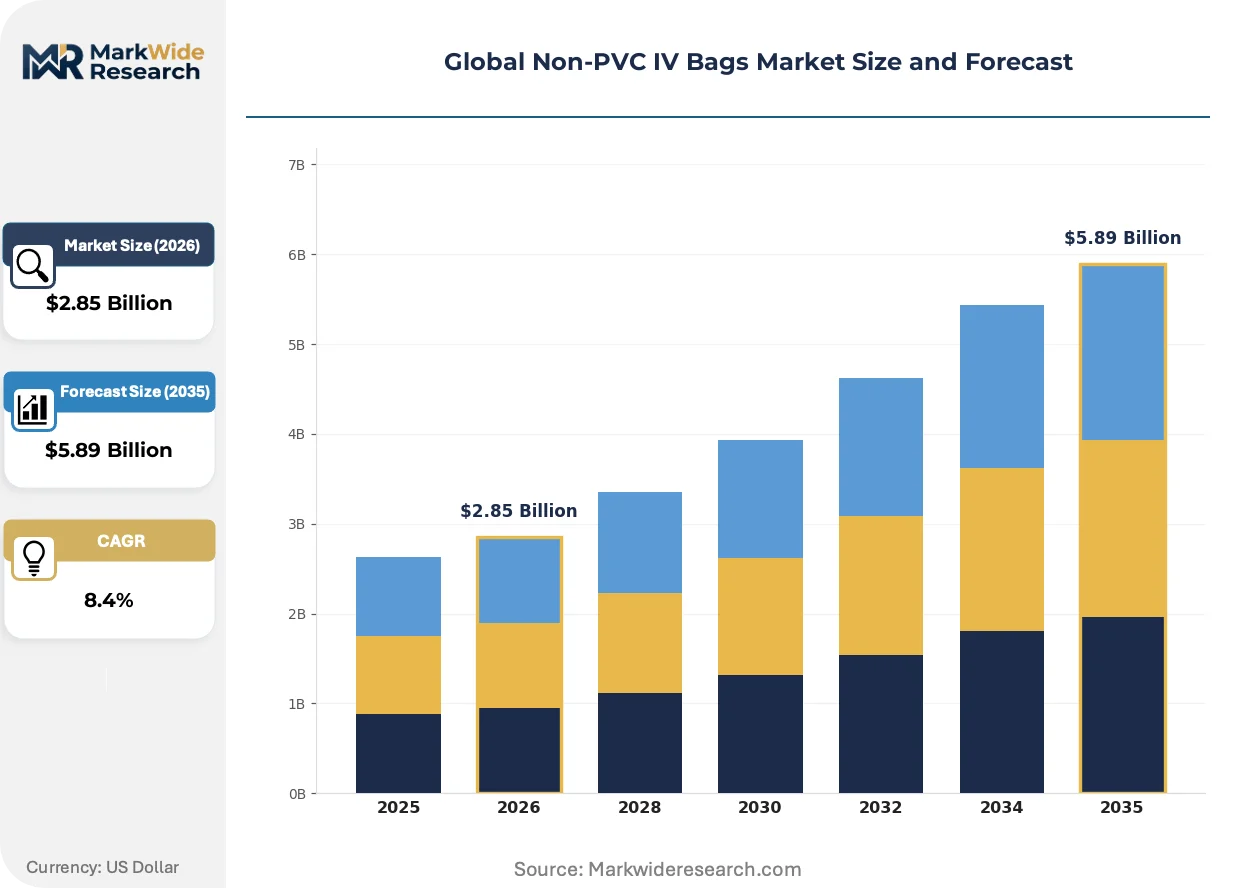
Market Dynamics
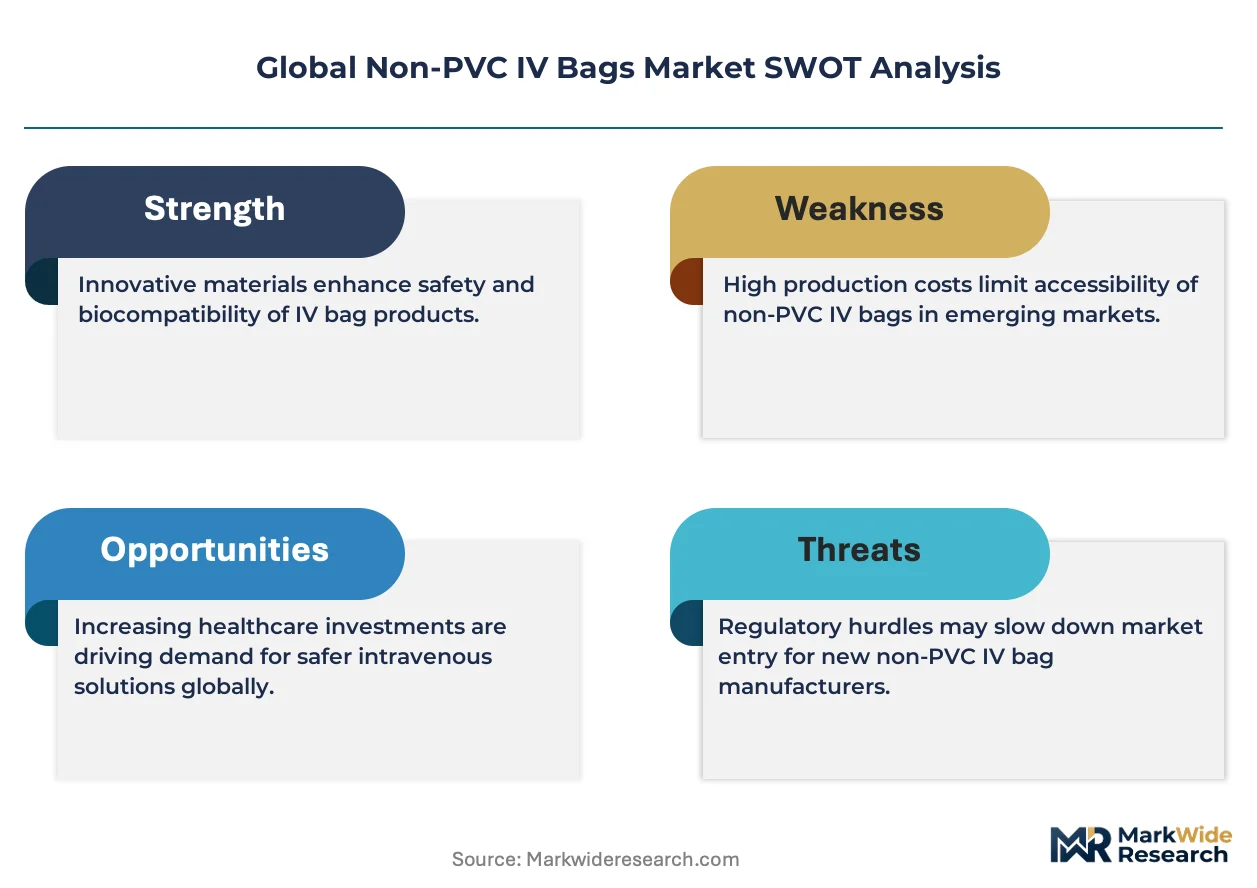
REACH restrictions on di-ethylhexyl phthalate and FDA guidance on DEHP-free medical devices are compressing polymer specification windows, forcing manufacturers to revalidate entire product lines around polyethylene and polypropylene films before tender cycles close.
Growth Catalysts
- EMA biocompatibility testing mandates:The European MDR's heightened scrutiny of leachable compounds accelerates hospital procurement of phthalate-free alternatives across Germany, France, and Italy.
- Lyophilized drug reconstitution workflows:Oncology and critical care units drive double-chamber bag volumes as clinicians seek closed-system preparation for high-value biologics.
- Home healthcare infusion programs:Ambulatory care expansion in North America and Western Europe creates pull-through demand for portable, non-PVC containers with extended stability profiles.
Market Restraints
- Ethylene vinyl acetate supply concentration:Medical-grade EVA film production clusters among three European polymer processors, exposing bag manufacturers to allocation risk during resin shortages.
- Cleanroom sterilization capex thresholds:Gamma and e-beam validation facilities require substantial upfront investment, elevating breakeven volumes for new market entrants.
- Multi-layer film technical limitations:Oxygen barrier performance in polyethylene containers remains inferior to PVC for certain parenteral nutrition formulations, restricting application scope.
Strategic Opportunities
- Japan's PMDA accelerated approval pathways:Streamlined device certification for materials with established US or EU dossiers reduces time-to-market for Western manufacturers targeting Asian hospital systems.
- Closed-system transfer device convergence:Integration of non-PVC bags with needle-free connectors and drug vial adapters creates bundled value propositions in hazardous drug handling protocols.
- India's CDSCO medical device rules:New risk-based classification and local manufacturing incentives open procurement channels for polyethylene IV containers in tier-one hospital chains.
Industry Challenges
- Polymer characterization expertise gaps:Analytical chemistry capabilities for extractables and leachables testing remain scarce among mid-tier contract manufacturers, extending validation timelines.
- Legacy filling line retrofit complexity:Existing PVC-formatted equipment requires mechanical and software modifications to handle stiffer polyethylene films without seal integrity compromise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-PVC IV Bags Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Ethylene Vinyl Acetate, Thermoplastic Elastomers, Biocompatible Copolymers Product Form: Flexible Bags, Rigid Containers, Composite Bags, Double Chamber Bags, Single Chamber Bags Application: Intravenous Therapy, Blood Transfusion, Parenteral Nutrition, Drug Delivery, Fluid Resuscitation End User: Hospitals, Ambulatory Surgical Centers, Dialysis Clinics, Home Healthcare Providers, Specialty Clinics |
| Companies Covered | Baxter, B. Braun Melsungen AG, Fresenius Kabi, JW Life Science, RENOLIT SE, Polycine GmbH, ANGIPLAST Pvt. Ltd., Technoflex SA, Shanghai Xin Gen Eco-Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-PVC IV Bags Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are compressing product development cycles while expanding the addressable application set for phthalate-free intravenous containers.
Multilayer coextrusion technology is expanding into high-barrier parenteral nutrition applications where oxygen sensitivity previously limited polyethylene adoption. German and Swiss hospital pharmacies are piloting these containers for lipid emulsion storage, with procurement committees evaluating total cost of ownership against PVC alternatives. The structural consequence is a compression of the premium pricing window for legacy ethylene vinyl acetate solutions as polyethylene performance gaps narrow.
REACH Annex XVII restrictions on classified substances are forcing polymer reformulation across European medical device supply chains. Manufacturers must resubmit technical dossiers for existing products, diverting R&D resources from next-generation development. Oncology drug compounders face the tightest compliance windows, with several German hospital tenders now specifying full material disclosure down to additive concentrations.
Hospital procurement committees are consolidating supplier relationships around integrated parenteral nutrition portfolios rather than standalone container sourcing. Group purchasing organizations in France and the Netherlands now bundle non-PVC bag contracts with amino acid and lipid emulsion supply agreements, displacing fragmented purchasing patterns. This concentration is most visible in academic medical centers with centralized pharmacy operations and formulary control authority.
Global Non-PVC IV Bags Market Segmentation
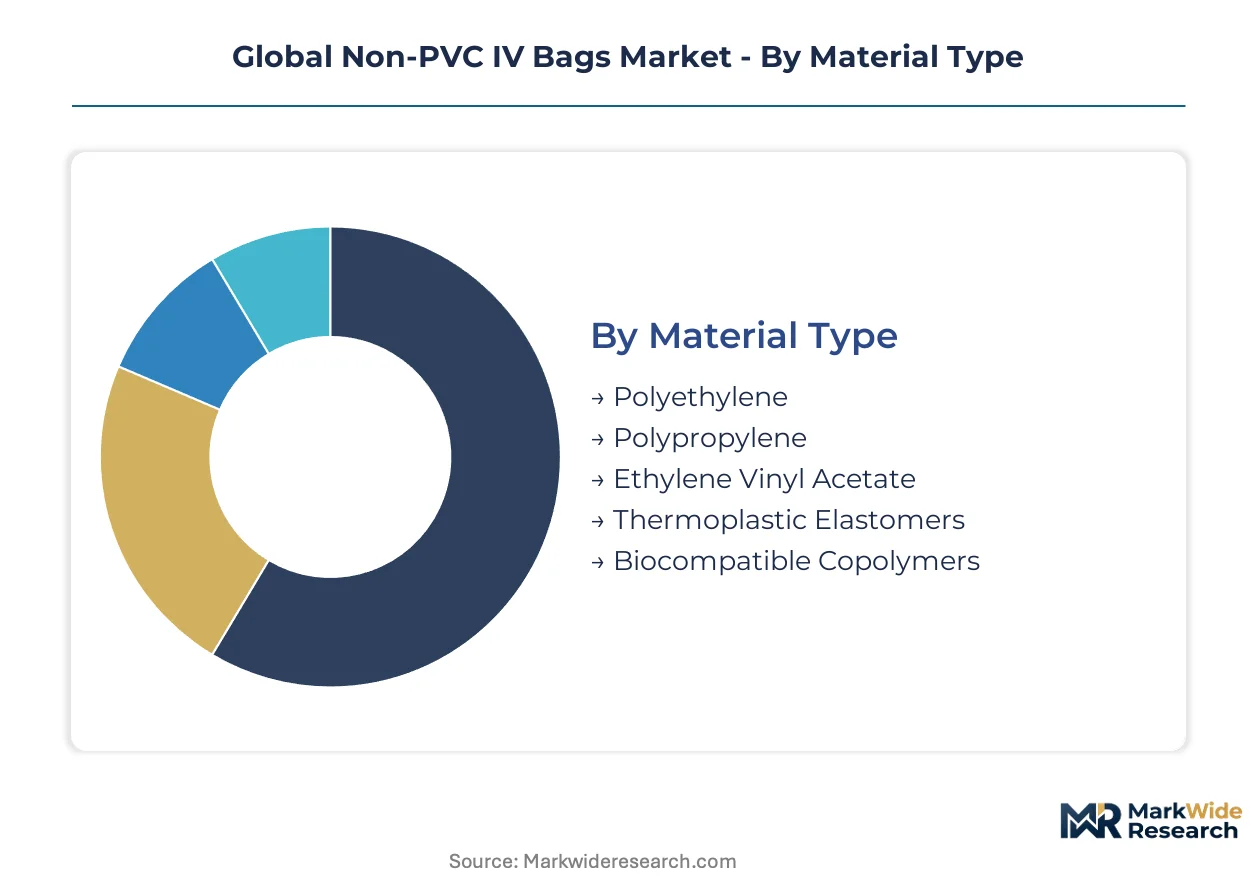
Material selection and product form specifications in non-PVC IV bags determine sterilization compatibility, barrier performance, and regulatory clearance pathways. Hospital procurement committees weight these attributes against total cost of ownership when consolidating supplier relationships across parenteral nutrition and oncology drug delivery workflows.
Material Type:
Polyethylene dominates volume production while ethylene vinyl acetate commands premium positioning in specialized applications.
- Polyethylene:Heat-sealed multilayer films provide standard moisture barriers for electrolyte solutions and crystalloid fluids. German hospital pharmacies specify polyethylene for high-throughput hydration therapy where cost efficiency outweighs oxygen sensitivity constraints.
- Ethylene Vinyl Acetate:Flexible copolymer films deliver superior clarity and resealability for lyophilized drug reconstitution. Oncology compounders in France and Switzerland prefer EVA for closed-system transfer device integration despite supply concentration risks among European polymer processors.
- Polypropylene:Stiffer polymer matrix suits rigid container formats with enhanced dimensional stability during automated filling.
- Thermoplastic Elastomers:Hybrid materials bridge flexibility and chemical resistance for specialty connector interfaces.
- Biocompatible Copolymers:Advanced formulations target pediatric and neonatal applications with the lowest extractables profiles.
Mature deployment sits with polyethylene. Newer deployment is concentrated in biocompatible copolymers.
Product Form:
Chamber configuration separates high-volume commodity supply from value-added drug preparation systems.
- Single Chamber Bags:Standard flexible containers accommodate saline, dextrose, and Ringer's lactate solutions with established gamma sterilization protocols. North American health systems procure single chamber polyethylene bags through group purchasing organizations for emergency department fluid resuscitation.
- Double Chamber Bags:Separated compartments enable closed-system mixing of lyophilized drugs with diluents prior to administration. Critical care units in academic medical centers specify double chamber designs for high-value biologics where contamination risk must approach zero.
- Flexible Bags:Conformable film construction suits ambulatory infusion pumps and patient mobility requirements.
- Rigid Containers:Blow-molded bottles provide structural integrity for automated compounding robotics.
- Composite Bags:Multilayer assemblies combine polymer films with foil or metallized barriers for extended stability.
Single chamber formats anchor procurement volume. Double chamber designs are climbing the fastest as oncology workflows expand.
Application:
Clinical setting determines barrier specifications, port configurations, and stability testing requirements.
- Intravenous Therapy:Electrolyte and hydration solutions represent the baseline application with the broadest material compatibility. General medical floors across US hospitals consume polyethylene single chamber bags for routine patient maintenance.
- Parenteral Nutrition:Lipid emulsions and amino acid solutions demand oxygen barriers and light protection that challenge standard polyethylene performance. German compounding pharmacies evaluate multilayer coextrusion advances against legacy EVA containers for total parenteral nutrition.
- Blood Transfusion:Specialized materials must meet hemocompatibility standards for red cell and platelet storage.
- Drug Delivery:Oncology and biologic formulations require documented extractables profiles and closed-system compatibility.
- Fluid Resuscitation:High-volume emergency applications prioritize supply security and rapid infusion mechanics.
Intravenous therapy sustains the largest procurement base. Parenteral nutrition presents the steepest specification escalation trajectory.
End User:
Facility type dictates order patterns, inventory turnover, and regulatory documentation depth.
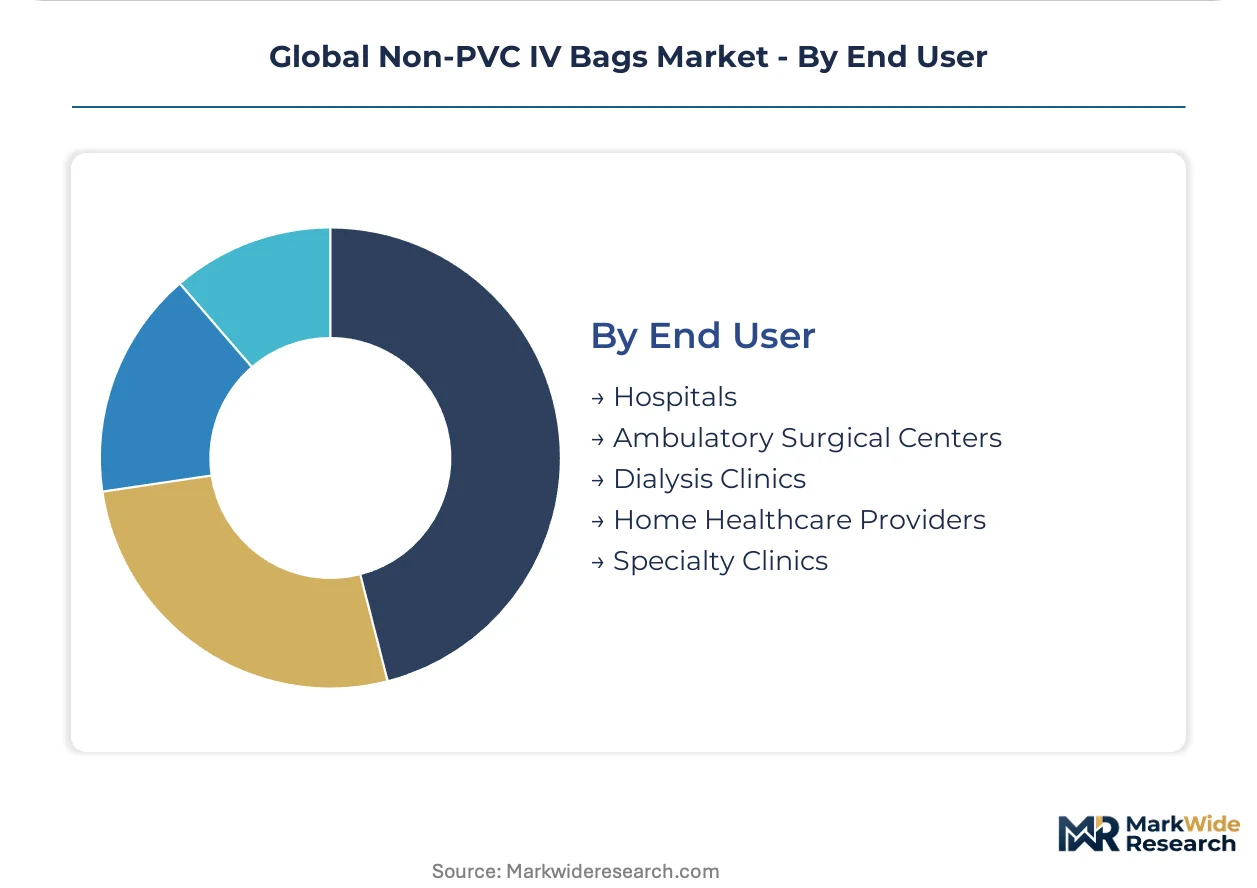
- Hospitals:Centralized pharmacy operations with formulary control drive consolidated non-PVC procurement across medical, surgical, and intensive care units. Academic medical centers in the Netherlands bundle container contracts with parenteral nutrition ingredient supply.
- Home Healthcare Providers:Ambulatory infusion programs require portable containers with extended stability for patient self-administration. Medicare reimbursement shifts in the United States accelerate home-based chemotherapy and antibiotic therapy.
- Ambulatory Surgical Centers:Same-day procedure volumes create demand for pre-filled, ready-to-hang configurations.
- Dialysis Clinics:Peritoneal dialysis solutions require specialized bag geometries and connector standards.
- Specialty Clinics:Oncology and infusion centers specify premium materials for hazardous drug handling protocols.
Hospitals anchor procurement concentration. Home healthcare providers are gaining share fastest through reimbursement-driven site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany command the largest national volume for phthalate-free intravenous containers. German hospital pharmacies specify polyethylene single chamber bags for hydration therapy while academic medical centers drive double chamber adoption for oncology workflows.
Germany
EMA biocompatibility testing mandates under the European MDR accelerate hospital tenders specifying full material disclosure. REACH Annex XVII restrictions on classified substances force polymer reformulation across medical device supply chains. The Melsungen industrial cluster anchors manufacturing leadership for flexible film extrusion serving central European hospital networks.
United States
Medicare reimbursement shifts toward home-based infusion programs expand ambulatory demand for portable non-PVC containers. FDA guidance on DEHP-free medical devices compresses specification windows for domestic manufacturers. The Greater Boston corridor concentrates oncology drug compounding expertise driving closed-system transfer device integration.
Japan
PMDA accelerated approval pathways for materials with established US or EU dossiers reduce time-to-market for Western manufacturers. METI industrial standards harmonization supports polyethylene adoption in hospital pharmacy operations. The Kansai region around Osaka hosts specialized polymer processing facilities serving domestic medical device assemblers.
India
CDSCO medical device rules introduce risk-based classification and local manufacturing incentives for polyethylene IV containers. Tier-one hospital chains in metropolitan areas expand procurement of phthalate-free alternatives for neonatal and pediatric populations. The Maharashtra pharmaceutical corridor concentrates contract manufacturing capabilities for export-oriented medical device production.
France
ANSM pharmacovigilance requirements elevate documentation depth for extractables and leachables testing in hospital tenders. Group purchasing organizations bundle non-PVC bag contracts with parenteral nutrition ingredient supply agreements. The Île-de-France region concentrates academic medical center procurement authority driving consolidated supplier relationships.
Global Non-PVC IV Bags Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit legacy filling lines for polyethylene film handling. The vendor base structures around three tiers: integrated parenteral nutrition suppliers with captive container production, specialized polymer film processors serving contract manufacturers, and regional fabricators focused on standard electrolyte solutions. Strategic archetypes include backward-integrated healthcare conglomerates and technology-focused film specialists. Portfolio diversification and geographic expansion represent the dominant competitive moves as firms seek to bundle container supply with drug formulation services.
Among German-based integrated suppliers, B. Braun Melsungen AG and Fresenius Kabi exemplify the backward-integrated archetype, anchoring positions through direct hospital distribution networks and DIN-standard compliance. Baxter represents the multinational healthcare conglomerate model with captive film extrusion capacity securing polyethylene supply chains. These three entities occupy positions that reflect divergent strategic emphases: regional manufacturing depth versus global supply chain control versus integrated drug-device portfolio bundling.
| Leading Market Players |
|---|
| Baxter |
| B. Braun Melsungen AG |
| Fresenius Kabi |
| JW Life Science |
| RENOLIT SE |
| Polycine GmbH |
| ANGIPLAST Pvt. Ltd. |
| Technoflex SA |
| Shanghai Xin Gen Eco-Technologies Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ethylene vinyl acetate resin price indices cascade through European polymer processors into three distinct pricing tiers for finished non-PVC IV bags. German hospital procurement committees leverage volume commitments to compress margins on standard polyethylene single-chamber formats while premium double-chamber designs retain pricing power through closed-system compatibility.
Pricing Analysis
High-volume single-chamber polyethylene bags trade at commodity margins while specialized double-chamber and multilayer formats capture premium returns. Price differentiation rests on EMA biocompatibility certification tier and oxygen barrier performance grade. Cost compression in standard hydration therapy segments is intensifying because REACH-driven reformulation expenses are concentrating among mid-tier contract manufacturers. Ambulatory home healthcare providers exhibit the greatest price sensitivity due to Medicare reimbursement constraints, whereas German academic medical centers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight cost volatility from Middle Eastern petrochemical feedstock sources amplifies working capital requirements for European film extrusion facilities. Medical-grade polymer production clusters in Germany, Belgium, and the Netherlands, with compounding operations drawing from Saudi Arabian ethylene and South Korean specialty additive suppliers. Single-source vulnerability concentrates in gamma sterilization capacity, where three European facilities handle the majority of hospital-contracted volumes. Distribution runs through direct manufacturer-to-hospital contracts in Germany and group purchasing organization channels in France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-PVC IV bags market sits in a materials-transition phase as multilayer polyethylene coextrusion displaces legacy ethylene vinyl acetate in parenteral nutrition applications. This technology substitution is compressing the premium pricing window for incumbent film formulations while opening specification opportunities for barrier-enhanced alternatives.
For Market Incumbents: Lock in German hospital contracting relationships through DIN-standard compliance and integrated parenteral nutrition portfolio bundling before REACH Annex XVII reformulation deadlines close. Prioritize captive polyethylene film extrusion capacity to secure supply chain control against resin allocation risks from European polymer processors. For New Entrants and Emerging Players: The mid-tier pricing gap between premium EVA oncology bags and economy polyethylene hydration formats offers entry positioning for barrier-enhanced polyethylene specialists. Target India's tier-one hospital chains under CDSCO medical device rules where local manufacturing incentives reduce import cost disadvantages, emphasizing pediatric and neonatal biocompatibility copolymer applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European contract manufacturers with validated cleanroom sterilization infrastructure but limited backward integration into film extrusion. Watch for EMA accelerated assessment designations for novel barrier materials as the inflection signal for portfolio repositioning toward next-generation parenteral nutrition containers.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Scale-Up | German manufacturers deploy barrier-enhanced polyethylene to capture parenteral nutrition volumes from legacy EVA suppliers. |
| Backward Integration into Film Extrusion | Captive polymer supply chains insulate against REACH-driven resin reformulation delays and allocation shortages. |
| Hospital System Partnership | Direct distribution networks in the Netherlands and France displace fragmented GPO purchasing through formulary bundling. |
| CE Marking Pathway Expansion | European MDR biocompatibility dossiers accelerate PMDA approvals for Japanese market entry by Western manufacturers. |
| Closed-System Transfer Device Convergence | Integration with needle-free connectors creates bundled value propositions in hazardous drug handling protocols. |
Research Methodology
Multi-period observation of hospital procurement tender awards, polymer processor capacity utilization, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and polymer film R&D leads. Secondary validation drew from EMA public assessment reports, FDA 510(k) clearances, REACH Annex XVII substance restrictions, and hospital procurement database aggregations. Bottom-up volume modeling across material type, product form, and end-user segments triangulated against top-down healthcare expenditure flows.
Input-output matrices mapped polyethylene resin throughput to finished bag volumes across German, US, and Japanese manufacturing footprints. Segmentation dimensions included material barrier tier, chamber configuration, clinical application intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated REACH substance restriction timelines and Medicare reimbursement shift trajectories for site-of-care migration.
Underlying measurement precision varies by segment; mature polyethylene single-chamber formats carry tighter precision than emerging biocompatible copolymer categories. Forecasts reflect assumptions about EMA MDR implementation pacing and polymer processor capacity allocation priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Medical Liners Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Compression Socks Market
Medical Supplies
Breast Shells Market