

Luer Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Luer Plug Market Insights
The EU MDR is decoupling legacy luer plug designs from European hospital tenders, forcing manufacturers to recertify under stricter biocompatibility and sterility assurance benchmarks. Becton, Dickinson and Company leverages its vertically controlled polymer compounding operations to fast-track compliant resin formulations. B. Braun SE anchors its European position through captive sterilization infrastructure that reduces third-party validation bottlenecks. ICU Medical competes by specializing in closed-system transfer devices that integrate locking luer plugs with needle-free connectors.
A luer plug is a small, tapered connector component that seals or terminates a luer fitting, typically molded from medical-grade polypropylene or polycarbonate to achieve dimensional tolerances of ISO 594-1 and ISO 594-2 standards for conical interoperability. Its primary purpose is to prevent fluid leakage, contamination ingress, and accidental disconnection in pressurized or gravity-fed medical fluid pathways. Locking luer plugs command margin premiums in oncology and hazardous drug compounding workflows where accidental separation carries severe safety consequences. Polypropylene dominates material selection due to its gamma sterilization compatibility and cost-efficient injection molding cycle times, though thermoplastic elastomer variants are gaining share in applications requiring repeated connect-disconnect durability.
The FDA enforces 21 CFR Part 820 quality system requirements for luer plug manufacturers, while the EU MDR and ISO 13485 collectively govern design history files, risk management documentation, and post-market surveillance obligations for devices sold into regulated jurisdictions. These frameworks elevate barriers for commodity producers lacking in-house regulatory affairs capabilities and certified cleanroom molding operations. Stakeholders must monitor evolving state-level pharmaceutical compounding regulations in the United States, where USP <797> and USP <800> revisions continue to redefine closed-system requirements for sterile preparation environments.
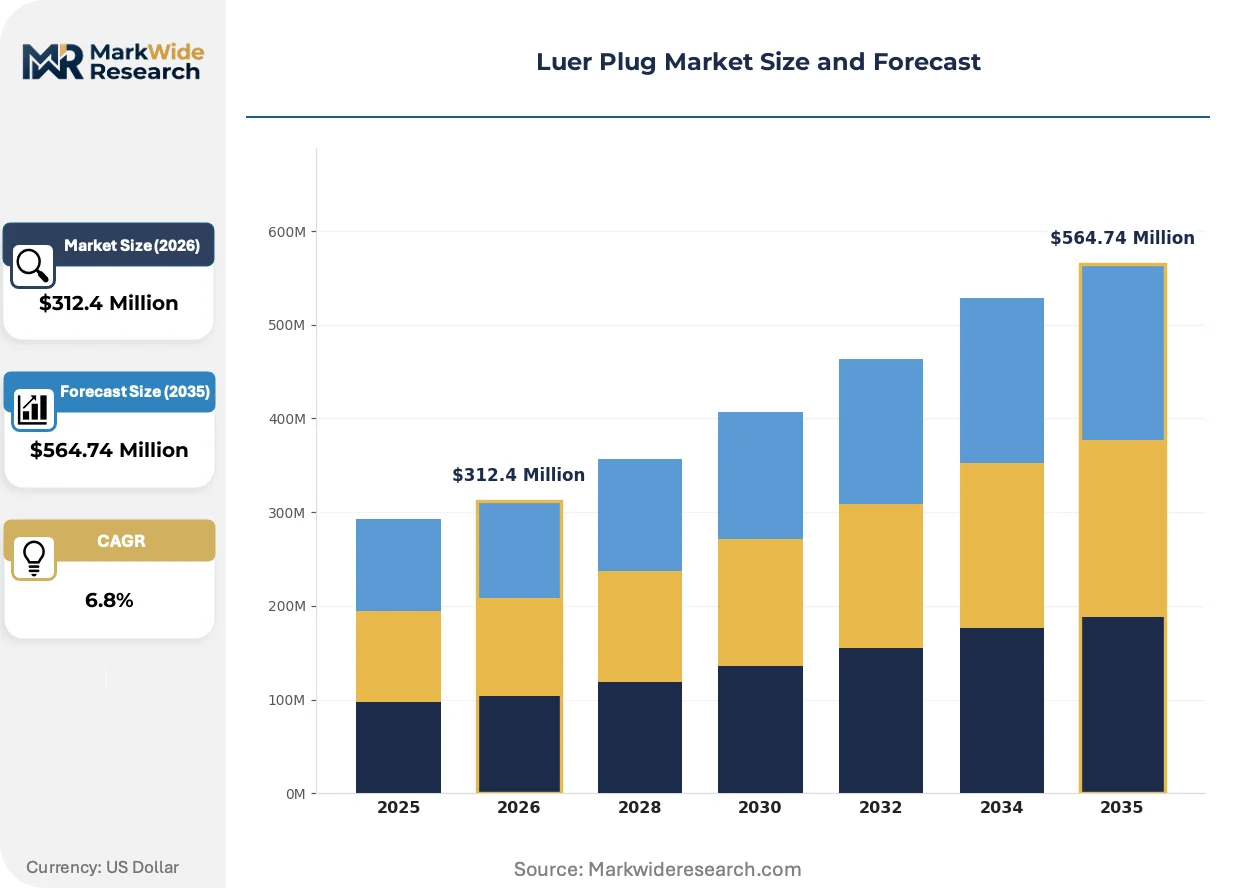
Market Dynamics
ISO 80369-7 small-bore connector standards are forcing manufacturers to redesign legacy luer geometries, compressing product lifecycles and redistributing tooling investments across medical device supply chains.
Growth Catalysts
- EU MDR recertification mandates:Stricter biocompatibility testing under the EU Medical Device Regulation is filtering out commodity producers, concentrating volume among certified molders with validated cleanroom operations.
- Ambulatory surgical center expansion:United States outpatient facility construction is accelerating disposable connector procurement for same-day procedures requiring sealed fluid pathways.
- Closed-system transfer device adoption:Oncology compounding workflows under USP 800 hazardous drug handling guidelines are integrating locking luer plugs into needle-free connector assemblies.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene homopolymer feedstock prices fluctuate with propylene monomer supply disruptions from Gulf Coast petrochemical complexes.
- Gamma sterilization capacity concentration:Contract irradiation services cluster in Belgium and Illinois, creating geographic bottlenecks for European and North American manufacturers without captive electron-beam facilities.
- ISO 594 dimensional tolerances:Legacy taper angle specifications limit design freedom for next-generation connectors seeking to differentiate on retention force or ergonomic handling.
Strategic Opportunities
- Thermoplastic elastomer durability segments:Repeated connect-disconnect applications in dialysis and infusion pump lines favor TPE formulations that outlast rigid polypropylene in cyclic loading.
- India pharmaceutical manufacturing:CDSCO-aligned medical device rules and domestic production-linked incentive schemes are attracting molding investments for export-oriented connector supply.
- Point-of-care diagnostic integration:Microfluidic cartridge designers are specifying miniaturized luer plugs for sample-to-answer platforms in decentralized testing environments.
Industry Challenges
- Design history file remediation:Legacy product portfolios lack contemporary risk management documentation required for EU MDR technical file submissions, forcing retrospective clinical evaluation reports.
- Multi-cavity mold validation timelines:FDA 21 CFR Part 820 process validation protocols extend lead times for high-volume production tools, compressing margin recovery windows before design obsolescence.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luer Plug Market Trends and Innovations
Material science advances and regulatory harmonization efforts are converging to redefine connector performance benchmarks, with durability and traceability emerging as the primary axes of product differentiation.
Two-shot molding with integrated thermoplastic elastomer seals is electrifying the high-cycle durability segment. Dialysis centers and infusion therapy providers are specifying these hybrid constructions for applications exceeding 50 connect-disconnect cycles per day. The technology is electrifying competitive positioning by collapsing the historical trade-off between gamma stability and mechanical resilience.
REACH SVHC substance restrictions are tightening phthalate and bisphenol-A scrutiny across European polymer supply chains. Compounders must reformulate color masterbatches and stabilizer packages to maintain CE marking eligibility. Oncology device manufacturers sourcing into Germany and France are accelerating migration to certified additive-free resin grades ahead of sunset date enforcement.
Consolidated procurement through group purchasing organizations is compressing supplier rosters for United States health systems. Integrated delivery networks in Texas and California are mandating lot-level serialization and electronic device history record access as table stakes for vendor qualification. Hospital materials management departments are unbundling after-sales technical support from unit pricing negotiations.
Luer Plug Market Segmentation
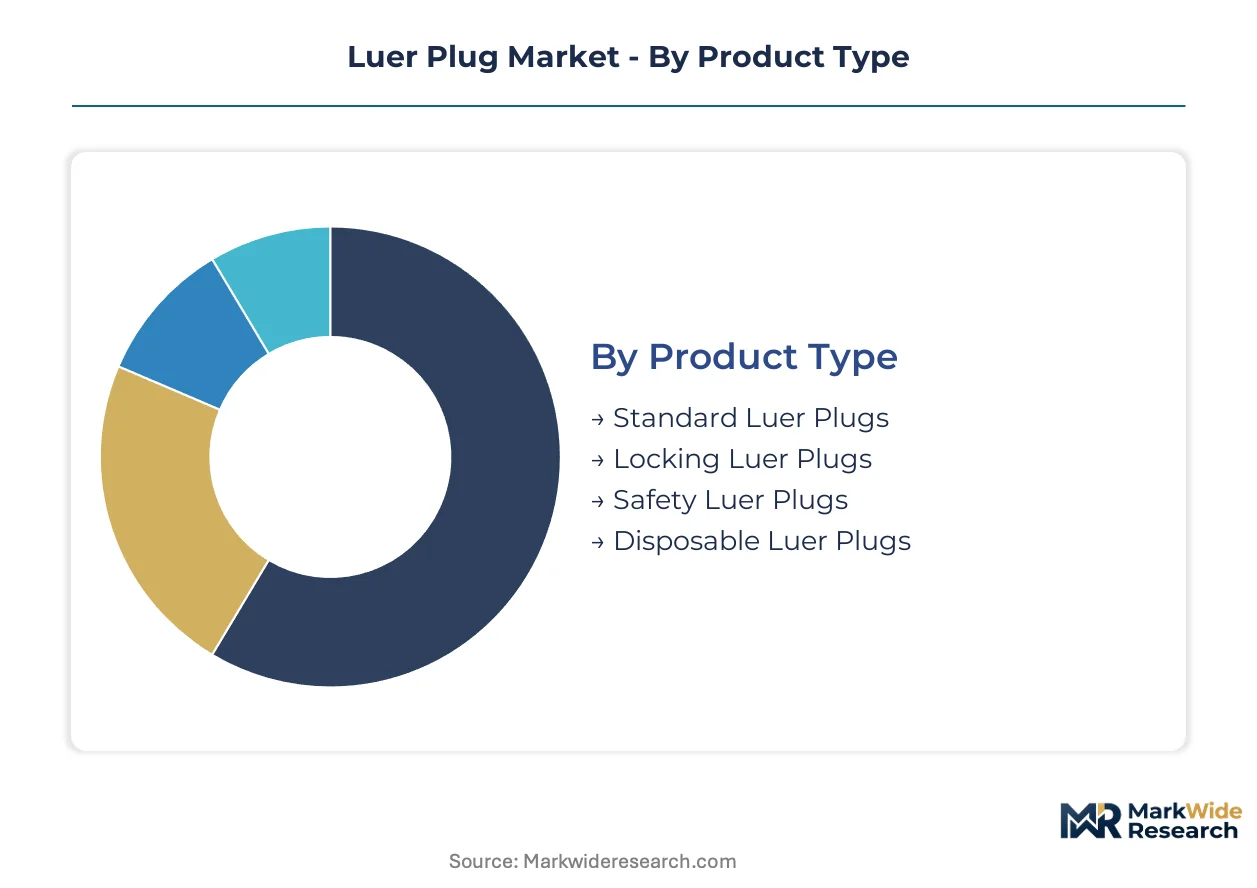
Luer plug segmentation reflects divergent capital requirements across product architectures, material processing technologies, and sterilization workflows. Manufacturers must align tooling investments with specific end-user compliance thresholds rather than pursuing undifferentiated scale.
Product Type:
Capital intensity varies sharply across luer plug architectures, with multi-cavity mold complexity and secondary assembly operations driving upfront investment thresholds.
- Locking Luer Plugs:Threaded retention mechanisms require precision-machined mold cores and automated torque-testing stations. Oncology compounding suites in United States hospital systems specify these for USP 800 hazardous drug containment, absorbing premium pricing for fail-safe retention.
- Standard Luer Plugs:Simple conical geometries minimize mold fabrication costs and accelerate FDA 510(k) clearance timelines. High-volume disposable procurement by Indian pharmaceutical exporters favors these for cost-sensitive sterile filling operations.
- Safety Luer Plugs:Integrated breakaway or shielding features demand specialized actuation testing equipment.
- Disposable Luer Plugs:Single-use designs prioritize gamma-stable resin selection over mechanical durability.
Most installed capacity flows through Standard Luer Plugs. Expansion is steepest in Locking Luer Plugs.
Material:
Polymer selection determines cleanroom infrastructure requirements, with hygroscopic resins demanding stricter environmental controls during processing.
- Polypropylene:Gamma sterilization compatibility and rapid injection molding cycle times dominate hospital disposable procurement. German device manufacturers specify medical-grade homopolymer grades for automated assembly lines serving European diagnostic laboratory networks.
- Thermoplastic Elastomers:Shore hardness tunability enables repeated connect-disconnect durability exceeding 50 cycles daily. Dialysis center operators in Japan specify TPE formulations for infusion pump lines where rigid polymers fatigue.
- Polycarbonate:Optical clarity suits fluid visibility applications in blood management sets.
- Polyethylene:Lower density reduces shipping costs for high-volume export orders.
- Silicone Rubber:Platinum-cured grades serve temperature-extreme autoclave sterilization protocols.
Polypropylene commands the broadest installed base. Thermoplastic Elastomers are climbing the fastest on durability premiums.
Application:
Regulatory scrutiny intensity varies by fluid pathway risk classification, with central line applications triggering enhanced biocompatibility documentation.
- Intravenous Therapy:Pressurized infusion sets demand dimensional stability under 300 mmHg operating pressures. United States ambulatory surgical centers specify locking variants for same-day discharge protocols where disconnection events carry litigation exposure.
- Drug Delivery:Closed-system transfer device integration requires validated extractables profiles for oncology therapeutic compatibility. French hospital pharmacies under ANSM oversight mandate silicone-free constructions for monoclonal antibody administration.
- Blood Sampling:Hemocompatibility testing adds developmental cost layers for vacuum tube applications.
- Medical Device Protection:Sterile barrier maintenance during shipping favors low-outgassing polymer selections.
- Fluid Management:Drainage and irrigation sets prioritize cost minimization over cyclic durability.
Intravenous Therapy absorbs the majority of molding capacity. Drug Delivery is gaining share fastest on hazardous handling mandates.
End User:
Procurement sophistication diverges sharply, with integrated delivery networks imposing electronic device history record requirements absent from research institution purchasing.
- Hospitals:Group purchasing organization consolidation in Texas and California health systems demands lot-level serialization and technical support bundling. FDA 21 CFR Part 820 quality system audits favor suppliers with validated cleanroom operations.
- Pharmaceutical Manufacturers:Aseptic filling line integration requires custom luer geometries validated for robotic handling speeds. CDSCO-registered Indian exporters specify disposable plugs for EU MDR-compliant sterile drug product export.
- Diagnostic Laboratories:High-throughput analyzer connectivity favors standardized ISO 594 geometries.
- Ambulatory Surgical Centers:Same-day procedure volume growth in United States outpatient construction drives disposable connector procurement.
- Research Institutions:Low-volume, high-mix purchasing tolerates longer lead times for specialized formulations.
Hospitals represent the dominant demand concentration. Pharmaceutical Manufacturers are expanding most quickly on production-linked incentive scheme investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The luer plug industry traces its commercial origins to mid-20th century European precision molding clusters, where Swiss and German medical device engineers standardized conical taper geometries for intravenous therapy systems.
United States
Ambulatory surgical center construction in Texas and Florida accelerates disposable connector procurement for same-day discharge protocols. The FDA enforces 21 CFR Part 820 quality system requirements that elevate barriers for offshore molders lacking validated cleanroom operations. Chicago-area contract irradiation facilities process gamma sterilization batches for domestic manufacturers serving hospital group purchasing organizations.
Germany
Baden-Württemberg medical device clusters anchor European production of high-precision luer geometries for diagnostic laboratory networks. REACH SVHC substance restrictions compel compounders to reformulate color masterbatches and stabilizer packages ahead of sunset date enforcement. Frankfurt Rhine-Main logistics hubs coordinate distribution to French and Benelux hospital systems under EU MDR compliance frameworks.
China
Yangtze River Delta molding centers supply cost-sensitive disposable plugs for Indian pharmaceutical exporters and Southeast Asian diagnostic manufacturers. NMPA medical device registration rules tighten biocompatibility documentation requirements for polymer-based connectors entering domestic hospital procurement channels. Suzhou industrial parks host electron-beam sterilization capacity serving regional device assemblers.
India
CDSCO-aligned medical device rules and production-linked incentive schemes attract molding investments for export-oriented connector supply to EU and Middle East markets. Maharashtra pharmaceutical manufacturing corridors integrate disposable luer plugs into aseptic filling lines for sterile drug product export. Gujarat specialty chemical clusters supply medical-grade polypropylene homopolymer grades to domestic device molders.
Japan
Metropolitan Tokyo dialysis center operators specify thermoplastic elastomer formulations for infusion pump lines where rigid polymers fatigue under repeated connect-disconnect cycles. PMDA quality management system ordinances align with ISO 13485 standards for design history file maintenance. Osaka-Kobe industrial zones concentrate precision mold fabrication for miniaturized connectors serving point-of-care diagnostic platforms.
Luer Plug Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the luer plug value chain. Vertically integrated polymer compounders and captive sterilization operators command procurement preference from hospital systems facing EU MDR recertification deadlines. The vendor base separates into three archetypes: diversified medical device conglomerates with captive molding capacity, specialized connector manufacturers with validated cleanroom operations, and regional commodity molders serving cost-sensitive export markets. Strategic moves concentrate on backward integration into resin compounding and geographic expansion into Indian pharmaceutical manufacturing corridors.
Among diversified medical device conglomerates, Becton, Dickinson and Company and B. Braun SE exemplify archetypes with vertically controlled supply chains. ICU Medical occupies a position within the specialized connector tier, representing manufacturers that integrate locking luer geometries into closed-system transfer devices. These three entities anchor competitive positioning across premium and mid-market procurement segments where regulatory compliance capabilities determine vendor qualification outcomes.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun SE |
| Baxter International |
| ICU Medical |
| Vygon |
| CODAN Companies |
| Amsino International |
| NP Medical |
| Merit Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer futures from Gulf Coast petrochemical complexes cascade through medical-grade polypropylene homopolymer pricing, compressing margins for commodity molders while concentrating pricing power among compounders with captive resin operations and validated cleanroom infrastructure serving EU MDR-compliant hospital systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates locking luer plugs with EU MDR technical files from standard ISO 594 geometries and unvalidated commodity disposables. Price differentiation hinges on certification grade and after-sales technical support bundling. Cost compression in economy tiers is intensifying because Indian pharmaceutical exporters are consolidating procurement volumes. Ambulatory surgical centers in Texas and Florida absorb premium pricing for fail-safe retention mechanisms, while research institutions remain most price-sensitive.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States hospital group purchasing organizations, while distributor networks serve mid-tier diagnostic laboratories and pharmaceutical manufacturers. Manufacturing concentrates in Germany, the United States, and China. Medical-grade polypropylene homopolymer, precision-machined mold cores, and gamma sterilization services constitute critical input dependencies. Single-source vulnerability in contract irradiation services clustering around Chicago and Belgium creates geographic bottlenecks for manufacturers lacking captive electron-beam capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification timelines and CDSCO production-linked incentive schemes create a geographic-arbitrage window, with regulatory compliance costs in European markets diverging sharply from subsidized capacity buildout in Indian pharmaceutical manufacturing corridors.
For Market Incumbents: Anchor market position through backward integration into medical-grade resin compounding and captive sterilization infrastructure that insulates against third-party validation bottlenecks. Defend against emerging specialized connector manufacturers by accelerating FDA 510(k) clearance timelines for next-generation locking geometries. Prioritize certification investment in ISO 80369-7 small-bore connector standards ahead of design obsolescence cycles. For New Entrants and Emerging Players: Launch via private-label partnerships with Indian pharmaceutical exporters seeking EU MDR-compliant disposable plugs for sterile drug product export. White-space concentration sits with thermoplastic elastomer formulations for dialysis center operators in Japan requiring cyclic durability exceeding 50 connect-disconnect cycles daily. Target point-of-care diagnostic integration through microfluidic cartridge designers specifying miniaturized luer geometries. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized connector manufacturers possessing validated cleanroom operations and existing FDA master files. Long-term viability over the next decade favors asset-light designers with regulatory affairs capabilities over capital-heavy commodity molders. Watch for inflection signals in state-level USP 797 and USP 800 compounding regulation revisions that redefine closed-system requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Submission | Recertification under stricter biocompatibility benchmarks filters out commodity competitors from European hospital tenders. |
| Backward Integration into Resin Compounding | Captive polymer formulation control accelerates compliant grade development ahead of REACH SVHC sunset enforcement. |
| Captive Gamma Sterilization Capacity | In-house irradiation infrastructure eliminates third-party validation bottlenecks concentrated in Belgium and Illinois. |
| Two-Shot Molding Technology Adoption | Hybrid thermoplastic elastomer construction collapses the trade-off between gamma stability and cyclic mechanical resilience. |
| CDSCO-Aligned Manufacturing Investment | Production-linked incentive schemes in Maharashtra and Gujarat attract molding capacity for export-oriented pharmaceutical supply. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at polymer compounders grounded qualitative assessment, cross-referenced against FDA 510(k) filings, EU MDR technical file databases, customs trade records, and hospital procurement contract disclosures. Bottom-up volume estimates from molding capacity utilization and top-down expenditure flows from health system capital equipment budgets were triangulated for consistency.
Segmented outputs across product architecture, material processing technology, sterilization workflow, application risk classification, and end-user procurement sophistication were generated across the analysis window. CAGRs were derived from installed base replacement cycles, ambulatory surgical center construction permits, and pharmaceutical manufacturing capacity expansion announcements. Forecast inputs incorporated REACH SVHC substance restriction timelines and USP 797/800 revision implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene monomer supply disruptions from Gulf Coast weather events or accelerated EU MDR enforcement actions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.