
 France Hospital Supplies Market | 2026-2036
France Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
France Hospital Supplies Market Foresight
EU MDR is recalibrating the cost-of-entry calculus for manufacturers seeking to place hospital supplies on the French market. Becton Dickinson and Company leverages its extensive notified body relationships to sustain regulatory throughput across its consumables portfolio. B Braun Melsungen AG anchors its competitive position through backward integration into sterilization packaging and surgical instrument manufacturing.
Hospital supplies encompass the full spectrum of disposable and reusable materials, instruments, and equipment used in patient diagnosis, treatment, and care delivery, including specifications such as biocompatibility testing under ISO 10993 for patient-contacting devices and ethylene oxide sterilization validation for critical-use items. Their primary purpose is to enable safe, effective clinical workflows while minimizing cross-contamination risk in acute and chronic care settings. Medical consumables command the largest revenue share due to their irreplaceable role in daily clinical operations, while sterilization products are gaining structural prominence as reprocessing standards tighten under MDR traceability mandates. Patient care devices occupy a mature margin pool where replacement cycles and connectivity upgrades drive purchasing decisions.
ANSM enforces pre-market vigilance and post-market surveillance for medical devices circulating in France, while the EU Green Deal's waste reduction targets are pressing manufacturers to redesign single-use product lines. CSRD disclosure requirements will soon compel hospital supply vendors to document supply chain emissions and circularity metrics. Stakeholders must monitor how France's regional health agencies consolidate procurement frameworks and whether MDR transition deadlines compress competitive timelines for smaller notified body clients.
Market Dynamics
Regional health agency consolidation in France is compressing supplier negotiation leverage while EU MDR traceability mandates force capital reallocation toward sterilization validation infrastructure.
Growth Catalysts
- Île-de-France acute care expansion:Hospital networks in this region are scaling single-use surgical kit procurement to support operating theater throughput targets. This concentrates demand volume for sterilized consumables.
- EU Green Deal waste reduction targets:Manufacturers redesigning single-use product lines to meet circularity metrics unlock preferential status in public procurement frameworks. ANSM vigilance protocols reward documented sustainability pathways.
- Grand Est hospital consolidation:Regional health agencies centralizing purchasing power create standardized tender specifications that favor suppliers with full-category coverage and notified body certification depth.
Market Restraints
- Ethylene oxide sterilization capacity constraints:Critical sterilization validation bottlenecks limit throughput for patient-contacting devices requiring ethylene oxide cycles under ISO 11135.
- Notified body scarcity:EU MDR transition has compressed the pool of designated conformity assessment bodies, extending certification timelines for reusable instrument reprocessing equipment.
- Reusable instrument substitution pressure:MDR traceability mandates and reprocessing cost escalation are accelerating hospital migration toward single-use alternatives, straining sterilization service provider revenue models.
Strategic Opportunities
- CSRD disclosure readiness:Early compliance with supply chain emissions documentation requirements positions vendors for preferential scoring in regional health agency ESG-weighted tenders.
- Connectivity-enabled patient care devices:Integration of telemetry and workflow analytics into replacement cycles for mature equipment categories creates service revenue attachment points.
- Biocompatibility testing consolidation:ISO 10993 laboratory capacity expansion in France reduces outsourcing dependency for manufacturers seeking accelerated market entry.
Industry Challenges
- MDR technical documentation skill scarcity:Qualified personnel for clinical evaluation report preparation and post-market surveillance file maintenance command premium compensation, compressing mid-tier manufacturer margins.
- Legacy sterilization infrastructure reconfiguration:Hospitals face capital intensity in retrofitting central sterile supply departments to meet revised EN ISO 17665 steam sterilization validation protocols.
- Supply chain emissions data integration:CSRD scope 3 disclosure requirements demand granular supplier engagement that many distributors lack systems to automate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Hospital Supplies Market |
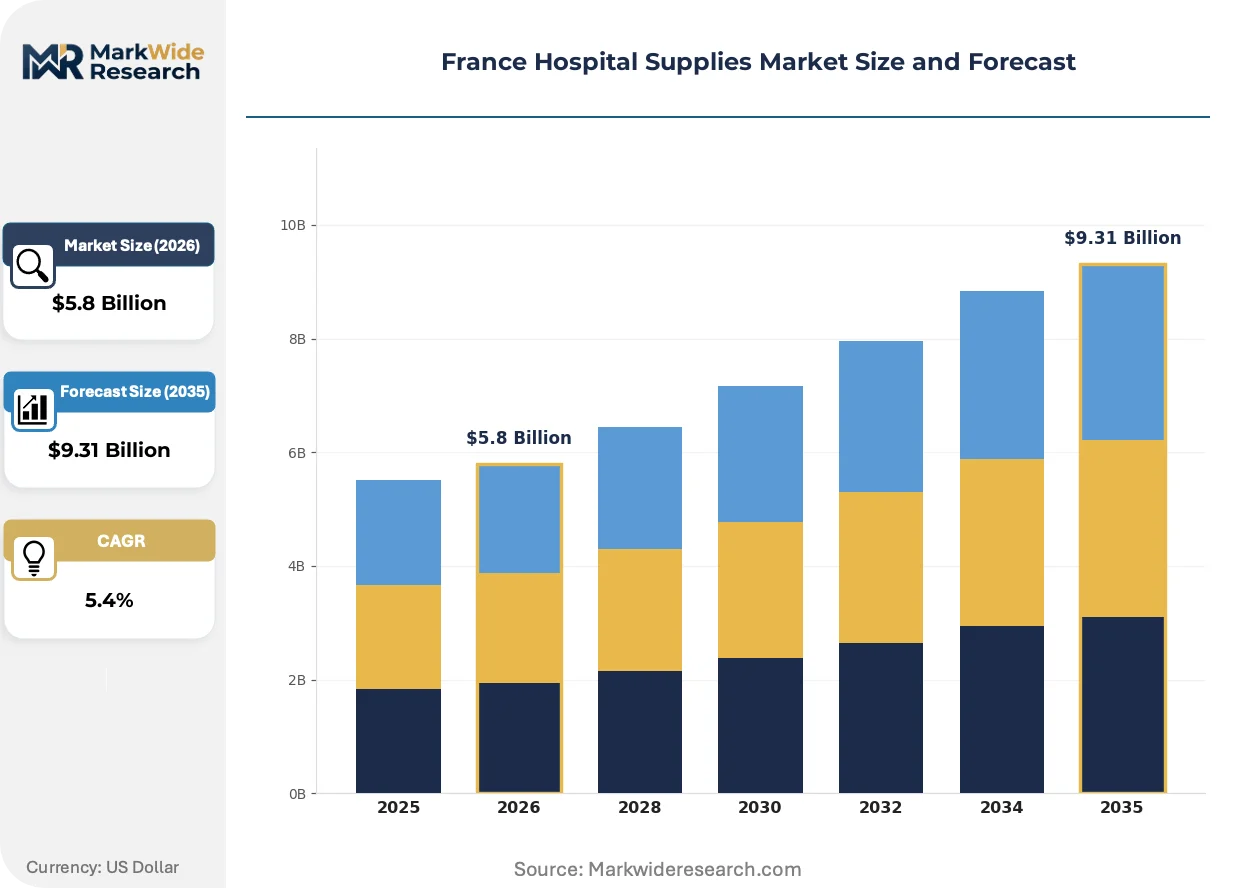
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Consumables, Surgical Instruments, Diagnostic Equipment, Patient Care Devices, Sterilization Products Application: Wound Management, Infection Control, Anesthesia, Critical Care, Rehabilitation End User: Public Healthcare Facilities, Private Clinics, Ambulatory Centers, Long-term Care Facilities, Emergency Services Distribution Channel: Direct Sales, Medical Distributors, E-Commerce Platforms, Group Purchasing Organizations, Pharmacies |
| Companies Covered | Cardinal Health Inc, Medtronic PLC, 3M Healthcare, Boston Scientific Corporation, B Braun Melsungen AG, GE Healthcare, Becton Dickinson and Company, Baxter International Inc, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Hospital Supplies Market Shifts & Advancements
Sterilization modality diversification and procurement centralization are restructuring how hospital supplies reach acute care facilities across French regions.
Plasma sterilization technology is expanding into cardiac catheterization laboratories and endoscopy suites where moisture-sensitive instrumentation dominates. Grand Est regional health agencies are piloting hydrogen peroxide vapor systems to reduce ethylene oxide dependency. This modality shift is expanding into broader surgical service lines as sterilization cycle time advantages compound with MDR traceability integration.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to reconstruct quality management systems around risk management file depth. ANSM post-market surveillance inspections now prioritize clinical follow-up study commitments over pre-market clinical data alone. Reusable instrument manufacturers face the steepest compliance recalibration as biological evaluation endpoints multiply under updated ISO 10993-1 guidance.
Regional health agency framework agreements are displacing hospital-level purchasing autonomy in France. Grand Est and Île-de-France ARS structures now mandate consolidated tender participation for categories exceeding defined volume thresholds. This aggregation is most visible in disposable surgical consumables where three-year framework commitments lock out non-compliant suppliers.
France Hospital Supplies Market Segmentation
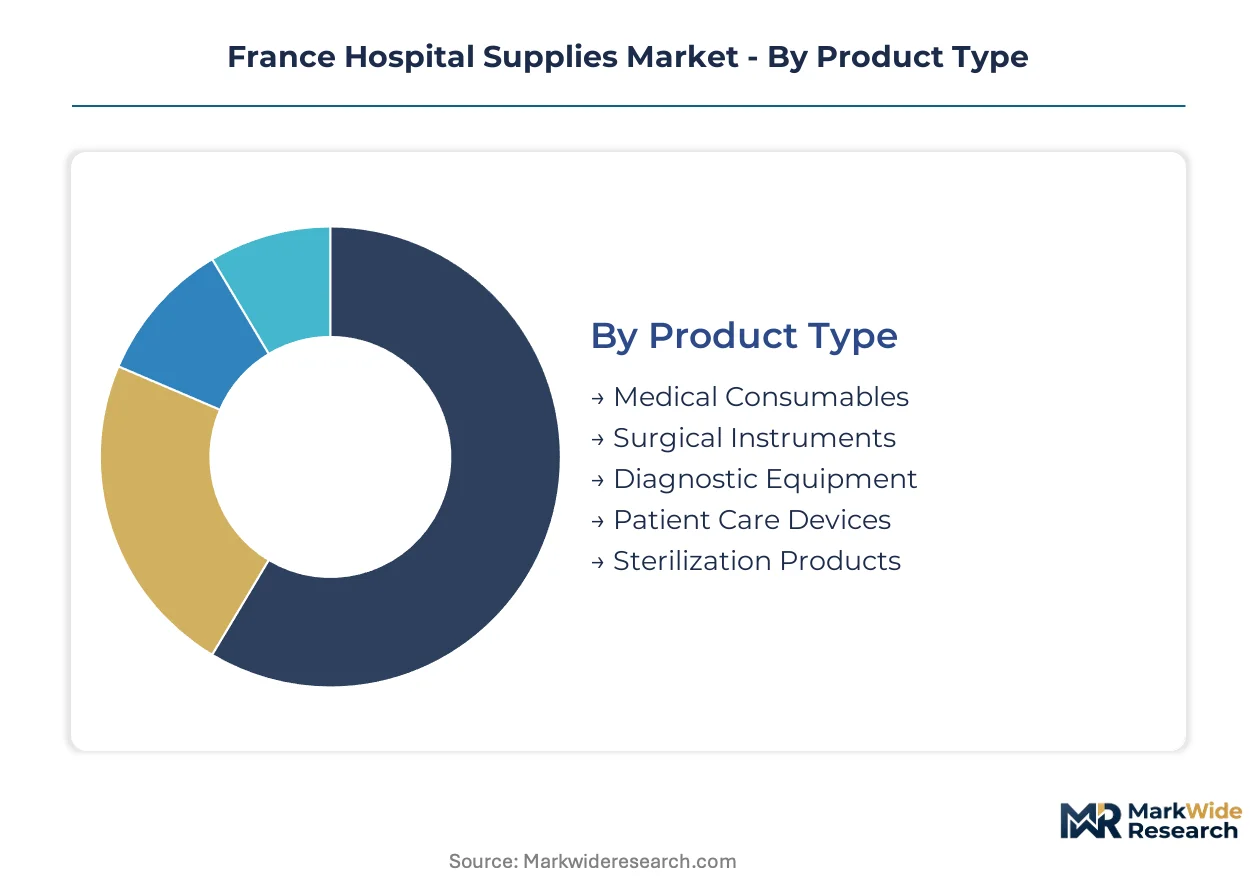
Hospital supply procurement in France stratifies across product risk classes and sterilization requirements that determine ANSM notification pathways. Segmentation reveals where EU MDR technical documentation burdens concentrate and which channels bypass centralized regional health agency frameworks.
Product Type:
EU MDR Class IIa and IIb certification demands vary sharply across this category, with patient-contacting devices requiring ISO 10993 biological evaluation and sterilization validation under ISO 11135 or ISO 17665.
- Medical Consumables:Single-use syringes, catheters, and infusion sets dominate procurement volumes in Île-de-France acute care networks. Grand Est regional health agencies consolidate tenders for three-year framework commitments, compressing supplier margins while locking in ethylene oxide sterilization capacity.
- Sterilization Products:Hydrogen peroxide vapor and plasma sterilization systems are displacing ethylene oxide in cardiac catheterization laboratories across Grand Est. ANSM post-market surveillance now prioritizes sterilization cycle validation documentation over pre-market clinical data alone.
- Surgical Instruments:Reusable instrument manufacturers face biological evaluation endpoint multiplication under updated ISO 10993-1 guidance.
- Diagnostic Equipment:Imaging consumables and point-of-care test kits require Class IIa technical documentation under EU MDR Article 10.
- Patient Care Devices:Telemetry-enabled monitors and infusion pumps occupy mature replacement cycles driven by connectivity upgrades.
Leading the category by volume: Medical Consumables. Growing fastest: Sterilization Products.
Application:
Cost tier stratification separates high-volume disposable categories from capital-intensive equipment segments with extended amortization schedules.
- Infection Control:Hand hygiene compliance monitoring and antimicrobial surface coatings command premium pricing in Île-de-France academic medical centers. EU Green Deal circularity metrics now weight public procurement scoring for single-use isolation gown alternatives.
- Critical Care:Ventilator circuits, hemodynamic monitoring kits, and dialysis consumables concentrate demand in Parisian tertiary referral networks. MDR traceability mandates force lot-level serialization investments that smaller distributors cannot absorb.
- Wound Management:Advanced dressing portfolios require biocompatibility testing under ISO 10993-5 cytotoxicity protocols.
- Anesthesia:Laryngeal mask airways and breathing circuit assemblies face ethylene oxide sterilization capacity bottlenecks.
- Rehabilitation:Mobility aids and pressure injury prevention surfaces fall outside high-risk device classifications.
Highest procurement value: Critical Care. Steepest expansion trajectory: Infection Control.
End User:
Customer type determines contract structure, with public facilities bound by regional health agency framework agreements and private operators retaining direct negotiation autonomy.
- Public Healthcare Facilities:Academic medical centers and general hospitals in Île-de-France operate under ARS-consolidated tenders exceeding defined volume thresholds. CSRD disclosure requirements will soon mandate supply chain emissions documentation from all framework participants.
- Ambulatory Centers:Outpatient surgical clinics in Grand Est bypass centralized procurement for specialized single-use kits. MDR transition deadlines compress competitive timelines for smaller notified body clients serving this fragmented channel.
- Private Clinics:Independent facilities retain purchasing autonomy outside regional health agency aggregation.
- Long-term Care Facilities:Pressure injury prevention and enteral feeding consumables dominate category spend.
- Emergency Services:Pre-hospital trauma kits and airway management devices require rapid replenishment logistics.
Dominant contract volume: Public Healthcare Facilities. Gaining share fastest: Ambulatory Centers.
Distribution Channel:
Supply concentration in notified body-certified manufacturers shapes channel viability, with direct relationships reserved for suppliers possessing technical documentation depth.
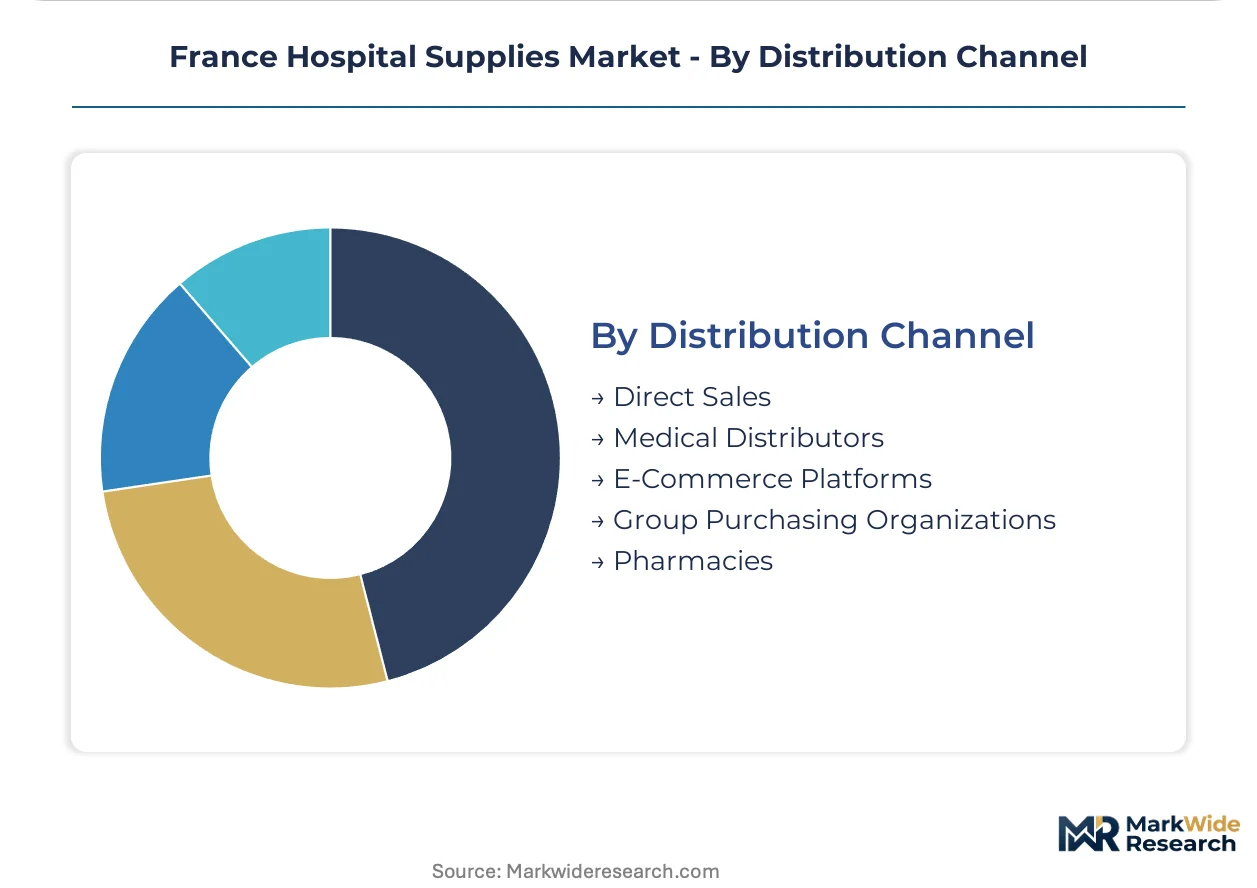
- Group Purchasing Organizations:Regional health agency framework agreements function as GPO structures aggregating Grand Est and Île-de-France demand. Three-year commitments lock out non-compliant suppliers lacking full-category coverage and certification depth.
- Medical Distributors:Independent distributors face margin compression as CSRD scope 3 disclosure requirements demand granular supplier engagement their systems cannot automate.
- Direct Sales:Capital equipment and connectivity-enabled devices bypass distributor markups through manufacturer field service organizations.
- E-Commerce Platforms:Low-risk consumables migrate to digital procurement portals with standardized specifications.
- Pharmacies:Retail channels capture limited hospital supply categories with over-the-counter regulatory status.
Controlling procurement volume: Group Purchasing Organizations. Expanding most quickly: Medical Distributors with CSRD compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's status as a designated innovation cluster under France's Territoires d'Industrie program concentrates hospital supply demand in Parisian acute care networks. Regional health agency consolidation redirects procurement flows toward framework-compliant vendors.
Île-de-France
Academic medical centers in Paris and surrounding departments scale single-use surgical kit procurement to meet operating theater throughput targets. ANSM post-market surveillance inspections prioritize clinical follow-up study commitments in this cluster. Grand Paris hospital networks centralize sterilization validation documentation for ethylene oxide-dependent consumables.
Grand Est
Regional health agency framework agreements in Strasbourg and Reims aggregate purchasing power for disposable surgical consumables. EU MDR traceability mandates force lot-level serialization investments that smaller distributors serving this region cannot absorb. Mulhouse-based sterilization service providers face revenue pressure from single-use substitution trends.
Auvergne-Rhône-Alpes
Lyon's biomedical research corridor drives demand for biocompatibility testing capacity under ISO 10993 protocols. CSRD disclosure requirements press manufacturers in this region to document supply chain emissions for ESG-weighted tenders. Grenoble's medical device cluster concentrates hydrogen peroxide vapor sterilization pilot programs.
Hauts-de-France
Lille's university hospital center anchors procurement volume for critical care consumables including ventilator circuits and hemodynamic monitoring kits. EU Green Deal circularity metrics weight public procurement scoring for single-use isolation gown alternatives. Calais distribution hubs face margin compression from CSRD scope 3 disclosure automation demands.
Provence-Alpes-Côte d'Azur
Marseille's territorial hospital group consolidates tenders for patient care devices with connectivity upgrade requirements. ANSM enforces pre-market vigilance protocols for medical devices circulating through this Mediterranean corridor. Nice's private clinic networks retain direct negotiation autonomy outside regional health agency aggregation.
France Hospital Supplies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's hospital supply procurement tiers. The vendor base stratifies around notified body certification depth and full-category coverage capabilities. Three archetypes dominate: integrated multinationals with captive sterilization infrastructure, regional distributors with CSRD compliance automation, and niche specialists in plasma sterilization modalities. Competitive intensity centers on M&A-driven portfolio diversification and backward integration into sterilization packaging manufacturing.
Among Germany-based diversified manufacturers, B Braun Melsungen AG and Becton Dickinson and Company occupy positions defined by notified body relationship depth and sterilization validation infrastructure. Boston Scientific Corporation exemplifies the connectivity-enabled device archetype. These three anchors represent how certification throughput and technical documentation capabilities determine framework agreement eligibility in consolidated regional health agency tenders.
| Leading Market Players |
|---|
| Cardinal Health Inc |
| Medtronic PLC |
| 3M Healthcare |
| Boston Scientific Corporation |
| B Braun Melsungen AG |
| GE Healthcare |
| Becton Dickinson and Company |
| Baxter International Inc |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Plasma sterilization technology adoption in French cardiac catheterization laboratories is simultaneously reducing ethylene oxide dependency and redistributing procurement premiums toward suppliers with validated alternative modalities. This production-method transition compresses margins for legacy sterilization service providers while concentrating pricing power among manufacturers with captive hydrogen peroxide vapor infrastructure.
Pricing Analysis
Short lead-time premiums for ethylene oxide-sterilized consumables command pricing advantages as capacity constraints tighten validation queues. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and lot-level traceability compliance. Pricing pressure stems from regional health agency framework aggregation in Grand Est and Île-de-France, where standardized tender specifications compress supplier margins. Ambulatory surgical centers exhibit highest price sensitivity due to fragmented purchasing volumes, while academic medical centers prioritize compliance over cost.
Supply Chain Analysis
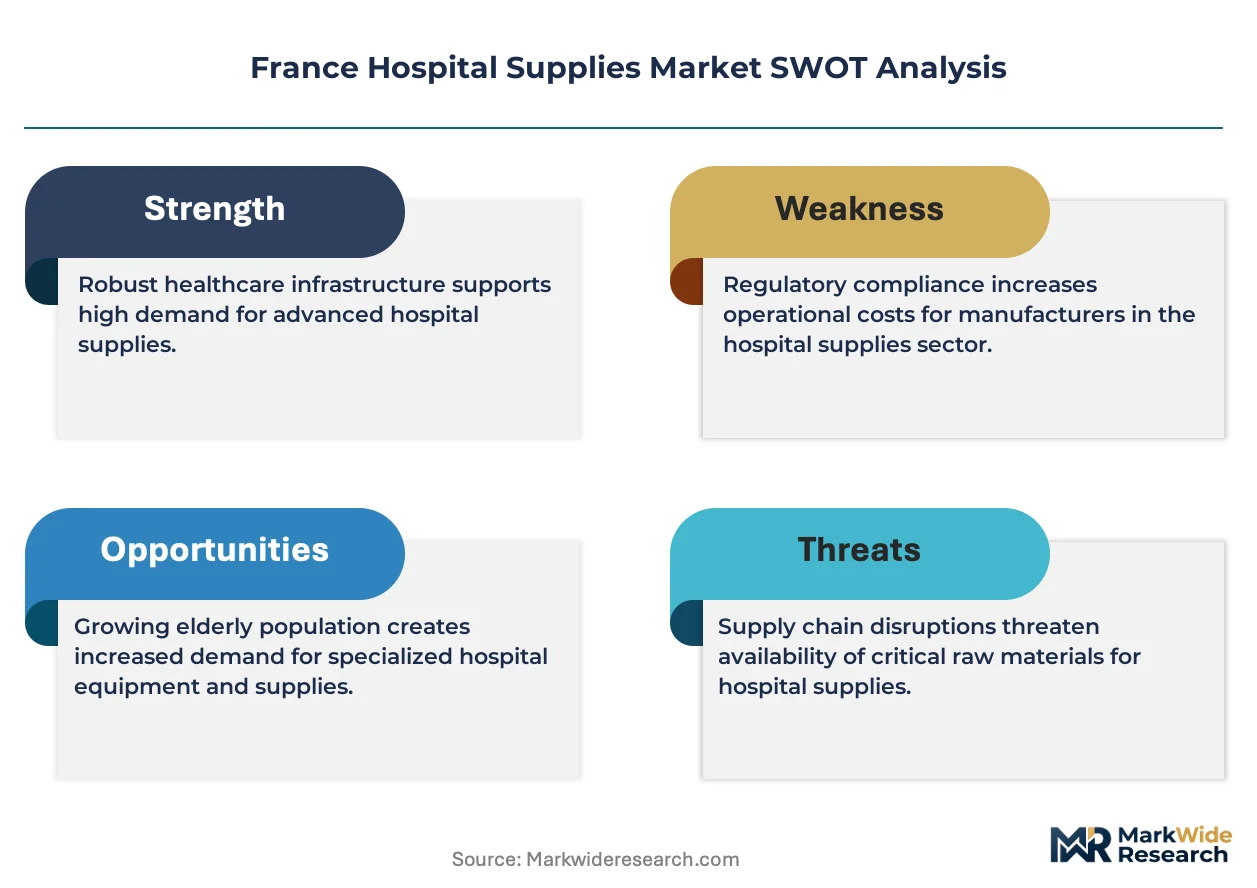
Workforce availability constraints in German and Swiss sterilization packaging manufacturing are extending component lead times for French hospital supply distributors. Geographic supply concentration centers on Germany, Switzerland, and Belgium for sterilization validation services and ethylene oxide sterilants. Raw material dependencies include medical-grade polymers, sterilization indicator chemicals, and biocompatibility testing reagents. Single-source vulnerability runs through consolidated ethylene oxide sterilization capacity. Distribution runs through regional health agency framework agreements that bypass traditional distributor markups for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's hospital supply market sits in a sterilization-modality transition phase, with hydrogen peroxide vapor and plasma systems displacing legacy ethylene oxide infrastructure. This technology replacement cycle favors suppliers with validated alternative modalities and technical documentation depth.
For Market Incumbents: Hedge against single-use substitution pressure by backward integration into sterilization packaging manufacturing and captive plasma sterilization capacity. Regional health agency consolidation threatens distributor margins; defend position through full-category coverage and notified body certification depth that locks in three-year framework commitments. ANSM post-market surveillance intensification demands clinical evaluation report capabilities that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: The premium-to-economy pricing gap in biocompatibility testing services offers white-space entry for ISO 10993 laboratory capacity expansion in Lyon and Grenoble clusters. Target ambulatory surgical centers in Grand Est bypassing centralized procurement for specialized single-use kits. CSRD disclosure automation capabilities create differentiation for distributor entrants serving fragmented private clinic networks. For Investors and Strategic Acquirers: Exit pathways concentrate in sterilization modality specialists and CSRD compliance infrastructure providers with regional health agency framework eligibility. Long-term viability favors targets with hydrogen peroxide vapor validation depth and backward integration into sterilization packaging. Watch ANSM enforcement intensity against legacy ethylene oxide infrastructure as inflection indicator for single-use substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks regional health agency framework eligibility in France. |
| Hospital System Partnership | Grand Est ARS three-year commitments lock out non-compliant sterilization suppliers. |
| Backward Integration | Captive sterilization packaging manufacturing defends margins against distributor compression. |
| Software Companion Development | Telemetry-enabled patient care devices create service revenue attachment in Île-de-France. |
| Reimbursement Strategy | ANSM vigilance protocols reward documented sustainability pathways in public procurement. |
Research Methodology
Multi-period observation of sterilization capacity utilization, regional health agency tender awards, and ANSM enforcement patterns anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and sterilization service provider operations directors. Secondary validation drew from ANSM medical device vigilance databases, EU MDR notified body designation records, hospital procurement framework agreements, and CSRD disclosure filings. Bottom-up demand modeling across acute care networks triangulated against top-down macroeconomic indicators.
Input-output matrix analysis structured the forecasting framework across product risk class, sterilization modality, end-user facility type, and regional health agency jurisdiction. CAGRs were derived from sterilization capacity expansion trajectories and framework agreement volume commitments over the projection horizon. Industry-specific inputs included ethylene oxide sterilization queue lengths, ISO 10993 laboratory capacity utilization, and MDR technical documentation filing rates.
Inputs from ANSM vigilance reports and regional health agency procurement disclosures were available through the study window; gaps in private clinic purchasing data and ambulatory center inventory levels introduce uncertainty bands around distributor channel forecasts. Material deviation in MDR transition deadlines, ethylene oxide capacity regulatory restrictions, or CSRD enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Compression Socks Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Pressure Monitoring Extension Tubing Sets Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Surgical Tapes Market