
 Specimen Retrieval Bags Market | 2026-2036
Specimen Retrieval Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Specimen Retrieval Bags Market Analytics
Single-use sterility assurance and tensile-strength specification upgrades is redrawing competitive boundaries in specimen retrieval bags. Johnson & Johnson leverages its laparoscopic portfolio breadth to bundle retrieval systems with trocar platforms. Stryker anchors its position through dedicated minimally invasive surgery divisions with direct hospital contracting. Medtronic competes by integrating retrieval bags into broader surgical workflow solutions.
Specimen retrieval bags are sterile, flexible containment devices manufactured from polyethylene, polypropylene, or nylon films, typically 0.05–0.15 mm thick, designed to isolate excised tissue during minimally invasive procedures and prevent port-site seeding or contamination. Open-ended bag configurations dominate hospital procurement due to lower per-unit cost and compatibility with diverse specimen sizes, while closed bag variants command premium positioning in robotic surgery applications where pneumoperitoneum maintenance is critical. Polyethylene remains the volume material of choice for disposable lines, though nylon-reinforced constructions gain share in reusable sterilization cycles where puncture resistance determines replacement frequency.
FDA 510(k) premarket notification requirements govern U.S. commercialization, while EU MDR technical documentation and biocompatibility testing under ISO 10993 constrain European market access timelines. Japan's PMDA enforces Japan Industrial Standards for film integrity and sterility validation, adding a third compliance layer for multinational suppliers. Stakeholders must monitor evolving sterilization validation protocols and single-use plastic restriction proposals across multiple jurisdictions to anticipate specification shifts and sourcing requirements.
Market Dynamics
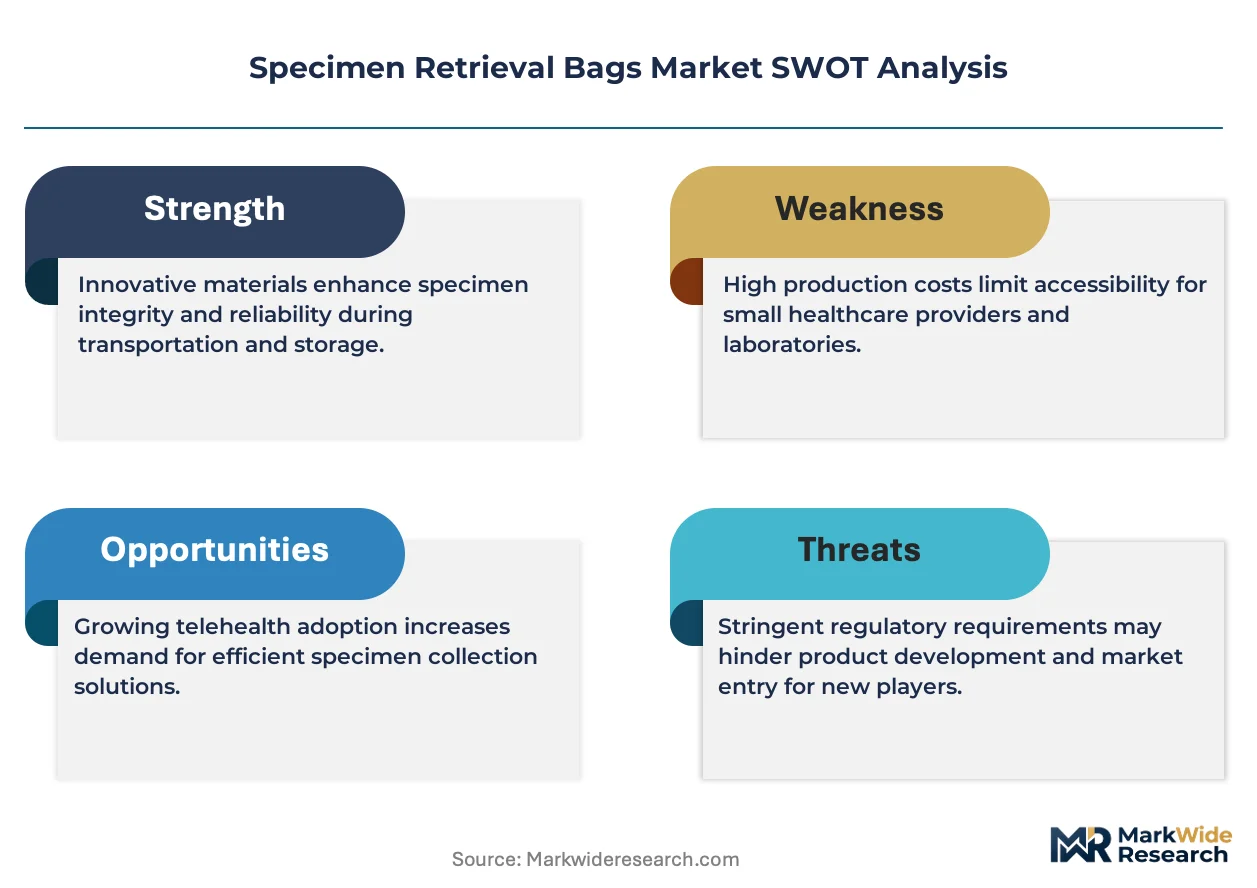
Single-use sterility mandates and EU MDR technical documentation requirements are compressing product development cycles while elevating compliance costs for specimen retrieval bag manufacturers. These dual pressures favor suppliers with established regulatory infrastructure and dedicated quality management systems.
Growth Catalysts
- Laparoscopic procedure volume expansion:Tertiary hospitals in the United States, Germany, and Japan are scaling minimally invasive surgery suites, creating sustained demand for sterile containment systems compatible with robotic and manual retrieval instruments.
- FDA 510(k) pathway efficiency:Predicate device referencing accelerates clearance timelines for polyethylene and nylon film configurations, enabling faster commercialization of next-generation puncture-resistant designs.
- Nylon-reinforced material innovation:Reusable sterilization cycles in cost-conscious hospital systems are driving specification upgrades that extend bag lifespan and reduce per-procedure waste volume.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, squeezing margin predictability for disposable product lines.
- Single-use plastic restriction proposals:Legislative initiatives in France and Germany threaten standard polyethylene bag specifications, forcing premature R&D redirection toward biodegradable alternatives.
- Closed-system technical limitations:Pneumoperitoneum maintenance requirements in robotic surgery constrain bag design flexibility, limiting addressable procedure types for premium configurations.
Strategic Opportunities
- Underpenetrated outpatient surgical centers:Ambulatory facilities in India and Brazil lack dedicated minimally invasive surgery infrastructure, presenting first-mover expansion potential for bundled retrieval systems.
- EU MDR conformity consultancy services:Technical documentation complexity creates adjacent revenue streams for manufacturers willing to guide smaller competitors through biocompatibility testing under ISO 10993.
- RFID-enabled traceability integration:Convergence of sterile packaging with inventory management systems allows premium positioning in university hospital networks pursuing supply chain digitization.
Industry Challenges
- Sterilization validation expertise scarcity:Ethylene oxide and gamma irradiation protocol optimization requires specialized quality engineering talent that competes with broader medical device sectors.
- EU MDR notified body capacity constraints:Certification backlog delays product launches by 12-18 months, forcing working capital absorption during extended approval windows.
- Legacy hospital procurement system integration:ERP compatibility with automated dispensing units requires custom middleware development, fragmenting sales cycles across integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specimen Retrieval Bags Market |
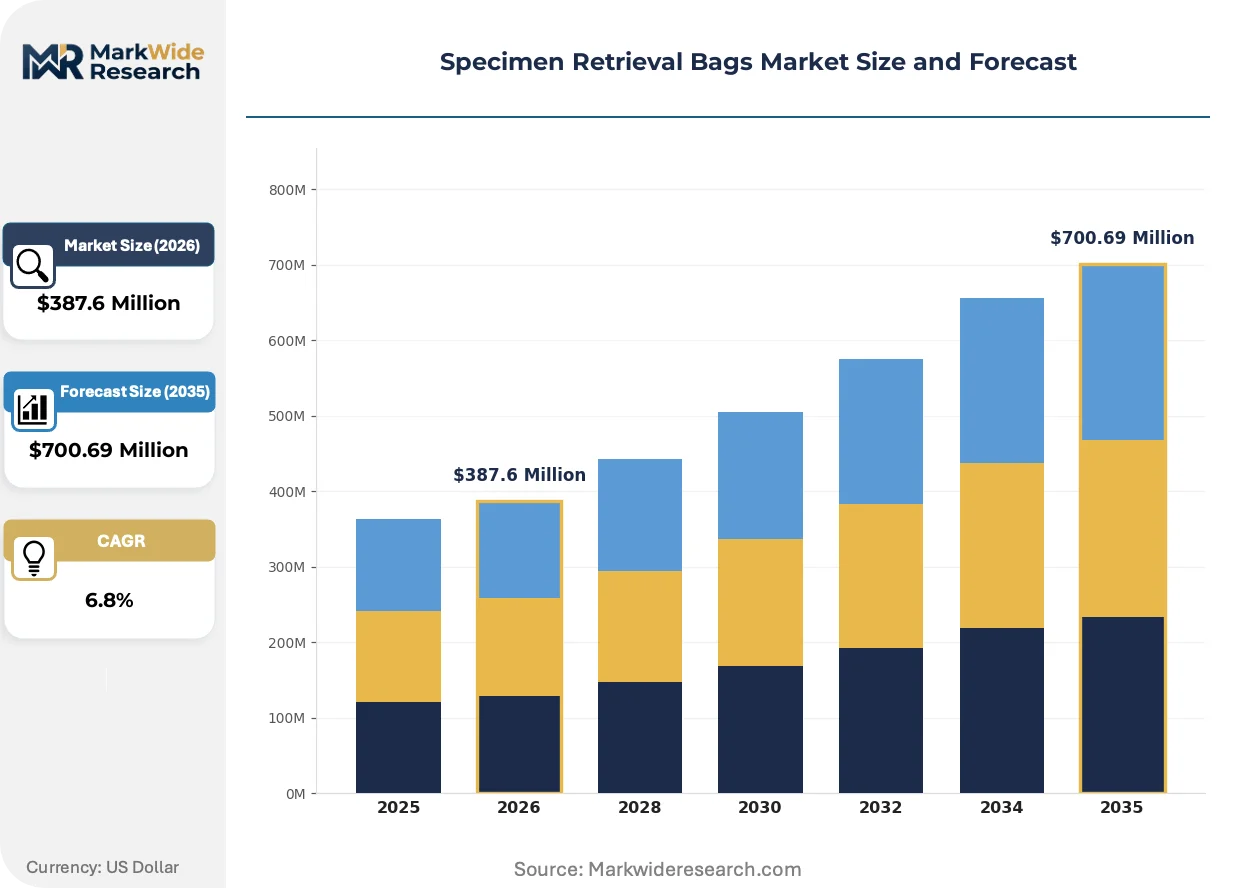
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Ended Bags, Closed Bags, Disposable Bags, Reusable Bags Material: Polyethylene, Polypropylene, Nylon, Vinyl Application: Minimally Invasive Surgery, Robotic Surgery, Laparoscopic Surgery, Endoscopic Procedures End User: Hospitals, Ambulatory Surgery Centers, Clinics, Diagnostic Labs |
| Companies Covered | Applied Medical Resources, B. Braun, Johnson & Johnson, Purple Surgical, Stryker, Medtronic, CONMED Corporation, LaproSurge, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specimen Retrieval Bags Market Evolving Landscape
Material science advances and regulatory digitization are compressing traditional product lifecycles while opening specification differentiation pathways previously unavailable to mid-tier suppliers. These forces reward technical agility over scale alone.
Multilayer coextruded polyethylene films with integrated nylon reinforcement layers are displacing monolayer constructions in high-volume hospital purchasing. Academic medical centers in the United States are specifying these hybrid materials for robotic cholecystectomy and colectomy procedures. The displacement is compressing commodity bag margins while expanding addressable premium segments for puncture-resistant designs.
EU MDR unique device identification mandates and enhanced post-market surveillance requirements are extending technical documentation obligations across the product lifecycle. Manufacturers must now maintain clinical evidence registries for polyethylene and nylon film configurations that previously required only bench testing. European tertiary hospitals are responding by consolidating procurement around suppliers with established quality management systems and notified body relationships.
Hospital value analysis committees are unbundling specimen retrieval bags from traditional trocar and insufflator bundles, creating direct contracting opportunities for specialized manufacturers. Group purchasing organizations in the United States are losing leverage as individual health systems negotiate performance-based agreements tied to sterility assurance metrics. This behavioral shift is most visible in California and Texas, where integrated delivery networks with centralized supply chain functions dominate regional purchasing.
Specimen Retrieval Bags Market Segmentation
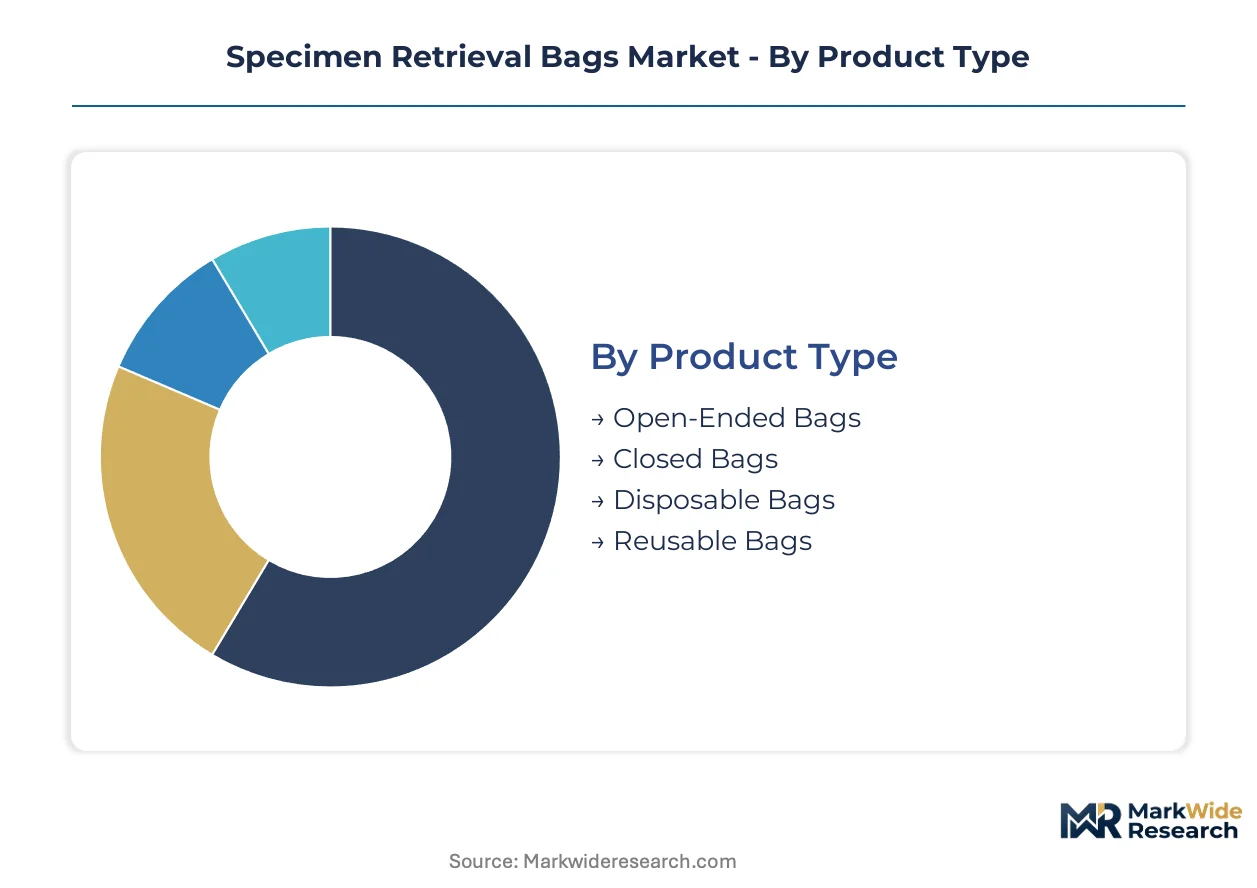
Segmentation in specimen retrieval bags reveals how material specifications, sterility requirements, and surgical workflow integration create distinct margin pools. Procurement patterns vary sharply between high-volume disposable lines and premium reusable configurations.
Product Type:
Margin concentration sits in configurations that balance sterility assurance with procedural flexibility across manual and robotic platforms.
- Open-Ended Bags:Manufactured from polyethylene or polypropylene films with 0.05–0.15 mm thickness, these configurations accommodate variable specimen sizes without pre-formed closure mechanisms. Demand clusters in tertiary hospitals across the United States and Germany where cost-per-procedure sensitivity dominates procurement decisions.
- Closed Bags:Pre-sealed designs with integrated drawstring or snap-lock mechanisms maintain pneumoperitoneum integrity during robotic-assisted procedures. Premium positioning in Japanese university hospital networks reflects stringent contamination control protocols and longer procedure durations.
- Disposable Bags:Single-use polyethylene constructions dominate volume procurement through group purchasing organizations.
- Reusable Bags:Nylon-reinforced designs withstand gamma irradiation and ethylene oxide cycles for cost-conscious health systems.
The dominant share belongs to Open-Ended Bags, while Closed Bags are expanding most quickly through robotic surgery adoption.
Material:
Cost tier stratification separates commodity resin lines from reinforced constructions that command specification premiums in sterilization-intensive settings.
- Polyethylene:Low-density and linear low-density formulations provide puncture resistance at 0.08–0.12 mm gauges for high-volume laparoscopic suites. Procurement concentrates in ambulatory surgery centers across Texas and California where per-unit pricing drives vendor selection.
- Nylon:Multilayer coextruded constructions with polyethylene substrates deliver tensile strength exceeding 30 MPa for reusable sterilization cycles. German hospital systems specify these configurations for sustainability targets and waste reduction mandates.
- Polypropylene:Higher melting point resins suit autoclave sterilization protocols in academic medical centers.
- Vinyl:Cost-sensitive alternatives penetrate price-constrained clinic segments with limited procedure volumes.
Polyethylene retains the largest procurement volume, though Nylon is gaining share fastest through EU single-use plastic restriction anticipation.
Application:
Technology intensity determines specification requirements, with robotic platforms demanding integrated pneumoperitoneum maintenance that manual techniques do not require.
- Laparoscopic Surgery:Manual retrieval through 10–15 mm trocar ports requires flexible, puncture-resistant films that collapse for extraction without tissue damage. United States tertiary hospitals drive specification upgrades toward multilayer hybrid materials.
- Robotic Surgery:Da Vinci and comparable platforms require closed-system bags with automated deployment mechanisms that preserve insufflation pressure. Japanese and German procurement committees prioritize these configurations for procedure efficiency metrics.
- Minimally Invasive Surgery:Broad category encompassing manual and assisted techniques with intermediate specification requirements.
- Endoscopic Procedures:Smaller-diameter retrieval through natural orifice approaches demands ultra-thin, high-tensile film constructions.
Laparoscopic Surgery commands the dominant procedure volume, while Robotic Surgery is climbing the fastest through capital equipment installation expansion.
End User:
Customer scale and centralization level reshape contracting dynamics, with integrated delivery networks extracting volume discounts unavailable to fragmented clinic purchasers.
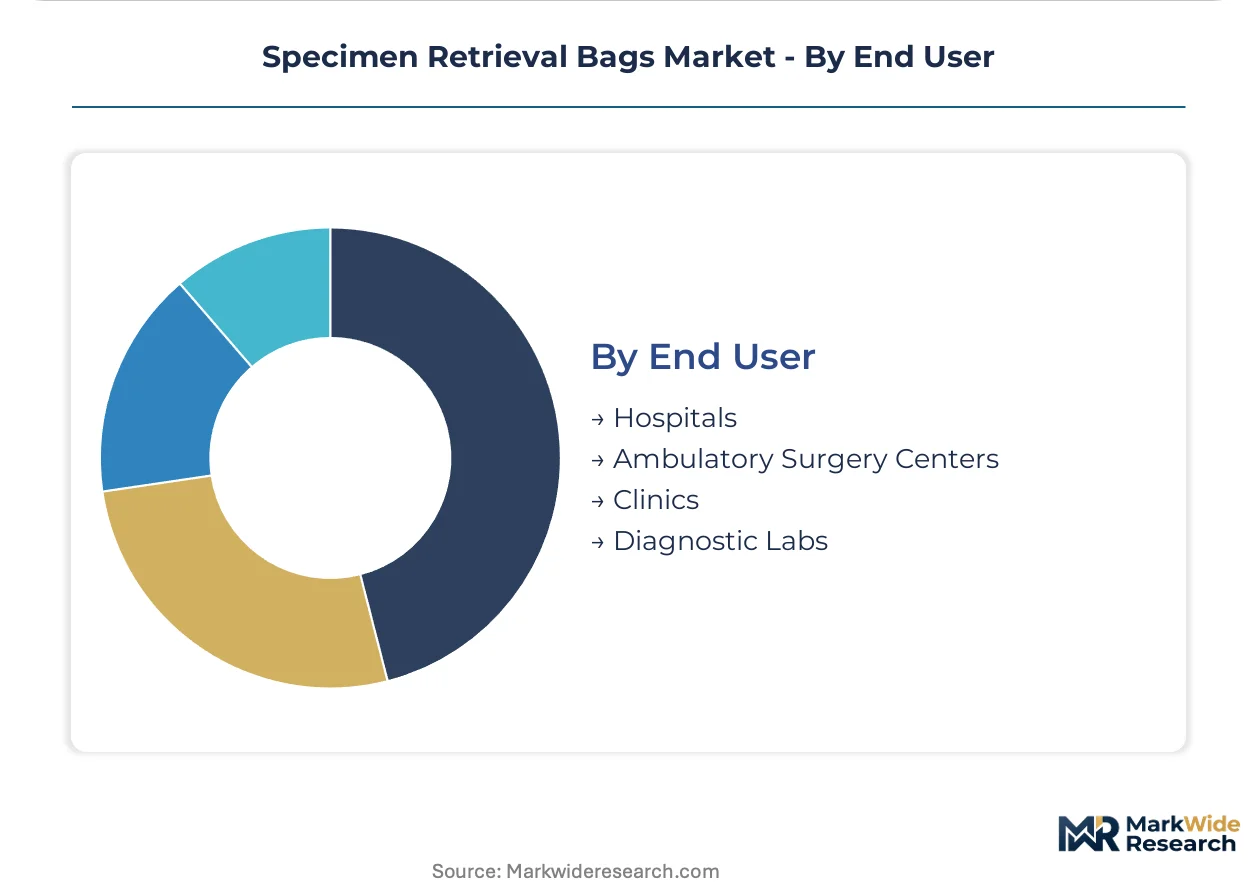
- Hospitals:Tertiary and academic medical centers with dedicated minimally invasive surgery suites specify premium puncture-resistant configurations through value analysis committees. California and Texas integrated delivery networks unbundle retrieval bags from traditional trocar bundles for direct manufacturer negotiation.
- Ambulatory Surgery Centers:Freestanding facilities prioritize disposable polyethylene lines with simplified inventory management and lower sterilization infrastructure investment. Brazilian and Indian outpatient facilities represent underpenetrated expansion targets.
- Clinics:Limited-procedure settings drive commodity procurement with minimal specification differentiation.
- Diagnostic Labs:Specimen transport applications require secondary containment validation distinct from surgical sterility standards.
Hospitals retain the dominant procurement share, while Ambulatory Surgery Centers are gaining share fastest through outpatient migration of cholecystectomy and hernia repair procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in specimen retrieval bags tilt toward developed surgical markets importing specialized nylon-reinforced configurations while exporting commodity polyethylene lines. Trade flows concentrate through medical device distribution hubs serving tertiary hospital networks.
United States
Tertiary hospitals in California and Texas drive procurement of multilayer hybrid bags for robotic surgery suites. FDA 510(k) predicate device pathways accelerate clearance timelines for polyethylene configurations. The Dallas-Fort Worth integrated delivery network corridor unbundles retrieval systems from traditional trocar bundles for direct manufacturer negotiation.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia specify nylon-reinforced reusable bags for sustainability compliance. EU MDR technical documentation requirements extend approval timelines for new film configurations. The Stuttgart surgical instruments cluster concentrates sterilization validation expertise serving Central European health systems.
Japan
Tokyo and Osaka academic medical centers prioritize closed-system bags for Da Vinci platform compatibility. PMDA enforces Japan Industrial Standards for film integrity and sterility validation that exceed baseline ISO requirements. The Kansai region hosts specialized distributors bridging domestic hospital procurement with multinational suppliers.
India
Ambulatory surgery centers in Maharashtra and Karnataka lack dedicated minimally invasive surgery infrastructure, creating first-mover expansion potential. CDSCO medical device rules govern import licensing for polyethylene and nylon film configurations. The Chennai medical device manufacturing zone attracts contract sterilization providers serving Southeast Asian export markets.
Brazil
Outpatient facilities in São Paulo and Minas Gerais represent underpenetrated targets for bundled retrieval systems. ANVISA registration requirements for Class II medical devices constrain market entry timelines for foreign manufacturers. The Campinas health technology corridor concentrates private hospital chains pursuing surgical suite modernization.
Specimen Retrieval Bags Market Competitive Landscape
Listed leaders compete with private specialists across regulatory infrastructure and hospital contracting relationships. Johnson & Johnson, Stryker, and Medtronic anchor the consolidated tier through dedicated minimally invasive surgery divisions, while mid-tier specialists exploit unbundling trends in value analysis committee procurement. Strategic moves concentrate on portfolio bundling with trocar platforms and direct contracting bypass of group purchasing organizations.
Within the diversified medical technology tier, Johnson & Johnson and Medtronic exemplify archetypes integrating retrieval bags into broader surgical workflow ecosystems. Stryker occupies a position emphasizing dedicated minimally invasive surgery infrastructure. Among specialized manufacturers, Applied Medical Resources and Purple Surgical represent private specialists competing through focused product lines and regional hospital relationships. B. Braun and CONMED Corporation sit within the European-anchored fabrication tier leveraging sterilization expertise. Teleflex exemplifies the vascular access crossover archetype applying catheter manufacturing discipline to retrieval bag film specifications.
| Leading Market Players |
|---|
| Applied Medical Resources |
| B. Braun |
| Johnson & Johnson |
| Purple Surgical |
| Stryker |
| Medtronic |
| CONMED Corporation |
| LaproSurge |
| Teleflex |
| Others |
Value Network & Pricing Analysis
Nylon-reinforced multilayer films displacing monolayer polyethylene constructions are simultaneously shifting procurement geography toward German sterilization validation clusters and compressing margin pools for commodity resin suppliers in Texas and California. This substitution dynamic concentrates pricing power with converters possessing ethylene oxide protocol expertise while forcing ambulatory surgery centers toward longer-term contracting to hedge per-unit volatility.
Pricing Analysis
Hospital value analysis committees anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 10993 biocompatibility certification tier and volume scale commitments through integrated delivery networks. Pricing pressure stems from EU MDR technical documentation cost absorption, with ambulatory surgery centers exhibiting highest price sensitivity due to limited sterilization infrastructure investment.
Supply Chain Analysis
Ethylene oxide sterilization capacity chokepoints in the Stuttgart surgical instruments cluster underwrite supply security for Central European hospital networks. Raw material flows draw from Saudi petrochemical feedstocks, South Korean nylon resin production, and domestic polyethylene compounding in Texas. Single-source vulnerability concentrates in gamma irradiation facilities serving Japanese PMDA compliance requirements. Distribution runs through specialized medical device distributors bridging multinational manufacturers with regional hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specimen retrieval bags function as a service-attach opportunity where sterilization validation consulting and EU MDR conformity guidance expand faster than hardware unit economics. Recurring revenue from technical documentation support and notified body relationship management outpaces disposable bag procurement growth.
For Market Incumbents: Compound defensive positioning through backward integration into nylon resin compounding and captive sterilization capacity in Bavaria. FDA 510(k) predicate libraries and established GPO relationships defend against mid-tier specialists exploiting unbundling trends. Priority investment targets ethylene oxide alternative validation as EU single-use plastic restrictions tighten.
For New Entrants and Emerging Players: Differentiate on EU MDR consultancy bundling with hardware supply, targeting Maharashtra and Karnataka ambulatory surgery centers lacking minimally invasive surgery infrastructure. Direct manufacturer contracting with Brazilian private hospital chains in Campinas bypasses established distribution layers. White-space penetration requires CDSCO import licensing navigation and localized sterilization partnerships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sterilization service providers possessing notified body relationships and hospital GPO access. Long-term viability hinges on regulatory digitization readiness and alternative material pipelines. The signal to watch is EU MDR unique device identification mandate acceleration compressing documentation outsourcing demand cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device referencing accelerates polyethylene bag clearance timelines for robotic surgery compatibility. |
| CE Marking Pathway | EU MDR technical documentation investment secures German university hospital network procurement consolidation. |
| Hospital System Partnership | Direct contracting with California integrated delivery networks bypasses traditional GPO leverage structures. |
| Software Companion Development | RFID-enabled traceability integration captures university hospital supply chain digitization budgets. |
| Reimbursement Strategy | Outpatient procedure migration alignment secures ambulatory surgery center volume commitments in Texas. |
Research Methodology
A standing panel of laparoscopic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation through FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and customs trade records. Bottom-up procedure volume modeling triangulated with top-down manufacturer revenue aggregation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across material type, sterility configuration, application intensity, and end-user centralization dimensions. CAGRs derived from segmented procedure growth rates and pricing trajectory assumptions incorporated robotic surgery capital equipment installation pipelines and EU single-use plastic restriction anticipation effects.
The analysis sits within stated boundaries; outcomes outside sustained laparoscopic procedure volume expansion and regulatory pathway stability would require recalibration. Practitioners should keep alternative scenarios live as EU MDR notified body capacity constraints and petrochemical input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Soaker Pads Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Bleeding Control Kit Market