
 Ultrasound Gels Market | 2026-2036
Ultrasound Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Gels Market Intelligence
North American gel production is decoupling from European supply chains as domestic manufacturers expand compounding capacity. Parker Laboratories leverages its vertical integration into polymer sourcing to control formulation consistency across hospital networks. HR Pharmaceuticals sustains brand loyalty among outpatient clinics through specialized aloe vera-based portfolios. Medline Industries anchors bulk procurement contracts with integrated delivery networks, competing on logistics scale rather than formulation novelty.
Ultrasound gels are viscous, acoustically transparent coupling media formulated from water, humectants, and rheology modifiers to eliminate air gaps between transducer and tissue during sonographic imaging. Water-based formulations dominate hospital purchasing due to lowest cost per procedure and broad transducer compatibility, while aloe vera-based variants command margin premiums in dermatology-sensitive applications and pediatric settings. Diagnostic imaging applications absorb the majority of volume, though physiotherapy clinics represent a faster-growing channel as musculoskeletal ultrasound expands beyond radiology departments.
FDA 510(k) clearance requirements for medical device accessories govern gel biocompatibility and sterility claims in the United States, while EU MDR and REACH frameworks constrain preservative chemistry and labeling across European markets. China's NMPA registration pathways for imported medical consumables add compliance layers that favor domestic manufacturers with established type-testing relationships. Stakeholders must monitor evolving dermatological safety standards and polymer substitution trends as clean-label preferences reshape procurement specifications across end-user segments.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while simultaneously demanding expanded sterile gel portfolios, forcing manufacturers to recalibrate formulation investments against logistics scale.
Growth Catalysts
- EU MDR sterility mandates:Class I reclassification of ultrasound gels as medical device accessories accelerates facility-wide switching to certified sterile formulations across German and French hospital networks.
- Musculoskeletal ultrasound expansion:Physiotherapy clinics in the United States absorb rising gel volumes as point-of-care imaging displaces referral-dependent diagnostic pathways.
- Polymer substitution R&D:Carbomer-free rheology modifiers derived from cellulose derivatives gain traction among pediatric and dermatology-sensitive patient populations.
Market Restraints
- Propylene glycol price volatility:Petrochemical feedstock fluctuations compress formulation margins for mid-tier manufacturers lacking captive humectant supply.
- Single-source polymer concentration:Carbomer production clusters in Chinese and German chemical hubs expose gel compounders to geographic supply disruption.
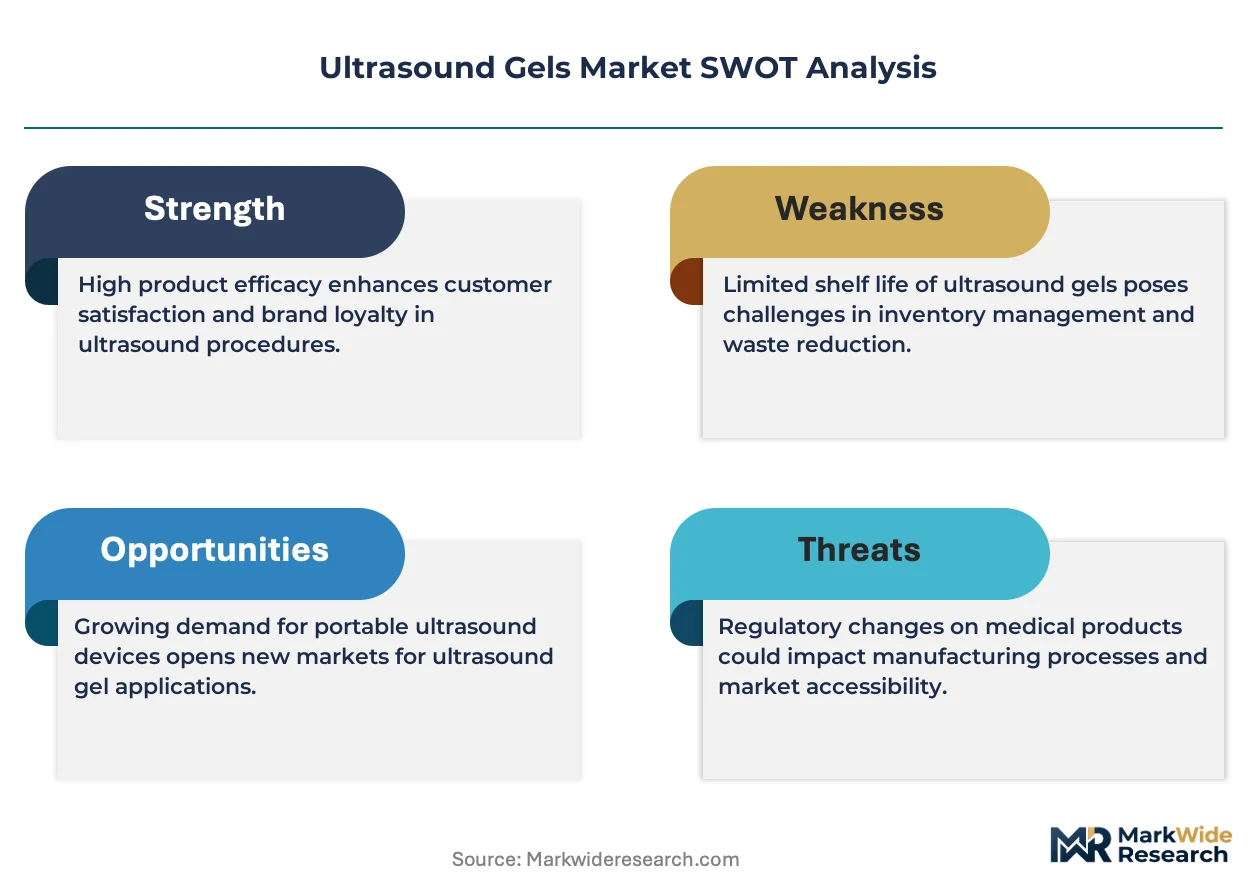
- Preservative-free shelf-life limitations:Elimination of parabens and formaldehyde releasers under REACH constraints reduces product stability windows to 18-24 months.
Strategic Opportunities
- India outpatient diagnostic expansion:CDSCO streamlined medical device registration creates entry pathways for sterile gel portfolios targeting tier-2 and tier-3 city imaging centers.
- Veterinary ultrasound adoption:Equine and small-animal diagnostic practices represent underpenetrated volume channels with lower regulatory barriers than human medical markets.
- Sustainability-linked procurement:EU Green Deal carbon accounting requirements favor gel manufacturers with ISO 14001-certified production and bio-based packaging credentials.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Extended cytotoxicity and sensitization study timelines delay new formulation launches by 8-14 months.
- Legacy ERP integration friction:Hospital IDN procurement platforms demand EDI connectivity that smaller compounders struggle to implement without dedicated IT capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Gels Market |
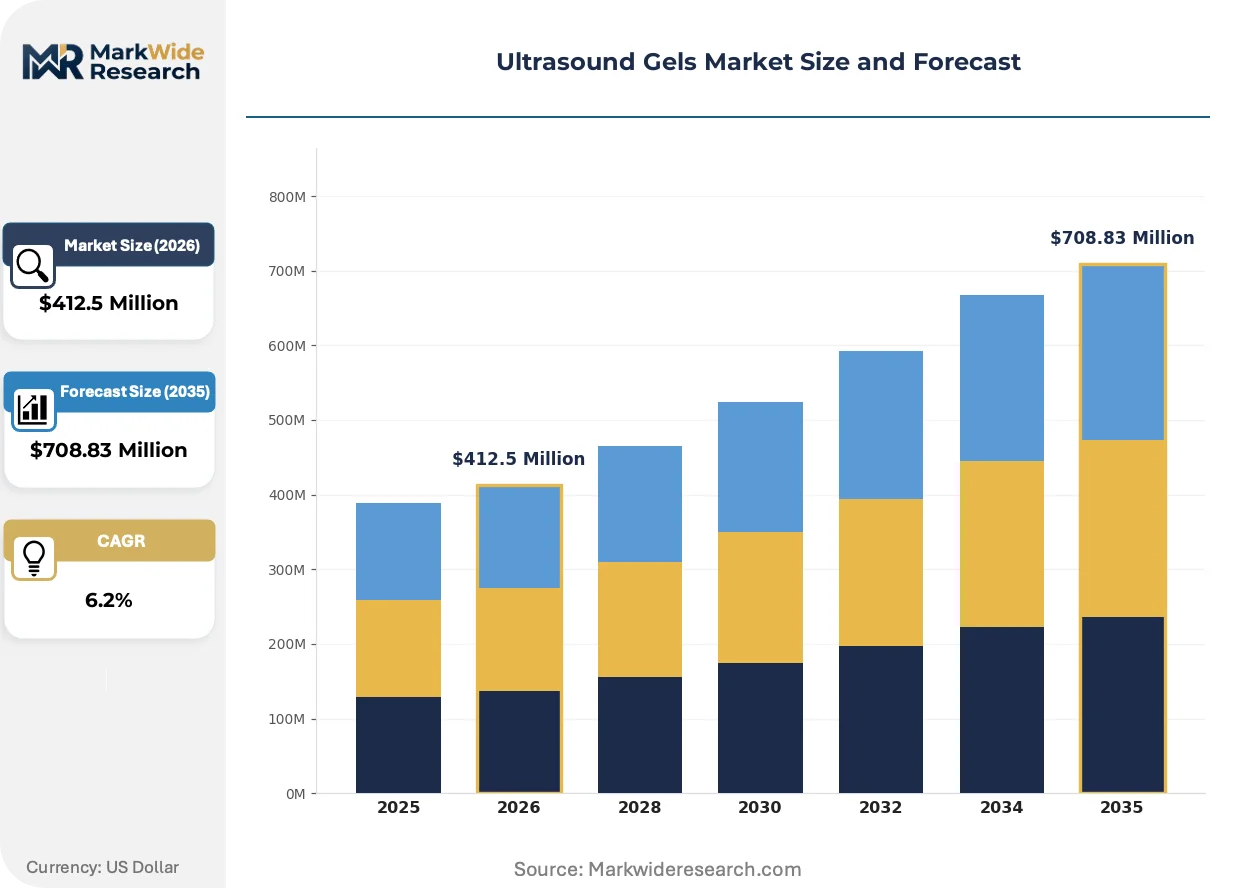
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $708.83 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Aloe Vera-Based, Hydrogel, Conductive Gel Application: Diagnostic Imaging, Therapeutic Applications, Physiotherapy, Veterinary Use End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Packaging Type: Tubes, Jars, Sachets, Bulk Containers |
| Companies Covered | Parker Laboratories, HR Pharmaceuticals, Medline Industries, Compass Health Brands, National Therapy Products, ECO-MED, Cardinal Health, Sonogel Vertriebs, Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Gels Market Strategic Shifts & Innovations
Formulation chemistry and procurement specifications are diverging from decade-old standards as end-users prioritize dermatological safety alongside acoustic performance.
Spray-dried hydroxypropyl methylcellulose (HPMC) is decentralizing rheology control in next-generation gels by replacing carbomer matrices with plant-derived alternatives that reduce transducer residue and improve skin tolerability. Pediatric wards and dermatology clinics in the United States are piloting HPMC-based portfolios at triple the rate of general imaging departments. This substitution is decentralizing supplier power away from petrochemical-specialized compounders toward cellulose processors with pharmaceutical-grade purification capabilities.
REACH Annex XVII restrictions on methylisothiazolinone (MI) preservatives are forcing European manufacturers to reformulate entire product lines before 2026 compliance deadlines. The industrial consequence is accelerated R&D spending on alternative preservation systems including caprylyl glycol and ethylhexylglycerin combinations. Sterile single-use sachet formats are gaining share in Germany and France as manufacturers sidestep shelf-life stability challenges entirely.
Hospital value-analysis committees now mandate side-by-side clinical evaluations before approving gel switches, extending procurement cycles from 90 days to 8-12 months. Group purchasing organizations are consolidating supplier rosters to three preferred vendors per IDN, displacing fragmented local distribution relationships. This concentration is most visible in Texas and California health systems where Ascension and Kaiser Permanente networks have completed standardization programs.
Ultrasound Gels Market Segmentation
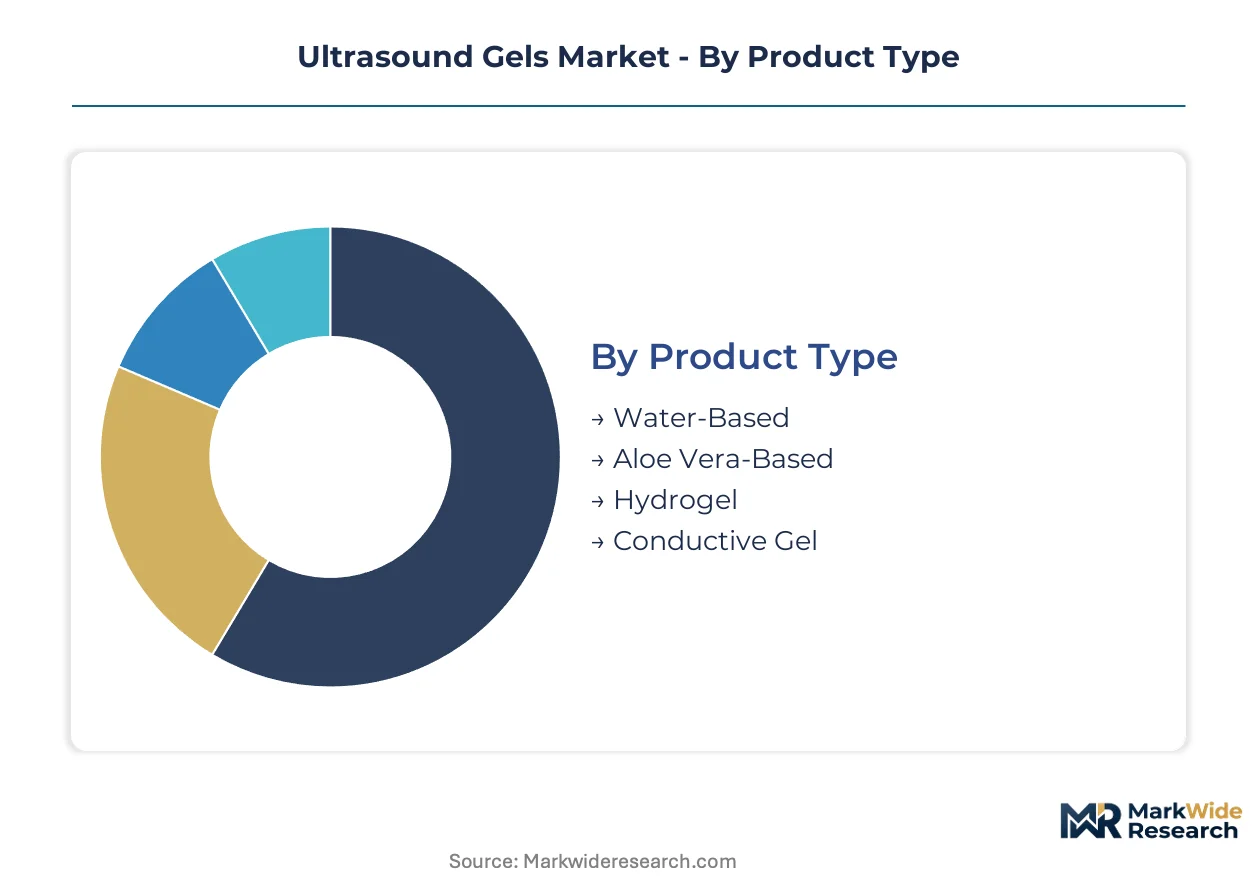
Ultrasound gel procurement diverges sharply across clinical settings, with formulation chemistry, sterility requirements, and procedure volume dictating supplier selection. Manufacturers must align production capacity against these segment-specific demand profiles to avoid margin compression from mismatched inventory.
Product Type:
Carbomer supply concentration in Chinese and German chemical hubs shapes competitive positioning across formulation categories.
- Water-Based:Formulated with deionized water, propylene glycol humectants, and carbomer rheology modifiers for broad transducer compatibility. Hospital networks in the United States absorb the majority of volume due to lowest cost-per-procedure and standardized procurement at IDN level.
- Aloe Vera-Based:Incorporates Aloe barbadensis leaf extract as primary humectant alongside cellulose-derived thickeners for dermatological sensitivity. Pediatric wards and dermatology clinics in Germany command margin premiums for these formulations amid REACH-driven preservative restrictions.
- Hydrogel:Cross-linked polymer matrices with elevated water content for extended acoustic coupling duration. Research laboratories specify these for high-resolution imaging protocols.
- Conductive Gel:Ionic salt additives enhance electrical conductivity for combined ultrasound-ECG procedures. Cardiology departments in diagnostic centers represent primary uptake channel.
Water-Based absorbs the bulk of installed capacity; Aloe Vera-Based is expanding most quickly.
Application:
Procedure reimbursement rates and point-of-care technology diffusion determine volume allocation across clinical use cases.
- Diagnostic Imaging:Abdominal, obstetric, and cardiac sonography protocols in hospital radiology departments. United States health systems standardize on sterile single-use formats to satisfy Joint Commission infection control audits.
- Therapeutic Applications:Phacoemulsification coupling and lithotripsy media in ophthalmology and urology suites. Outpatient surgical centers in Texas and California drive specification upgrades.
- Physiotherapy:Musculoskeletal ultrasound guidance for injection procedures in sports medicine clinics. Faster volume expansion here as physical therapists deploy portable imaging units.
- Veterinary Use:Equine tendon imaging and small-animal abdominal scanning in specialty practices. Lower regulatory barriers than human medical markets attract mid-tier compounders.
Diagnostic Imaging commands the majority of current volume; Physiotherapy shows the steepest expansion trajectory.
End User:
Consolidated procurement platforms versus fragmented purchasing authority creates divergent pricing power across customer types.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements with stringent ISO 10993 biocompatibility documentation. Kaiser Permanente and Ascension networks have completed vendor consolidation programs.
- Clinics:Independent outpatient facilities prioritize aloe vera-based and preservative-free portfolios for patient satisfaction metrics. HR Pharmaceuticals sustains brand loyalty through specialized formulations.
- Diagnostic Centers:High-throughput imaging facilities in tier-2 Indian cities absorb rising sterile gel volumes as CDSCO registration streamlines.
- Research Laboratories:Academic medical centers specify hydrogel variants for experimental imaging protocols with custom viscosity requirements.
Hospitals dominate absolute consumption; Diagnostic Centers are climbing the fastest as outpatient networks proliferate.
Packaging Type:
Shelf-life stability constraints and infection control protocols drive format selection across sterile and non-sterile portfolios.
- Tubes:Collapsible aluminum or laminated plastic containers for multi-use clinical settings. Standard format for hospital central supply warehouses.
- Jars:Wide-mouth polypropylene containers for high-volume physiotherapy departments. Pump dispenser compatibility reduces cross-contamination risk.
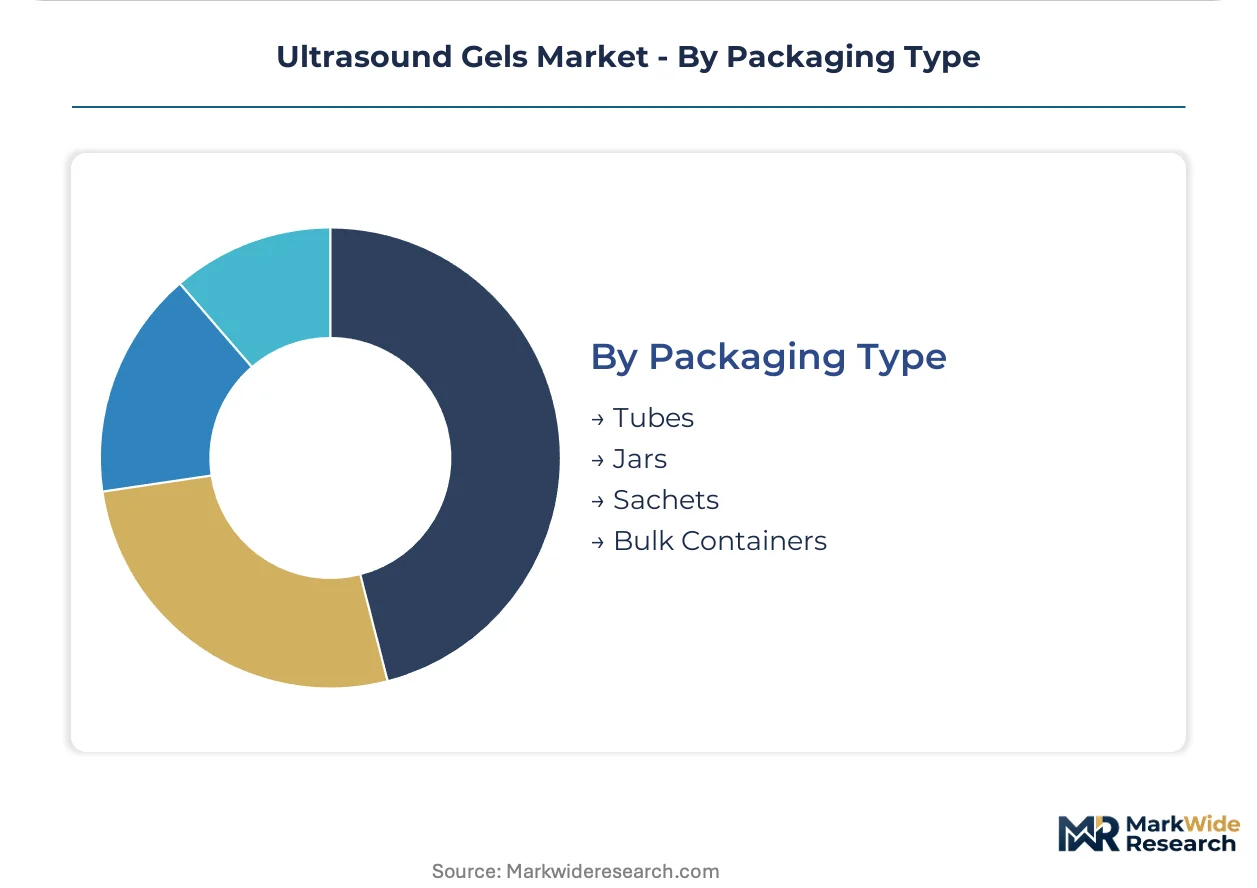
- Sachets:Sterile single-use foil pouches gaining share in Germany and France as manufacturers sidestep preservative-free stability challenges entirely.
- Bulk Containers:Five-liter bags with dispenser systems for high-throughput diagnostic imaging centers. Medline Industries anchors contracts through logistics scale.
Tubes retain the largest installed base; Sachets are gaining share fastest amid sterility mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene glycol feedstock availability in Texas and Louisiana underpins North American formulation capacity, while carbomer production clusters in Shanghai and Ludwigshafen shape procurement geography for compounders worldwide.
United States
Hospital procurement consolidation through Kaiser Permanente and Ascension networks drives sterile gel standardization across California and Texas health systems. FDA 510(k) clearance requirements for medical device accessories govern biocompatibility claims and sterility labeling. The Dallas-Fort Worth metroplex anchors bulk distribution infrastructure serving outpatient diagnostic networks throughout the Southwest.
Germany
EU MDR sterility mandates accelerate facility-wide switching to certified sterile formulations across university hospital networks in Bavaria and North Rhine-Westphalia. REACH Annex XVII restrictions on methylisothiazolinone preservatives force reformulation of entire product lines before 2026 deadlines. Frankfurt chemical processing hubs concentrate carbomer and cellulose derivative supply for gel compounders serving French and Benelux markets.
China
NMPA registration pathways for imported medical consumables add compliance layers that favor domestic manufacturers with established type-testing relationships in Shanghai and Beijing. Tier-2 city diagnostic centers in Chengdu and Wuhan absorb rising sterile gel volumes as hospital-based ultrasound services expand beyond coastal provinces. Yangtze River Delta polymer producers supply rheology modifiers to regional compounders at cost advantages over European imports.
India
CDSCO streamlined medical device registration creates entry pathways for sterile gel portfolios targeting tier-2 and tier-3 city imaging centers in Maharashtra and Karnataka. Outpatient diagnostic networks in Mumbai and Bangalore drive consumption of hypoallergenic formulations amid dermatological safety awareness campaigns. Domestic compounders leverage local aloe vera cultivation in Rajasthan for botanical-humectant gel variants.
Japan
PMDA quality management system requirements sustain premium positioning for preservative-free formulations in Tokyo and Osaka metropolitan hospital networks. Aging demographics expand obstetric and cardiac ultrasound procedural volumes in Kansai region diagnostic centers. Chubu-based cellulose processors supply pharmaceutical-grade HPMC for next-generation pediatric gel alternatives.
Ultrasound Gels Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue preservative-free and sustainable formulations to differentiate positioning. The market structure reflects moderate consolidation around integrated delivery network procurement platforms, with three to five preferred vendors capturing majority volume in consolidated health systems. Strategic archetypes include petrochemical-integrated compounders controlling polymer supply, botanical-formulation specialists serving dermatology-sensitive segments, and logistics-scale distributors anchoring bulk procurement contracts. Dominant competitive moves encompass backward integration into humectant sourcing and sterile single-use format expansion to satisfy infection control mandates.
Among North American manufacturers, Parker Laboratories exemplifies polymer-supply control through captive sourcing relationships, while HR Pharmaceuticals occupies the botanical-formulation specialist archetype with aloe vera-based portfolios. Medline Industries anchors the logistics-scale distributor position through integrated delivery network contracting. These three entities represent distinct strategic vectors: upstream supply control, patient-sensitivity specialization, and procurement platform dominance.
| Leading Market Players |
|---|
| Parker Laboratories |
| HR Pharmaceuticals |
| Medline Industries |
| Compass Health Brands |
| National Therapy Products |
| ECO-MED |
| Cardinal Health |
| Sonogel Vertriebs |
| Trivitron Healthcare |
| Others |
Cost & Logistics Intelligence
Polymer chemist concentrations in Ludwigshafen and Shanghai sustain labor-cost differentials that widen pricing-tier spreads between premium cellulose-derived formulations and commodity carbomer-based alternatives.
Pricing Analysis
Service bundling separates sterile single-use sachet formats with ISO 10993 documentation from unbundled bulk-container supply lacking biocompatibility certification. Three-tier pricing structure across premium, standard, and economy levels reflects formulation chemistry, sterility claims, and after-sales technical support. Pricing pressure stems from hospital procurement consolidation through integrated delivery networks compressing mid-tier supplier margins. Outpatient clinics exhibit highest price sensitivity due to fragmented purchasing authority, while Kaiser Permanente-scale networks leverage volume scale for least sensitivity.
Supply Chain Analysis
Freight cost exposure concentrates around carbomer shipments from Chinese chemical hubs to European compounding facilities, with container-rate volatility feeding directly into formulation margins. Manufacturing gravity centers on Germany, China, and the United States for polymer processing and final gel compounding. Raw material dependencies encompass propylene glycol humectants, carbomer and HPMC rheology modifiers, and aloe vera botanical extracts. Single-source polymer concentration in Shanghai and Ludwigshafen exposes compounders to geographic supply disruption. Distribution runs through integrated delivery network procurement platforms and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around procurement platform dominance as ISO 10993 biocompatibility testing backlogs and ERP integration requirements force weaker compounders toward exit.
For Market Incumbents: Deepen backward integration into cellulose derivative supply to secure HPMC access as carbomer substitution accelerates in pediatric and dermatology-sensitive segments. Expand sterile single-use sachet production capacity in Frankfurt chemical processing hubs to capture EU MDR mandate-driven demand in German and French hospital networks. Anchor multi-year supply agreements with Ascension and Kaiser Permanente networks before procurement roster consolidation completes. For New Entrants and Emerging Players: Capture veterinary ultrasound channels in equine and small-animal diagnostic practices where regulatory barriers fall below human medical thresholds. Target tier-2 Indian city diagnostic centers through CDSCO streamlined registration pathways for sterile gel portfolios. Pursue sustainability-linked procurement positioning with ISO 14001-certified production and bio-based packaging credentials to differentiate against established petrochemical-integrated compounders. For Investors and Strategic Acquirers: Re-rating potential sits with botanical-formulation specialists given REACH-driven preservative restrictions and clean-label procurement preferences reshaping hospital value-analysis committee specifications. Long-term viability favors compounders with captive polymer supply and sterile format diversification over logistics-scale distributors exposed to margin compression. Watch for EU MDR compliance deadline acceleration as inflection indicator for sterile formulation demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Supply | HPMC access secures positioning as carbomer substitution accelerates in pediatric wards. |
| Sterile Single-Use Sachet Expansion | Sidesteps preservative-free shelf-life limitations while capturing EU MDR mandate compliance. |
| ISO 14001 Certification Program | EU Green Deal carbon accounting requirements favor gel manufacturers with verified sustainability credentials. |
| Veterinary Channel Entry | Lower regulatory barriers in equine and small-animal diagnostics enable faster volume accumulation. |
| Hospital IDN Partnership | Ascension and Kaiser Permanente procurement consolidation rewards early preferred-vendor positioning. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, CDSCO registration databases, and hospital procurement contracts, complemented by interviews with gel formulation chemists, hospital purchasing committee managers, biomedical engineers, and group purchasing organization contract directors. Secondary validation drew from customs trade data, SEC filings of medical device distributors, and REACH Annex XVII regulatory updates. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry segments.
Quantitative outputs span product type, application, end user, and packaging format dimensions across the projection horizon. CAGRs derive from procedure volume trajectories in diagnostic imaging and physiotherapy channels, polymer substitution rates in pediatric settings, and sterility mandate compliance timelines. Industry-specific inputs include propylene glycol feedstock price indices, ISO 10993 testing backlog durations, and integrated delivery network procurement platform adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH preservative restriction enforcement, EU MDR sterility mandate acceleration, and polymer supply disruption in Chinese chemical hubs. Forecasts reflect documented assumptions around procedure volume growth and regulatory compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Fibrin Sealants Market