
 Middle-East and Africa Coil Coatings Market | 2026-2036
Middle-East and Africa Coil Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Coil Coatings Market Foresight
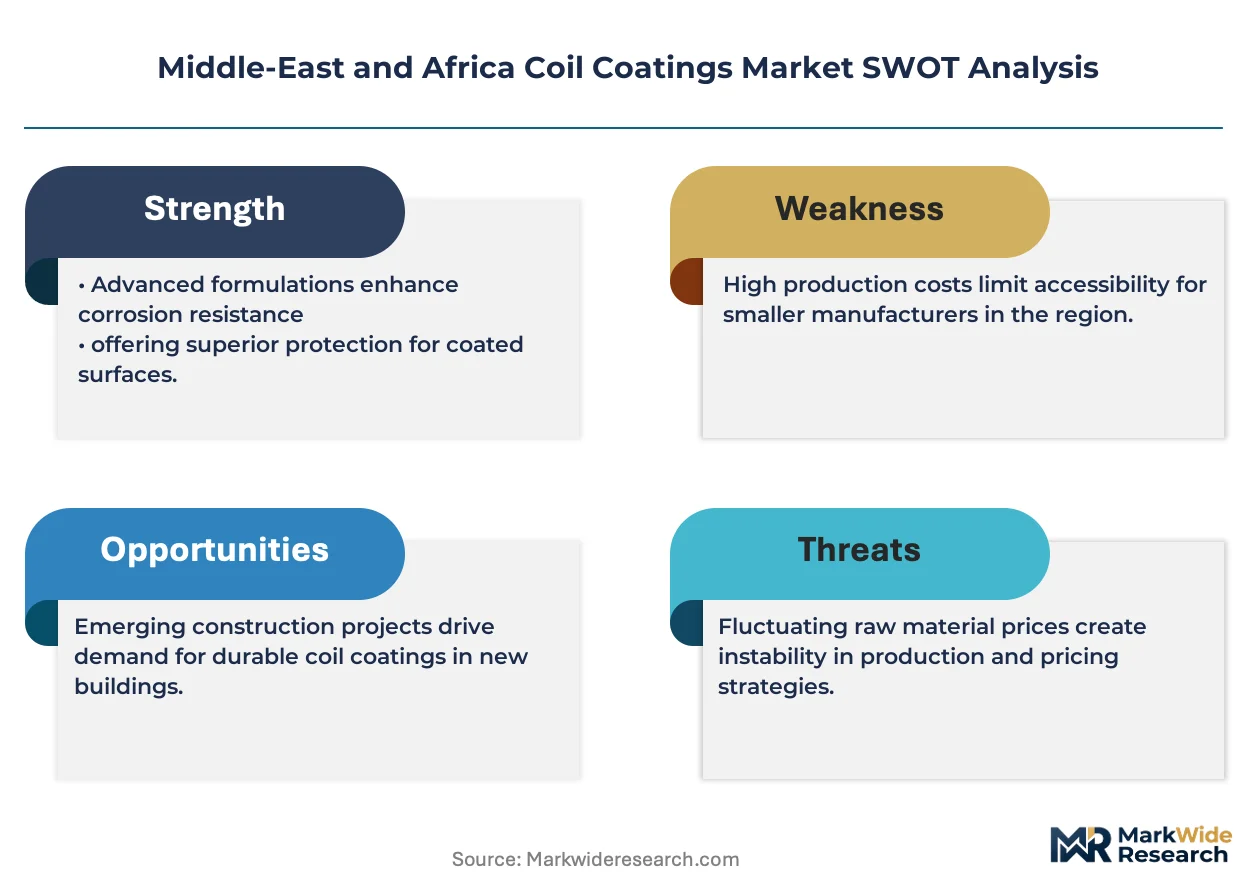
Premium-grade fluoropolymer specification tiers is collapsing into mainstream architectural procurement across Gulf markets. AkzoNobel N.V. leverages its regional manufacturing footprint to supply high-durability coil coatings for Saudi megaprojects. PPG Industries, Inc. anchors its position through technical service centers in Dubai and Johannesburg. Beckers Group differentiates via specialized color-matching capabilities for desert-climate UV resistance requirements.
Coil coatings are factory-applied liquid or powder finishes cured onto continuous metal strips, typically aluminum or galvanized steel, at coating weights of 20–25 micrometers for exterior architectural duty. The process involves chemical pretreatment, primer application, topcoat deposition, and thermal curing in continuous coil lines to deliver uniform corrosion protection and aesthetic consistency across large building envelopes. Polyester formulations dominate volume consumption across Middle-East and Africa construction applications due to cost-performance balance in high-UV environments. Polyurethane segments capture margin pools in HVAC and appliance end uses where flexibility and chemical resistance command specification premiums. Fluoropolymer coatings lead growth trajectory in exterior architectural segments across Gulf states where fifty-year durability warranties drive material selection.
Saudi Arabia's SFDA enforces volatile organic compound emission standards on imported coating formulations, while UAE's MOHAP aligns with Gulf Standardization Organization building material regulations that mandate exterior coating weathering performance testing. South Africa's National Regulator for Compulsory Specifications enforces SANS standards for metal roofing corrosion protection in coastal zones. Stakeholders must monitor evolving Gulf Cooperation Council harmonization of construction product certification requirements and position formulation portfolios to meet tightening low-VOC mandates without sacrificing tropical ultraviolet degradation resistance.
Market Dynamics
Saudi Arabia's SFDA volatile organic compound emission limits are compressing formulation margins across the Gulf Cooperation Council, forcing suppliers to re-engineer polyester and fluoropolymer chemistries without sacrificing fifty-year warranty performance in desert ultraviolet conditions.
Growth Catalysts
- SFDA Low-VOC Mandates:Saudi Arabia's tightening emission standards on architectural coatings are accelerating specification upgrades toward premium fluoropolymer tiers across Riyadh and Jeddah megaproject corridors.
- Pre-coated Metal Cladding:Construction sector procurement of factory-finished building envelopes is intensifying across Gulf Cooperation Council states as developers compress on-site labor schedules and weather-dependent application windows.
- Continuous Coil Line Technology:Advances in thermal curing efficiency and chemical pretreatment automation are expanding viable substrate ranges to include thinner-gauge aluminum for lightweight architectural applications.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment cost swings in polyester and polyurethane formulations compress margin pools for regional coating manufacturers dependent on import-heavy supply chains.
- Fluoropolymer Resin Concentration:Global supply of PVDF and FEVE resins concentrates among a limited supplier base, exposing Gulf architectural specifiers to allocation risk during capacity tightness.
- Desert UV Degradation Physics:Extreme thermal cycling and sand abrasion create accelerated failure modes that outpace standard ASTM weathering test protocols, complicating warranty underwriting.
Strategic Opportunities
- South Africa Coastal Corrosion:SANS standard enforcement for metal roofing in Durban and Cape Town coastal zones creates specification demand for specialized primer-topcoat systems with enhanced salt-spray resistance.
- UAE MOHAP-GSO Harmonization:Converging building material certification requirements across Emirates and Gulf Standardization Organization frameworks streamline multi-country product registration for compliant suppliers.
- Powder Coil Coating Convergence:Zero-VOC powder formulations meeting HVAC and appliance flexibility requirements are penetrating architectural segments previously reserved for liquid fluoropolymers.
Industry Challenges
- Formulation Chemist Scarcity:Gulf-based technical talent capable of balancing low-VOC compliance with tropical UV stability specifications remains concentrated among multinational coating manufacturers.
- Continuous Line Capex Intensity:Regional investment in dedicated coil coating capacity requires long-term offtake commitments from megaproject developers with compressed decision timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Coil Coatings Market |
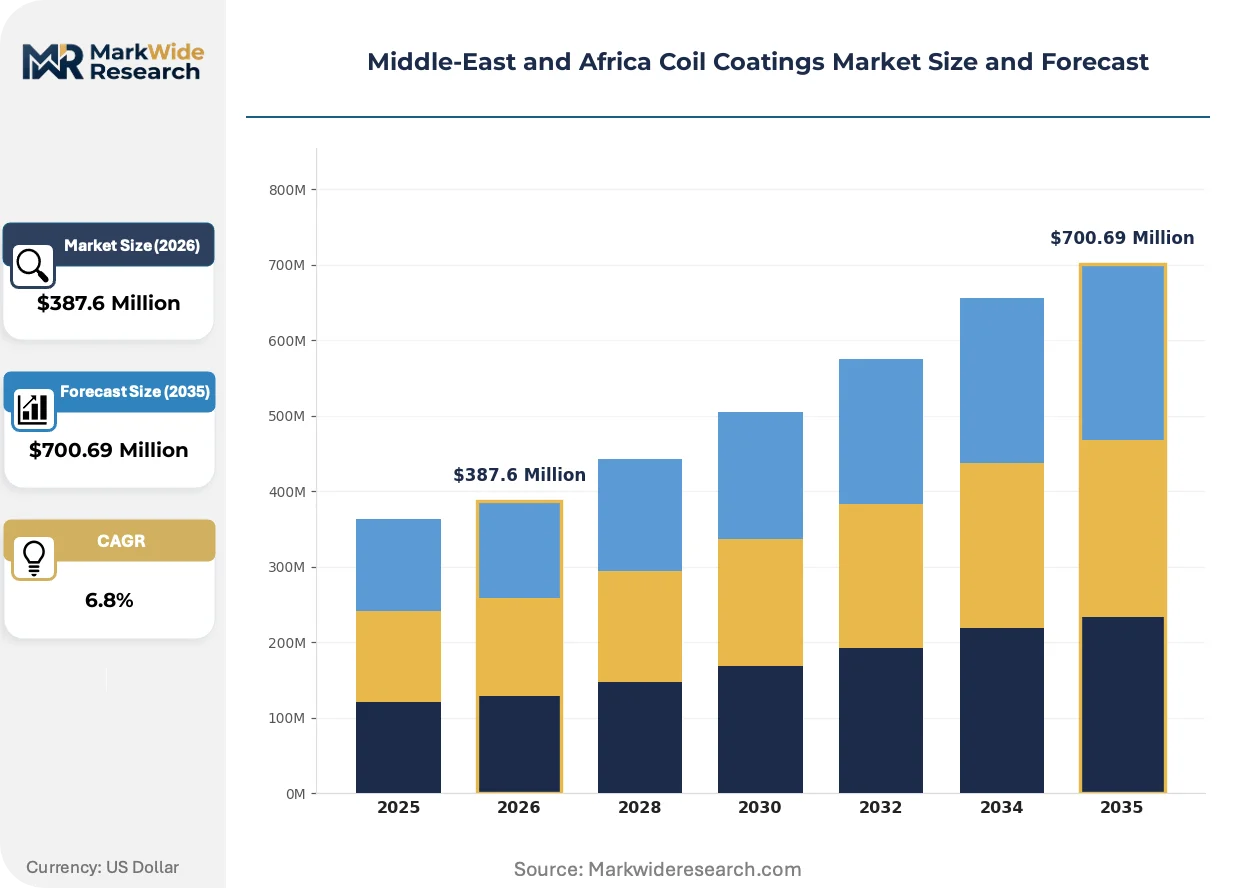
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyurethane, Plastisol, Fluropolymer End Use Industry: Construction, HVAC, Automotive, Appliances Application: Interior, Exterior, Electrical Housing, Metal Components Technology: Thermoset, Thermoplastic, Electrostatic Spraying, Roller Coating |
| Companies Covered | AkzoNobel N.V., Alcoa Corporation, PPG Industries, Inc., The Sherwin-Williams Company, Tata Steel, Axalta Coating Systems, Norsk Hydro ASA, Beckers Group, Kansai Paint Co., Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Coil Coatings Market Shifts & Advancements
Factory-applied coating systems are undergoing functional specialization as Gulf construction procurement shifts toward performance-guaranteed building envelopes with embedded durability warranties rather than commodity metal finishes.
Photocatalytic self-cleaning topcoats incorporating titanium dioxide nanoparticles are miniaturizing maintenance intervals for high-rise curtain wall applications across Dubai and Riyadh. Saudi megaproject developers specify these surfaces to reduce facade cleaning frequency in dust-intensive desert environments. The technology is compressing lifecycle service cost calculations and tilting material selection toward premium coating tiers.
UAE's MOHAP alignment with Gulf Standardization Organization weathering performance testing mandates is disqualifying imported formulations lacking accelerated UV exposure documentation. Regional coating distributors now maintain in-country testing partnerships to validate Gulf-specific climate resilience. Architectural specification committees in Abu Dhabi and Sharjah are rejecting uncertified products from established European suppliers.
Developer procurement teams are consolidating coating specifications across multi-tower residential portfolios to capture volume pricing and simplify supply chain coordination. This concentration is displacing project-by-project competitive bidding for metal cladding finishes. The pattern is most visible in Saudi Arabia's Neom and Red Sea Project developments where master developers enforce approved product lists.
Middle-East and Africa Coil Coatings Market Segmentation
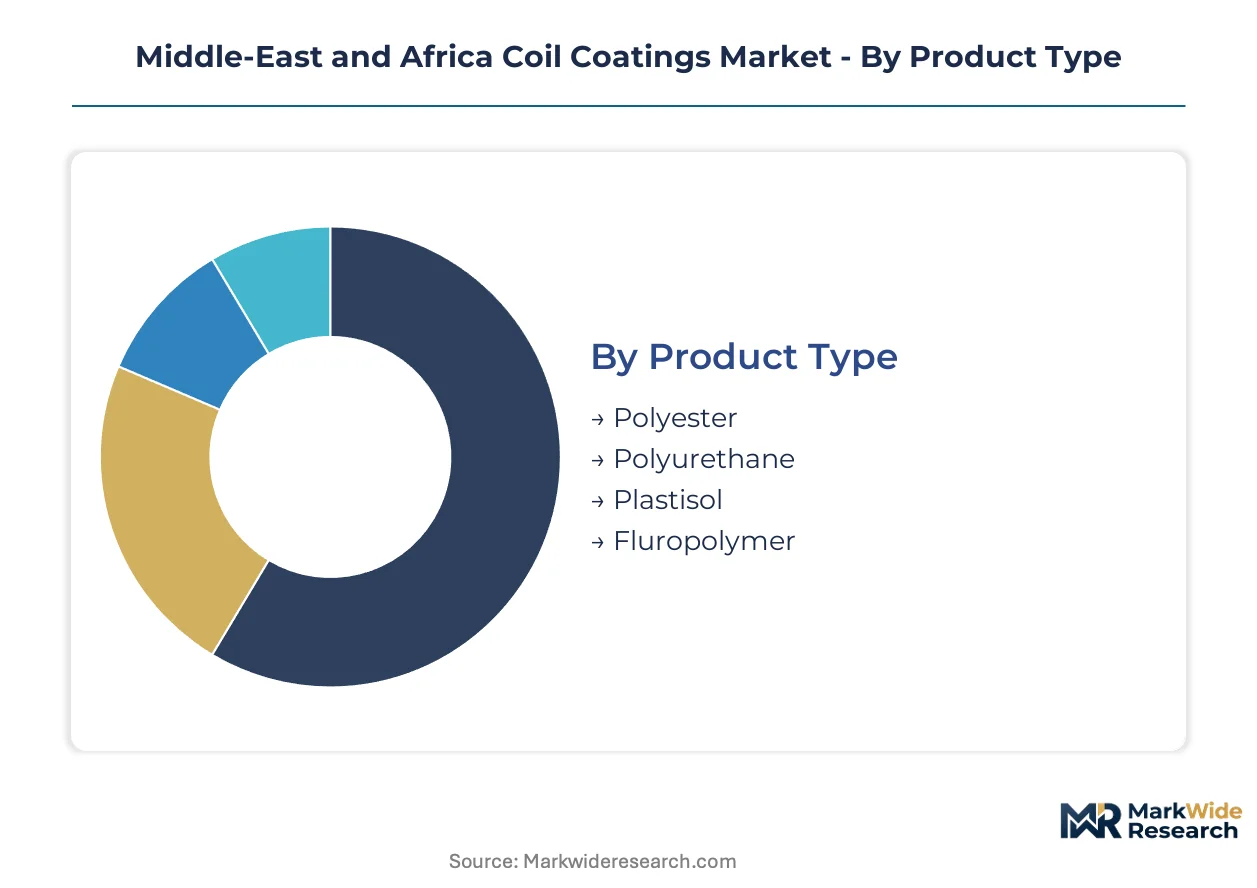
Coil coatings flow through distinct procurement channels based on performance tier and end-use criticality. Specification committees in Saudi megaprojects and South African coastal developments segment demand by durability warranty and climate exposure rather than commodity chemistry alone.
Product Type:
Polyester formulations move through high-volume distributor channels serving regional metal fabricators, while fluoropolymer specifications route through direct manufacturer relationships with master developers.
- Polyester:Saturated and super-polyester formulations deliver 20-25 micrometer coating weights with balanced UV resistance and cost efficiency. Demand concentrates in Saudi Arabia's Riyadh-Jeddah corridor where mid-rise commercial developments specify fifteen-year warranty tiers. SFDA low-VOC mandates are forcing reformulation of traditional solvent-borne polyesters without degrading tropical weathering performance.
- Fluoropolymer:PVDF and FEVE resin-based systems achieve fifty-year durability warranties through superior chalk resistance and color retention. Gulf Cooperation Council megaproject procurement channels specify these tiers for high-rise curtain walls and signature architectural envelopes where lifecycle cost calculations dominate initial material outlays.
- Polyurethane:Flexible film-forming characteristics serve HVAC equipment manufacturers requiring impact resistance and chemical tolerance in coil-coated aluminum fins.
- Plastisol:Thick-film PVC-based coatings provide deep-draw formability for appliance panels and interior metal components with soft-touch aesthetic requirements.
Polyester dominates installed base across volume construction applications. Fluoropolymer is where expansion concentrates as Gulf developers consolidate specifications toward performance-guaranteed building envelopes.
End Use Industry:
Cost tier stratification separates specification-grade architectural procurement from commodity appliance and automotive volume applications.
- Construction:Pre-coated metal cladding procurement is intensifying across Gulf Cooperation Council states as developers compress on-site labor schedules. Saudi Arabia's Neom and Red Sea Project developments enforce approved product lists that displace project-by-project competitive bidding. Specification committees in Abu Dhabi and Sharjah now reject uncertified European imports lacking Gulf-specific accelerated UV exposure documentation.
- HVAC:Coil-coated aluminum fins for heat exchangers demand polyurethane flexibility and chemical resistance to withstand refrigerant exposure and thermal cycling. South African coastal specifications under SANS standards require enhanced salt-spray resistance for Durban and Cape Town installations.
- Automotive:Decorative trim and under-hood applications specify thin-gauge coated steel with precise color matching to assembly plant requirements.
- Appliances:Refrigerator panels and washing machine cabinets utilize plastisol and polyester formulations where scratch resistance and household chemical tolerance outweigh exterior weathering demands.
Construction commands specification premium pools. HVAC is climbing the fastest as regional climate control infrastructure expands.
Application:
Geography within the title scope determines performance tier selection more than end-use category alone.
- Exterior:Building envelope surfaces in desert climates face extreme thermal cycling, sand abrasion, and UV flux that outpace standard ASTM weathering protocols. Photocatalytic self-cleaning topcoats incorporating titanium dioxide nanoparticles are miniaturizing maintenance intervals for Dubai and Riyadh high-rise curtain walls.
- Interior:Controlled environment applications prioritize aesthetic consistency and formability over weathering resistance, channeling demand through appliance and automotive OEM procurement systems.
- Electrical Housing:Transformer and switchgear enclosures require dielectric properties and corrosion protection in coastal humidity zones.
- Metal Components:General industrial fabrication serves maintenance and repair channels with shorter lead time requirements than megaproject specification cycles.
Exterior applications concentrate margin capture. Interior is where volume scale accumulates through appliance and automotive OEM contracts.
Technology:
Supply concentration among continuous coil line operators favors thermoset curing infrastructure over emerging zero-VOC alternatives.
- Thermoset:Cross-linked polyester and fluoropolymer chemistries cured at 200-250°C dominate architectural duty cycles. Regional investment in dedicated coil coating capacity requires long-term offtake commitments from megaproject developers with compressed decision timelines.
- Roller Coating:Precision metered deposition achieves uniform 20-25 micrometer films across continuous metal strips at speeds exceeding 100 meters per minute. Advances in thermal curing efficiency and chemical pretreatment automation are expanding viable substrate ranges to include thinner-gauge aluminum.
- Thermoplastic:Plastisol and powder formulations offer re-workability and lower cure temperatures for heat-sensitive substrates.
- Electrostatic Spraying:Powder coating convergence is penetrating architectural segments previously reserved for liquid fluoropolymers as zero-VOC formulations meet flexibility requirements.
Thermoset roller coating dominates installed production capacity. Electrostatic spraying powder systems are gaining share fastest as UAE MOHAP-GSO harmonization tightens emission standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coil coating supply chains concentrate in Saudi Arabia and UAE manufacturing corridors, with specification authority migrating toward megaproject master developers. Regional demand splits between Gulf Cooperation Council architectural procurement and South African industrial maintenance channels.
Saudi Arabia
Riyadh-Jeddah megaproject corridors drive fluoropolymer specification upgrades as Neom and Red Sea Project developers enforce approved product lists. SFDA volatile organic compound emission limits are compressing polyester formulation margins without degrading fifty-year warranty performance. Eastern Province industrial zones anchor continuous coil line investment requiring long-term offtake commitments.
United Arab Emirates
Dubai high-rise curtain wall procurement specifies photocatalytic self-cleaning topcoats to reduce facade maintenance frequency in dust-intensive environments. MOHAP alignment with Gulf Standardization Organization weathering performance testing disqualifies uncertified European imports lacking accelerated UV exposure documentation. Abu Dhabi and Sharjah specification committees now require in-country validation partnerships.
South Africa
Durban and Cape Town coastal zones generate demand for specialized primer-topcoat systems under SANS standard enforcement for metal roofing corrosion protection. National Regulator for Compulsory Specifications mandates salt-spray resistance documentation for installations within five kilometers of shoreline. Johannesburg industrial corridors serve inland HVAC and appliance manufacturing with polyurethane flexibility requirements.
Qatar
World Cup legacy infrastructure maintenance creates specification windows for high-durability architectural coatings in Doha commercial districts. Qatar General Organization for Standardization building material regulations align with Gulf Standardization Organization frameworks streamlining multi-country product registration. Lusail development zones concentrate pre-coated metal cladding procurement for hospitality and retail portfolios.
Egypt
New Administrative Capital construction generates demand for cost-optimized polyester tiers in mid-rise commercial developments. Egyptian Organization for Standardization and Quality building codes are converging toward Gulf Cooperation Council weathering performance benchmarks. Cairo-Alexandria corridor metal fabricators upgrade continuous line capacity to serve North African export markets.
Middle-East and Africa Coil Coatings Market Competitive Landscape
Concentration sits with integrated multinational coating manufacturers and regional metal substrate suppliers. The vendor base separates into three tiers: global formulation specialists with regional manufacturing footprints, steel and aluminum producers with captive coating lines, and independent coil coaters serving maintenance channels. Strategic moves center on capacity expansion in Saudi Arabia and UAE megaproject corridors alongside formulation portfolio re-engineering for low-VOC compliance.
Within the multinational formulation tier, AkzoNobel N.V. and PPG Industries, Inc. exemplify supply chain anchoring through regional technical service infrastructure. Beckers Group occupies a position among specialized color-matching providers addressing desert-climate ultraviolet resistance requirements. Among substrate-integrated suppliers, Alcoa Corporation and Norsk Hydro ASA represent aluminum rolling mill operators with coating capability adjacencies.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Alcoa Corporation |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Tata Steel |
| Axalta Coating Systems |
| Norsk Hydro ASA |
| Beckers Group |
| Kansai Paint Co., Ltd. |
| Others |
Supply & Pricing Matrix
SFDA volatile organic compound emission standards gate both supply qualification and price differentiation across Middle-East and Africa coil coatings procurement. Manufacturers must reformulate polyester and fluoropolymer chemistries to maintain fifty-year warranty performance while absorbing compliance costs that compress margin pools.
Pricing Analysis
SFDA low-VOC mandates dictate the pricing tier structure across Saudi Arabia's megaproject corridors. Three-tier pricing stratifies across premium fluoropolymer, standard super-polyester, and economy-grade polyester levels. Price differentiation hinges on certification grade for Gulf Standardization Organization weathering performance and volume scale from master developer portfolios. Cost compression in mid-tier polyester formulations is intensifying because titanium dioxide feedstock volatility squeezes import-dependent manufacturers. Regional metal fabricators exhibit highest price sensitivity, while Neom and Red Sea Project master developers prioritize lifecycle cost over initial material outlays.
Supply Chain Analysis
Saudi Arabia and the United Arab Emirates anchor continuous coil line manufacturing across the Middle-East and Africa region. Raw material dependencies draw from Chinese titanium dioxide pigment suppliers, European fluoropolymer resin producers, and regional aluminum rolling mills. Single-source vulnerability concentrates in PVDF and FEVE resin supply among limited global manufacturers. Distribution runs through direct manufacturer relationships with master developers for fluoropolymer tiers and regional distributor networks serving metal fabricator channels for polyester volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise capable of balancing low-VOC compliance with desert UV stability represents the critical capability gap constraining regional supply expansion. Technical talent scarcity among Gulf-based chemists limits formulation portfolio re-engineering speed.
For Market Incumbents: Secure long-term offtake commitments from Saudi megaproject developers before committing capital to dedicated coil line capacity additions. Defend margin position by backward integration into titanium dioxide pigment sourcing through regional distribution partnerships. Channel control through approved product list placement in Neom and Red Sea Project developments creates switching costs for specification committees. For New Entrants and Emerging Players: Technical service gaps in color-matching for desert-climate UV resistance requirements present white-space opportunities. South African coastal corrosion protection under SANS standards offers the most penetrable segment given specialized primer-topcoat demand. Establish in-country testing partnerships with UAE MOHAP-recognized laboratories to validate Gulf-specific accelerated UV exposure documentation as a go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous coil line infrastructure as megaproject developers compress decision timelines. Long-term viability over the next decade favors substrate-integrated suppliers with captive aluminum rolling capacity. Acquisition target archetypes include independent coil coaters with SANS certification credentials and established distributor relationships. Watch for SFDA enforcement intensity as the signal indicating margin compression versus specification upgrade inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Saudi Eastern Province coil line investments require Neom offtake commitments to justify capital deployment. |
| Backward Integration | Regional manufacturers source titanium dioxide through Middle Eastern distribution hubs to reduce import dependency. |
| Green Manufacturing Transition | Zero-VOC powder formulations penetrate architectural segments previously reserved for liquid fluoropolymers. |
| Long-term Supply Agreement | Master developers consolidate coating specifications across multi-tower portfolios to capture volume pricing. |
| Joint Venture | In-country testing partnerships with UAE MOHAP-recognized laboratories validate Gulf-specific climate resilience. |
Research Methodology
Desk research of customs trade data, Gulf Standardization Organization certification registries, and Saudi SFDA regulatory filings preceded structured interviews with coil coating plant managers, megaproject procurement leads, and technical R&D directors at multinational formulation manufacturers. Primary fieldwork with metal fabricators and master developer specification committees combined with secondary validation from SEC filings and regional building material trade associations. Bottom-up volume modeling across product tiers triangulated against top-down construction spending projections.
Variance decomposition across the projection horizon isolates price, volume, and mix effects by segmentation dimension. The analytical framework models resin chemistry tier, end-use industry, application exposure class, and regional regulatory cluster throughout the forecast period. CAGRs derive from regression-based trajectory fitting against historical megaproject completion patterns and SFDA enforcement intensity assumptions. Industry-specific inputs include titanium dioxide pigment price indices and continuous coil line capacity utilization surveys.
Material uncertainties — SFDA regulatory enforcement timing, fluoropolymer resin allocation disruptions, and megaproject developer insolvency events — sit outside the modeled envelope. Forecasts reflect assumptions around Gulf Cooperation Council harmonization pace and coastal corrosion standard adoption in South Africa. Recalibration cycles align with material shifts in SFDA emission limit revisions and master developer procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Antifouling Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Silicone Coating Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Marking Coatings Market
Coatings
BPA-Free Coatings Market
Coatings
US Protective Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market