
 Self-Healing Microcapsule Systems for Protective Coatings Market | 2026-2036
Self-Healing Microcapsule Systems for Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Microcapsule Systems for Protective Coatings Market Insights
Modular coating kits that pair microencapsulated healing agents with standard resin bases is broadening buyer choice across maintenance and OEM procurement channels. BASF leverages its polymer science depth to sustain formulation leadership in polymeric microcapsule architectures. Evonik Industries anchors European supply through specialized silica-shell encapsulation competencies. Autonomic Materials differentiates via dedicated R&D intensity in autonomic healing chemistry for military and industrial grades.
Self-healing microcapsule systems for protective coatings embed reactive agents—typically dicyclopentadiene, isocyanates, or epoxy resins—within 10–300 μm polymer or inorganic shells that rupture upon mechanical damage to release healing compounds and restore barrier integrity. Polymeric microcapsules dominate current volume due to processing compatibility with solvent and water-borne liquid coatings, while hybrid microcapsules capturing both organic flexibility and inorganic thermal resistance represent the fastest-growing configuration as aerospace and electronics assemblers specify wider operating temperature ranges. Anti-corrosion applications command the largest value share given lifecycle cost advantages in marine and infrastructure assets, whereas scratch resistance coatings for consumer electronics surfaces are emerging as a concentrated margin pool.
EPA oversight of volatile organic compound emissions shapes liquid coating formulation requirements in the United States, while REACH registration obligations in Europe constrain raw material selection and supplier qualification timelines for capsule shell chemistries. China's GB standards on industrial coating performance and the EU Green Deal's decarbonization benchmarks for construction materials are converging to favor water-borne and powder deployment formats with embedded healing functionality. Stakeholders must monitor regulatory divergence between jurisdictions on microcapsule additive classification to avoid reformulation costs that erode the technology's lifecycle economics.
Market Dynamics
Capsule shell chemistry standardization is fragmenting as REACH registration timelines force European formulators toward pre-qualified hybrid architectures while Asian manufacturers pursue alternative encapsulation pathways.
Growth Catalysts
- EU Green Deal decarbonization benchmarks:Construction material specifications now embed lifecycle durability requirements that favor autonomic repair functionality in structural coatings.
- Marine infrastructure lifecycle economics:Offshore asset operators in Germany specify capsule-based anti-corrosion systems to extend maintenance intervals on wind turbine foundations and port facilities.
- Hybrid microcapsule architectures:Aerospace assemblers demand wider operating temperature ranges that polymeric shells alone cannot satisfy.
Market Restraints
- Core-shell precursor cost volatility:Silica and melamine-formaldehyde feedstock prices fluctuate with energy markets, squeezing margin on inorganic-hybrid capsules.
- Healing agent supply concentration:Dicyclopentadiene and isocyanate production clusters in the US Gulf Coast and Rhine-Ruhr corridor create geographic vulnerability.
- Capsule-matrix compatibility limitations:Water-borne coating pH and shear conditions degrade urea-formaldehyde shell integrity during industrial mixing.
Strategic Opportunities
- India industrial OEM penetration:PLI scheme incentives for domestic manufacturing equipment create first-mover openings for localized capsule formulation partnerships.
- Consumer electronics scratch-resistance:Smartphone and wearable manufacturers specify sub-50 μm capsules for invisible surface repair on foldable displays.
- MEE enforcement of GB coating standards:China's tightened VOC limits accelerate water-borne format conversion compatible with microcapsule embedding.
Industry Challenges
- Encapsulation chemist talent scarcity:Industrial formulation teams lack personnel trained in interfacial polymerization and emulsion stabilization at production scale.
- REACH substance dossier compilation:Novel shell chemistries face 18-24 month registration timelines before commercial deployment in EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Microcapsule Systems for Protective Coatings Market |
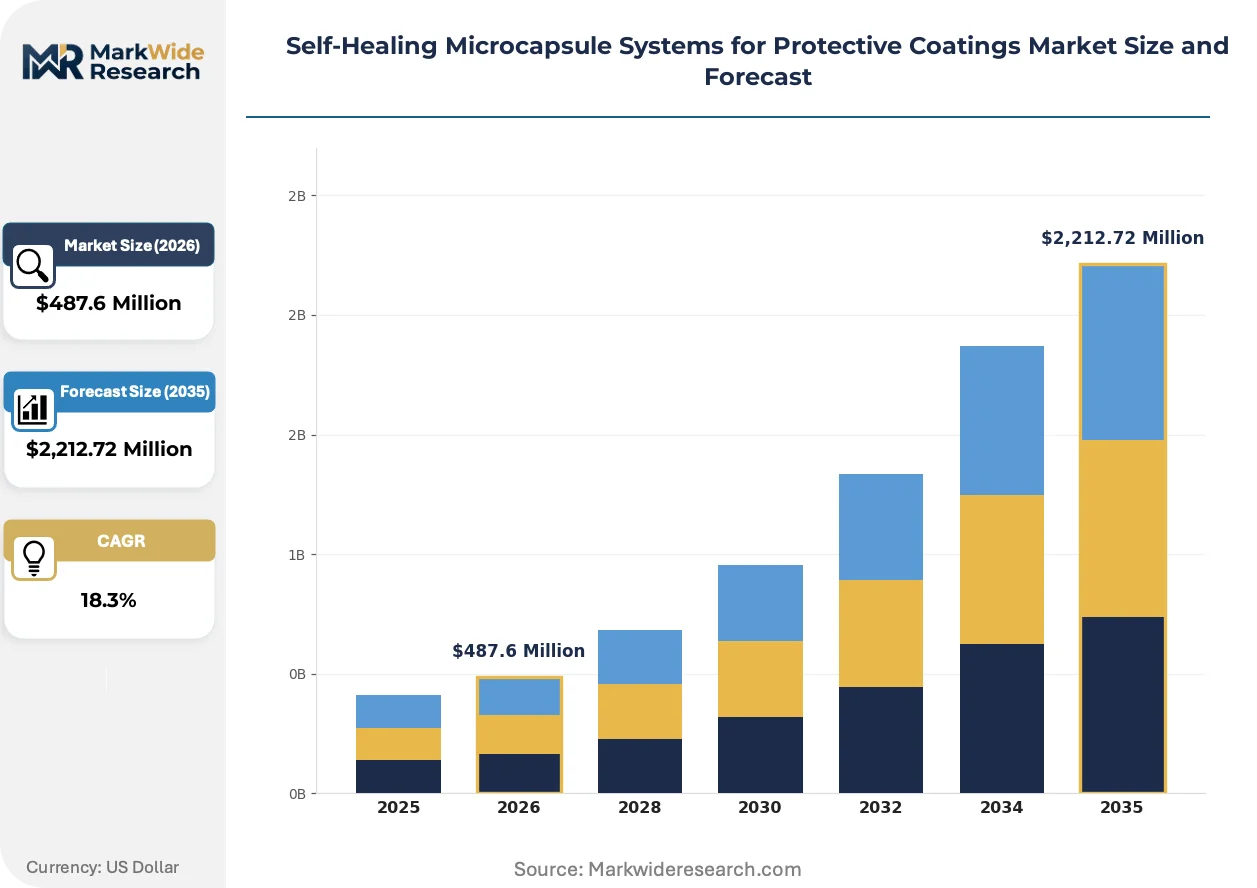
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,212.72 Million |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Microcapsules, Inorganic Microcapsules, Hybrid Microcapsules, Multi-Core Microcapsules Application: Anti-Corrosion, Scratch Resistance, UV Protection, Water Repellent, Chemical Resistance End User Industry: Marine Equipment Manufacturers, Aerospace Components, Construction Materials, Electronics Assemblers, Packaging Producers Deployment Format: Liquid Coatings, Powder Coatings, Spray Systems, Brush-Applied Coatings |
| Companies Covered | BASF, Evonik Industries, 3M, Dow, Henkel, AkzoNobel, Nouryon, Microtek Laboratories, Autonomic Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Microcapsule Systems for Protective Coatings Market Trends and Innovations
Formulation architectures are diverging toward application-specific capsule designs rather than universal healing systems, with processing compatibility now driving R&D allocation more than healing efficiency metrics alone.
Silica-polymer hybrid microcapsule construction is modularizing across aerospace and electronics coating lines. German automotive suppliers integrate these shells into powder coating bake cycles without thermal degradation. The technology is modularizing procurement by allowing buyers to specify shell composition independently from core healing chemistry.
REACH authorization requirements for certain isocyanate precursors are tightening substance evaluation protocols. Coating formulators must document safe-use scenarios across the capsule lifecycle from production to end-of-life coating removal. Marine and infrastructure contractors face extended qualification timelines as ECHA reviews accumulate, pushing demand toward pre-registered epoxy-based healing agents.
Maintenance procurement is consolidating under asset owner direct contracts rather than distributor intermediaries. German industrial OEMs and wind farm operators now source capsule-embedded coatings through technical specification teams rather than traditional paint resellers. This pattern concentrates most visibly in North Sea offshore installations where lifecycle cost modeling dominates supplier selection criteria.
Self-Healing Microcapsule Systems for Protective Coatings Market Segmentation
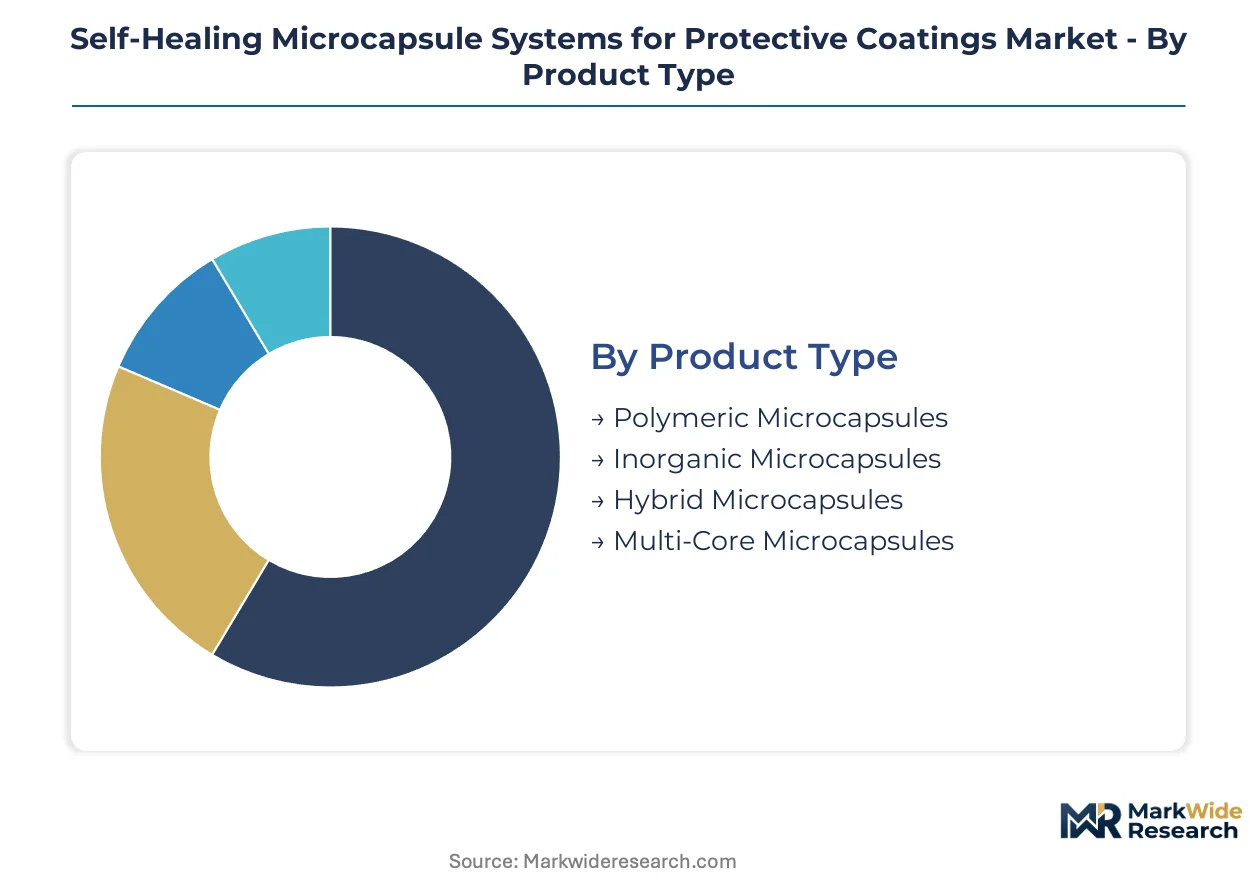
Segmentation in self-healing microcapsule systems reveals how shell chemistry and deployment constraints fragment procurement patterns across industrial buyers. Each dimension—product architecture, functional application, end-use sector, and coating format—carries distinct technical qualification requirements that reshape supplier selection criteria.
Product Type:
Supply concentration in polymeric shell production dominates current volume, while hybrid architectures attract specialized procurement from temperature-critical end-uses.
- Polymeric Microcapsules:Urea-formaldehyde and melamine-formaldehyde shells encapsulate dicyclopentadiene or epoxy healing agents with 10–300 μm diameter control. German automotive suppliers specify these for standard bake cycles in OEM coating lines where thermal exposure stays below 180°C. REACH registration timelines for novel shell chemistries reinforce buyer preference toward pre-qualified polymeric platforms.
- Hybrid Microcapsules:Silica-polymer composite shells combine organic flexibility with inorganic thermal resistance for aerospace specification. German wind turbine manufacturers and electronics assemblers drive procurement where operating ranges span -40°C to 250°C. ECHA substance dossier requirements for pure inorganic alternatives push formulators toward hybrid intermediates.
- Inorganic Microcapsules:Pure silica or ceramic shells serve extreme thermal environments in jet engine components.
- Multi-Core Microcapsules:Multiple healing agent reservoirs within single shells enable staged release for severe damage scenarios.
Today's leader: Polymeric Microcapsules. Tomorrow's challenger: Hybrid Microcapsules.
Application:
Cost tier differentiation separates high-volume infrastructure protection from premium electronics surface repair.
- Anti-Corrosion:Marine-grade capsules embed in offshore platform coatings where salt spray and cathodic protection cycles demand barrier restoration. German North Sea wind farm operators specify these systems to extend maintenance intervals on turbine foundations. Lifecycle cost modeling favors higher upfront capsule loading against repainting frequency.
- Scratch Resistance:Sub-50 μm capsules integrate into consumer electronics finishes where foldable display surfaces require invisible repair. Smartphone manufacturers in Asia-Pacific drive specification for ultra-thin capsule architectures that maintain optical clarity.
- UV Protection:Photostabilizer-loaded capsules release under UV-induced microcracking in exterior architectural coatings.
- Water Repellent:Hydrophobic healing agents restore superhydrophobicity in self-cleaning facade systems.
- Chemical Resistance:Solvent-resistant shell chemistries protect industrial tank linings from acid and alkali exposure.
Anti-Corrosion commands infrastructure procurement volume. Scratch Resistance captures the steepest expansion trajectory in consumer electronics margins.
End User Industry:
Customer type fragmentation concentrates specification authority among asset owners with direct lifecycle cost accountability.
- Marine Equipment Manufacturers:Shipbuilders and offshore fabricators integrate capsule systems into ballast tank and deck coatings. German port authorities specify these for quay infrastructure where maintenance access is restricted.
- Aerospace Components:Tier-1 suppliers embed hybrids into engine nacelle and landing gear coatings. FAA airworthiness qualification timelines extend procurement cycles to 24–36 months.
- Construction Materials:Precast concrete and structural steel coaters specify autonomic repair for bridge and tunnel assets.
- Electronics Assemblers:Wearable and foldable device manufacturers drive sub-50 μm capsule demand for surface integrity.
- Packaging Producers:Barrier coating applications in food and pharmaceutical packaging explore capsule-based pinhole repair.
Marine Equipment Manufacturers anchor current procurement volume. Electronics Assemblers reshape specification priorities toward micro-scale architectures.
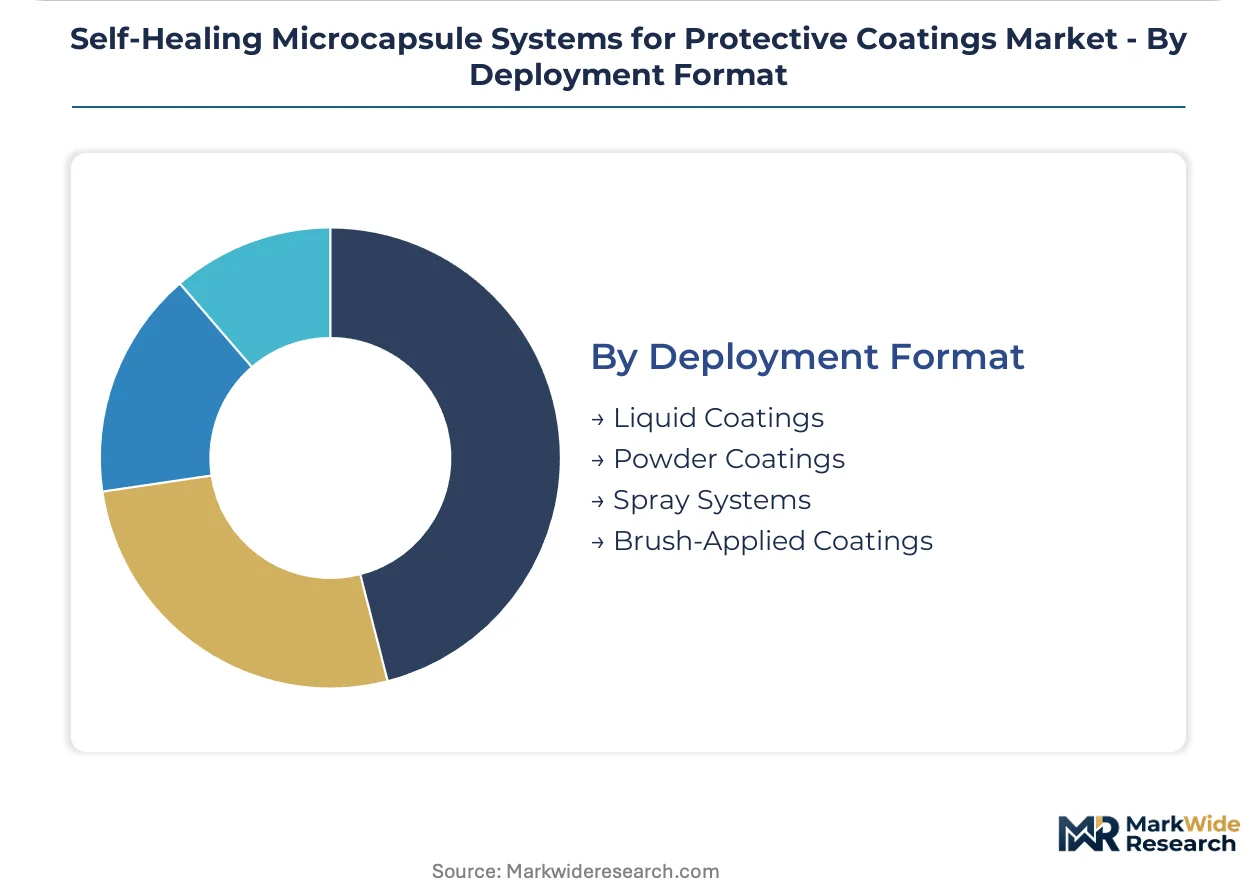
Deployment Format:
Maturity gradients separate established liquid coating integration from emerging powder and spray system compatibility.
- Liquid Coatings:Solvent-borne and water-borne formats dominate current embedding practice. EPA VOC regulations and China's GB standards constrain solvent systems while water-borne pH and shear conditions challenge urea-formaldehyde shell stability.
- Powder Coatings:Electrostatic spray and fluidized bed application requires thermal stability through 180–200°C cure cycles. German automotive suppliers qualify hybrid capsules for powder lines to eliminate solvent handling.
- Spray Systems:High-pressure airless and HVLP equipment demands capsule shear resistance during atomization.
- Brush-Applied Coatings:Manual touch-up and maintenance applications tolerate larger capsule diameters with lower dispersion requirements.
Liquid Coatings retain formulation familiarity. Powder Coatings gain share fastest as VOC regulations tighten across manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The self-healing microcapsule coatings industry traces its commercial roots to German polymer science laboratories and automotive OEM qualification programs, with subsequent scaling across North American aerospace clusters and East Asian electronics manufacturing corridors.
Germany
Industrial OEMs in Baden-Württemberg and North Rhine-Westphalia specify capsule-embedded powder coatings for automotive underbody protection and wind turbine foundations. REACH registration timelines from ECHA constrain novel shell chemistry deployment, pushing formulators toward pre-qualified urea-formaldehyde platforms. The Rhine-Ruhr corridor hosts concentrated production of dicyclopentadiene healing agents serving marine and infrastructure contractors.
United States
Aerospace assemblers in the Pacific Northwest and Southeast specify hybrid microcapsules for engine nacelle coatings requiring FAA airworthiness qualification. EPA oversight of VOC emissions shapes liquid coating formulation requirements, favoring water-borne formats compatible with polymeric shell architectures. The US Gulf Coast anchors isocyanate precursor production, creating geographic concentration risk for healing agent supply.
China
Electronics manufacturers in the Yangtze River Delta and Pearl River Delta drive sub-50 μm capsule demand for foldable display surface protection. MEE enforcement of GB coating standards accelerates water-borne format conversion, challenging urea-formaldehyde shell stability under alkaline pH conditions. Shenzhen-based assemblers specify ultra-thin capsule architectures for smartphone invisible repair functionality.
Japan
Automotive suppliers in the Chubu region around Nagoya integrate microcapsule systems into OEM coating lines for scratch-resistant finishes. METI industrial standards on coating durability favor autonomic repair functionality in high-value equipment protection. Kansai-based chemical formulators develop hybrid shell chemistries for electronics and precision machinery applications.
India
Industrial equipment manufacturers in Maharashtra and Gujarat explore capsule-based protection under PLI scheme incentives for domestic manufacturing. BIS standards on industrial coating performance create qualification pathways for imported formulation technologies. Tamil Nadu automotive clusters represent emerging demand for powder coating-compatible microcapsule systems.
Self-Healing Microcapsule Systems for Protective Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across shell chemistry specialization and healing agent formulation depth. The vendor base stratifies between integrated chemical conglomerates with captive polymer science capabilities and specialized encapsulation technology developers. Three archetypes dominate: diversified materials conglomerates leveraging formulation breadth, dedicated microcapsule technology specialists, and regional coating formulators sourcing capsule additives. Competitive moves concentrate on hybrid architecture patent filings and direct procurement relationships with asset-owning end-users.
Within the diversified chemical tier, BASF and Evonik Industries occupy positions anchored in European polymer and materials science depth. Autonomic Materials exemplifies the specialized technology developer archetype, with its name signaling dedicated focus on autonomic healing chemistry. These three entities represent distinct strategic postures: integrated formulation leadership, specialized encapsulation competency, and dedicated R&D intensity respectively.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| 3M |
| Dow |
| Henkel |
| AkzoNobel |
| Nouryon |
| Microtek Laboratories |
| Autonomic Materials |
| Others |
Pricing and Supply Chain Analysis
Encapsulation chemist concentration in the Rhine-Ruhr corridor and Baden-Württemberg region anchors labor-cost differentials that widen pricing-tier spreads between standardized polymeric capsules and specialized hybrid architectures. German formulators command premium positioning for REACH-registered shell chemistries while Asian manufacturers compete on cost through alternative urea-formaldehyde pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume commitment. Premium tiers capture aerospace and marine contractors requiring ECHA-registered hybrid capsules with documented safe-use scenarios, while economy tiers serve maintenance brush-applied coatings with larger diameter polymeric shells. Price differentiation stems from REACH dossier completion status and thermal stability specifications. Cost compression in the standard tier is intensifying because melamine-formaldehyde feedstock prices fluctuate with energy markets. Marine infrastructure contractors exhibit highest price sensitivity due to lifecycle cost modeling pressures, whereas electronics assemblers prioritize optical clarity over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or degraded capsule formulations remain underdeveloped, creating end-of-life coating removal cost burdens that asset owners increasingly internalize. Raw material production clusters in Germany, the United States, and China shape geographic supply concentration for dicyclopentadiene and isocyanate healing agents. Silica shell precursors draw from specialty chemical producers in the Rhine-Ruhr corridor and US Gulf Coast. Single-source vulnerability in isocyanate supply from the Rhine-Ruhr corridor creates geographic concentration risk. Distribution runs through technical specification teams at asset-owning end-users rather than traditional paint reseller channels, concentrating procurement authority under direct maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on powder coating format conversion eliminating solvent-handling costs and hybrid architecture premiums capturing aerospace specification authority.
For Market Incumbents: Deepen backward integration into dicyclopentadiene production to offset Rhine-Ruhr supply concentration risk and anchor cost positions against Asian urea-formaldehyde competitors. Invest in ECHA pre-registration of novel shell chemistries to compress 18-24 month authorization timelines that delay revenue recognition. Prioritize powder coating bake cycle compatibility to capture German automotive supplier procurement shifting from liquid formats. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for domestic manufacturing equipment, where localized capsule formulation partnerships face limited incumbent penetration. Target sub-50 μm architectures for foldable display surface protection in China's Yangtze River Delta electronics clusters, the most penetrable segment given specification fluidity and rapid product refresh cycles. Pursue direct technical specification relationships with wind farm operators rather than distributor intermediaries. For Investors and Strategic Acquirers: Chemical conglomerates with captive polymer science capabilities are the most active acquirer in this space, seeking hybrid architecture patent portfolios to complement formulation breadth. Long-term viability hinges on water-borne format compatibility as VOC regulations tighten across manufacturing geographies. Monitor ECHA substance dossier accumulation rates as an inflection indicator for pre-registered platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Healing Agent Production | Rhine-Ruhr dicyclopentadiene concentration creates supply security premiums for captive producers. |
| REACH Pre-Registration Investment | ECHA authorization timelines compress competitive windows for novel shell chemistries. |
| Powder Coating Format Qualification | German automotive bake cycles at 180-200°C demand thermal stability certification. |
| Direct Procurement Relationship Development | North Sea wind farm operators consolidate specification authority under asset owner contracts. |
| Hybrid Architecture Patent Filing | Silica-polymer composites capture aerospace temperature range specifications. |
Research Methodology
Coverage spans Germany, the United States, China, and Japan, with primary inputs from each regional cluster combining interviews with encapsulation R&D directors, coating formulator procurement leads, marine maintenance contractors, and aerospace tier-1 supplier quality engineers. Secondary validation draws from ECHA substance dossier databases, EPA VOC regulatory filings, Chinese GB standard enforcement records, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across shell chemistry tiers.
Granularity-level modeling distinguishes polymeric, hybrid, inorganic, and multi-core architectures; anti-corrosion, scratch resistance, UV protection, and chemical resistance applications; marine, aerospace, construction, electronics, and packaging end-uses; plus liquid, powder, spray, and brush-applied deployment formats. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporate REACH registration timeline assumptions and water-borne format conversion elasticity under tightening VOC regulations.
Inputs from ECHA, EPA, and Chinese MEE regulatory databases were available through the study window; gaps in real-time capsule-matrix compatibility field performance data introduce uncertainty bands around water-borne pH stability assumptions. Forecasts reflect documented assumptions on hybrid architecture adoption curves and powder coating market share trajectories. Practitioners should monitor ECHA authorization queue lengths and German automotive supplier format conversion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electrocoat Market
Coatings
Anti Fog Coatings Market
Coatings
FBE Coatings Market
Coatings
Glazes Market
Coatings
Epoxy Powder Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Silicate Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Packaging Coatings Market