
 Middle-East and Africa Acrylic Adhesives Market | 2026-2036
Middle-East and Africa Acrylic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Acrylic Adhesives Market Foresight
Saudi Arabia's industrial capacity build-out is tilting regional supply dynamics toward localized acrylic adhesive production. Henkel AG & Co. KGaA leverages its regional formulation centers to serve construction bond-line applications across Riyadh and Jeddah megaprojects. Sika AG anchors its position through specialized concrete repair and waterproofing adhesive systems designed for Gulf climate extremes. Dow competes on manufacturing scale, operating regional resin supply chains that feed downstream adhesive blending operations.
Acrylic adhesives are thermoplastic or thermosetting polymers formulated from acrylic ester monomers, typically cured through free-radical polymerization to achieve bond strengths ranging from flexible tack to structural load-bearing capacity; these systems bond metals, composites, plastics, and ceramics across industrial assembly lines. Water-based acrylic formulations lead volume demand due to regulatory pressure on solvent emissions, while reactive two-part systems capture premium margin pools in automotive and electronics structural bonding. UV-curable technology represents the fastest-expanding segment, driven by electronics miniaturization and medical device assembly precision requirements across South African and UAE manufacturing hubs.
South Africa's Air Quality Act enforcement, Saudi Standards, Metrology and Quality Organization (SASO) technical regulations, and UAE's Emirates Authority for Standardization and Metrology (ESMA) product conformity schemes collectively tighten VOC thresholds and chemical registration requirements for imported adhesive formulations. These frameworks compel multinationals to reformulate region-specific product lines or establish local blending capacity to maintain market access. Stakeholders must monitor evolving Gulf harmonization standards and South African environmental enforcement intensity to align R&D portfolios with compliance trajectories.
Market Dynamics
Saudi Arabia's megaproject pipeline is compressing specification cycles for acrylic adhesive suppliers, forcing simultaneous localization of production capacity and reformulation for Gulf climate extremes.
Growth Catalysts
- Water-based formulation mandates:South Africa's Air Quality Act enforcement is redirecting procurement toward low-VOC acrylic systems in industrial coating and assembly applications.
- Modular construction:Saudi Arabia's bonded assembly demand in transport equipment and prefabricated building modules is pulling structural adhesive volumes.
- UV-curable precision bonding:Electronics manufacturers in UAE and South African medical device hubs are adopting rapid-cure acrylics for miniaturized component assembly.
Market Restraints
- Petrochemical feedstock volatility:Acrylic ester monomer costs fluctuate with regional naphtha and propylene supply disruptions.
- Import dependency concentration:Resin supply chains remain anchored to Asian bulk chemical producers, exposing blenders to freight and currency risk.
- Cure-rate limitations in extreme heat:Two-part reactive systems face pot-life compression above 45°C ambient temperatures common in Gulf summer conditions.
Strategic Opportunities
- Egyptian industrial zone expansion:Suez Canal Economic Zone manufacturing incentives are attracting adhesive blending investments to serve North African and Levantine markets.
- SASO conformity pre-certification:Early alignment with Saudi Standards, Metrology and Quality Organization technical regulations secures preferential positioning for government-tendered infrastructure projects.
- Digital inventory integration:Construction material distributors are adopting vendor-managed inventory systems that compress order-to-delivery cycles for project sites.
Industry Challenges
- Formulation chemist scarcity:Regional universities produce limited polymer science graduates capable of climate-adapted adhesive development.
- Multi-jurisdiction registration complexity:Separate chemical notification requirements under South Africa's Department of Forestry, Fisheries and Environment, SASO, and UAE's Emirates Authority for Standardization and Metrology extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Acrylic Adhesives Market |
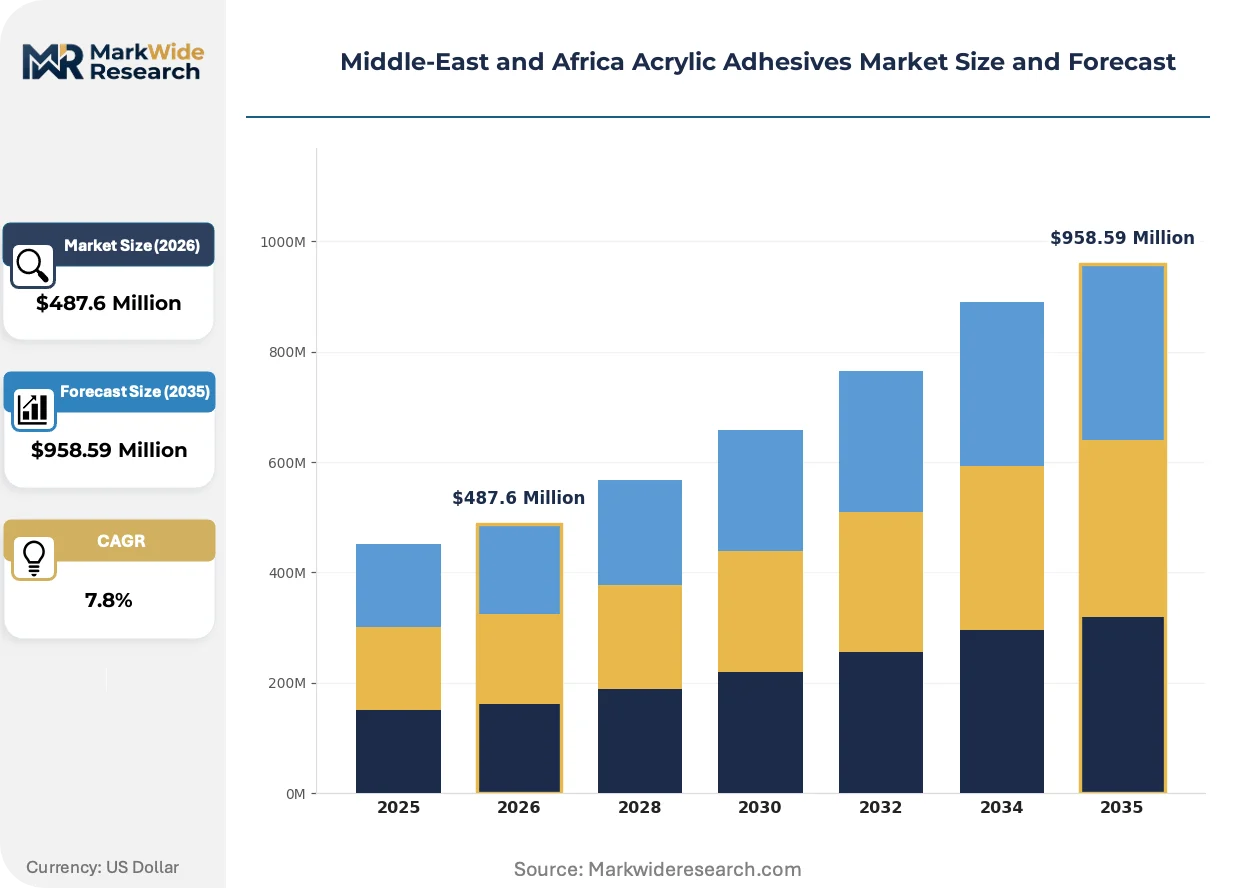
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $958.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Application: Automotive, Construction, Electronics, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Technology: UV-Curable, Thermal, Chemical, Pressure-Sensitive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller, Dow, Pidilite Industries Ltd., Avery Dennison Corporation, Huntsman International LLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Acrylic Adhesives Market Shifts & Advancements
Acrylic adhesive technology trajectories in this region center on curing speed acceleration, emissions compliance, and supply chain proximity to project execution sites.
UV-LED curable acrylic systems are collapsing the throughput constraints of conventional thermal or moisture-cure processes in electronics assembly lines. South African medical device manufacturers and UAE semiconductor packaging operations are adopting these systems to eliminate oven curing bottlenecks. The technology is collapsing capital equipment footprints and enabling cleanroom-compatible bonding stations with sub-5-second fixture times.
SASO technical regulations and South Africa's Air Quality Act amendments are tightening VOC thresholds in parallel, compelling multinationals to maintain parallel water-based and solvent-free formulation portfolios. Industrial consequence includes accelerated R&D spending on hybrid acrylic-urethane systems that retain structural performance while meeting emission limits. Construction sector procurement in Saudi Arabia and industrial coating buyers in South Africa are now screening suppliers on pre-certified compliance documentation.
Project-site direct delivery is displacing traditional distributor stockholding in Gulf construction supply chains. EPC contractors on Saudi megaprojects are negotiating frame agreements that bypass regional wholesalers, instead receiving adhesive shipments matched to construction phase schedules. This pattern concentrates most visibly in Riyadh and Jeddah infrastructure corridors where just-in-time bonded assembly materials reduce on-site inventory carrying costs.
Middle-East and Africa Acrylic Adhesives Market Segmentation
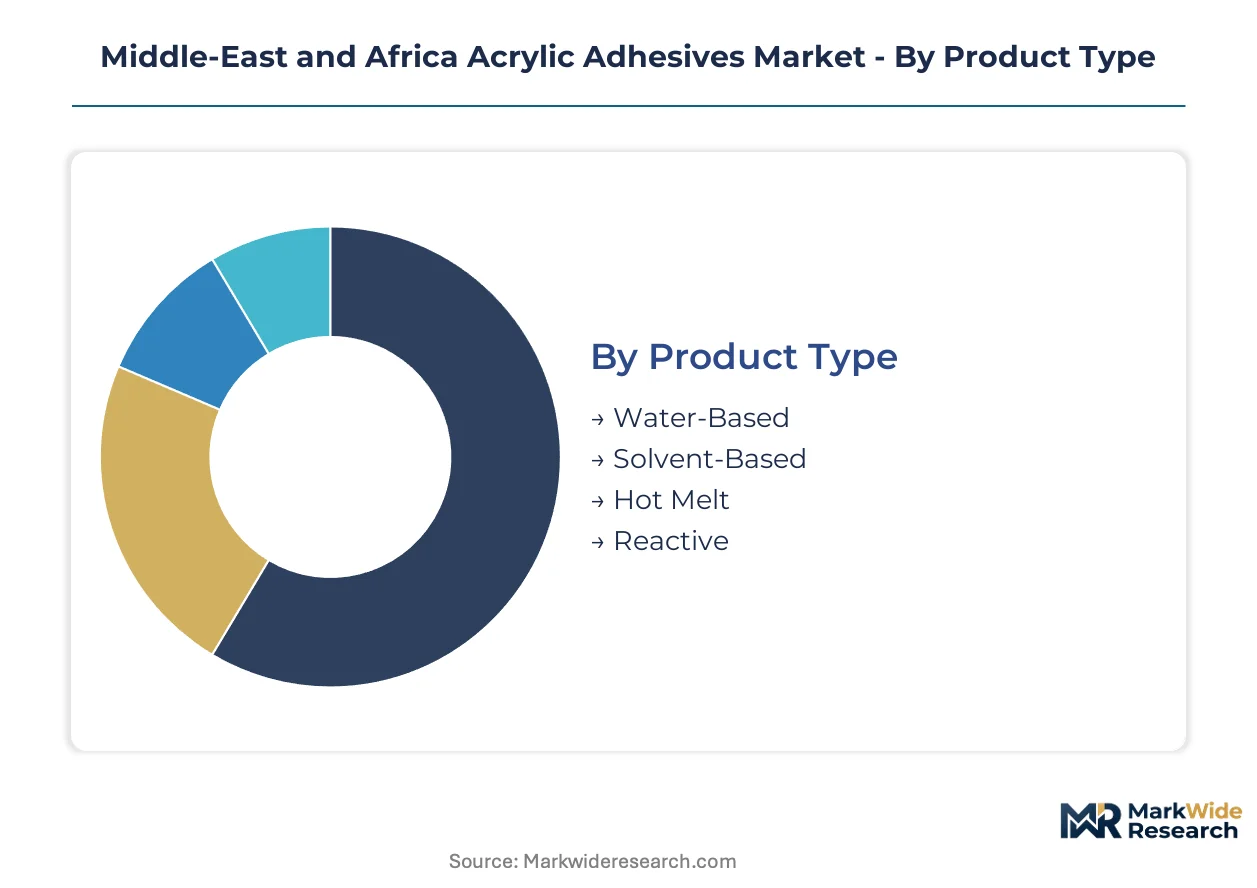
Acrylic adhesive procurement cycles vary dramatically across formulation chemistry and end-use intensity. Construction contractors in Saudi Arabia turn inventory monthly during megaproject peaks, while electronics manufacturers in UAE plan UV-curable resin purchases on quarterly semiconductor production schedules. Understanding these velocity differentials enables suppliers to align working capital deployment with demand patterns.
Product Type:
Water-based formulations rotate through distribution channels fastest due to regulatory pressure and construction seasonality, while reactive systems sit longest in specification pipelines before contract award.
- Water-Based:Emulsion polymers suspended in aqueous carriers cure through moisture evaporation, delivering bond strengths suitable for porous substrates. South African industrial coating operations under Air Quality Act enforcement are consolidating procurement around these systems to avoid VOC penalties. Saudi construction distributors report 30-day inventory turns during Riyadh infrastructure build-out phases.
- Solvent-Based:Solutions of acrylic polymers in organic carriers achieve rapid tack and high initial grab on non-porous surfaces. Demand concentrates in Egyptian automotive trim assembly where substrate compatibility trumps emission concerns. Formulators face reformulation deadlines as SASO technical regulations tighten aromatic solvent thresholds.
- Hot Melt:Thermoplastic blocks applied molten and set on cooling dominate packaging line integration for speed.
- Reactive:Two-part systems polymerizing through chemical reaction deliver structural load-bearing capacity for bonded assemblies.
Water-based systems anchor the volume base while UV-curable technology gains share at the steepest rate across electronics manufacturing hubs.
Application:
Margin profiles diverge sharply across end-use sectors, with electronics commanding formulation premiums and construction driving raw tonnage.
- Construction:Bonded assembly applications in modular building, concrete repair, and waterproofing consume acrylic adhesives by volume across GCC megaprojects. Saudi EPC contractors specify water-based and reactive systems for structural glazing and prefabricated module joining. Climate extremes in Gulf summers compress workable pot-life windows, forcing rapid-application formulation requirements.
- Electronics:Miniaturized component assembly in UAE semiconductor packaging and South African medical device manufacturing demands sub-5-second fixture times. UV-curable acrylics eliminate thermal curing bottlenecks, collapsing capital equipment footprints in cleanroom environments. Precision bonding specifications command 3-4x formulation premiums over construction grades.
- Automotive:Interior trim, badge attachment, and lightweight structural bonding in North African assembly plants.
- Packaging:High-speed carton sealing and label application across consumer goods manufacturing.
Construction absorbs the heaviest absolute volumes while electronics generates the highest per-kilogram margins and fastest technology refresh cycles.
End User:
Procurement sophistication scales with technical specification authority, separating formulation-specifying manufacturers from price-taking intermediaries.
- Manufacturers:OEMs and tier suppliers with in-house polymer science capabilities dictate adhesive specifications directly. South African medical device producers and UAE electronics assemblers maintain approved vendor lists with pre-qualified formulation portfolios. These buyers negotiate frame agreements compressing order-to-delivery cycles through vendor-managed inventory systems.
- Contractors:Construction execution firms on Saudi megaprojects purchase through project-specific procurement portals. Bonded assembly material requirements tie to construction phase schedules, with just-in-time delivery bypassing traditional distributor stockholding. Technical support demands peak during specification and commissioning phases.
- Distributors:Regional chemical wholesalers carrying formulation inventories for spot market sales.
- Retailers:Consumer-facing channels for maintenance-repair-operations volumes in smaller packaging formats.
Manufacturers and contractors concentrate strategic account management investment while distributor relationships emphasize logistics efficiency and credit terms.
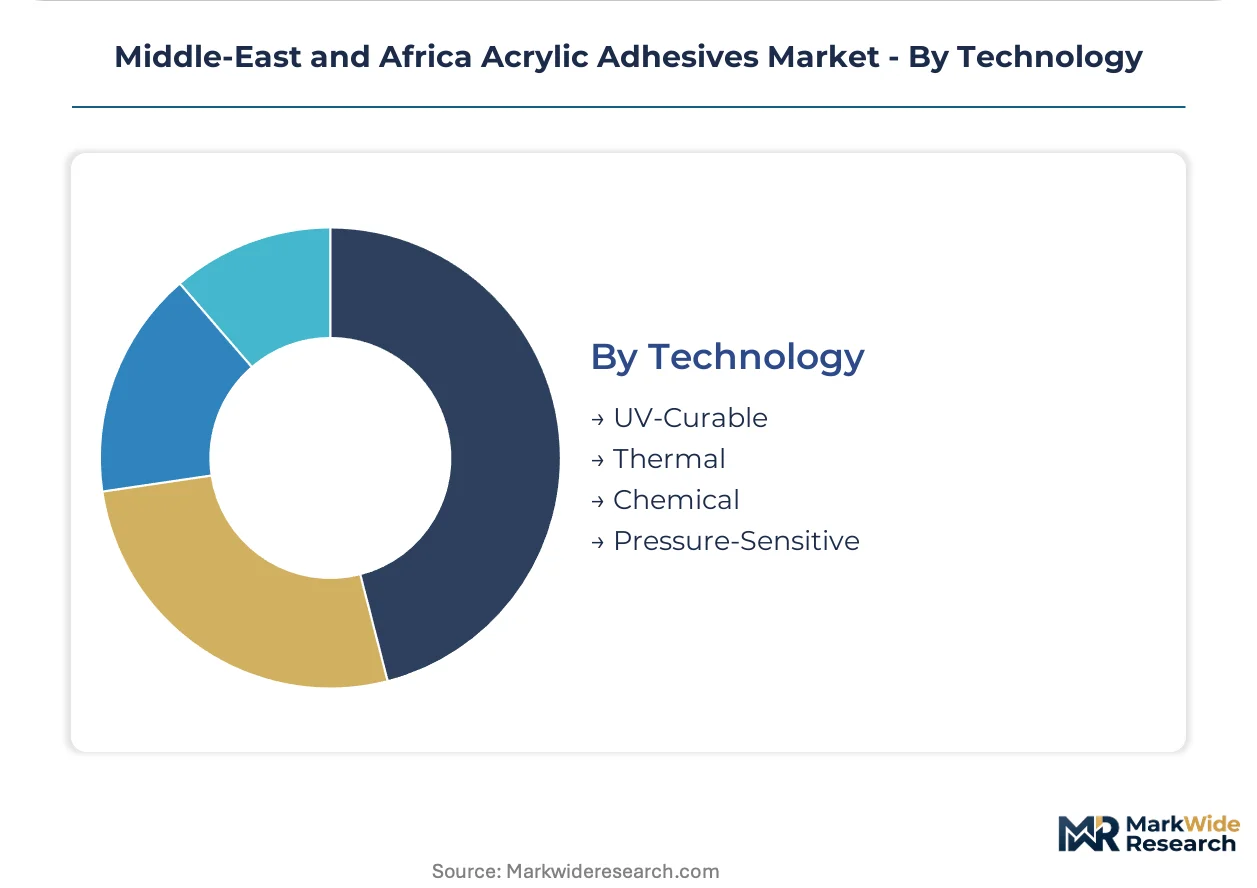
Technology:
Capital intensity and curing energy requirements create distinct competitive moats across technology platforms.
- UV-Curable:Photoinitiator-containing formulations polymerize on UV-LED exposure, delivering instant fixture without thermal stress. South African medical device cleanrooms and UAE semiconductor packaging operations are eliminating oven curing bottlenecks through adoption. Equipment retrofit costs create switching friction favoring incumbent suppliers with integrated dosing-curing system offerings.
- Pressure-Sensitive:Tack-retaining adhesives in tape and label formats serve high-volume packaging and logistics applications. Egyptian consumer goods manufacturing and Saudi retail distribution centers drive recurring demand for removable and permanent label stocks. Formulation differentiation centers on shear resistance and temperature performance.
- Thermal:Heat-activated curing systems requiring oven or induction equipment for bond development.
- Chemical:Moisture-cure or two-part reaction systems relying on ambient conditions or mixing ratios.
Pressure-sensitive technology holds the broadest installed base while UV-curable platforms expand most quickly in precision manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations anchor Saudi Arabia's procurement specifications, creating compliance templates that cascade across Gulf Cooperation Council markets and reshape formulation requirements throughout the broader region.
Saudi Arabia
Riyadh's megaproject pipeline and NEOM construction phases drive bonded assembly demand for modular building and transport equipment applications. SASO conformity pre-certification requirements compress supplier qualification timelines for government-tendered infrastructure. Eastern Province petrochemical complexes feed downstream adhesive blending operations with localized resin supply chains.
United Arab Emirates
ESMA product conformity schemes tighten VOC thresholds for imported adhesive formulations entering Dubai and Abu Dhabi manufacturing hubs. Semiconductor packaging operations in Dubai Silicon Oasis adopt UV-curable acrylics for miniaturized component assembly. Jebel Ali industrial zones concentrate electronics manufacturing demand for rapid-cure precision bonding systems.
South Africa
Gauteng province's medical device manufacturers and Western Cape industrial coating operations redirect procurement toward water-based acrylic systems under Air Quality Act enforcement. The Department of Forestry, Fisheries and Environment extends chemical notification timelines for reformulated low-VOC product lines. Durban automotive component plants maintain hybrid acrylic-urethane specifications for interior trim bonding.
Egypt
Suez Canal Economic Zone manufacturing incentives attract adhesive blending investments serving North African and Levantine construction markets. Cairo automotive assembly plants specify solvent-based systems for trim applications where substrate compatibility outweighs emission concerns. Alexandria industrial zones concentrate packaging line demand for hot melt pressure-sensitive adhesives.
Israel
Advanced electronics manufacturing in Tel Aviv and Haifa corridors drives specification authority for UV-LED curable acrylic systems in semiconductor packaging. Medical device cleanrooms in central Israel eliminate thermal curing bottlenecks through sub-5-second fixture technologies. National standards alignment with EU REACH frameworks simplifies multinational supplier qualification processes.
Middle-East and Africa Acrylic Adhesives Market Competitive Landscape
Capability concentration sits with specialized formulation developers; scale advantage sits with diversified chemical conglomerates. The vendor base stratifies across three tiers: multinational adhesive specialists with regional formulation centers, petrochemical majors leveraging captive resin supply, and regional blenders serving spot construction markets. Two competitive moves dominate: establishment of local blending capacity to satisfy SASO and ESMA conformity requirements, and portfolio diversification into UV-curable technologies for electronics assembly applications.
Within the multinational specialist tier, Henkel AG & Co. KGaA and Sika AG occupy positions anchored to construction sector procurement across Gulf megaprojects. Dow exemplifies the petrochemical-major archetype, with regional resin supply chains feeding downstream adhesive operations. Among Asia-Pacific-origin specialists, Pidilite Industries Ltd. represents the regional blender model adapted to Middle-East and Africa distribution networks.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller |
| Dow |
| Pidilite Industries Ltd. |
| Avery Dennison Corporation |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Jebel Ali port freight corridors from Asian resin producers concentrate supply-side leverage among Dubai-based distributors, compressing margins for Saudi construction contractors while creating price differentiation between Gulf-imported and Egypt-blended formulations.
Pricing Analysis
Price spreads between GCC and North African markets exceed formulation-grade differentials, with SASO-certified water-based systems commanding premiums over Egyptian spot-market solvent-based alternatives. Three-tier pricing structure across premium UV-curable, standard reactive, and economy water-based levels separates electronics manufacturers from construction contractors. Pricing pressure stems from petrochemical feedstock volatility as naphtha-linked acrylic ester costs fluctuate. Distributors serving spot construction markets exhibit highest price sensitivity, while medical device OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Upstream acrylic ester monomer production concentrates in Saudi Arabia's Eastern Province petrochemical complexes, South Korean bulk chemical exporters, and Chinese resin manufacturers. Formulators draw from naphtha-derived propylene, methyl methacrylate intermediates, and photoinitiator additives. Single-source vulnerability runs through Asian bulk chemical producers exposed to Red Sea shipping disruptions. Distribution runs through project-site direct delivery agreements bypassing traditional wholesaler stockholding for Saudi megaproject bonded assembly materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as Gulf megaproject construction phases accelerate bonded assembly material procurement.
For Market Incumbents: Build formulation IP moats around climate-adapted rapid-cure systems for Gulf summer conditions. Deepen backward integration into captive resin supply through Eastern Province petrochemical offtake agreements. Secure SASO pre-certification for government-tendered infrastructure to lock out reformulation-lagged competitors. For New Entrants and Emerging Players: Establish a beachhead in Egyptian automotive trim assembly where solvent-based specifications persist and import substitution incentives apply. Target Suez Canal Economic Zone blending capacity to serve North African construction markets with lower freight exposure. Lead with technical service capabilities to offset incumbent brand recognition in specification-driven segments. For Investors and Strategic Acquirers: Regional blenders with established ESMA conformity pathways and electronics-sector UV-curable portfolios represent the most defensible acquisition archetype. Long-term viability hinges on localization mandates tightening across GCC markets. Watch SASO technical regulation amendment timelines as inflection indicators for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Ester Production | Eastern Province resin supply chains reduce Asian import dependency for Gulf formulators. |
| SASO Conformity Pre-Certification | Government-tendered Saudi megaprojects require pre-qualified adhesive specifications for contract eligibility. |
| UV-Curable Technology Portfolio Expansion | UAE semiconductor packaging and South African medical device cleanrooms demand sub-5-second fixture systems. |
| Project-Site Direct Delivery Agreements | Saudi EPC contractors bypass distributor markups through just-in-time bonded assembly logistics. |
| Water-Based Formulation R&D Investment | South Africa's Air Quality Act enforcement redirects procurement toward low-VOC acrylic systems. |
Research Methodology
Desk research of customs trade databases, petrochemical industry association reports, and SASO technical regulation filings preceded structured interviews with adhesive formulation chemists, Saudi EPC contractor procurement managers, UAE electronics manufacturing engineers, South African industrial coating operations directors, and Egyptian automotive tier supplier quality leads. Primary field intelligence combined with secondary validation across SEC 10-K disclosures, regional chemical distributor financials, and construction project pipeline databases. Bottom-up segment sizing triangulated against top-down petrochemical feedstock consumption estimates.
Assumptions held fixed include current Gulf harmonization standards trajectory and South African environmental enforcement intensity; variables stress-tested encompass Red Sea shipping disruption duration and naphtha price volatility bands. Segmentation dimensions modeled span formulation chemistry, end-use intensity, curing technology, and regional regulatory cluster. CAGRs derived from adhesive tonnage consumption patterns indexed to construction project completion schedules and electronics manufacturing capacity expansion announcements.
Stress conditions across feedstock cost bands, freight rate spikes, and regulatory amendment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions; abrupt SASO standard acceleration or extended Suez Canal closure would revise trajectory. Cross-checking against regional petrochemical producer resin pricing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Electronics Adhesives Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Spray Glue Market