
 Middle-East and Africa Thermal Spray Market | 2026-2036
Middle-East and Africa Thermal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Thermal Spray Market Foresight
Demand from the oil and gas sector is shifting toward offshore platform maintenance and subsea pipeline protection across the Middle-East and Africa Thermal Spray Market. OC Oerlikon Management AG leverages its plasma spray technology leadership to anchor premium coating contracts in Abu Dhabi's energy hub. Linde plc sustains industrial gas supply integration that controls feedstock availability for HVOF operators in the region. Kennametal Inc specializes in tungsten carbide powder formulations that dominate wear-resistant applications for drilling equipment.
Middle-East and Africa thermal spray encompasses deposition processes where molten or semi-molten materials—typically metals, ceramics, or cermets—are propelled onto substrates at velocities exceeding 300 m/s to build protective layers ranging from 50 µm to several millimeters thick. These coatings primarily serve to extend component life in extreme environments involving erosion, corrosion, and thermal cycling. The technology dimension shows HVOF systems capturing margin-rich contracts due to their denser, lower-porosity outputs preferred for critical rotating equipment, while plasma spray retains scale advantages in thermal barrier coatings for gas turbines. Within end user industry segmentation, aerospace repair stations in the UAE and Saudi Arabia represent the fastest-growing demand pool as fleet expansion drives MRO capacity buildup.
Saudi Arabia's national standards body and South Africa's national regulator enforce coating qualification protocols that shape supplier certification requirements across the region. The UAE's civil aviation authority mandates OEM-approved thermal spray processes for engine component repairs, restricting market access to qualified applicators. Stakeholders must monitor how local content requirements in Gulf industrial policies reshape sourcing decisions for coating services and powder feedstock.
Market Dynamics
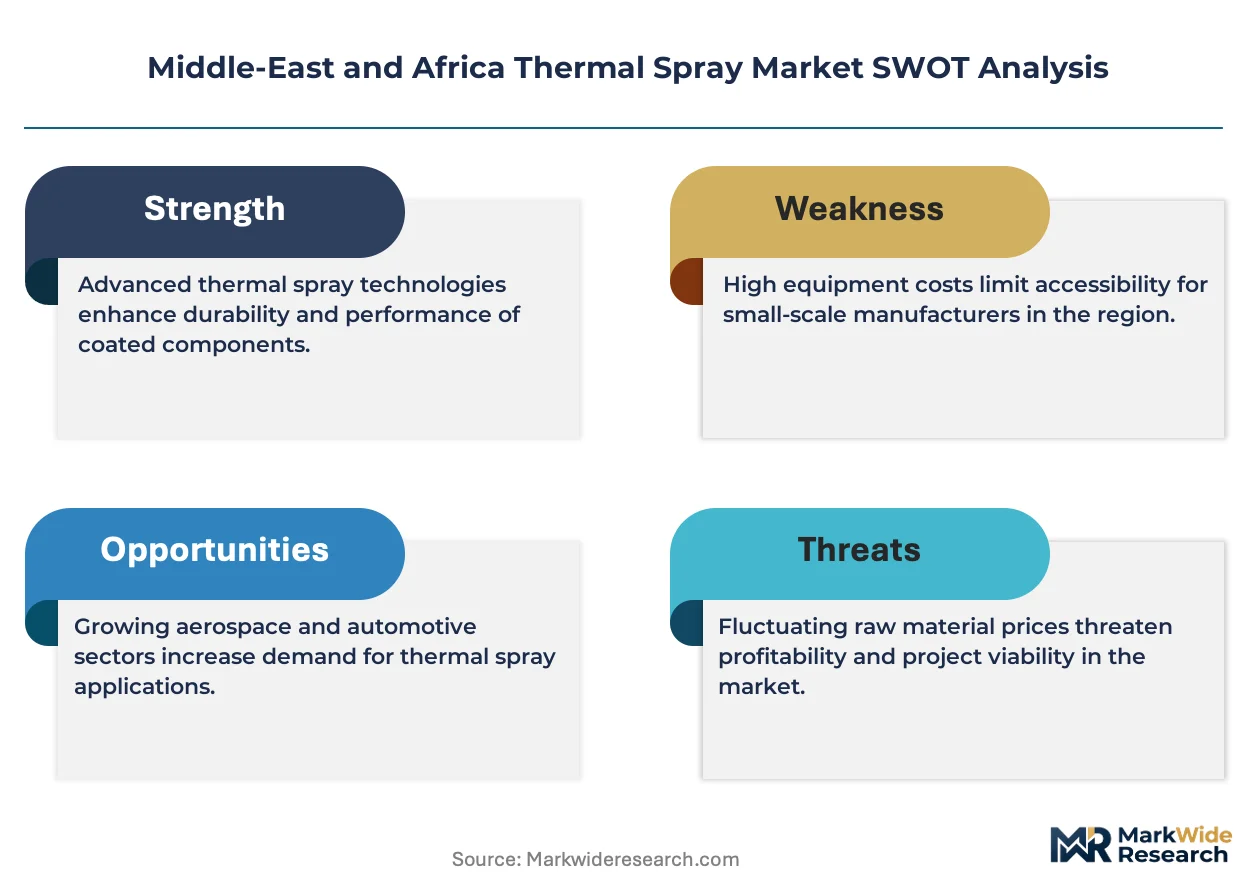
HVOF densification requirements from Saudi Arabia's SFDA and UAE's MOHAP are forcing applicators to upgrade equipment portfolios, compressing margins for mid-tier service providers while concentrating contract awards among certified specialists.
Growth Catalysts
- Vision 2030 Localization Mandates:Saudi Arabia's industrial policy requires hard-facing coatings for domestically manufactured oilfield equipment, redirecting procurement toward regional applicators.
- Plasma Spray Thermal Barrier Advancement:Ceramic topcoat deposition processes now achieve 1200°C surface protection, extending turbine blade overhaul intervals for Abu Dhabi MRO facilities.
- Wear-Resistant Cermet Formulations:Tungsten carbide-cobalt chrome composites dominate dragline bucket rebuild contracts across South Africa's platinum belt mining operations.
Market Restraints
- Feedstock Powder Volatility:Nickel and cobalt price swings destabilize coating job costing for Johannesburg-based HVOF operators serving the mining sector.
- Applicator Certification Bottlenecks:UAE civil aviation authority OEM-approval requirements restrict engine component repair contracts to under twelve qualified facilities across Dubai and Abu Dhabi.
- Laser Cladding Substitution:Directed energy deposition systems capture precision repair applications previously served by plasma spray in aerospace maintenance stations.
Strategic Opportunities
- Subsea Pipeline Protection Gap:Qatar and Kuwait offshore platform operators lack qualified thermal spray contractors for cathodic barrier coating deployment at depths exceeding 200 meters.
- Automated Spray Cell Integration:Robotic trajectory control combined with real-time particle temperature monitoring enables unmanned coating operations for Riyadh industrial manufacturing zones.
- SFDA Medical Device Coating Pathway:Saudi Arabia's pharmaceutical regulator is establishing approval frameworks for hydroxyapatite orthopedic implant surfaces, opening device manufacturer contracts.
Industry Challenges
- Certified Technician Scarcity:NACE coating inspector qualifications and ASME spray operator certifications face twelve-month training backlogs across UAE technical institutes.
- Multi-Layer Deposition Complexity:Bond coat-topcoat interface engineering for thermal barrier systems requires process control expertise that exceeds current workforce capabilities in African mining equipment rebuild shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Thermal Spray Market |
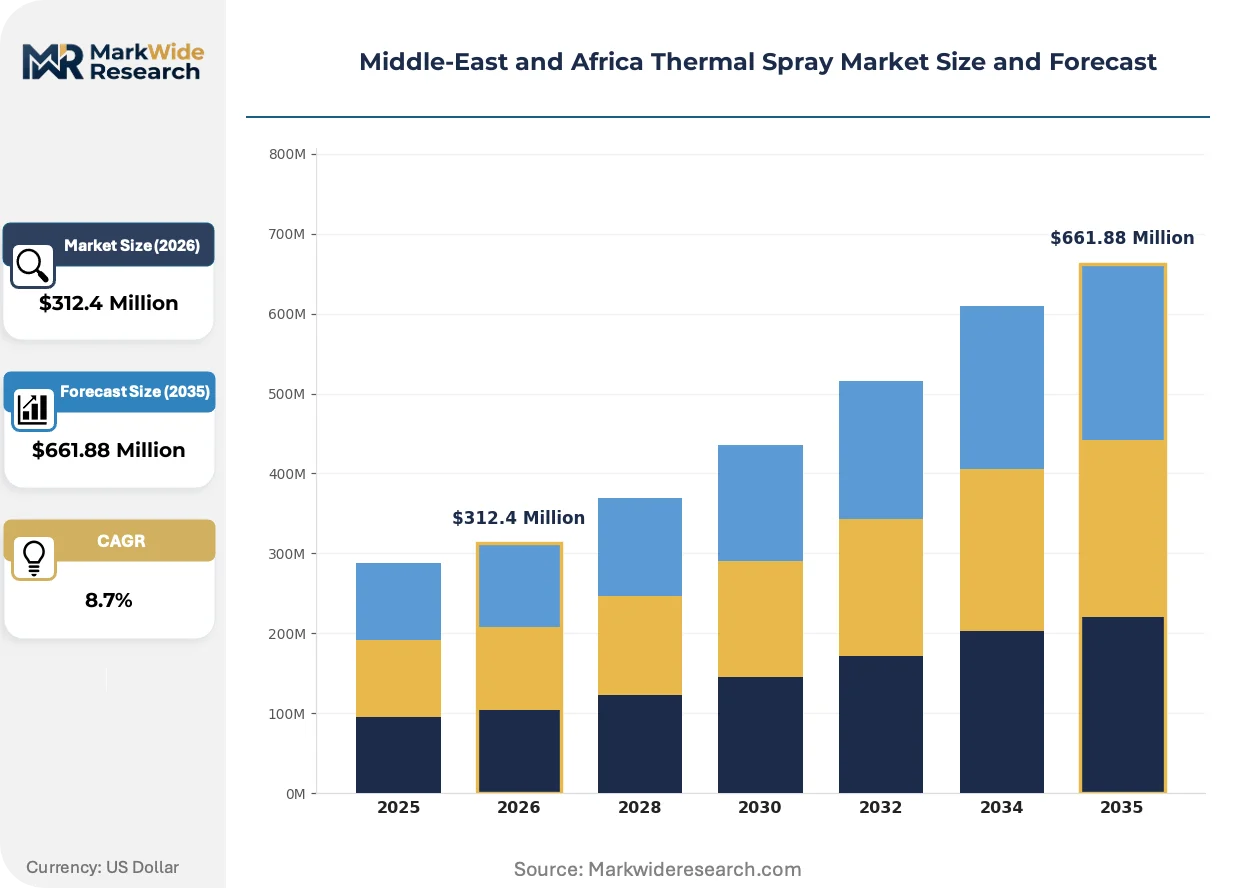
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Thermal Barrier, Hard Facing, Wear Resistant, Corrosion Resistant Material Type: Metals, Ceramics, Composites, Alloys End User Industry: Aerospace, Automotive, Oil & Gas, Industrial Equipment Technology: Flame Spray, Plasma Spray, Wire Arc Spray, HVOF |
| Companies Covered | OC Oerlikon Management AG, Oerlikon Metco, Linde plc, Kennametal Inc, Bodycote, Chromalloy Gas Turbine LLC, Sandvik AB, Saint-Gobain, Castolin Eutectic GmbH, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Thermal Spray Market Shifts & Advancements
Process automation and regulatory qualification protocols are restructuring competitive advantage around certification depth rather than equipment scale, favoring specialized applicators over diversified coating shops.
Cold spray deposition systems are modularizing repair workflows for aluminum and magnesium aerospace components. Emirates Engineering and Saudia Technic are adopting portable units for on-wing blade restoration, eliminating component removal cycles. This technology is modularizing MRO turnaround scheduling, compressing maintenance windows from weeks to days for regional fleet operators.
UAE's MOHAP medical device coating registration requirements are mandating ISO 13485 quality system integration for orthopedic implant surface providers. Industrial consequence includes mandatory batch traceability for hydroxyapatite and titanium plasma spray processes. Cardiovascular and dental implant manufacturers in Dubai Healthcare City are consolidating supplier bases to pre-qualified applicators holding dual aerospace-medical certifications.
Asset owner engineering teams are embedding coating specifications into original equipment procurement rather than outsourcing to third-party rebuild shops. Mining houses in South Africa's Bushveld Complex now require OEM-applied ceramic overlays on new crusher components. This specification shift concentrates coating volume with equipment manufacturers, displacing independent applicators from the rebuild aftermarket.
Middle-East and Africa Thermal Spray Market Segmentation
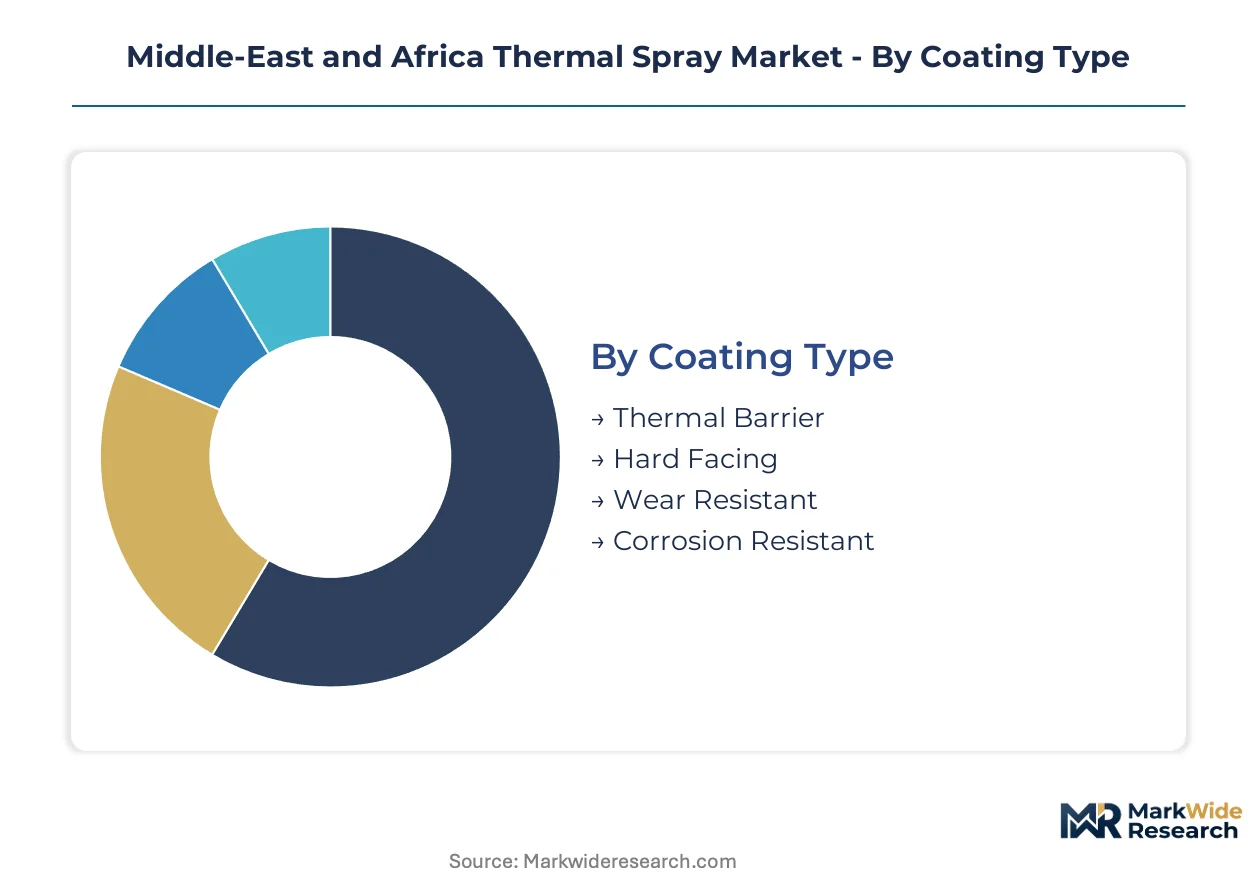
Thermal spray coating specifications diverge sharply across end-use environments, dictating capital allocation toward process-specific equipment portfolios. Material selection and deposition technology choices determine facility investment thresholds, with aerospace-qualified HVOF cells requiring substantially higher upfront expenditure than general industrial flame spray operations.
Coating Type:
Capital intensity varies most dramatically across coating functions, with thermal barrier systems demanding multi-million dollar plasma spray infrastructure versus lower-threshold hard facing installations.
- Thermal Barrier:Ceramic topcoat systems utilizing yttria-stabilized zirconia achieve 1200°C surface protection for gas turbine hot section components. Abu Dhabi MRO facilities concentrate demand as fleet expansion drives overhaul capacity buildup, with SFDA and UAE civil aviation authority protocols restricting qualified applicators to under twelve certified operations.
- Hard Facing:Tungsten carbide-cobalt chrome overlays restore dimensional tolerances on oilfield drilling equipment subjected to abrasive wear. Saudi Arabia's Vision 2030 localization mandates redirect procurement toward Riyadh-based applicators serving domestically manufactured equipment, compressing margins for uncertified mid-tier providers.
- Wear Resistant:Ceramic overlays on dragline buckets and crusher components dominate South Africa's platinum belt mining operations.
- Corrosion Resistant:Aluminum and zinc sacrificial coatings protect subsea pipeline infrastructure across Qatar and Kuwait offshore developments.
Thermal barrier coatings absorb the bulk of installed capacity; hard facing is expanding most quickly under Saudi industrial localization policies.
Material Type:
Feedstock chemistry determines coating performance envelopes and shapes supplier relationships with powder metallurgy specialists.
- Metals:Aluminum, zinc, and nickel-based wires and powders provide sacrificial corrosion protection and dimensional restoration for general industrial applications. Flame spray and wire arc systems dominate metal deposition across African mining equipment rebuild shops where lower capital barriers support fragmented service provider landscapes.
- Ceramics:Alumina, zirconia, and chromia formulations deliver electrical insulation and thermal protection for turbine components. Plasma spray retains scale advantages in ceramic deposition despite HVOF densification requirements from Saudi and UAE regulators forcing equipment upgrades among regional applicators.
- Composites:Cermet formulations combining ceramic hardness with metallic toughness dominate wear-critical oilfield and mining applications.
- Alloys:Nickel-chromium and cobalt-based superalloys provide oxidation resistance for aerospace engine repairs.
Ceramics command premium pricing tiers; composites are gaining share fastest in wear-resistant applications.
End User Industry:
Customer concentration and qualification requirements create distinct margin profiles across vertical markets.
- Aerospace:Engine component restoration and airframe protection demand OEM-approved processes with AS9100 quality system integration. UAE civil aviation authority mandates restrict engine repair contracts to qualified facilities, with Emirates Engineering and Saudia Technic adopting cold spray units for on-wing blade restoration.
- Oil & Gas:Offshore platform maintenance and subsea pipeline protection concentrate demand for corrosion-resistant aluminum coatings. Qatar and Kuwait operators lack qualified contractors for cathodic barrier deployment at depths exceeding 200 meters, creating structural supply gaps.
- Automotive:Cylinder bore thermal spray coatings support regional manufacturing zones with lower qualification barriers than aerospace.
- Industrial Equipment:General machinery restoration represents volume base with compressed margins and fragmented competition.
Aerospace commands the steepest pricing premiums; oil and gas is climbing the fastest on offshore infrastructure investment cycles.
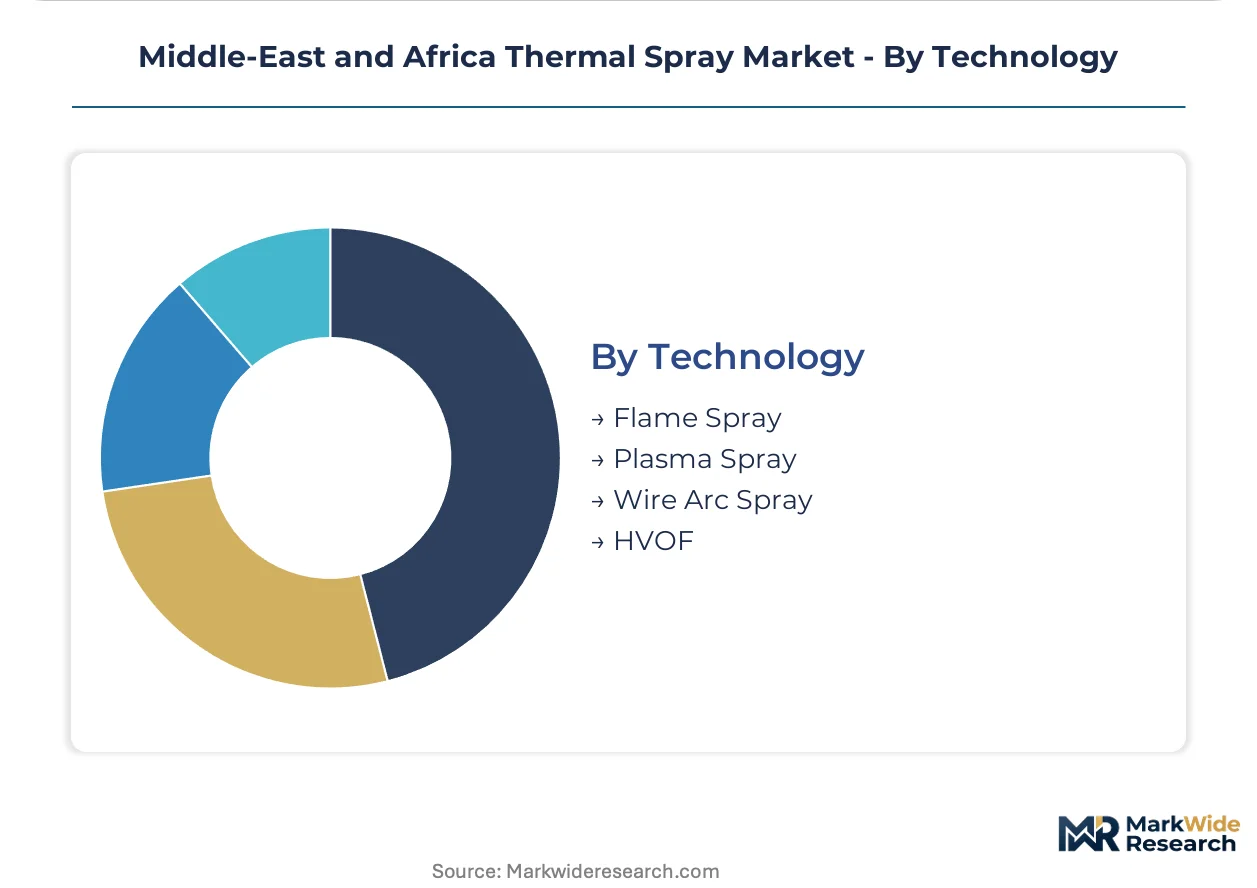
Technology:
Deposition process selection determines coating density, bond strength, and regulatory acceptance for critical applications.
- HVOF:High-velocity oxy-fuel systems propel particles at 700 m/s to produce dense, low-porosity coatings preferred for rotating equipment. SFDA and UAE MOHAP densification requirements force applicator equipment upgrades, concentrating contract awards among certified specialists with capital reserves for system modernization.
- Plasma Spray:Electric arc plasma generation achieves temperatures exceeding 15000°C for ceramic deposition in thermal barrier applications. Scale advantages persist in gas turbine coating despite laser cladding substitution capturing precision repair segments.
- Flame Spray:Combustion-driven particle acceleration serves cost-sensitive general industrial applications with lower performance requirements.
- Wire Arc Spray:Electric arc melting of feedstock wires delivers high deposition rates for large-area corrosion protection.
HVOF captures the majority of margin-rich contracts; cold spray modularization is disrupting aerospace MRO workflows fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Dubai Industrial Park concentrate thermal spray infrastructure through tax-exempt zones purpose-built for heavy manufacturing and aerospace MRO operations.
Saudi Arabia
Vision 2030 localization mandates redirect oilfield equipment procurement toward Riyadh-based applicators. The Saudi Food and Drug Authority enforces densification standards for HVOF coatings on domestically manufactured drilling components. King Abdullah Economic City hosts hard-facing specialists serving Aramco-contracted equipment fabricators.
United Arab Emirates
Abu Dhabi MRO facilities drive thermal barrier coating demand as Etihad and Emirates expand fleet overhaul capacity. The General Civil Aviation Authority restricts engine component repairs to OEM-approved processes. Dubai Industrial Park clusters plasma spray operators serving aerospace repair stations with AS9100 quality integration.
South Africa
Platinum belt mining operations concentrate demand for wear-resistant ceramic overlays on dragline buckets and crusher components. The country's national mining regulator encloses coating qualification protocols for equipment rebuild contractors. Johannesburg hosts HVOF operators facing nickel and cobalt feedstock price volatility.
Qatar
North Field offshore expansion generates subsea pipeline protection requirements at depths exceeding 200 meters. The national petroleum authority lacks qualified thermal spray contractors for cathodic barrier deployment. Ras Laffan Industrial City concentrates corrosion-resistant aluminum coating demand for platform infrastructure.
Kuwait
Burgan Field maintenance cycles drive demand for tungsten carbide hard-facing on downhole drilling equipment. The national oil company mandates local content thresholds for coating services on domestic contracts. Al-Ahmadi industrial zone hosts flame spray operators serving general machinery restoration with lower capital barriers.
Middle-East and Africa Thermal Spray Market Competitive Landscape
Top-tier vendors anchor premium coating contracts through OEM-approval and regulatory certification, while mid-tier service providers face margin compression from equipment upgrade mandates. The supplier base stratifies around three archetypes: integrated powder-equipment specialists, pure-play coating applicators, and diversified industrial services conglomerates. Consolidation pressure favors certified specialists with capital reserves for HVOF system modernization. Strategic moves center on geographic expansion into Gulf industrial zones and backward integration into captive powder feedstock production.
Among Swiss-anchored industrial groups, OC Oerlikon Management AG occupies a position exemplifying integrated plasma spray technology leadership. Linde plc represents the industrial gas supply archetype controlling feedstock availability for regional HVOF operators. Kennametal Inc sits within the powder formulation specialist tier, anchoring tungsten carbide supply relationships for wear-resistant applications.
| Leading Market Players |
|---|
| OC Oerlikon Management AG |
| Oerlikon Metco |
| Linde plc |
| Kennametal Inc |
| Bodycote |
| Chromalloy Gas Turbine LLC |
| Sandvik AB |
| Saint-Gobain |
| Castolin Eutectic GmbH |
| Others |
Supply & Pricing Matrix
SFDA densification mandates for HVOF coatings gate qualified supply access and premium-tier pricing power, compressing margins for uncertified applicators while concentrating contract awards among Riyadh-based specialists with equipment modernization reserves.
Pricing Analysis
Short lead-time premiums separate emergency repair contracts from scheduled maintenance slots across Abu Dhabi MRO facilities. Three-tier pricing structure across OEM-certified, AS9100-qualified, and general industrial levels reflects certification grade and bond coat-topcoat interface engineering complexity. Cost compression in mid-tier flame spray services is intensifying because Johannesburg operators face nickel and cobalt feedstock volatility without volume scale buffers. Mining equipment rebuild shops exhibit highest price sensitivity; aerospace engine component restorations show lowest.
Supply Chain Analysis
Certification bottlenecks at UAE technical institutes restrict qualified technician throughput, anchoring supply concentration in Switzerland, Germany, and the United States for powder metallurgy and plasma spray system manufacturing. Feedstock chemistry draws from nickel-chromium superalloy, yttria-stabilized zirconia, and tungsten carbide-cobalt chrome inputs. Single-source vulnerability runs through Linde plc's industrial gas supply integration controlling regional HVOF feedstock availability. Distribution runs through King Abdullah Economic City and Dubai Industrial Park tax-exempt zones purpose-built for heavy manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where UAE civil aviation authority OEM-approval requirements erect a barrier-to-entry moat protecting certified specialists from price-based competition.
For Market Incumbents: Lock in captive powder feedstock production through backward integration into tungsten carbide formulation capabilities, insulating margin position from cobalt price volatility. Expand HVOF cell capacity in Riyadh industrial zones to capture Vision 2030 localization-mandated contracts before mid-tier competitors complete equipment upgrades. Laser cladding substitution in aerospace precision repair segments demands defensive R&D investment in cold spray modularization. For New Entrants and Emerging Players: MOHAP medical device coating registration requirements in Dubai Healthcare City open a window for orthopedic implant surface specialists holding dual aerospace-medical ISO 13485 certifications. Target subsea pipeline protection gaps in Qatar and Kuwait offshore developments where cathodic barrier deployment exceeds 200 meters depth without qualified contractor coverage. Automated spray cell integration with robotic trajectory control offers a differentiated go-to-market angle for unmanned coating operations in Saudi industrial manufacturing zones. For Investors and Strategic Acquirers: SFDA establishment of hydroxyapatite orthopedic implant approval frameworks is the leading indicator that medical device coating volume will concentrate with pre-qualified applicators over the next decade. Acquisition target archetype: mid-cap specialists with existing AS9100 quality systems and capital reserves for HVOF densification equipment upgrades. Watch for Emirates Engineering and Saudia Technic cold spray adoption rates as the signal for portable on-wing restoration technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Feedstock | Kennametal Inc's tungsten carbide formulations anchor wear-resistant supply relationships for drilling equipment. |
| Automated Spray Cell Deployment | Robotic trajectory control with real-time particle temperature monitoring enables unmanned operations in Riyadh zones. |
| Dual Certification Investment | ISO 13485 quality system integration captures Dubai Healthcare City orthopedic implant manufacturer consolidation. |
| Geographic Expansion into Gulf Industrial Zones | King Abdullah Economic City tax exemptions attract hard-facing specialists serving Aramco-contracted fabricators. |
| Cold Spray Technology Modularization | Portable units compress maintenance windows from weeks to days for Emirates Engineering blade restoration. |
Research Methodology
Document review covered trade customs data, SEC filings from coating equipment manufacturers, SFDA and UAE civil aviation authority regulatory filings, and mining equipment procurement databases, complemented by interviews with MRO facility engineering directors, powder metallurgy procurement leads, NACE coating inspectors, and thermal spray system OEM technical sales specialists. Secondary validation drew from aerospace quality system audit reports, industrial gas supply chain disclosures, and regional industrial zone investment announcements. Bottom-up coating job costing models and top-down regional infrastructure investment forecasts were triangulated.
Installed base projections for HVOF and plasma spray cells across the analysis window were generated through segmentation by coating type, material chemistry, end-user industry vertical, and deposition technology platform. CAGRs were derived from equipment replacement cycles, fleet expansion schedules, and localization policy implementation timelines. Industry-specific inputs included turbine blade overhaul interval extensions from 1200°C thermal barrier advancements and dragline bucket rebuild frequency data from South Africa's platinum belt operations.
The model assumes a particular technology adoption path; alternative pathways for laser cladding substitution in aerospace precision repair segments would alter the outlook for plasma spray market share. Forecasts reflect assumptions regarding SFDA equipment upgrade compliance deadlines and UAE technical institute certification throughput capacity. A model refresh is warranted upon material change in nickel and cobalt commodity price volatility or regulatory relaxation of OEM-approval requirements for engine component repairs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Anti-Friction Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Global Sputter Coater Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
BPA-Free Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
China Marine Coatings Market
Coatings
Coating Agents for Synthetic Leather Market