
 Canada Automotive OEM Coatings Market | 2026-2036
Canada Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive OEM Coatings Market Outlook
Light truck and SUV manufacturing is repositioning coating procurement priorities across Canadian assembly plants. PPG Industries sustains broad technology leadership through integrated color-matching systems serving Detroit Three operations in Ontario. BASF SE anchors its position with cathodic electrocoat primer lines optimized for corrosion resistance in Canadian winter conditions. Axalta Coatings Systems differentiates through dedicated waterborne basecoat capacity aligned with OEM sustainability mandates.
Canada automotive OEM coatings comprise multi-layer polymer film systems applied to vehicle bodies during original manufacture, typically incorporating epoxy-based electrocoat primers, polyurethane or acrylic basecoats, and polyurethane clearcoats engineered for gloss retention and chip resistance. These coatings protect substrates from corrosion, UV degradation, and mechanical damage while providing aesthetic finish. Waterborne technology leads volume adoption as OEMs phase down solvent-borne systems under federal environmental compliance timelines. Clearcoat formulations command premium positioning due to their dual functional role in appearance and durability. Powder coating registers the fastest technology trajectory, particularly for underbody and wheel applications where film thickness and edge coverage requirements intensify.
Health Canada's PMRA regulates biocide content in coating formulations, while Environment and Climate Change Canada administers VOC concentration limits under the Canadian Environmental Protection Act. Transport Canada's Motor Vehicle Safety Standards indirectly shape coating performance specifications through corrosion resistance and flammability requirements. Stakeholders must monitor pending amendments to federal VOC regulations and provincial carbon pricing mechanisms that alter coating system economics.
Market Dynamics
Electric vehicle manufacturing is restructuring coating demand across Ontario and Quebec assembly corridors, forcing suppliers to reformulate for aluminum-intensive body architectures and battery enclosure protection requirements.
Growth Catalysts
- Environment and Climate Change Canada VOC limits:Federal emission thresholds under the Canadian Environmental Protection Act are accelerating waterborne coating adoption across Windsor-Toronto assembly plants.
- Light truck and SUV production:Higher coating consumption per unit from larger vehicle geometries is expanding procurement volumes in Ontario's automotive corridor.
- Aluminum body panel migration:Corrosion-resistant pretreatment and conversion coating demand is intensifying as OEMs reduce steel content in next-generation platforms.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane resin and isocyanate precursor costs fluctuate with North American refinery output, compressing formulation margins.
- Single-source electrocoat supply:Cathodic epoxy primer production concentrates among three integrated suppliers serving Detroit Three operations in Ontario.
- Health Canada PMRA biocide restrictions:In-can preservation chemistry limitations are complicating waterborne system stability during extended supply chain transits.
Strategic Opportunities
- Quebec battery cell manufacturing:Gigafactory construction around Montreal and Bécancour is creating coating demand for thermal management housings and module enclosures.
- Powder coating underbody applications:Chip-resistant film requirements for gravel-prone Canadian road conditions favor powder technology for rocker panels and suspension components.
- Transport Canada corrosion warranty extension:OEMs are upgrading clearcoat durability specifications to meet 10-year perforation protection mandates in salt-belt provinces.
Industry Challenges
- Color-matching technician scarcity:Specialized spectrophotometry and tinting expertise is concentrating among aging workforces at Tier 1 coating applicators.
- Electrocoat tank conversion capex:Shifting from solvent-borne to waterborne primer systems requires multi-million dollar tank, rectifier, and wastewater infrastructure overhauls.
- PPG-BASF-Axalta specification lock-in:OEM approved vendor lists create switching friction for secondary coating suppliers seeking platform entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive OEM Coatings Market |
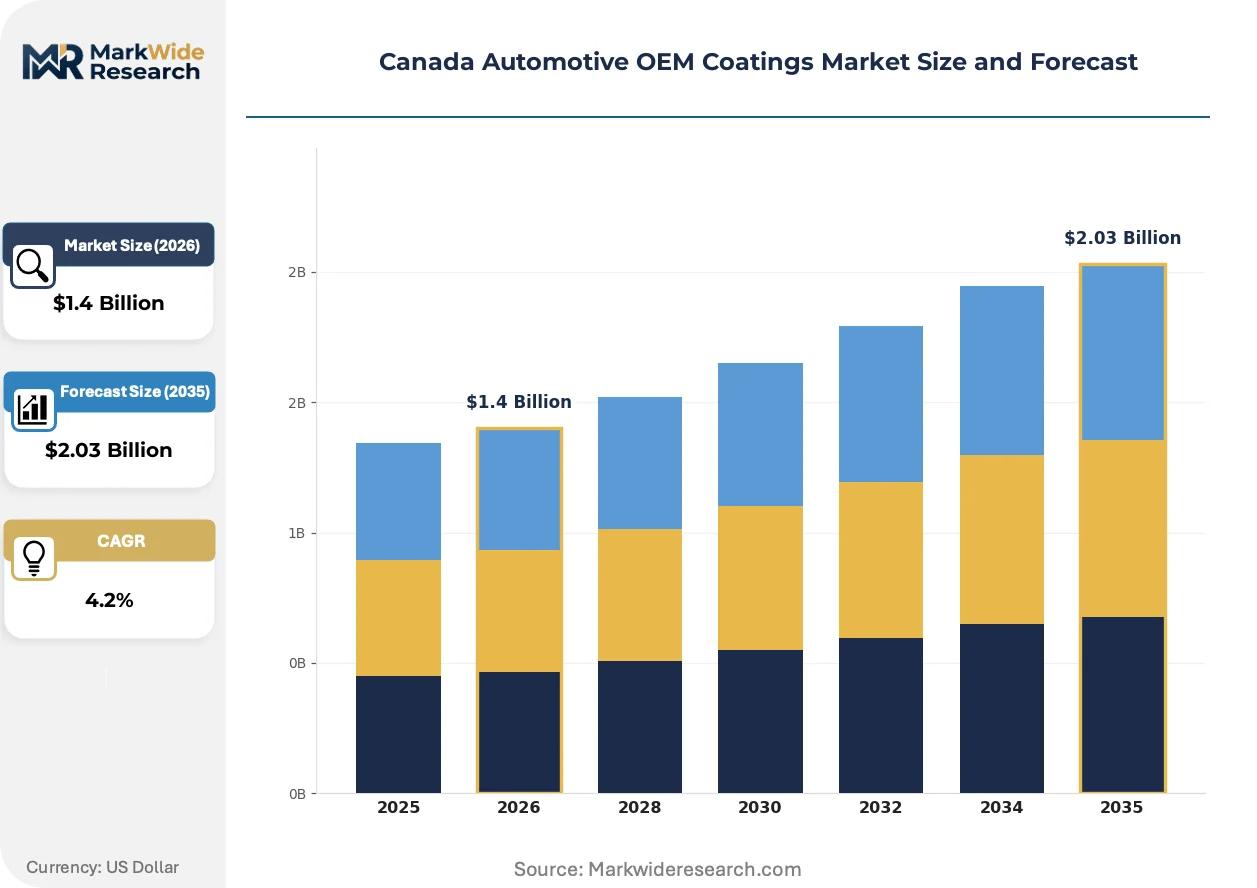
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
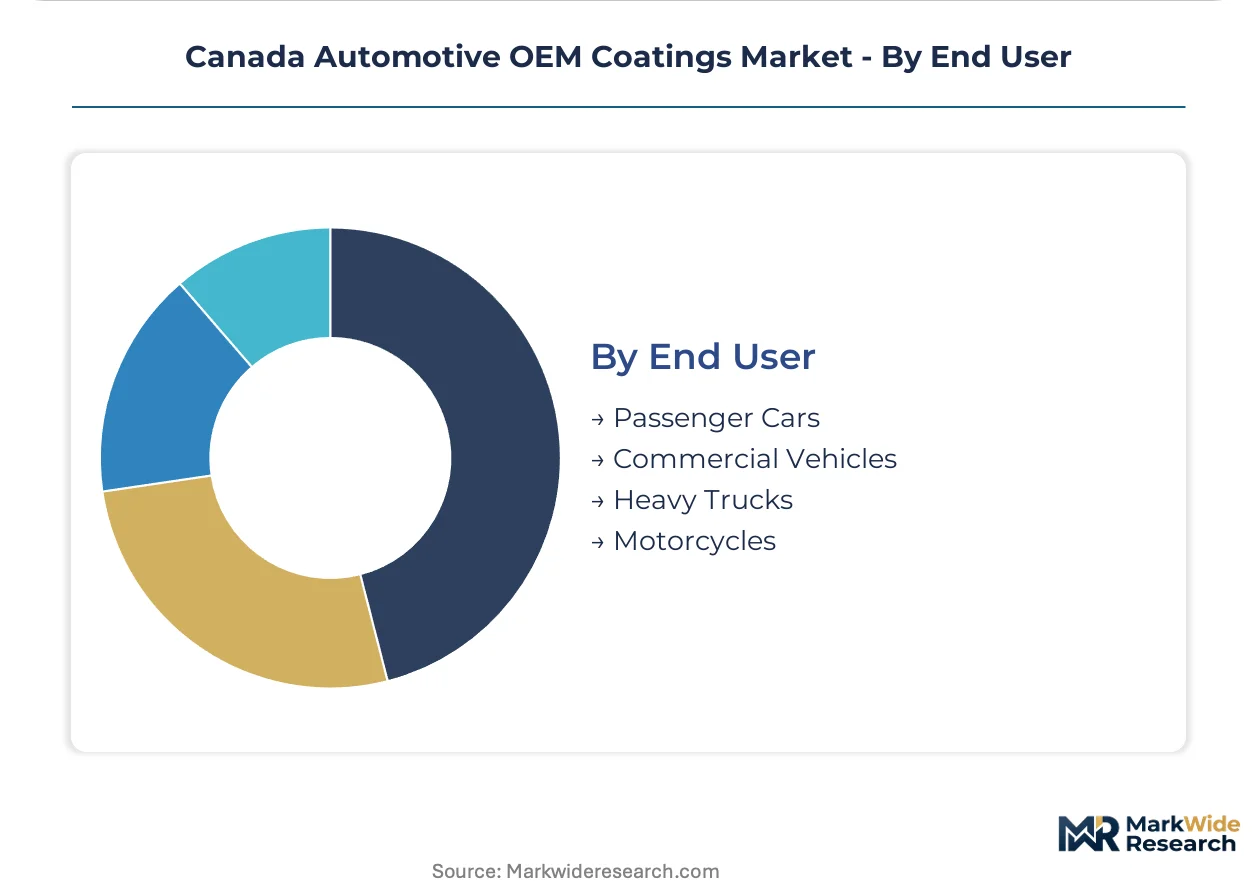
| Segmentation | Product Type: Basecoat, Clearcoat, Primer, Topcoat Application: Vehicle Assembly, Refinish, Aftermarket, Customization Technology: Waterborne, Solvent-based, UV-cured, Powder Coating End User: Passenger Cars, Commercial Vehicles, Heavy Trucks, Motorcycles |
| Companies Covered | Axalta Coatings Systems, Nippon Paint Holdings Co Ltd, BASF SE, Grainger Canada, Canada Car Color, PPG Industries Inc, RPM International Inc, The Sherwin-Williams Company, AkzoNobel NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive OEM Coatings Market Strategic Shifts
Coating formulation and application technology is pivoting toward sustainability compliance and process efficiency as federal environmental deadlines approach and electric vehicle architectures proliferate.
Self-healing clearcoat chemistry is modularizing repair functionality into factory-applied films. PPG and BASF development programs target microcapsule-embedded polyurethane networks that release healing agents upon scratch damage. Detroit Three OEMs in Ontario are piloting these systems for premium SUV lines where appearance retention drives residual value.
Health Canada's pending amendments to VOC concentration limits under the Canadian Environmental Protection Act will tighten solvent-borne basecoat exemptions. This regulatory compression is forcing Windsor-Toronto corridor plants to accelerate waterborne conversion timelines ahead of original equipment replacement cycles. Small and mid-volume OEMs face disproportionate compliance costs relative to integrated Detroit Three facilities.
Fleet procurement consolidation among Detroit Three operations is compressing coating supplier margins through multi-year volume agreements. Tier 1 applicators in Ontario are responding by integrating in-house color development laboratories to reduce OEM specification dependency. This buyer concentration dynamic is most pronounced in light truck and SUV platforms where annual coating volumes exceed 50 million liters per assembly plant.
Canada Automotive OEM Coatings Market Segmentation
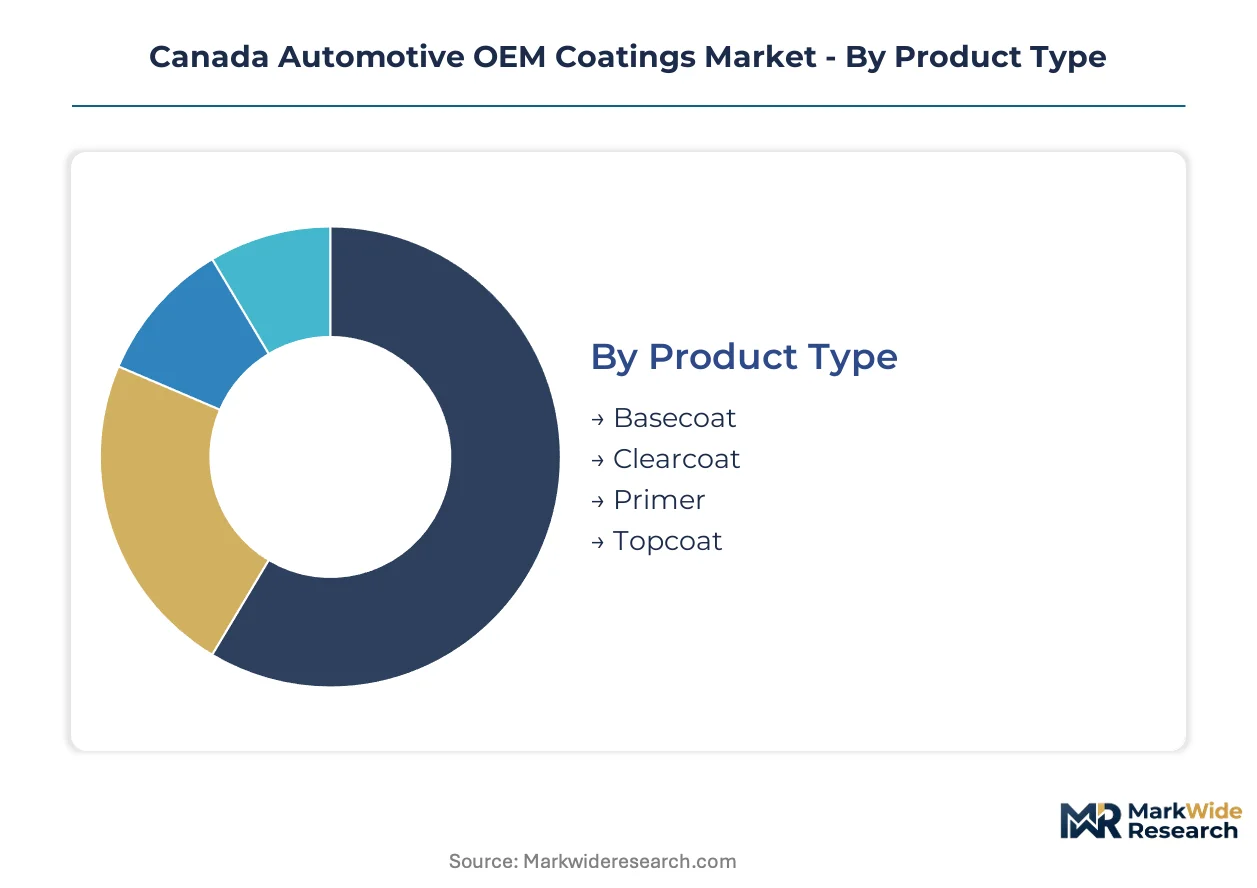
Coating procurement across Canadian assembly plants fragments along technical specifications and regulatory compliance requirements. Each segmentation dimension captures distinct cost structures and reformulation pressures.
Product Type:
Standardization dominates commodity layers while premium tiers demand bespoke chemistry for corrosion and appearance performance.
- Clearcoat:Polyurethane formulations provide gloss retention and chip resistance for exterior vehicle surfaces. Demand concentrates in Ontario's Windsor-Toronto corridor where Detroit Three OEMs specify premium durability grades for light truck and SUV platforms. Health Canada PMRA biocide restrictions are forcing reformulation of in-can preservation systems without compromising UV stability.
- Basecoat:Waterborne acrylic and polyurethane dispersions deliver color and metallic effects beneath protective clearcoat films. Procurement volumes align with high-volume assembly plants in Ontario, where color-matching laboratories reduce OEM specification dependency. Environment and Climate Change Canada VOC thresholds are accelerating waterborne conversion ahead of equipment replacement cycles.
- Primer:Cathodic epoxy electrocoat systems provide corrosion protection on metal substrates.
- Topcoat:Integrated primer-basecoat-clearcoat systems streamline application processes.
Leading the category by volume: Basecoat. Growing fastest: Clearcoat.
Application:
Process stage determines coating chemistry complexity and regulatory exposure intensity.
- Vehicle Assembly:Multi-layer OEM application during original manufacture integrates electrocoat primers, basecoats, and clearcoats through automated spray systems. Ontario assembly plants consume the majority of coating volumes, with aluminum-intensive EV architectures demanding pretreatment chemistry adaptations. Fleet procurement consolidation among Detroit Three operations compresses supplier margins through multi-year volume agreements.
- Refinish:Repair and restoration coatings match factory finishes for collision and warranty work.
- Aftermarket:Replacement coatings for non-warranty repair channels.
- Customization:Specialty finishes for limited-edition and fleet-specific color programs.
Vehicle Assembly commands procurement volumes. Refinish offers margin expansion potential.
Technology:
Environmental compliance deadlines are restructuring capital allocation across coating chemistry platforms.
- Waterborne:Acrylic and polyurethane dispersions replace solvent-borne systems under federal VOC limits. Windsor-Toronto corridor plants are accelerating conversion timelines as Health Canada pending amendments tighten basecoat exemptions. Small and mid-volume OEMs face disproportionate compliance costs relative to integrated Detroit Three facilities with captive wastewater infrastructure.
- Powder Coating:Thermosetting polymer films provide chip-resistant protection for underbody and wheel applications. Quebec battery cell manufacturing around Montreal and Bécancour is creating demand for thermal management housing coatings. Gravel-prone Canadian road conditions favor powder technology for rocker panels and suspension components where film thickness requirements intensify.
- Solvent-based:Conventional high-solids formulations face phase-down under Canadian Environmental Protection Act schedules.
- UV-cured:Rapid-cure chemistry for selected plastic substrate applications.
Waterborne dominates current procurement. Powder Coating is expanding most quickly.
End User:
Vehicle class determines coating consumption per unit and durability specification intensity.
- Light Truck and SUV:Larger vehicle geometries consume higher coating volumes per unit, anchoring procurement in Ontario's automotive corridor. Transport Canada corrosion warranty extensions to ten-year perforation protection mandates are upgrading clearcoat durability specifications for salt-belt provinces. Self-healing clearcoat pilot programs target premium SUV lines where appearance retention drives residual value.
- Passenger Cars:Sedan and hatchback platforms with standardized coating specifications.
- Commercial Vehicles:Fleet trucks and vans with functional finish requirements.
- Heavy Trucks:Long-haul and vocational vehicles with extended durability needs.
- Motorcycles:Low-volume specialty applications with distinct aesthetic requirements.
Light Truck and SUV segments anchor volume. Heavy Trucks present durability premium opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's automotive coating production concentrates in Ontario and Quebec while consumption patterns shift toward aluminum-intensive EV architectures. Domestic assembly plants source primarily from integrated North American suppliers, with cross-border material flows from US resin producers. The country's regulatory framework under Environment and Climate Change Canada tightens faster than US federal timelines, creating distinct compliance zones.
Ontario
Windsor-Toronto corridor plants consume the majority of Canadian coating volumes through Detroit Three light truck and SUV production. Environment and Climate Change Canada VOC enforcement accelerates waterborne conversion at St. Thomas and Oakville assembly facilities. Hamilton and Windsor applicator clusters face multi-million dollar electrocoat tank overhauls ahead of federal compliance deadlines.
Quebec
Battery cell manufacturing around Montreal and Bécancour generates thermal management housing coating demand for EV supply chains. The province's carbon pricing mechanism alters coating system economics relative to Ontario operations. Bécancour industrial park hosts emerging powder coating applications for battery module enclosures.
Alberta
Petrochemical feedstock proximity supports polyurethane resin precursor supply to Ontario formulators. Provincial industrial emissions regulations lag federal VOC timelines, creating regulatory arbitrage for solvent-borne system transitions. Edmonton-area chemical processing clusters supply isocyanate derivatives to automotive coating manufacturers.
British Columbia
Lower Mainland assembly operations remain minimal, with coating demand concentrated in port logistics and Pacific Rim trade facilitation. The province's zero-emission vehicle mandate accelerates EV coating specification imports from Ontario and US suppliers. Vancouver serves as distribution node for Asian coating technology licensing into Canadian markets.
Canada Automotive OEM Coatings Market Competitive Environment
Top-tier vendors anchor integrated electrocoat and clearcoat supply, while mid-tier specialists concentrate on waterborne basecoat conversions and regional color-matching services. The vendor base stratifies across three tiers: global chemistry conglomerates with captive resin production, North American coating applicators with OEM-approved laboratory networks, and regional tinting specialists serving aftermarket channels. Two dominant competitive moves are emerging: backward integration into waterborne resin production to capture margin from petrochemical volatility, and captive color development laboratory investments to reduce specification dependency on Detroit Three procurement consolidation.
Among integrated chemistry conglomerates, BASF SE and PPG Industries occupy positions exemplifying the full-stack supplier archetype with electrocoat-through-clearcoat portfolios. Axalta Coatings Systems represents the waterborne specialization vector aligned with federal sustainability mandates. These three anchors illustrate how specification lock-in dynamics favor incumbents with multi-decade OEM validation histories and captive wastewater infrastructure at Ontario assembly corridor plants.
| Leading Market Players |
|---|
| Axalta Coatings Systems |
| Nippon Paint Holdings Co Ltd |
| BASF SE |
| Grainger Canada |
| Canada Car Color |
| PPG Industries Inc |
| RPM International Inc |
| The Sherwin-Williams Company |
| AkzoNobel NV |
| Others |
Value Chain & Pricing Dynamics
Clearcoat-premium divergence from commodity primer tiers manifests in both pricing power and supply chain configuration across Ontario's automotive corridor. Health Canada PMRA biocide restrictions compress margins on standard waterborne basecoats while polyurethane clearcoat formulations retain pricing flexibility through Detroit Three specification lock-in.
Pricing Analysis
Short lead-time premiums command pricing power at Windsor-Toronto assembly plants running just-in-time coating programs. Contract-based long-term offtake dominates procurement, with price differentiation driven by ISO certification tier and volume scale commitments. Cost compression in waterborne basecoat tiers is intensifying because Environment and Climate Change Canada VOC deadlines force accelerated conversion timelines. Tier 1 applicators show least price sensitivity due to captive wastewater infrastructure, while small OEMs face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with cathodic epoxy electrocoat supply concentrated among three integrated suppliers serving Detroit Three operations. Raw material dependencies draw from Alberta petrochemical clusters for isocyanate precursors and US Gulf Coast refineries for polyurethane resins. Tariff exposure on cross-border resin flows presents structural risk. Distribution runs through Hamilton and Windsor applicator clusters with direct pipeline feed to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's automotive OEM coatings market operates as a vertical-integration race where backward control over waterborne resin production determines margin capture. Players are pursuing captive color development laboratories to reduce specification dependency on consolidated Detroit Three procurement.
For Market Incumbents: To counter PPG-BASF-Axalta specification lock-in, deepen captive wastewater infrastructure investments at Ontario corridor plants and accelerate self-healing clearcoat pilot programs to premium SUV platforms. Certification investment in Health Canada PMRA pre-approved biocide alternatives secures formulation stability during supply chain transits. For New Entrants and Emerging Players: Direct-to-applicator digital platforms offer route to bypass OEM-approved vendor list friction by serving Tier 1 color-matching laboratories in Quebec battery manufacturing zones. Target thermal management housing coatings for Montreal-Bécancour gigafactory supply chains with powder coating specialization for aluminum-intensive EV architectures. For Investors and Strategic Acquirers: Re-rating potential sits with waterborne resin specialists given pending federal VOC amendment enforcement timelines. Long-term viability over the projection horizon favors acquisition of mid-volume applicators with integrated laboratory networks. Watch Transport Canada corrosion warranty extension announcements as inflection signal for clearcoat durability specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Resin Production | Captures margin from Alberta petrochemical volatility and secures supply continuity. |
| Captive Color Development Laboratory Investment | Reduces OEM specification dependency at Hamilton and Windsor applicator clusters. |
| Powder Coating Capacity Expansion | Addresses Quebec battery enclosure demand and gravel-prone Canadian road conditions. |
| Electrocoat Tank Infrastructure Overhaul | Enables federal VOC compliance at St. Thomas and Oakville assembly facilities. |
| Self-Healing Clearcoat Commercialization | Targets premium SUV residual value retention through microcapsule-embedded polyurethane networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 coating applicator procurement leads, OEM platform engineers, aftermarket distribution channel heads, and Health Canada regulatory affairs specialists combined with Environment and Climate Change Canada enforcement disclosures and vehicle production databases. Bottom-up coating volume modeling and top-down market sizing triangulated across Windsor-Toronto corridor plant consumption patterns.
Data-stream reconciliation integrated cathodic electrocoat throughput metrics, waterborne basecoat conversion timelines, and powder coating capacity buildouts across the analysis window. Segmentation dimensions modeled include coating layer hierarchy, application process stage, chemistry platform, and vehicle class propulsion architecture. CAGRs derived from production volume trajectories at Ontario and Quebec assembly plants against federal compliance deadline schedules.
The model holds under sustained Detroit Three production commitments and stable Alberta petrochemical feedstock availability; deviation in battery cell manufacturing localization rates or PMRA biocide restriction severity would shift trajectory. Forecasts reflect documented assumptions about VOC enforcement timing and EV platform aluminum content migration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Industrial Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Rail Coatings Market
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
In-Mold Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Urethane Surface Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Biopolymer Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Global Photocatalytic Coatings Market