
 Middle-East Paints and Coatings Market | 2026-2036
Middle-East Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Paints and Coatings Market Foresight
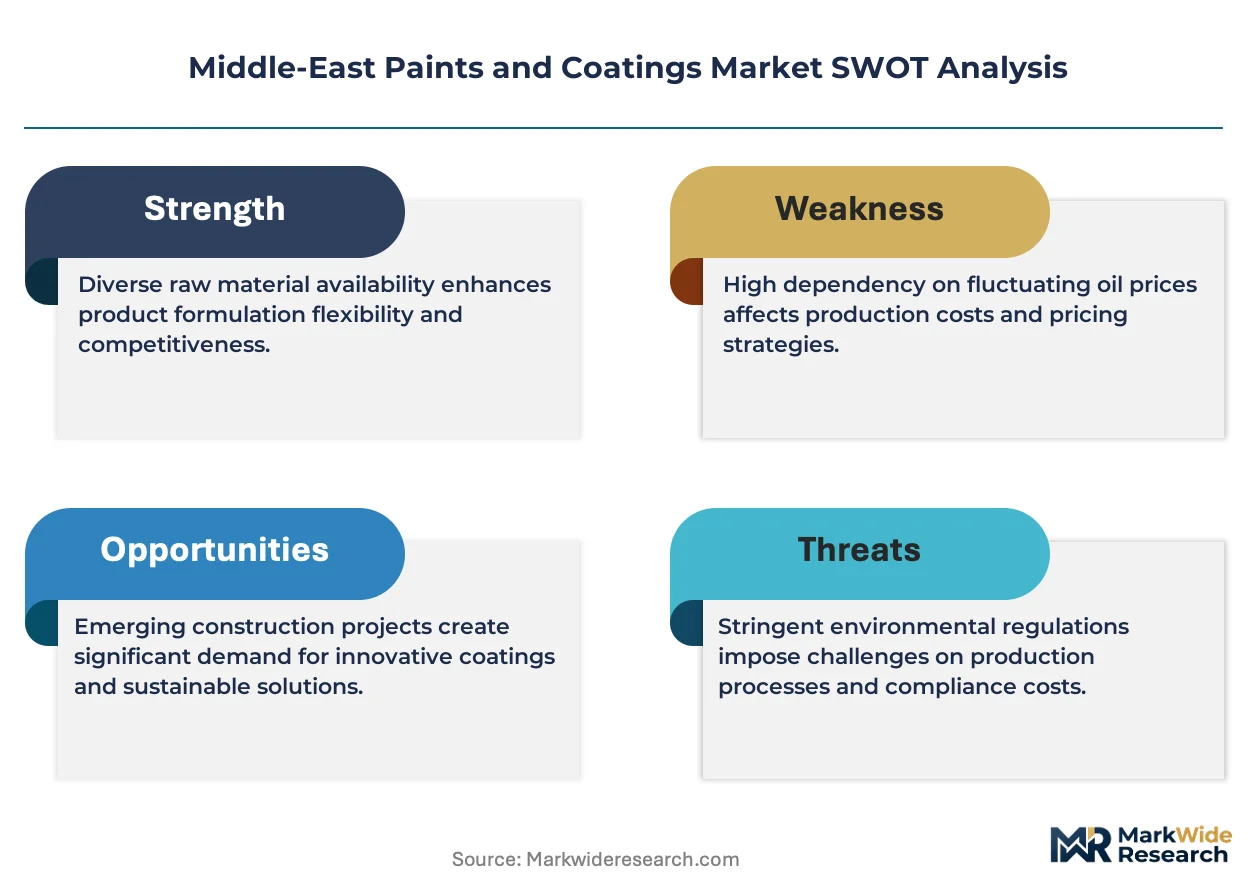
Project finance tied to sovereign wealth infrastructure programs is reconfiguring competitive access across the Middle-East Paints and Coatings landscape. Jotun leverages its marine and protective coatings heritage to anchor long-term supply relationships with port and energy developers. Akzo Nobel N.V. competes through decorative brand strength and localized production footprint. Hempel A/S specializes in high-performance protective systems for offshore and petrochemical installations.
Paints and coatings comprise formulated liquid, powder, or film-forming materials applied to substrates for protection, decoration, or functional modification, with specifications spanning VOC content below 50 g/L for premium water-based architectural grades and corrosion resistance exceeding 10,000 hours salt spray for marine epoxies. Water-based formulations lead volume in residential construction across the Gulf Cooperation Council, while powder coatings represent the fastest-growing technology segment as electrostatic application lines expand in Saudi industrial cities. Specialty coatings command the deepest margin pools where thermal insulation and anti-graffiti functionalities attract premium pricing from commercial developers.
Saudi Standards, Metrology and Quality Organization (SASO) and UAE Ministry of Industry and Advanced Technology enforce VOC limits and product conformity schemes that reshape import access and local formulation requirements. Green building rating systems including Estidama in Abu Dhabi and Mostadam in Saudi Arabia mandate certified coating specifications for public project eligibility. Stakeholders must monitor how evolving national content requirements and carbon disclosure rules alter supplier qualification criteria across megaproject procurement cycles.
Market Dynamics
Sovereign infrastructure procurement is concentrating demand around megaproject clusters in Saudi Arabia and the UAE, forcing suppliers to reconfigure distribution networks and technical service capabilities around specific construction timelines and national content thresholds.
Growth Catalysts
- SASO VOC Convergence:Saudi Arabia's tightening volatile organic compound limits under SASO are accelerating formulation upgrades across imported and locally manufactured architectural coatings, creating compliance-driven replacement cycles.
- Offshore Energy Expansion:Protective coatings demand from Saudi Aramco's Marjan and Zuluf offshore field developments is pulling high-performance epoxy and polyurethane systems through specialized applicator networks.
- Estidama Certification:Abu Dhabi's green building rating system mandates low-emission interior finishes for all government and commercial developments, embedding certified coating specifications into project finance covenants.
Market Restraints
- Titanium Dioxide Concentration:Pigment supply dependence on Chinese sulfate-process TiO2 producers exposes formulators to freight volatility and tariff uncertainty affecting white architectural coatings.
- Technical Limitation of Water-Based Systems:Corrosion protection performance gaps in high-humidity coastal environments restrict water-based technology penetration in marine and heavy industrial segments.
- Substitution Threat from Prefinished Materials:Factory-applied coil coatings on aluminum composite panels are displacing field-applied decorative finishes in high-rise commercial facades across Dubai and Riyadh.
Strategic Opportunities
- Kuwait Infrastructure Pipeline:The stalled but reviving Silk City and Northern Economic Zone developments represent underpenetrated demand for protective and architectural coating systems.
- Anti-Microbial Functionalization:Healthcare construction across the GCC is creating specification pull for silver-ion and copper-oxide modified interior paints in hospital and clinic environments.
- Direct-to-Contractor Digital Platforms:B2B procurement portals are disintermediating traditional distributor networks for standardized maintenance coatings in facility management sectors.
Industry Challenges
- Applicator Certification Bottlenecks:Mostadam and Estidama compliance requires trained contractor networks that remain thin outside Riyadh, Jeddah, Dubai, and Abu Dhabi metropolitan zones.
- Capex Intensity of Powder Coating Lines:Electrostatic application infrastructure requires substantial upfront investment, limiting conversion from liquid systems among smaller Saudi industrial coating operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Paints and Coatings Market |
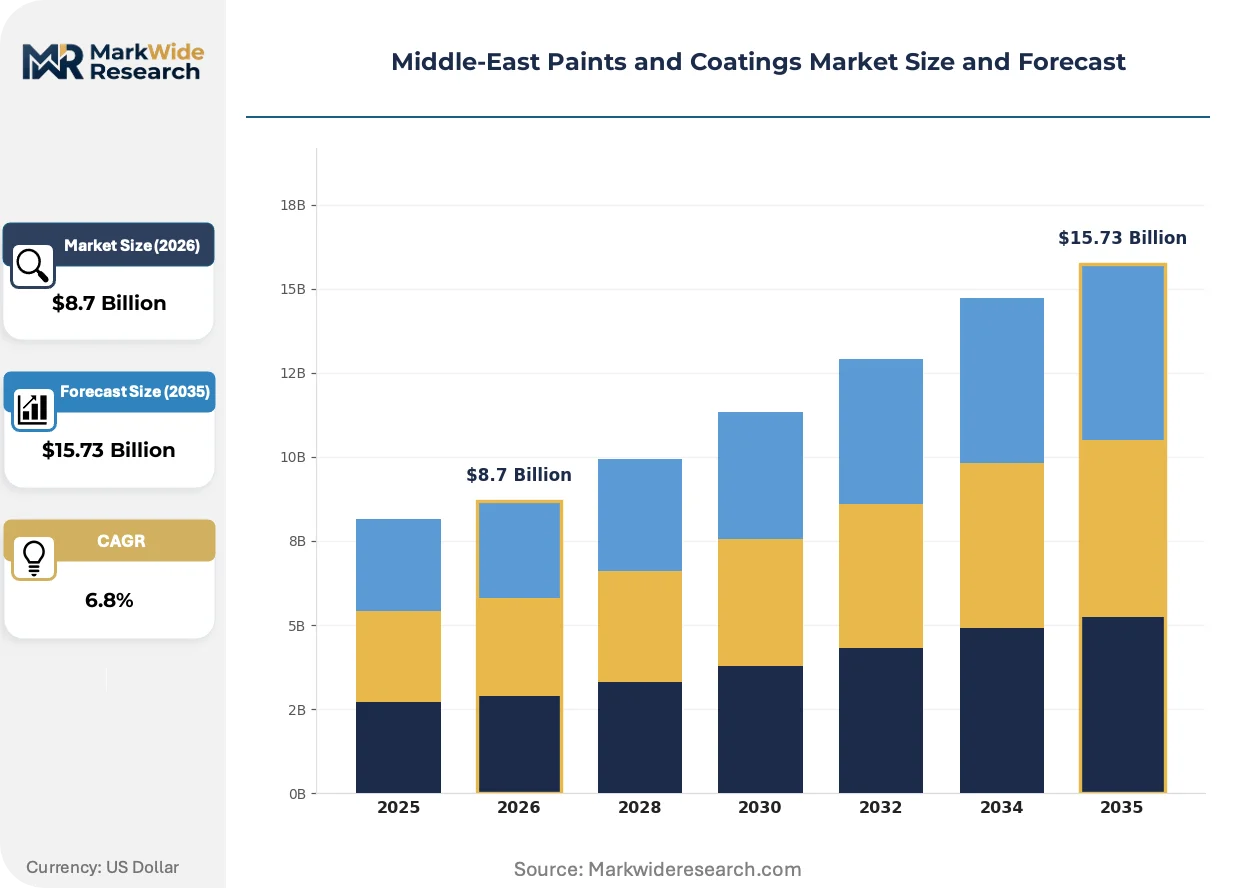
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, Powder Coatings, Specialty Coatings End Use Industry: Construction, Automotive, Marine, Furniture Application: Decorative, Industrial, Protective, Functional Technology: Electrostatic, Spray, Roller, Brush |
| Companies Covered | Jotun, Akzo Nobel N.V., Hempel A/S, NATIONAL PAINTS FACTORIES CO. LTD., Jazeera Paints, PPG Industries Inc, Asian Paints Berger, RPM International Inc, Caparol Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Paints and Coatings Market Shifts & Advancements
Formulation science and application technology are converging around sustainability mandates and performance verification requirements, compressing development cycles while expanding functional boundaries.
Self-healing polymer technology is digitizing quality assurance protocols in protective coatings. Marine and infrastructure asset operators in Saudi Arabia's Red Sea developments are piloting microcapsule-based systems that autonomously repair mechanical damage. This capability is digitizing inspection workflows by reducing manual coating assessment frequency and enabling predictive maintenance scheduling through embedded sensor integration.
Mostadam green building standards are mandating environmental product declarations and embodied carbon disclosures for all coating materials used in Saudi public projects. This regulatory architecture is forcing reformulation of solvent-based industrial systems and accelerating local manufacturing investments to shorten supply chains. High-performance protective segments face the steepest compliance curves as petrochemical and energy infrastructure projects align with sovereign sustainability commitments.
Consolidated procurement through sovereign wealth-backed project development companies is compressing supplier qualification timelines. Master service agreements with single-source coating specifications are displacing fragmented contractor-driven material selection across Saudi giga-projects. This concentration is most visible in Neom and Qiddiya developments, where long-term supply partnerships are locking out distributors unable to meet technical service and inventory holding requirements.
Middle-East Paints and Coatings Market Segmentation
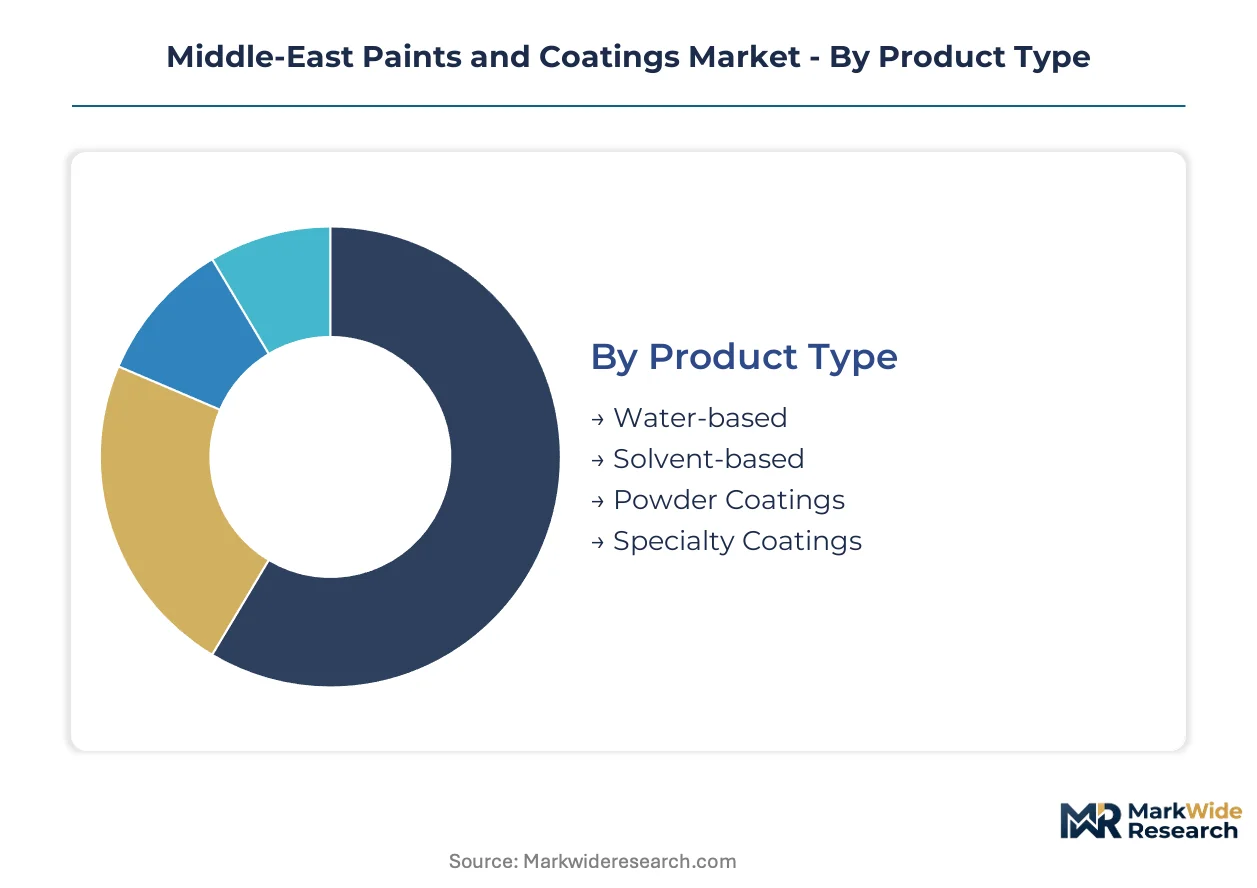
Paints and coatings segmentation in the Middle East reflects divergent replacement cycles across construction, industrial maintenance, and consumer durables. Understanding turnover velocity helps suppliers align inventory, technical service, and formulation investments with actual demand pulses.
Product Type:
Cycle times vary dramatically: architectural coatings refresh every 5-7 years in residential settings, while industrial protective systems endure 15-25 years offshore. Specialty formulations turn over fastest as functional specifications evolve with green building mandates.
- Water-based:Acrylic and polyurethane dispersions with VOC content below 50 g/L dominate Saudi residential construction under SASO compliance deadlines. Neom and Qiddiya megaprojects specify these formulations for interior applications, pulling volume through certified applicator networks trained to Mostadam standards.
- Solvent-based:Alkyd and epoxy solvent systems retain dominance in heavy industrial and marine segments where humidity resistance and rapid cure properties outweigh emissions considerations. Saudi Aramco's offshore field developments specify high-build epoxy primers for subsea infrastructure, sustaining demand despite regulatory pressure.
- Powder Coatings:Thermoset polyester and epoxy-polyester hybrids applied via electrostatic lines in Saudi industrial cities.
- Specialty Coatings:Functional layers including intumescent fire protection, thermal insulation, and anti-graffiti systems.
Water-based formulations anchor the volume base while specialty coatings gain share at the steepest rate.
End Use Industry:
Cost tier stratification separates commodity architectural supply from premium protective systems. Construction absorbs the highest absolute volume at compressed margins, while marine commands pricing power through technical certification requirements.
- Construction:Decorative and protective coatings for residential, commercial, and infrastructure projects across the GCC. Saudi Vision 2030 infrastructure mandates concentrate procurement through sovereign wealth-backed developers, consolidating supplier access around Estidama and Mostadam certification compliance.
- Automotive:OEM refinish and aftermarket coatings for vehicle assembly and repair operations.
- Marine:Immersion-grade epoxies and antifouling systems for port infrastructure, offshore platforms, and vessel maintenance. Jotun and Hempel anchor supply relationships through Aramco's Marjan and Zuluf developments, where salt spray resistance exceeding 10,000 hours is mandatory.
- Furniture:Wood coatings and finishes for residential and commercial fixture manufacturing.
Construction absorbs the greatest volume while marine delivers the deepest margin pools.
Application:
Application type determines customer concentration and service intensity. Decorative coatings fragment across thousands of contractors, while protective applications consolidate around specialized applicators with certification assets.
- Decorative:Interior and exterior architectural finishes for aesthetic and light protection purposes. Dubai and Riyadh high-rise residential towers drive specification of low-sheen acrylics and elastomeric exterior systems, though prefinished aluminum composite panels displace field-applied facades in premium commercial segments.
- Industrial:Manufacturing facility coatings for machinery, flooring, and process equipment. Saudi industrial cities expanding electrostatic powder lines convert from liquid systems where capex availability permits.
- Protective:Heavy-duty corrosion control for infrastructure, energy, and marine assets.
- Functional:Performance-modified coatings delivering thermal, electrical, or hygienic properties.
Decorative coatings dominate volume throughput while protective applications expand most quickly on infrastructure investment cycles.
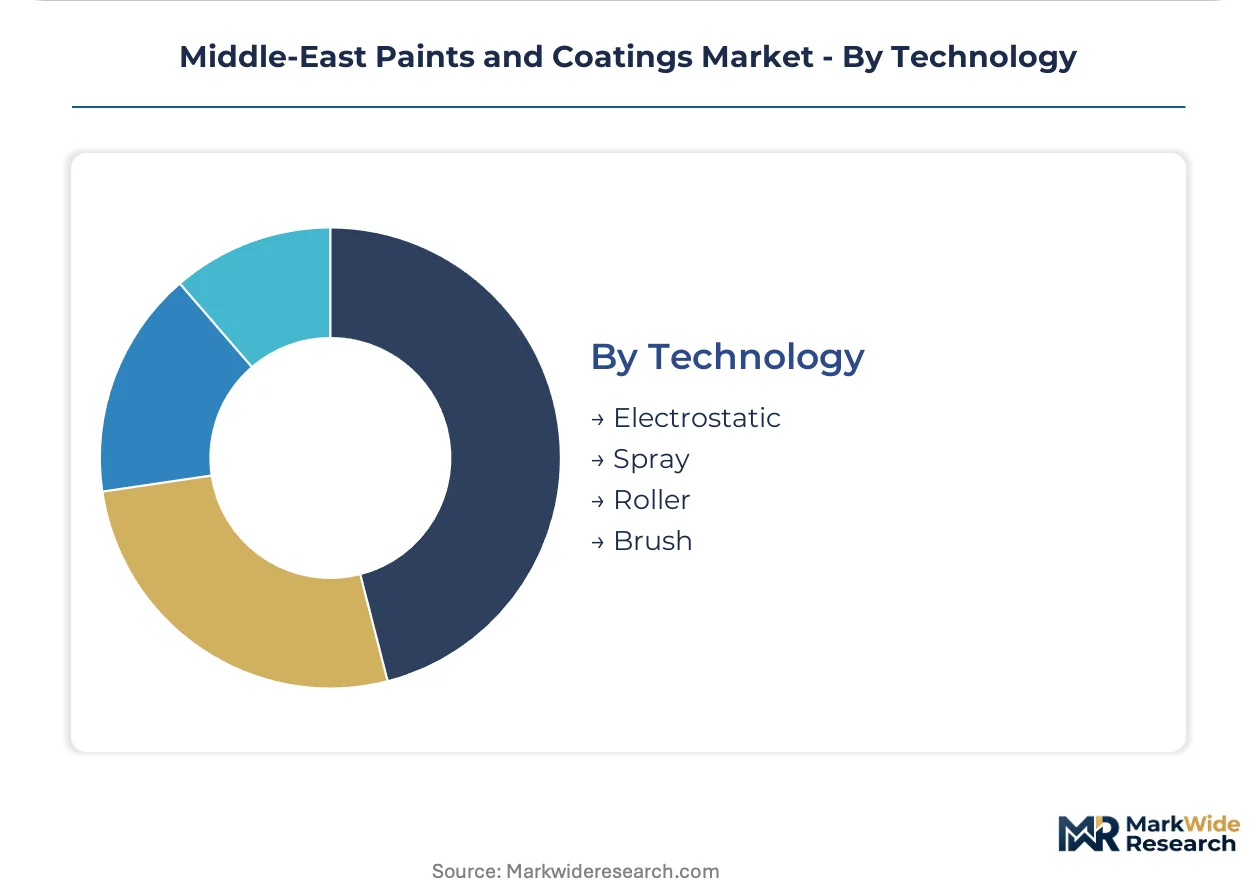
Technology:
Technology selection tracks automation penetration and substrate complexity. Manual methods persist in maintenance and touch-up, while capital-intensive application shifts toward continuous industrial operations.
- Electrostatic:Charged particle deposition for powder coatings and liquid systems in automated manufacturing environments. Saudi industrial city expansions favor this technology for metal fabrication and appliance finishing where transfer efficiency and film uniformity justify equipment investment.
- Spray:Airless and conventional atomization for field application and complex geometries.
- Roller:Large-surface application for flooring and wall systems in commercial construction.
- Brush:Manual touch-up and small-area maintenance across all end uses.
Spray technology retains the broadest installed base while electrostatic systems climb the fastest on manufacturing automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle-East paints and coatings market runs a structural trade deficit in specialty formulations while exporting commodity architectural grades to neighboring markets. Import dependence concentrates in high-performance epoxies and polyurethane systems serving energy infrastructure.
Saudi Arabia
Neom and Qiddiya megaprojects pull low-VOC water-based coatings through Mostadam-certified applicator networks. SASO VOC limits below 50 g/L for interior architectural grades force reformulation of legacy solvent systems. Riyadh and Jeddah metropolitan zones concentrate procurement through sovereign wealth-backed developers consolidating supplier access.
United Arab Emirates
Dubai's high-rise commercial towers specify elastomeric exterior acrylics while prefinished aluminum panels displace field-applied facades in premium segments. Estidama Pearl Rating System mandates certified low-emission finishes for government and commercial developments. Abu Dhabi's industrial zones anchor powder coating line expansions serving regional metal fabrication demand.
Kuwait
Silk City and Northern Economic Zone revivals represent underpenetrated demand for protective and architectural systems after years of stalled development. The country's national standards body enforces product conformity schemes that reshape import access for decorative coatings. Al Ahmadi industrial clusters host maintenance coating demand from petrochemical infrastructure requiring corrosion-resistant epoxies.
Qatar
Post-World Cup infrastructure maintenance sustains protective coatings demand for stadium and transport assets in coastal humidity conditions. The Ministry of Municipality and Environment enforces green building specifications aligning with GCC sustainability convergence. Lusail City development continues pulling specialized exterior finishes through consolidated contractor procurement.
Middle-East Paints and Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and pigment supply. The Middle-East paints and coatings market structures around three tiers: global multinationals with full portfolio coverage, regional specialists anchored in protective segments, and local formulators serving price-sensitive architectural demand. Strategic archetypes include marine heritage players leveraging offshore energy relationships, decorative brand builders with localized production footprints, and industrial coating specialists with applicator certification assets. Competitive moves concentrate on long-term supply partnerships with sovereign project developers and backward integration into titanium dioxide sourcing.
Within the marine and protective tier, Jotun and Hempel A/S occupy positions anchored through Saudi Aramco offshore field relationships. Akzo Nobel N.V. exemplifies the decorative platform archetype with localized manufacturing serving GCC residential construction. Among regional specialists, Jazeera Paints and NATIONAL PAINTS FACTORIES CO. LTD. represent the local formulator segment competing on SASO compliance proximity and distributor network density.
| Leading Market Players |
|---|
| Jotun |
| Akzo Nobel N.V. |
| Hempel A/S |
| NATIONAL PAINTS FACTORIES CO. LTD. |
| Jazeera Paints |
| PPG Industries Inc |
| Asian Paints Berger |
| RPM International Inc |
| Caparol Paints |
| Others |
Supply & Pricing Matrix
Titanium dioxide import dependence on Chinese sulfate-process producers exposes Middle Eastern formulators to freight volatility and tariff uncertainty that compresses white architectural coating margins while forcing inventory holding patterns toward regional buffer stock arrangements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Middle-East paints and coatings landscape. Price differentiation separates Mostadam-certified formulations with environmental product declarations from commodity architectural grades and unbranded local alternatives. Pricing pressure stems from prefinished aluminum composite panels displacing field-applied decorative finishes in Dubai and Riyadh high-rise commercial facades. Facility management contractors exhibit the highest price sensitivity due to standardized maintenance coating procurement through emerging B2B digital platforms, while marine protective segments retain pricing power through Aramco-mandated salt spray certification requirements.
Supply Chain Analysis
Toll manufacturing concentration among Saudi industrial city electrostatic application lines and UAE-based coil coating operations shapes regional supply availability. Raw material sourcing draws from Chinese TiO2 producers, South Korean resin suppliers, and European specialty additive manufacturers. Single-source vulnerability concentrates in marine-grade epoxy resin feedstocks for offshore energy applications. Distribution runs through Jotun and Hempel-controlled applicator certification networks for protective segments, while decorative coatings fragment across thousands of contractor-grade distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master service agreement consolidation by sovereign wealth-backed project developers is transforming coating procurement into a platform-economics inflection where interoperability with Mostadam and Estidama certification databases determines supplier access.
For Market Incumbents: Harden long-term supply partnerships with Neom and Qiddiya development companies by embedding technical service teams within project management offices. Deepen backward integration into titanium dioxide sourcing to offset Chinese import volatility. Lock in applicator certification assets through exclusive training partnerships with Saudi Standards, Metrology and Quality Organization-accredited institutions.
For New Entrants and Emerging Players: Pursue Kuwait's reviving Silk City and Northern Economic Zone developments as underpenetrated white-space targets where incumbent distribution networks remain thin. Target anti-microbial functionalized interior coatings for GCC healthcare construction as the most penetrable specialty segment. Deploy direct-to-contractor digital procurement platforms to bypass established distributor hierarchies in standardized maintenance coating categories.
For Investors and Strategic Acquirers: SASO VOC limit convergence below 50 g/L reshapes the acquisition landscape toward reformulation-capable local manufacturers with compliant water-based production assets. Long-term viability centers on suppliers with demonstrated sovereign project developer relationships and certification database integration. Watch for powder coating line expansion announcements in Saudi industrial cities as inflection indicators for technology conversion momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TiO2 Sourcing | Captive pigment supply insulates margins from Chinese freight volatility and tariff exposure. |
| Mostadam Certification Program Investment | Compliance database integration unlocks Saudi public project procurement eligibility. |
| Electrostatic Powder Coating Line Expansion | Automation transfer efficiency gains displace liquid systems in Saudi industrial cities. |
| Direct-to-Contractor Digital Platform Launch | B2B procurement disintermediation captures standardized maintenance coating volume. |
| Anti-Microbial Functionalization R&D | Silver-ion and copper-oxide modifications address GCC healthcare construction specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with coating formulators, applicator network managers, and sovereign project procurement officers; and secondary validation through SASO technical regulation filings, GCC customs trade databases, and Estidama/Mostadam certification registries. Bottom-up volume triangulation from megaproject coating specifications was cross-checked against top-down market sizing from regional production capacity disclosures.
Forecast inputs across the projection horizon incorporated product type segmentation by formulation chemistry, end-use industry concentration in construction versus marine, and technology adoption curves for electrostatic application systems. CAGRs were derived from elasticity modeling against Saudi Vision 2030 infrastructure spend trajectories and green building mandate enforcement timelines. Industry-specific inputs included Mostadam compliance deadline schedules and Aramco offshore field development coating procurement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese TiO2 producers or accelerated powder coating line investments by Saudi industrial city operators would shift outcomes. Quarterly review of SASO regulatory amendment notices and sovereign project developer master service agreement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Primer Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Paints and Coatings Additives Market