
 Automotive Conformal Coatings Market | 2026-2036
Automotive Conformal Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Conformal Coatings Market Analysis
A shift from single-source to multi-source procurement of specialty chemicals is rebalancing how automotive electronics manufacturers secure conformal coating supply. Dow leverages its silicone chemistry portfolio to anchor North American supply chains for high-temperature automotive underhood applications. Henkel AG & Co. KGaA competes through its Loctite brand strength and selective coating equipment integration, while Shin-Etsu Chemical Co., Ltd. dominates organosilicon feedstock production for Asian coating formulators.
Automotive conformal coatings are thin polymeric films applied to printed circuit assemblies and electronic components to protect against moisture, thermal cycling, vibration, and corrosive contaminants; typical formulations achieve 25-75 micron dry-film thickness with dielectric strength exceeding 1500 volts per mil. Their primary purpose is extending the operational life of sensors, control modules, and power electronics in harsh vehicle environments. UV-curable acrylics lead product type demand due to instant cure cycles that match high-volume automotive throughput requirements, while water-based formulations gain share as OEMs enforce volatile organic compound reduction targets. Spray coating technology occupies the largest equipment installed base, though selective coating is displacing dip methods for complex multi-board assemblies where masking precision determines yield.
EPA regulations on hazardous air pollutants constrain solvent-based formulation production in the United States, while REACH registration requirements in Europe force suppliers to document full substance toxicity profiles for coating chemistries. China's GB standards for automotive electronics reliability, administered by MIIT, mandate conformal coating on all control units for new energy vehicles. Stakeholders must monitor how battery electric vehicle platform architectures reshape coating specification requirements across powertrain, thermal management, and charging subsystems.
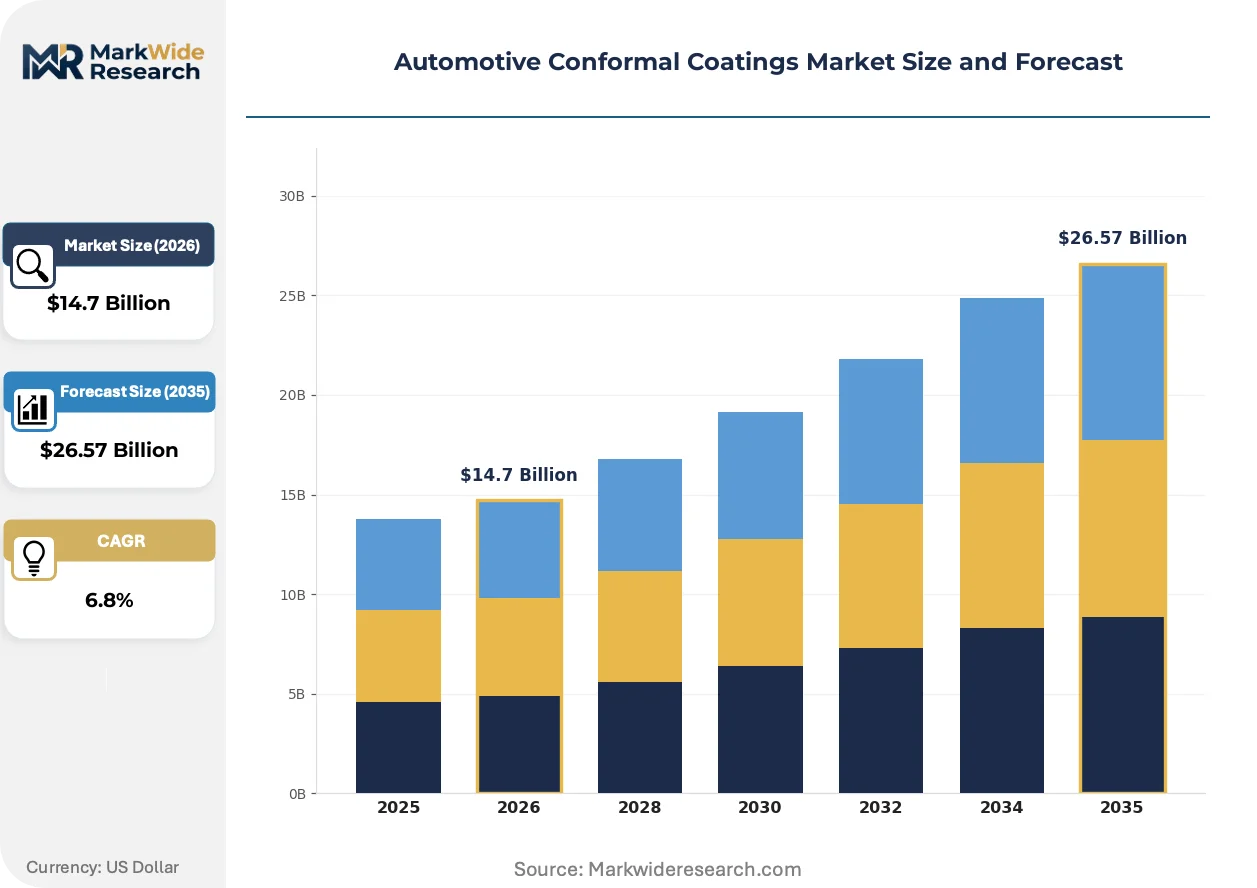
Market Dynamics
Platform electrification is fragmenting coating specifications across powertrain architectures, forcing formulators to engineer chemistries for battery thermal management modules, onboard chargers, and high-voltage inverters simultaneously.
Growth Catalysts
- MIIT GB Standards:China's mandatory conformal coating requirements for new energy vehicle control units are pulling volume through Asian electronics manufacturing clusters.
- UV-Curable Acrylics:Instant cure cycles align with automotive throughput demands while eliminating solvent handling infrastructure.
- Germany:KBA enforcement of electronics reliability standards for autonomous driving systems is expanding coating specifications across sensor modules.
Market Restraints
- Organosilicon Feedstock Concentration:Asian suppliers dominate silicone resin production, creating geographic single-source exposure for high-temperature formulations.
- EPA Hazardous Air Pollutant Rules:Solvent-based acrylic production faces capacity constraints in the United States, compressing domestic supply elasticity.
- Dielectric Thickness Limitations:Sub-25 micron films struggle to meet 1500 volt-per-mil requirements in high-humidity environments, restricting miniaturization pathways.
Strategic Opportunities
- India:PLI scheme incentives for automotive electronics manufacturing are opening greenfield coating demand as OEMs localize control module production.
- Selective Coating Equipment:Precision masking systems for multi-board assemblies represent white space as dip methods reach complexity limits.
- Water-Based Formulations:Volatile organic compound reduction mandates from OEM sustainability programs are accelerating chemistry transitions ahead of regulatory deadlines.
Industry Challenges
- Formulation-Certification Timelines:OEM qualification cycles for new chemistries extend 18-24 months, compressing innovation payback windows.
- Multi-Material Compatibility:Powertrain electronics integrate aluminum substrates, copper traces, and polymer housings, complicating adhesion engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Conformal Coatings Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, UV-Curable, Solvent-Based, Epoxy Technology: Spray Coating, Dip Coating, Brush Coating, Selective Coating End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Electrical Components, Circuit Boards, Sensors, Connectors |
| Companies Covered | Dow, Henkel AG & Co. KGaA, H.B. Fuller, Shin-Etsu Chemical Co., Ltd., Chase Corporation, Electrolube, Dymax Corporation, Specialty Coating Systems, ALTANA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Conformal Coatings Market Emerging Trajectories
Coating application methodologies are fragmenting as vehicle electronics multiply in count and complexity, with precision equipment and chemistry converging to protect densely packed assemblies.
Parylene vapor deposition is decentralizing conformal protection from traditional spray and dip lines into specialized subcontractor facilities. Tier-2 electronics suppliers serving autonomous sensor manufacturers are adopting this technology to achieve pinhole-free coverage on complex geometries. The shift is decentralizing high-reliability coating capacity away from high-volume automotive plants toward niche service providers.
REACH registration requirements are forcing full substance toxicity documentation across European supply chains. ECHA's expanded dossier demands for polymer constituents are extending lead times for new formulation introductions. UV-curable suppliers are responding by pre-registering modified oligomer structures to maintain market access.
Buyer consolidation among automotive electronics manufacturers is compressing supplier negotiation cycles. Tier-1 control module producers are consolidating coating procurement across multiple vehicle programs, displacing program-specific sourcing arrangements. Germany's Bosch and Continental supply bases are most advanced in this transition, with similar patterns emerging in Michigan and Shanghai manufacturing clusters.
Automotive Conformal Coatings Market Segmentation
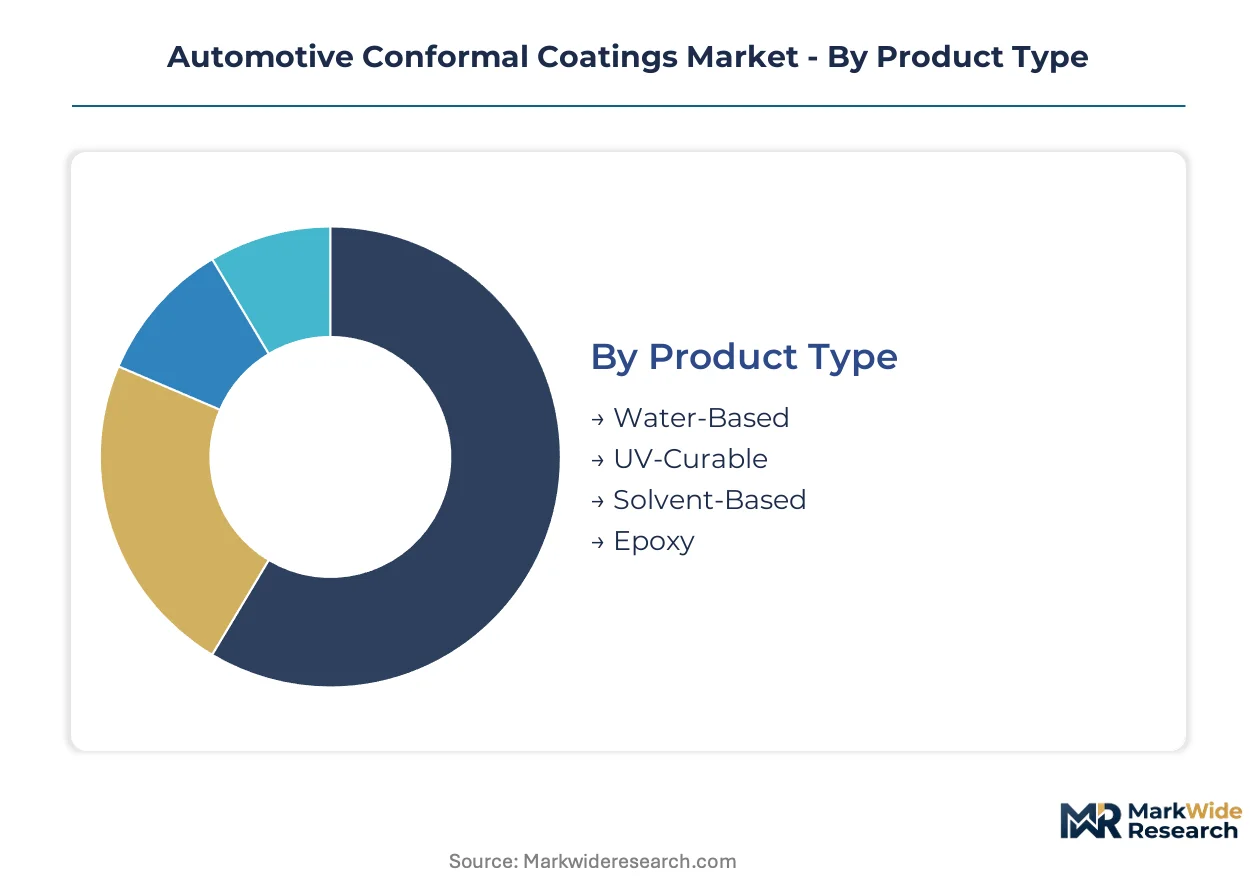
Automotive conformal coatings fragment across formulation chemistry, application method, and supply chain position. Each segmentation dimension carries distinct margin profiles and qualification barriers that shape how suppliers allocate R&D and manufacturing capacity.
Product Type:
Upgrade cycles from solvent-based to cleaner chemistries are compressing as OEM sustainability mandates accelerate ahead of regulatory deadlines.
- UV-Curable:Acrylic oligomers cured by ultraviolet radiation achieve instant polymerization without thermal exposure. Demand concentrates in German and Chinese high-volume electronics plants where throughput requirements exclude conventional drying cycles; REACH compliance is eliminating solvent-handling infrastructure across European supply chains.
- Water-Based:Aqueous acrylic or polyurethane dispersions with zero volatile organic compound emissions. OEM sustainability programs in Michigan and Shanghai are pulling volume through Tier-1 procurement specifications ahead of EPA and MEE enforcement timelines.
- Solvent-Based:Traditional acrylic or urethane solutions in organic carriers. Capacity constraints from EPA hazardous air pollutant rules are compressing domestic US supply elasticity for legacy formulations.
- Epoxy:Two-part thermoset systems delivering chemical resistance for underhood applications. Limited adoption due to extended cure cycles incompatible with automotive line speeds.
Volume placements concentrate in UV-Curable; the faster expansion belongs to Water-Based.
Technology:
Application equipment selection follows board complexity and masking precision requirements rather than pure throughput economics.
- Spray Coating:Pneumatic or airless atomization delivering uniform film deposition. Dominates the installed equipment base across US and German automotive electronics plants serving high-volume control module production.
- Selective Coating:Programmable dispensing systems targeting specific board areas without masking. Demand is climbing fastest in Bosch and Continental supply chains where multi-board assemblies exceed dip method complexity limits.
- Dip Coating:Immersion-based application for simple board geometries. Losing share as component density and keep-out zones proliferate across powertrain electronics.
- Brush Coating:Manual application for repair and low-volume prototyping. Confined to aftermarket repair operations and engineering validation builds.
Equipment procurement concentrates in Spray Coating; selective systems are gaining share fastest in precision-demanding segments.
End User:
Procurement consolidation across vehicle programs is collapsing program-specific sourcing arrangements into enterprise-wide coating specifications.
- Tier-1 Suppliers:Control module manufacturers purchasing coatings for captive application. Bosch, Continental, and Denso procurement teams are consolidating specifications across powertrain and sensor programs.
- OEMs:Vehicle manufacturers with in-house electronics manufacturing. Tesla and BYD vertical integration strategies include captive coating lines for battery management systems.
- Vehicle Assemblers:Final assembly operations with limited electronics integration. Minimal direct coating procurement; specifications flow through Tier-1 contracts.
- Aftermarket Providers:Repair and remanufacturing operations. Fragmented demand with tolerance for longer cure cycles absent in original production.
Contract value concentrates in Tier-1 Suppliers; OEM direct procurement is expanding most quickly through vertical integration.
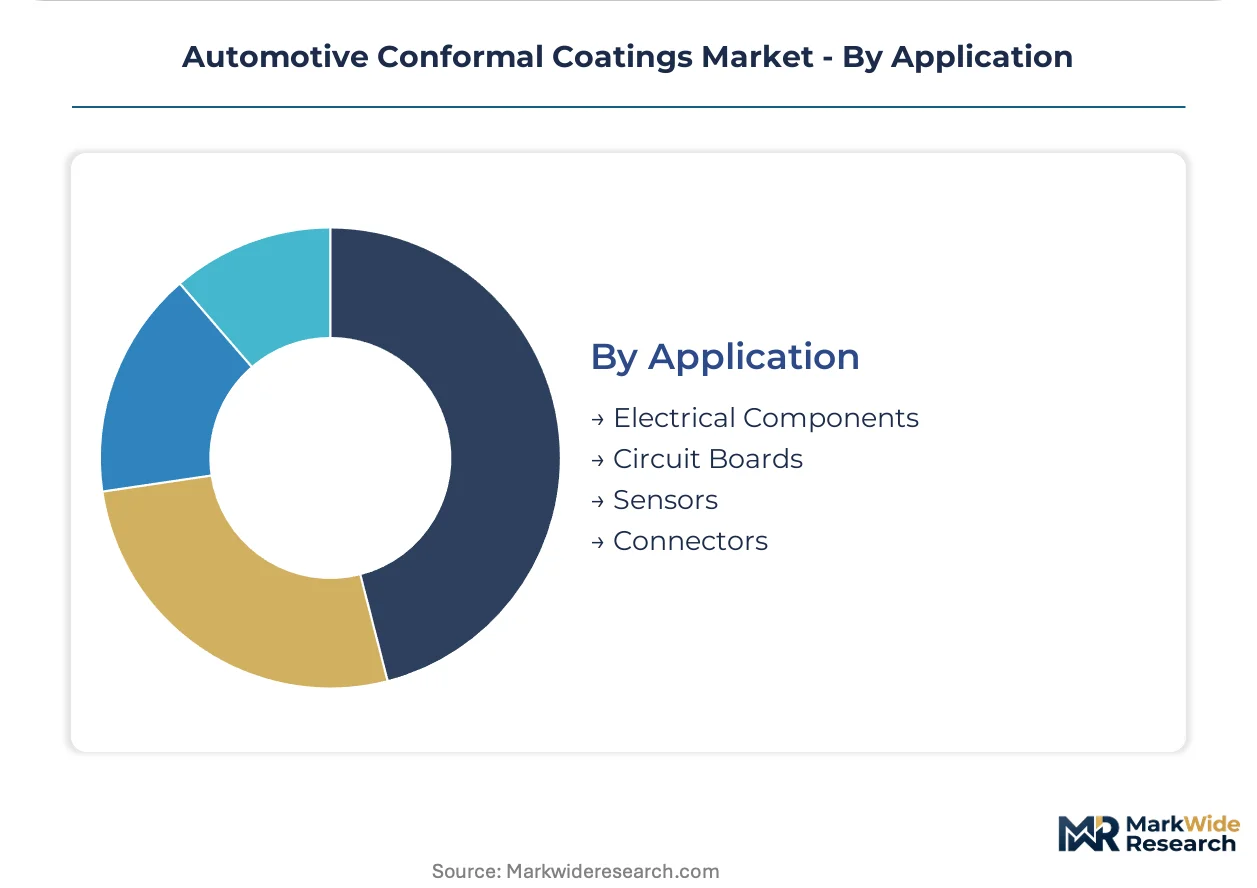
Application:
Component miniaturization and voltage escalation are fragmenting coating specifications across protective thickness and dielectric requirements.
- Circuit Boards:Printed circuit assemblies requiring complete surface coverage. MIIT GB standards mandate conformal coating on all new energy vehicle control units, pulling volume through Chinese electronics manufacturing clusters.
- Sensors:Autonomous driving and ADAS modules with complex geometries. KBA enforcement of electronics reliability standards in Germany is expanding specifications across lidar and radar sensor modules.
- Electrical Components:Discrete parts including capacitors and resistors. Standardized protection requirements with limited specification differentiation.
- Connectors:Interface components requiring selective coverage to preserve mating surfaces. Precision masking demands favor selective coating equipment adoption.
Coated area concentrates in Circuit Boards; sensor applications are climbing the fastest on autonomous vehicle platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing clusters in Germany, China, and the United States absorb the majority of automotive conformal coating procurement. These three markets concentrate Tier-1 control module production and enforce distinct regulatory frameworks that reshape formulation requirements.
Germany
Autonomous driving sensor modules and powertrain electronics drive coating demand across Bavarian and Baden-Württemberg manufacturing corridors. KBA enforcement of electronics reliability standards for ADAS components expands specification requirements for lidar and radar assemblies. Stuttgart and Munich host Continental and Bosch procurement teams consolidating enterprise-wide coating contracts.
China
New energy vehicle platform proliferation pulls volume through Yangtze River Delta and Pearl River Delta electronics clusters. MIIT GB standards mandate conformal coating on all control units for battery electric vehicles, creating regulatory pull-through for UV-curable formulations. Shanghai and Shenzhen manufacturing bases serve BYD and domestic OEM captive electronics operations.
United States
Michigan and Ohio automotive electronics corridors anchor North American demand for high-temperature underhood formulations. EPA hazardous air pollutant rules constrain solvent-based acrylic production capacity, compressing domestic supply elasticity. Detroit-area Tier-1 suppliers operate captive coating lines for powertrain control modules.
Japan
Hybrid powertrain electronics and precision sensor manufacturing sustain coating demand across Kanto and Kansai industrial belts. METI carbon neutrality roadmaps accelerate solvent-to-UV formulation transitions in automotive supply chains. Nagoya and Osaka electronics subcontractors serve Toyota and Honda control module specifications.
India
PLI scheme incentives for automotive electronics manufacturing open greenfield coating demand as OEMs localize control module production. BIS certification requirements for automotive electronics reliability create entry barriers for imported formulations. Tamil Nadu and Gujarat electronics manufacturing clusters attract Tier-1 suppliers establishing regional coating operations.
Automotive Conformal Coatings Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers align regional production with electrification-driven demand spikes. The vendor base concentrates among diversified chemical conglomerates and specialty coating specialists, with limited mid-tier presence between these poles. Two strategic archetypes define competitive positioning: integrated resin-to-formulation operators controlling feedstock access, and application-technology bundlers integrating coating chemistry with selective dispensing equipment. Geographic expansion and portfolio diversification represent the dominant competitive moves, with suppliers establishing technical service laboratories adjacent to major automotive electronics clusters.
Within the integrated chemical conglomerate tier, Dow and Shin-Etsu Chemical Co., Ltd. exemplify contrasting geographic anchors for feedstock-to-formulation supply chains. Henkel AG & Co. KGaA occupies a position bridging European automotive OEM relationships with equipment-integrated coating systems. These three entities represent distinct competitive positioning vectors: North American silicone chemistry depth, Asian organosilicon feedstock dominance, and European application-technology bundling.
| Leading Market Players |
|---|
| Dow |
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| Shin-Etsu Chemical Co., Ltd. |
| Chase Corporation |
| Electrolube |
| Dymax Corporation |
| Specialty Coating Systems |
| ALTANA AG |
| Others |
Supply Flow & Price Mechanics
Captive coating line ownership among Tier-1 suppliers anchors both supply security and pricing leverage across automotive electronics manufacturing clusters. Bosch, Continental, and Denso operate in-house application facilities that insulate procurement from spot-market volatility while compressing third-party formulator margins through volume consolidation.
Pricing Analysis
Warranty bundling separates coating procurement into performance-guaranteed supply contracts versus bare-material transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales technical support inclusion. Cost compression in standard-grade UV-curable formulations is intensifying because Chinese domestic suppliers are expanding capacity under MIIT GB standard compliance. Aftermarket repair operations exhibit highest price sensitivity due to tolerance for extended cure cycles absent in original production.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns as OEMs localize control module production. Silicone resin production concentrates in Japan, Germany, and the United States, while acrylic oligomer synthesis feeds from Chinese and German chemical corridors. Formulators draw from organosilicon feedstock, photoinitiator chemicals, and specialty solvent carriers. Single-source vulnerability persists in high-purity silicone resin supply. Distribution runs through direct technical service relationships with Tier-1 procurement teams rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organosilicon feedstock concentration in Asian supply chains props pricing power for integrated resin-to-formulation operators, constraining margin expansion for non-integrated competitors.
For Market Incumbents: Cement feedstock security through long-term supply agreements with Shin-Etsu Chemical or Dow silicone divisions. Expand technical service laboratory footprint adjacent to Stuttgart, Shanghai, and Detroit electronics clusters to defend against emerging Asian formulators capturing MIIT GB-mandated volume. For New Entrants and Emerging Players: Begin with selective coating equipment-chemistry bundles targeting Bosch and Continental supply chain complexity limits. India's PLI scheme incentives offer the most penetrable geography for greenfield coating operations. Pursue BIS certification pathways to unlock Tamil Nadu and Gujarat manufacturing demand. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking automotive electronics exposure. Five-to-ten year viability hinges on UV-curable formulation patent estates and MIIT GB standard compliance capabilities. Watch for MIIT expanding coating mandates beyond control units to sensor modules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Resin | Secures supply continuity against Asian feedstock concentration for high-temperature formulations. |
| Selective Coating Equipment-Chemistry Bundling | Captures precision masking demand from Bosch and Continental multi-board assembly complexity. |
| Technical Service Laboratory Expansion | Accelerates OEM qualification cycles that currently extend 18-24 months for new chemistries. |
| Water-Based Formulation Transition | Anticipates EPA and MEE enforcement timelines ahead of OEM sustainability mandates. |
| India PLI Scheme Localization | Positions for BIS-certified supply as OEMs shift control module production to Tamil Nadu clusters. |
Methodological Framework
SEC 10-K filings, chemical industry association reports, and customs trade data formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, coating application equipment specialists, and aftermarket distributors validated formulation demand patterns. Bottom-up volume estimates triangulated against top-down market sizing across chemistry type, application method, and end-user segment.
Historical trendline analysis of automotive electronics production volumes, coating content per vehicle, and formulation substitution rates established baseline growth parameters. Segmentation modeling spanned product chemistry, application technology, end-user category, and regional production cluster dimensions. CAGRs derived from slope analysis of normalized adoption curves, with specific inputs including MIIT GB standard implementation timelines and REACH registration completion rates.
Underlying measurement precision varies by segment; UV-curable and water-based formulation forecasts carry tighter precision than emerging parylene vapor deposition estimates. Forecasts reflect documented assumptions regarding electrification penetration and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Industrial Floor Coatings Market
Coatings
OEM Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Biopolymer Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
FBE Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Italy Protective Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
In-Mold Coatings Market
Coatings
United States Floor Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Global Powder Coating Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Global Heat Resistant Coatings Market