
 Middle-East and Africa Fluoropolymers Market | 2026-2036
Middle-East and Africa Fluoropolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Fluoropolymers Market Foresight
Multi-source procurement among petrochemical end-users is restructuring supply relationships across the Middle-East and Africa Fluoropolymers Market. The Chemours Company anchors its regional position through backward integration into fluorspar refining and local compounding partnerships. AGC Inc competes on high-purity FEP grades tailored to semiconductor fabrication standards now penetrating Gulf electronics manufacturing zones. Solvay extends its fluoropolymer film portfolio into coated fabrics for Saudi aerospace maintenance operations.
Fluoropolymers comprise carbon-fluorine backbone polymers such as PTFE, FEP, PFA, and ETFE, synthesized through free-radical polymerization of fluorinated monomers at elevated pressures with thermal stability exceeding 260°C and dielectric constants below 2.1. These properties render them indispensable for chemical containment, electrical insulation, and extreme-environment sealing across industrial process equipment. PTFE dominates volume throughput in chemical processing applications where aggressive acid and alkali resistance govern material selection, while ETFE film architectures command premium positioning in architectural and photovoltaic glazing systems. PFA grades are gaining fastest in medical device tubing as Gulf healthcare infrastructure expands catheter and endoscope manufacturing capacity.
SFDA and MOHAP biocompatibility protocols are tightening fluoropolymer validation requirements for medical device imports into Saudi Arabia and the UAE, diverting procurement toward ISO 10993-certified suppliers. REACH-aligned substance restrictions from European trade partners are propagating through Gulf supply chains, pressuring reformulation of legacy PTFE processing aids. Stakeholders must monitor evolving Gulf Standards Organization harmonization timelines and localize testing capabilities to preempt regulatory fragmentation across national borders.
Market Dynamics
Multi-source procurement among petrochemical end-users is restructuring supply relationships across the Middle-East and Africa Fluoropolymers Market, as Gulf operators diversify away from single-source dependencies toward qualified supplier pools.
Growth Catalysts
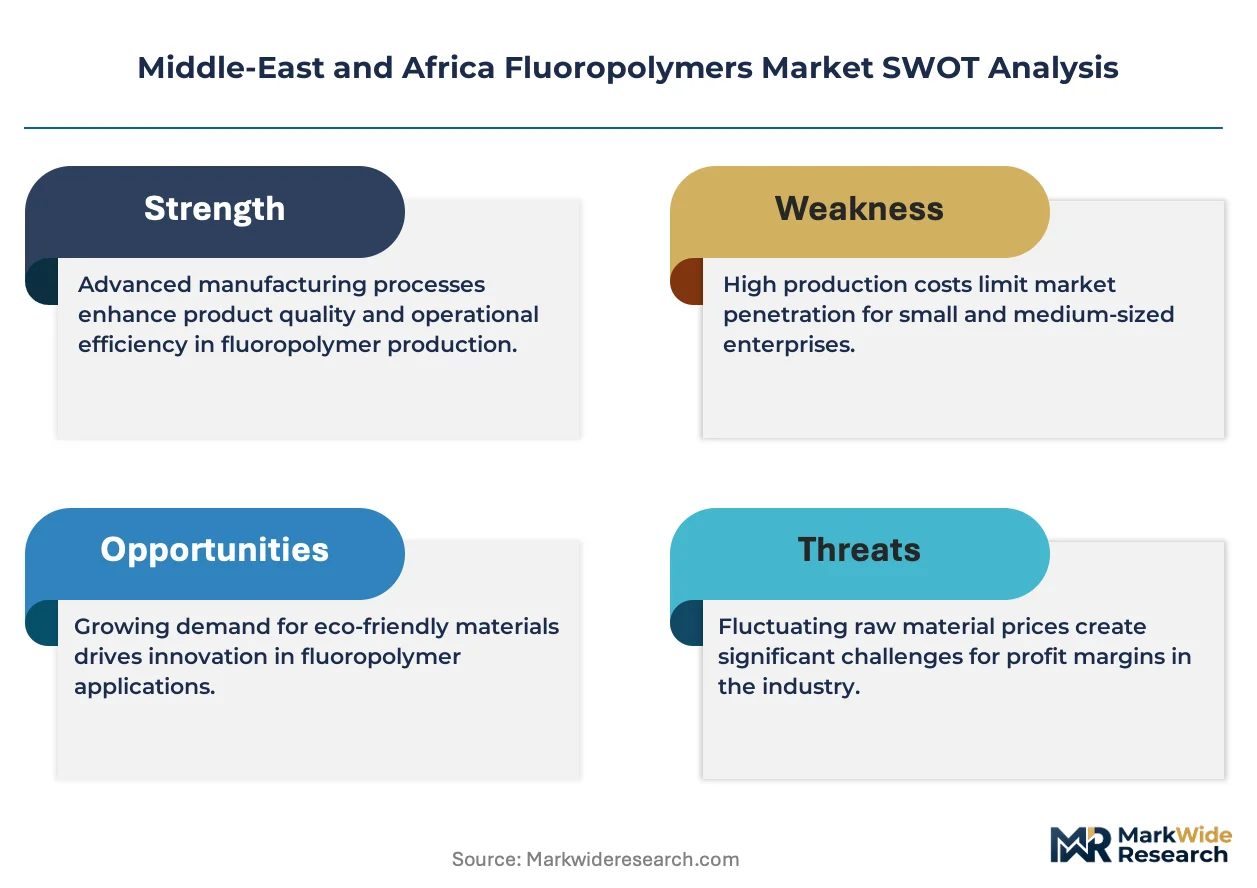
- Vision 2030 Localization:Saudi Arabia's downstream petrochemical expansion mandates domestic value-addition, accelerating fluoropolymer consumption in seals, linings, and process equipment for new crackers and aromatics complexes.
- F-Gas Regulation Alignment:REACH-equivalent chemical controls propagated through European trade partnerships are elevating compliance-grade material specifications across Gulf supply chains.
- Sour Gas Infrastructure:Corrosion-resistant fluoropolymer formulations are penetrating high-H2S extraction environments in Kuwait and Qatar where metallurgical failures drive material substitution.
Market Restraints
- Fluorspar Supply Concentration:Captive ore access concentrates among Chinese state-linked refiners, exposing Gulf compounders to feedstock disruption and volatile acid-grade pricing.
- PTFE Processing Aid Restrictions:Long-chain perfluorinated substance bans under EU PFOA regulations are forcing reformulation of legacy sintering aids without performance-equivalent substitutes.
- High-Performance Resin Cost Structure:PFA and ETFE grades carry 4-7x PTFE price multiples, limiting penetration in cost-sensitive water treatment and construction membrane applications.
Strategic Opportunities
- Egyptian Manufacturing Corridor:Suez Canal Economic Zone incentives and natural gas feedstock access position the country for fluoropolymer compounding and medical tubing extrusion serving African markets.
- Semiconductor Fabrication Standards:High-purity FEP grades certified to SEMI specifications are penetrating Gulf electronics manufacturing zones in Dubai Silicon Oasis and King Abdullah Economic City.
- SFDA Biocompatibility Pathways:Saudi medical device registration reforms are creating first-mover advantage for ISO 10993-certified fluoropolymer suppliers in catheter and endoscope markets.
Industry Challenges
- Polymer Processing Expertise Deficit:Gulf technical institutes lack specialized training programs for fluoropolymer sintering, compounding, and thin-film extrusion, constraining workforce pipeline expansion.
- Cross-Border Certification Fragmentation:Divergent biocompatibility validation timelines between SFDA and MOHAP are duplicating testing costs for suppliers serving both Saudi and UAE medical device markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Fluoropolymers Market |
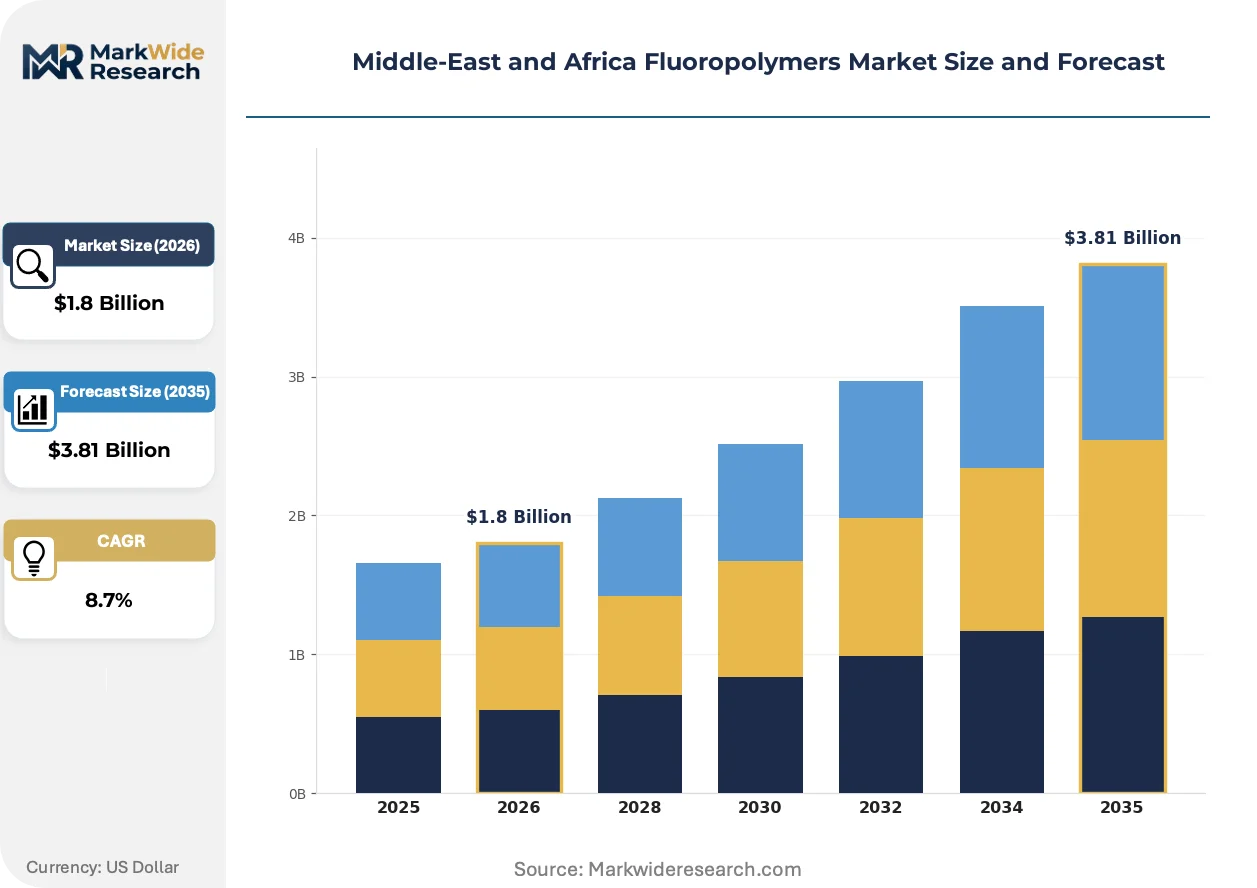
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE Application: Chemical Processing, Electrical Insulation, Coatings, Medical Devices End User: Aerospace, Automotive, Electronics, Oil & Gas Form: Non-Fibrous, Coated Fabrics, Films, Sheets |
| Companies Covered | 3M, AGC Inc, DAIKIN INDUSTRIES, Ltd., The Chemours Company, Arkema Group, Solvay, DuPont, KUREHA CORPORATION, Al-Rashed Fasteners, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Fluoropolymers Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance thresholds across Middle-East fluoropolymer applications.
Perfluoroalkoxy alkane (PFA) resin grades with sub-50 ppm metallic contamination are overtaking conventional FEP in semiconductor fluid handling systems. Abu Dhabi-based chip packaging facilities are specifying these materials for wet chemical delivery manifolds. The transition is compressing qualification timelines for legacy fluoropolymer suppliers without high-purity refining capabilities.
SFDA and MOHAP biocompatibility protocols are tightening validation requirements for medical device imports into Saudi Arabia and the UAE. Gulf healthcare infrastructure expansion is diverting procurement toward suppliers with established ISO 10993 test data packages. European and Asian compounders with pre-certified material portfolios are capturing catheter and endoscope tubing contracts ahead of regional qualification completion.
Petrochemical operators are consolidating qualified supplier pools from fragmented vendor bases toward dual-source frameworks with technical audit requirements. Aramco and ADNOC downstream affiliates are mandating fluoropolymer seal and lining vendors demonstrate captive compounding or backward ore integration. The shift is visible in Jubail Industrial City procurement specifications, where single-source PTFE bearing suppliers face disqualification from maintenance contract renewals.
Middle-East and Africa Fluoropolymers Market Segmentation
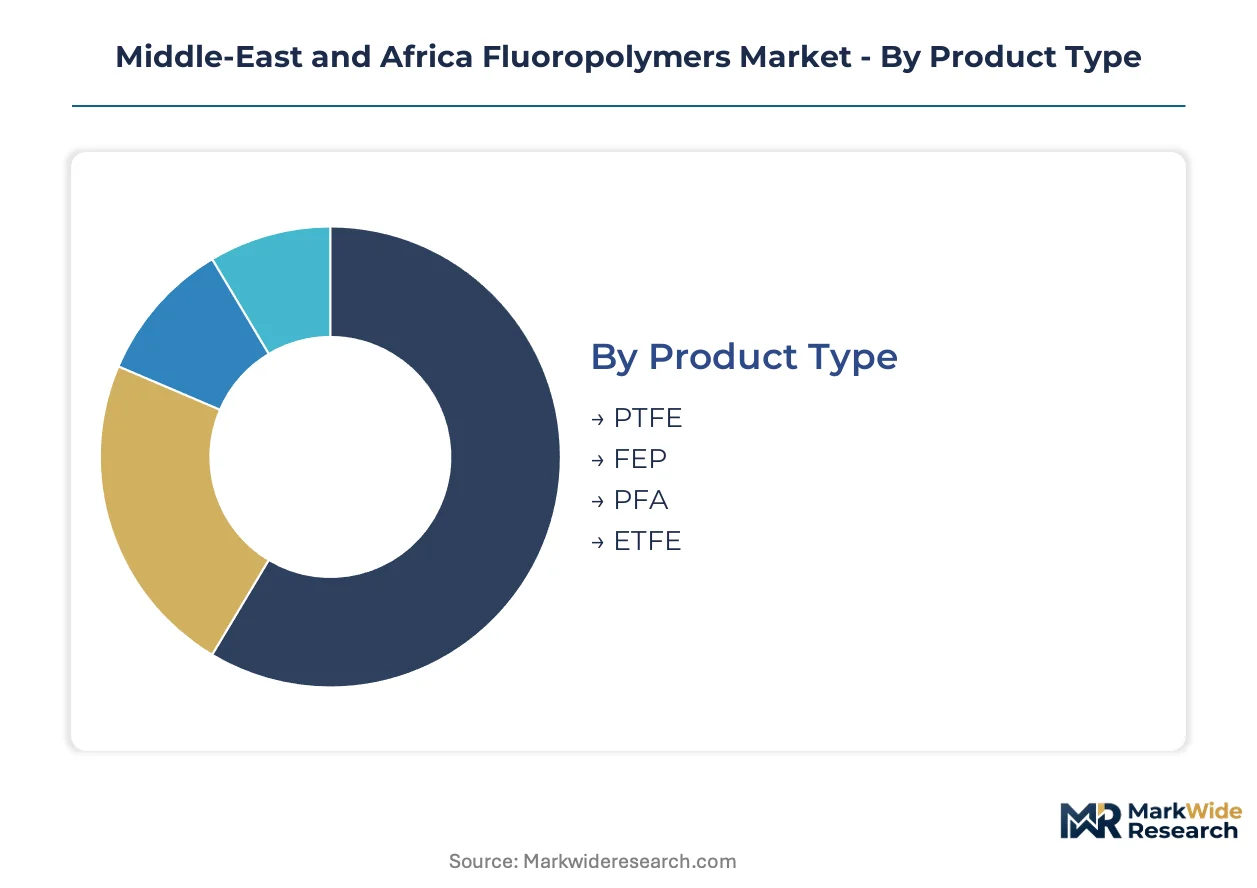
Fluoropolymer procurement patterns across the Middle-East and Africa diverge sharply between standalone component sales and embedded system supply. Understanding these integration depths reveals where Gulf petrochemical operators prioritize captive compounding versus merchant resin purchasing.
Product Type:
Integration depth varies substantially across fluoropolymer chemistries, with some grades dominating discrete component fabrication while others penetrate as formulated compounds within OEM supply chains.
- PTFE:Polytetrafluoroethylene constitutes the carbon-fluorine backbone polymer synthesized through free-radical polymerization of tetrafluoroethylene monomer, delivering thermal stability exceeding 260°C and dielectric constants below 2.1. Demand concentrates in Saudi Arabia's Jubail Industrial City where Aramco downstream affiliates specify virgin resin for seals and linings in sour gas processing equipment. Legacy processing aid restrictions under EU PFOA regulations are forcing reformulation of sintering compounds without performance-equivalent substitutes.
- FEP:Fluorinated ethylene propylene copolymer offers melt-processability advantages over PTFE through its lower molecular weight and reduced crystallinity, enabling thin-wall extrusion for wire insulation and tubing applications. Dubai Silicon Oasis chip packaging facilities are qualifying high-purity FEP grades for wet chemical delivery manifolds, compressing timelines for suppliers without semiconductor-grade refining capabilities.
- PFA:Perfluoroalkoxy alkane grades with sub-50 ppm metallic contamination are penetrating catheter and endoscope tubing as Gulf healthcare infrastructure expands manufacturing capacity under SFDA biocompatibility protocols.
- ETFE:Ethylene tetrafluoroethylene film architectures command premium positioning in architectural glazing systems and photovoltaic backsheet applications across UAE solar installations.
PTFE leads volumes today; PFA is gaining share fastest.
Application:
Cost tier stratification separates commodity-grade process equipment specifications from premium medical and semiconductor certifications that command 4-7x price multiples.
- Chemical Processing:Acid and alkali-resistant linings, gaskets, and seals for reactors and storage vessels handling aggressive media across Kuwait and Qatar high-H2S extraction environments. Metallurgical failure rates in sour gas infrastructure are accelerating material substitution toward fluoropolymer formulations.
- Electrical Insulation:High-voltage cable jacketing and connector housings for subsea umbilicals and downhole electrical systems in offshore Abu Dhabi oilfield developments.
- Coatings:Anti-corrosive and non-stick surface treatments applied through powder deposition or liquid dispersion methods for process equipment in Egyptian petrochemical corridors.
- Medical Devices:Biocompatible tubing and implantable component housings subject to ISO 10993 validation requirements under converging SFDA and MOHAP import protocols.
Chemical processing absorbs the largest volume share; medical devices demonstrate the steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent procurement sophistication, with oil and gas majors mandating backward integration audits while electronics assemblers prioritize semiconductor-grade certification.
- Aerospace:Coated fabrics and seals for engine components and fuel systems, with Solvay extending fluoropolymer film portfolios into Saudi aerospace maintenance operations at King Abdullah Economic City.
- Automotive:Fuel line barriers and sensor housings penetrating Gulf vehicle assembly plants as thermal management requirements intensify for electric powertrains.
- Electronics:High-purity fluid handling components for semiconductor fabrication zones in Dubai and Saudi Arabia, where SEMI specification compliance gates supplier qualification.
- Oil & Gas:Seals, packings, and linings for drilling, production, and refining equipment across ADNOC and Aramco downstream affiliates, with multi-source procurement mandates restructuring supply relationships toward qualified supplier pools.
Oil and gas dominates current consumption; electronics represents the fastest-climbing end-use segment.
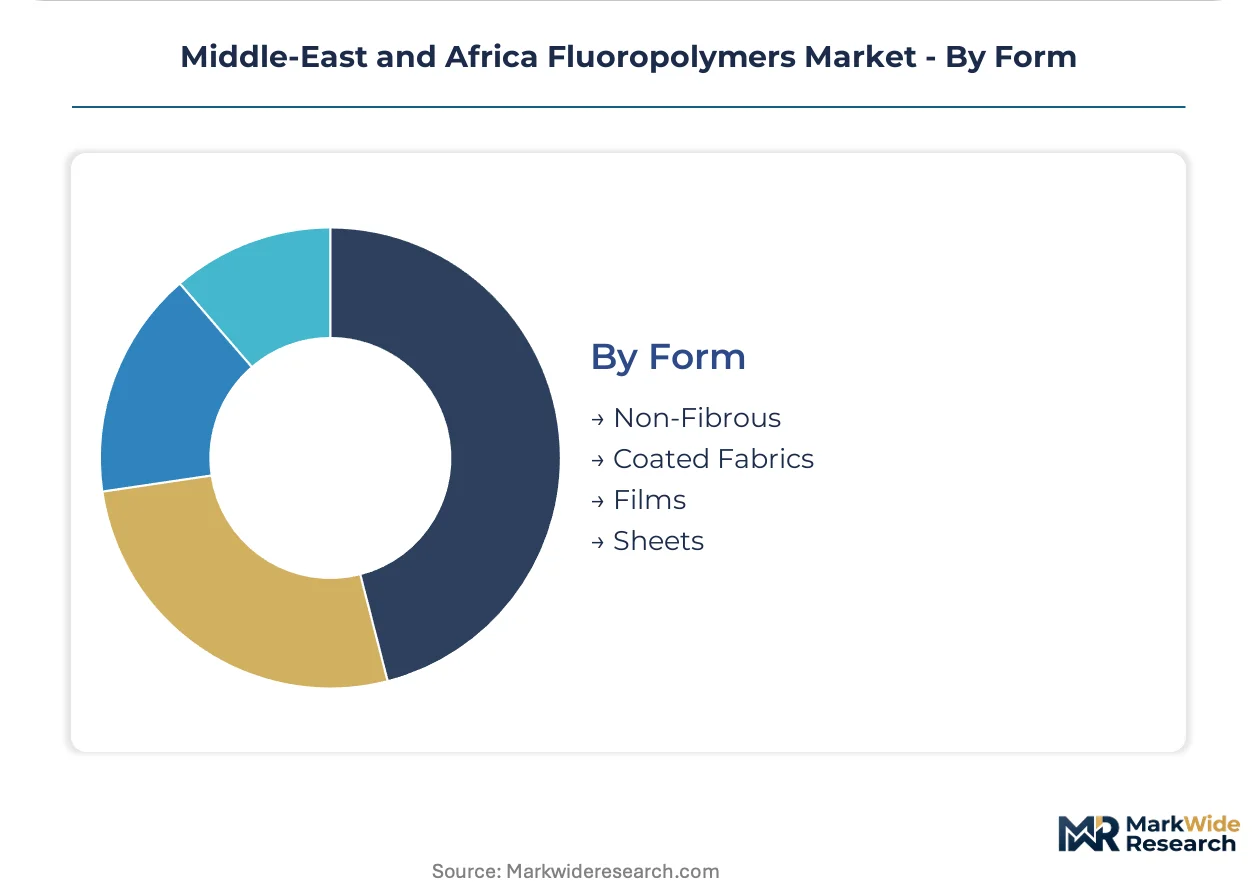
Form:
Supply concentration for finished forms shapes regional compounding investments, with film and sheet extrusion capacity expanding faster than fibrous product manufacturing.
- Non-Fibrous:Molded and machined components including bearings, bushings, and valve seats fabricated from virgin or filled resin stocks for process equipment maintenance.
- Coated Fabrics:Architectural membranes and industrial conveyor belts produced through calendering or dip-coating processes, with ETFE-coated textiles penetrating Saudi aerospace applications.
- Films:Thin-gauge extrusions for photovoltaic backsheets, release liners, and capacitor dielectrics, where biaxial orientation capabilities differentiate supplier technical positioning.
- Sheets:Thick-plate stock for chemical tank linings and semiconductor chamber components, requiring stress-relieved annealing to prevent warping during installation.
Non-fibrous forms anchor present volumes; films are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fluoropolymer compounding investments toward jurisdictions with streamlined chemical registration pathways and preferential feedstock access. Producers evaluate Gulf Standard Organization harmonization timelines against Egyptian Suez Canal Economic Zone incentives when siting regional capacity.
Saudi Arabia
Vision 2030 downstream expansion mandates domestic value-addition in petrochemical equipment, accelerating fluoropolymer consumption for seals and linings. SFDA biocompatibility protocols for medical device imports are tightening validation requirements for catheter and endoscope tubing suppliers. Jubail Industrial City hosts Aramco downstream affiliates specifying virgin PTFE resin for sour gas processing equipment.
United Arab Emirates
MOHAP import controls on medical device materials are converging with Saudi regulatory timelines, though testing cost duplication persists between jurisdictions. Dubai Silicon Oasis chip packaging facilities are qualifying high-purity FEP grades for wet chemical delivery manifolds. Abu Dhabi offshore oilfield developments specify fluoropolymer cable jacketing for subsea umbilicals.
Egypt
Suez Canal Economic Zone incentives and natural gas feedstock access position the country for fluoropolymer compounding serving African markets. The country's national chemical regulator is aligning with REACH-equivalent substance restrictions propagated through European trade partnerships. Egyptian petrochemical corridors are expanding anti-corrosive coating applications for process equipment maintenance.
Qatar
High-H2S extraction environments are accelerating material substitution toward corrosion-resistant fluoropolymer formulations where metallurgical failures previously dominated. National hydrocarbon operators are consolidating qualified supplier pools toward dual-source frameworks with technical audit requirements. Ras Laffan Industrial City maintenance specifications now disqualify single-source PTFE bearing suppliers from contract renewals.
South Africa
Mining equipment refurbishment programs are penetrating fluoropolymer-lined pump housings and valve components for acid handling circuits. The country's national standards body is monitoring EU F-Gas Regulation alignment for imported chemical processing materials. Gauteng industrial zones are expanding coated fabric production for conveyor belt applications in platinum and gold extraction operations.
Middle-East and Africa Fluoropolymers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue semiconductor-grade certification and medical biocompatibility pathways. The supplier base stratifies between backward-integrated ore holders and merchant compounders dependent on acid-grade fluorspar spot markets. Three archetypes dominate: captive refiners with desert-region compounding partnerships, high-purity specialists serving electronics fabrication zones, and regional distributors bridging certification gaps for medical device assemblers. Competitive moves center on dual-source procurement mandates from national oil companies and localization requirements under Gulf industrial policies.
Among Japanese and European material science groups, DAIKIN INDUSTRIES, Ltd., Solvay, and AGC Inc exemplify distinct positioning vectors. DAIKIN INDUSTRIES, Ltd. represents the integrated polymerization-to-compounding archetype with fluorspar access through captive supply arrangements. Solvay occupies a position emphasizing film and coated fabric architectures for aerospace and photovoltaic applications. AGC Inc exemplifies the high-purity specialization path, with its nomenclature suggesting glass and chemical heritage translated into semiconductor-grade fluoropolymer refinement. These three anchors demonstrate how geographic origin and corporate structure shape competitive options without converging on identical capability portfolios.
| Leading Market Players |
|---|
| 3M |
| AGC Inc |
| DAIKIN INDUSTRIES, Ltd. |
| The Chemours Company |
| Arkema Group |
| Solvay |
| DuPont |
| KUREHA CORPORATION |
| Al-Rashed Fasteners |
| Others |
Supply & Pricing Matrix
Specialized fluoropolymer sintering technicians concentrated in Jubail Industrial City and Düsseldorf chemical corridors create labor-cost differentials that widen pricing-tier spreads between merchant compounders and backward-integrated producers.
Pricing Analysis
Distributor margins on semiconductor-grade FEP and PFA resins absorb 12-18 points before reaching Dubai Silicon Oasis fabricators, while direct-to-OEM channels serving Aramco downstream affiliates command volume discounts on virgin PTFE. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from commodity chemical-processing formulations. Cost compression in standard-grade PTFE intensifies as Chinese acid-grade fluorspar spot volatility feeds into Gulf compounder feedstock costs. Electronics assemblers demonstrate least price sensitivity for SEMI-specification materials, while Egyptian water-treatment membrane buyers anchor the economy tier.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Aramco and ADNOC downstream affiliates, while regional distributors bridge certification gaps for medical device assemblers across Saudi Arabia and UAE. Acid-grade fluorspar supply concentrates in Chinese state-linked refiners, Mexican open-pit operations, and South African fluorspar belts. Gulf compounders draw from acid-grade fluorspar, tetrafluoroethylene monomer, and perfluoroalkoxy alkane resin stocks. Single-source vulnerability in Chinese ore access exposes regional processors to feedstock disruption. Distribution runs through qualified supplier pools mandated by national oil company procurement specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Egyptian Suez Canal Economic Zone labor and feedstock costs undercut Gulf compounding economics by meaningful margins, while SFDA-MOHAP regulatory convergence compresses time-to-market for certified suppliers.
For Market Incumbents: Anchor regional positioning through captive fluorspar refining partnerships or local compounding joint ventures in Jubail Industrial City. High-purity FEP specialists from East Asia threaten semiconductor-grade market share; defend through SEMI-specification qualification acceleration and technical audit compliance for Aramco dual-source mandates. Backward integration into acid-grade ore access represents the critical lever for margin defense against Chinese state-linked refiner pricing power. For New Entrants and Emerging Players: The 4-7x price multiple gap between PFA medical grades and commodity PTFE creates entry space for ISO 10993-certified compounders in Egyptian medical tubing extrusion. Target catheter and endoscope supply chains serving African healthcare infrastructure expansion. Pursue Suez Canal Economic Zone manufacturing corridor incentives with natural gas feedstock access as the primary go-to-market angle. For Investors and Strategic Acquirers: National oil company procurement divisions represent the most active strategic buyer category in this space, consolidating qualified supplier pools through technical audit mandates and dual-source frameworks. Long-term viability hinges on localization compliance with Vision 2030 and equivalent Gulf industrial policies rather than pure cost positioning. Acquisition targets should display captive compounding capabilities or established ISO 10993 certification portfolios. Monitor SFDA-MOHAP harmonization timeline acceleration as the signal for regulatory-arbitrage window closure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Refining | Chemours anchors regional supply security through captive ore access in Chinese state-linked partnerships. |
| SEMI Specification Qualification | AGC Inc captures Dubai Silicon Oasis chip packaging demand through high-purity FEP certification. |
| ISO 10993 Certification Investment | European compounders preempt SFDA biocompatibility requirements for Saudi catheter manufacturing expansion. |
| Suez Canal Economic Zone Capacity Buildout | Egyptian natural gas feedstock access positions regional compounding for African market penetration. |
| Dual-Source Procurement Compliance | Aramco and ADNOC maintenance specifications now disqualify single-source PTFE bearing suppliers. |
Research Methodology
Bottom-up fluoropolymer end-use modeling reconciled against top-down fluorspar supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at Jubail Industrial City petrochemical complexes, procurement leads at Aramco downstream affiliates, distribution channel partners serving Egyptian manufacturing corridors, and technical R&D directors at semiconductor-grade compounders were validated against secondary sources including Gulf customs and trade data, SFDA and MOHAP regulatory filings, SEC 10-K disclosures from listed material science groups, and ACC regional chemical industry reports.
Input-output matrices mapping fluorspar refining capacity through monomer polymerization to finished form fabrication generate volume and value estimates across the projection horizon. Segmentation dimensions include fluoropolymer chemistry grade, end-use industry application, finished form type, and regional production hub classification. CAGRs were derived from regression analysis of historical consumption patterns against announced petrochemical capacity expansion and healthcare infrastructure investment pipelines. Forecast inputs incorporate Vision 2030 downstream project timelines and SFDA biocompatibility protocol implementation schedules.
The model assumes a particular technology adoption path for high-purity PFA displacement of conventional FEP in semiconductor fluid handling; alternative pathways for ETFE film architecture penetration in photovoltaic backsheet applications would alter the outlook. Periodic stress-testing of base assumptions against fluorspar spot price volatility and regulatory harmonization timeline slippage is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
United States Geopolymer Market