
 BPA-Free Coatings Market | 2026-2036
BPA-Free Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
BPA-Free Coatings Market Analysis
Market Context
Food packaging is hardening as the dominant demand vertical for BPA-free coatings, displacing legacy industrial metal coating applications where alternatives remain cost-competitive. PPG Industries leverages its waterborne technology portfolio to anchor supply relationships with North American can manufacturers. AkzoNobel competes through specialized epoxy formulations that sustain compliance with evolving food contact material standards.
Technical Definition and Segment Structure
BPA-free coatings are polymeric surface treatments formulated without bisphenol A or its structural analogues, typically employing polyester or acrylic resin backbones with crosslink densities engineered to block chemical migration below regulatory thresholds. These coatings serve primarily to protect metal and plastic substrates in food contact applications while eliminating endocrine-disruptor exposure pathways. Waterborne technology leads volume production due to volatile organic compound restrictions, while radiation cure systems represent the fastest-expanding segment driven by line-speed advantages in high-throughput packaging operations. Powder coating occupies a mature position in industrial end uses where thermal curing constraints limit food-contact applicability.
Regulatory Frame and Outlook
REACH in Europe, FDA food contact notification requirements in the United States, and China's GB standards for food packaging materials collectively shape formulation constraints and testing burdens for coating suppliers. EFSA migration limit assessments and state-level disclosure laws such as California's Proposition 65 are forcing reformulation investments ahead of harmonized standards. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
Market Dynamics
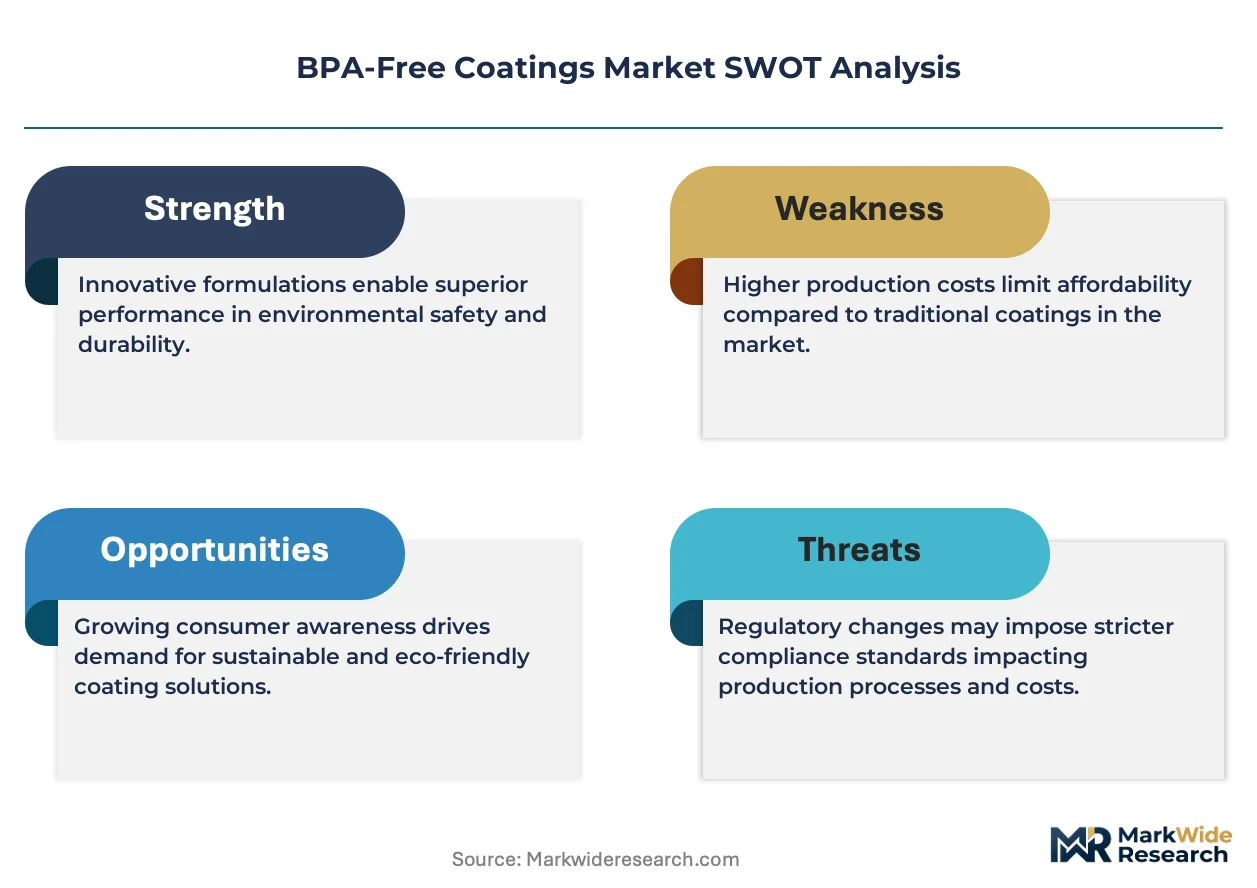
Migration limits under REACH and FDA food contact notifications are forcing simultaneous reformulation across polyester, acrylic, and epoxy resin systems, compressing development timelines and raising testing burdens for coating suppliers serving metal packaging converters.
Growth Catalysts
- EFSA migration assessments:Tightening European thresholds for bisphenol analogues are accelerating replacement cycles in beverage can lining applications. German brand owners now specify BPA-free systems as a procurement condition.
- Waterborne epoxy technology:Low-VOC formulations are capturing volume from solvent-based systems as can manufacturers face volatile organic compound enforcement in California and EU member states.
- China GB standards alignment:SAMR's food packaging material rules are converging with Western migration limits, opening export-qualified capacity for coating producers meeting dual certification.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and epoxy resin prices fluctuate with propylene and bisphenol A derivative markets, compressing formulation margins during crude oil spikes.
- Specialty additive concentration:Crosslinker and catalyst supply concentrates among German and Japanese chemical producers, creating single-source vulnerability for coating compounders.
- Performance gaps in high-acid foods:Polyester-based BPA-free systems exhibit inferior sulfur staining resistance versus legacy epoxy-phenolic coatings in tomato and citrus applications.
Strategic Opportunities
- India FSSAI compliance mandates:Pending food contact material regulations will force domestic metal packaging conversion, creating first-mover advantage for certified coating suppliers.
- Radiation cure line integration:Electron beam and UV systems enable 400+ can-per-minute throughput without thermal curing constraints, reshaping capital planning for high-volume converters.
- Recyclability certification:APR and How2Recycle recognition for mono-material compatible coatings commands price premiums from sustainability-focused CPG brand owners.
Industry Challenges
- Migration testing protocol complexity:Simulant selection and contact time parameters vary between FDA, EFSA, and GB methodologies, requiring redundant analytical expenditure for multi-territory suppliers.
- Can maker qualification timelines:New coating systems require 12-18 month organoleptic and corrosion testing cycles, delaying revenue recognition and straining working capital.
Report Scope
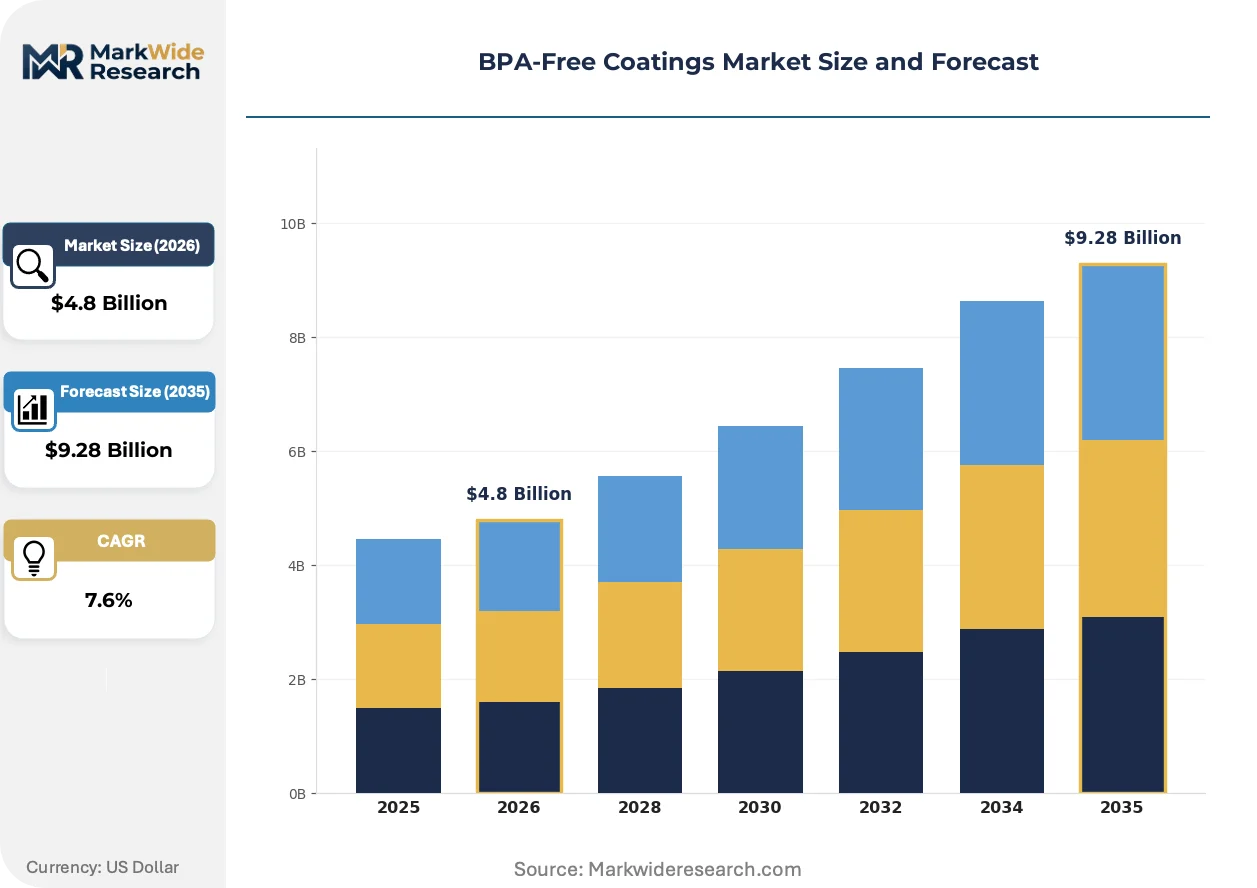
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BPA-Free Coatings Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Polyester Application: Packaging, Automotive, Electronics, Construction End User: Food Industry, Consumer Goods, Industrial, Healthcare Technology: Waterborne, Solvent-based, Powder Coating, Radiation Cure |
| Companies Covered | PPG Industries, AkzoNobel, Sherwin-Williams, Axalta Coatings, Nippon Paint Holdings, Asian Paints, BASF SE, Kansai Paint, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BPA-Free Coatings Market Emerging Trajectories
Formulation science is pivoting toward bio-based resin backbones and accelerated cure chemistries as regulatory migration limits tighten and line-speed economics dominate packaging converter procurement criteria.
Polyester-urethane hybrid systems are overtaking conventional acrylics in two-piece aluminum beverage can applications. North American can manufacturers are adopting these hybrids at pilot scale for acidic beverage compatibility. The technology is overtaking legacy epoxy-phenolic volume in segments where sulfur staining resistance proves acceptable.
REACH restriction proposals for bisphenol S and F analogues are expanding compliance scope beyond BPA alone. Coating suppliers must now certify against entire structural classes, multiplying analytical testing matrices. European metal packaging converters are responding by pre-qualifying third-generation non-bisphenol chemistries ahead of final ECHA determinations.
Direct-to-brand specification influence is displacing traditional can maker-led coating selection. Major beverage and food companies now mandate approved substance lists that constrain converter sourcing flexibility. This pattern concentrates most visibly in Germany and California, where Proposition 65 disclosure requirements and consumer litigation risk elevate procurement compliance functions.
BPA-Free Coatings Market Segmentation
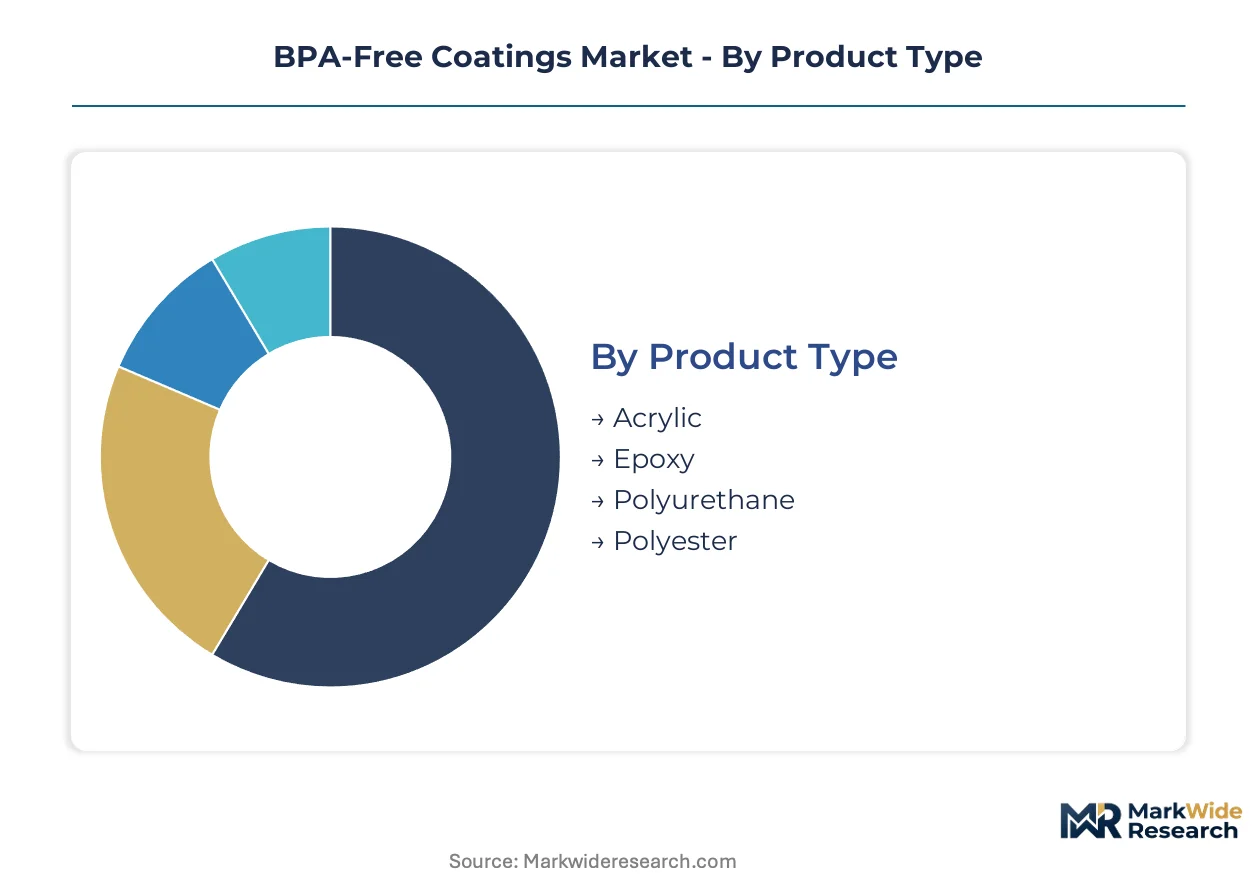
Segmentation in BPA-free coatings reveals how formulation chemistry, curing technology, and end-use compliance requirements fragment procurement patterns. Coating suppliers must align R&D portfolios with divergent capital requirements across resin systems and application methods.
Product Type:
Capital intensity varies sharply across resin backbones, with epoxy and polyurethane systems demanding specialized reactor infrastructure and longer qualification timelines than commodity acrylic alternatives.
- Epoxy:Crosslinked bisphenol-free formulations dominate metal packaging linings due to superior adhesion and chemical resistance. Migration testing under FDA food contact notifications and REACH compliance absorbs the majority of R&D expenditure in this segment. German can manufacturers specify epoxy systems for acidic beverage applications where corrosion resistance is non-negotiable.
- Polyester:Saturated and unsaturated variants serve flexible packaging and industrial metal coatings with faster cure profiles. Waterborne polyester-urethane hybrids are capturing share in two-piece aluminum beverage cans where sulfur staining trade-offs prove acceptable. California-based converters favor these systems for VOC compliance.
- Acrylic:Cost-competitive waterborne acrylics serve general industrial and decorative applications with lower crosslink density requirements.
- Polyurethane:High-performance two-component systems command premium positioning in automotive and electronics protective coatings.
Epoxy absorbs the bulk of installed capacity; polyester is expanding most quickly.
Application:
Regulatory exposure and migration liability concentrate demand in food-contact segments, while industrial applications prioritize cost-per-unit-coverage metrics over compliance documentation.
- Packaging:Beverage can linings, food container interiors, and flexible film laminations constitute the compliance-critical core of BPA-free coating demand. EFSA migration limit assessments and Proposition 65 disclosure requirements in California force continuous reformulation. Brand owners in Germany now mandate BPA-free specifications as standard procurement terms.
- Automotive:Underhood components and interior trim applications prioritize thermal stability and UV resistance over food-contact certification. Powder coating and high-solids solvent systems dominate this segment.
- Electronics:Conformal coatings for printed circuit boards and device housings emphasize dielectric properties and moisture barrier performance.
- Construction:Architectural metal coatings and protective treatments for structural steel emphasize weatherability and application efficiency.
Packaging commands the tightest formulation specifications; electronics is climbing the fastest as device miniaturization intensifies barrier requirements.
End User:
Procurement sophistication diverges between consumer-facing industries with litigation exposure and industrial buyers optimizing total applied cost.
- Food Industry:Metal packaging converters for canned beverages, processed foods, and infant nutrition products face the most stringent migration testing protocols. Direct-to-brand specification influence is displacing traditional can maker-led coating selection. Major beverage companies maintain approved substance lists that constrain converter sourcing flexibility.
- Consumer Goods:Personal care and household product packaging emphasizes aesthetic finish and label adhesion compatibility.
- Industrial:Machinery, equipment, and OEM component manufacturers prioritize throughput and film build consistency.
- Healthcare:Medical device packaging and pharmaceutical containers require biocompatibility certification beyond standard food-contact compliance.
Food industry qualification timelines stretch longest; healthcare is gaining share fastest as sterilization-compatible formulations advance.
Technology:
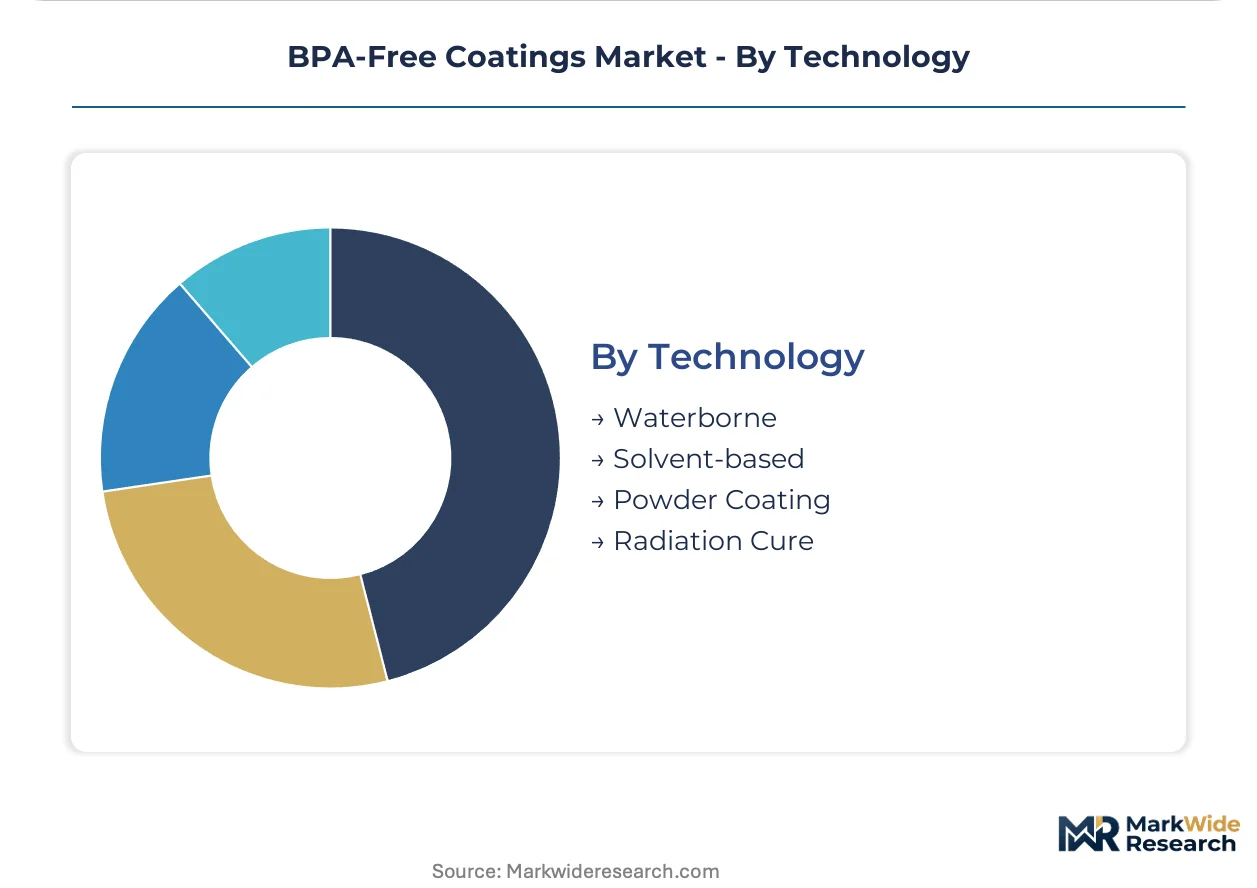
Curing method determines line-speed economics, energy consumption, and substrate compatibility, with waterborne systems requiring lower capital entry than radiation cure infrastructure.
- Waterborne:Low-VOC epoxy and acrylic dispersions have become the default for food packaging converters facing enforcement in California and EU member states. These systems require thermal ovens but avoid solvent recovery capital. PPG Industries and AkzoNobel anchor supply relationships through waterborne portfolio breadth.
- Radiation Cure:Electron beam and UV-curable formulations enable 400+ can-per-minute throughput without thermal curing constraints. Capital requirements for shielding and lamp systems limit adoption to high-volume converters. The technology is reshaping capital planning for North American beverage can manufacturers.
- Solvent-based:High-solids and conventional solvent systems persist in automotive and industrial applications where VOC regulations permit.
- Powder Coating:Thermoset powder systems occupy mature positions in industrial end uses where thermal curing constraints preclude food-contact applicability.
Waterborne technology holds the largest installed base; radiation cure is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's Gujarat Industrial Development Corporation are concentrating coating formulation capacity near food packaging manufacturing clusters.
United States
California's Proposition 65 disclosure requirements and FDA food contact notification enforcement are accelerating waterborne epoxy adoption among West Coast can manufacturers. The FDA maintains stringent migration testing protocols for metal packaging linings. Chicago-area converters are expanding radiation cure pilot lines to serve major beverage brand owners.
Germany
REACH restrictions on bisphenol analogues and EFSA migration limit assessments are compressing reformulation timelines for metal packaging suppliers. The ECHA's expanding scope beyond BPA to bisphenol S and F is forcing third-generation chemistry pre-qualification. Bavarian chemical producers dominate specialty crosslinker supply for coating compounders.
China
SAMR's GB standards alignment with Western migration limits is opening export-qualified capacity for dual-certified coating producers. The MIIT's food packaging material regulations are converging with FDA and EFSA thresholds. Yangtze River Delta coating plants are scaling waterborne polyester-urethane production for two-piece aluminum beverage cans.
India
FSSAI's pending food contact material compliance mandates are forcing domestic metal packaging conversion ahead of formal enforcement. The BIS is developing harmonized testing protocols aligned with international standards. Gujarat-based converters are pre-qualifying BPA-free epoxy systems for infant nutrition and processed food applications.
Japan
METI's chemical substance management policies and PMDA's biocompatibility requirements are shaping coating specifications for pharmaceutical and food-contact applications. JIS standards for food packaging materials emphasize migration control. Kansai-region coating compounders are developing radiation-curable formulations for high-throughput canning lines.
BPA-Free Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation science leaders capturing premium positioning in food-contact applications while regional compounders serve industrial end uses. The market structure concentrates among diversified chemical conglomerates with resin backward integration and specialized coating houses with regulatory certification depth. Three archetypes dominate: integrated resin-coating suppliers, application-technology licensors, and regional formulation specialists. Competitive moves center on dual-certification capacity expansion and radiation cure technology licensing to high-volume converters.
Among North American diversified coating suppliers, PPG Industries and Sherwin-Williams occupy positions anchored by waterborne technology portfolios and established supply relationships with can manufacturers. AkzoNobel represents the European specialist archetype with concentrated expertise in epoxy formulations serving migration-sensitive applications.
| Leading Market Players |
|---|
| PPG Industries |
| AkzoNobel |
| Sherwin-Williams |
| Axalta Coatings |
| Nippon Paint Holdings |
| Asian Paints |
| BASF SE |
| Kansai Paint |
| RPM International |
| Others |
Supply Flow & Price Mechanics
Epoxy resin feedstock costs originating from propylene derivative markets transmit directly through coating compounder margins into tiered pricing for food-contact-certified systems. This cost cascade separates premium dual-certified epoxy formulations from standard waterborne acrylics and economy-grade industrial coatings.
Pricing Analysis
Lead-time premiums attach to radiation-curable systems with 12-18 month can maker qualification timelines, while spot inventory discounts appear for commodity waterborne acrylics with shorter certification cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA food contact notification and REACH dual-certified epoxy commanding the highest tier. Pricing pressure stems from petrochemical feedstock volatility compressing formulation margins during crude oil spikes. Industrial coating buyers exhibit highest price sensitivity; food packaging converters with brand-owner mandates show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese chemical producers dominating specialty crosslinker and catalyst supply for coating compounders. Manufacturing capacity concentrates in China, Germany, and the United States, with Yangtze River Delta and Bavarian chemical clusters anchoring regional production. Raw material dependencies include acrylic acid, epoxy resins, and polyester polyols. Tariff exposure on Chinese-sourced intermediates creates structural risk for North American formulators. Distribution runs through direct supply relationships with metal packaging converters and authorized distributor networks serving industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH migration limit expansions and redundant certification burdens force smaller compounders without dual-certification capacity toward exit or acquisition.
For Market Incumbents: Hedge against bisphenol S and F analogue restrictions by pre-qualifying third-generation non-bisphenol chemistries ahead of final ECHA determinations. Acquire specialty crosslinker capabilities through backward integration into German or Japanese chemical suppliers to neutralize single-source vulnerability. Lock in radiation cure technology licensing agreements with high-volume North American beverage can manufacturers before competitors establish anchor positions. For New Entrants and Emerging Players: Launch via private-label supply relationships with India-based metal packaging converters preparing for FSSAI compliance mandates. Target infant nutrition and processed food applications in Gujarat where domestic conversion creates first-mover advantage. Enter through certified toll manufacturing arrangements with established compounders lacking India-specific regulatory expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor dual-certified coating specialists with REACH and FDA food contact notification depth in European geographies. Long-term viability centers on consolidation of formulation science capabilities serving migration-sensitive applications. Monitor ECHA restriction proposal finalization as the signal indicating accelerated replacement cycle timing and valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | REACH and FDA food contact notification compliance opens export-qualified production for Yangtze River Delta plants. |
| Radiation Cure Technology Licensing | Electron beam and UV system partnerships enable 400+ can-per-minute throughput for high-volume North American converters. |
| Backward Integration into Crosslinkers | Captive supply of specialty catalysts from German chemical producers neutralizes single-source vulnerability in formulation. |
| Recyclability Certification Program | APR and How2Recycle recognition commands price premiums from sustainability-focused CPG brand owners in California. |
| Joint Venture with Can Manufacturers | Co-development agreements with German beverage can makers accelerate 12-18 month organoleptic testing cycles. |
Methodological Framework
Multi-period observation of EFSA migration limit assessments, FDA food contact notification filings, and SAMR GB standards alignment anchored the trend analysis, supplemented by interviews with coating formulation R&D directors, metal packaging converter procurement leads, brand owner sustainability officers, and regulatory affairs specialists at chemical producers. Secondary validation drew from ECHA restriction proposal documentation, SEC 10-K filings of diversified coating suppliers, customs and trade data on epoxy resin and acrylic acid flows, and industry association reports from Cefic and the American Coatings Association. Bottom-up volume modeling across resin backbones, curing technologies, and end-use segments triangulated against top-down market sizing.
Input-output matrices connected petrochemical feedstock pricing, formulation cost structures, and end-user procurement budgets across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, curing technology type, food-contact versus industrial application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution rates from legacy epoxy-phenolic systems and line-speed economics for radiation cure adoption. Forecast inputs included REACH restriction timeline probabilities and FSSAI compliance mandate implementation sequencing.
Petrochemical price volatility, regulatory divergence between EFSA and FDA methodologies, and can maker qualification timeline extensions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about migration limit harmonization and dual-certification adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Hard Coating Market
Coatings
Superhydrophobic Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Mold Release Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Global Coil Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market