
 Middle East Activated Carbon Market | 2026-2036
Middle East Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Activated Carbon Market Intelligence
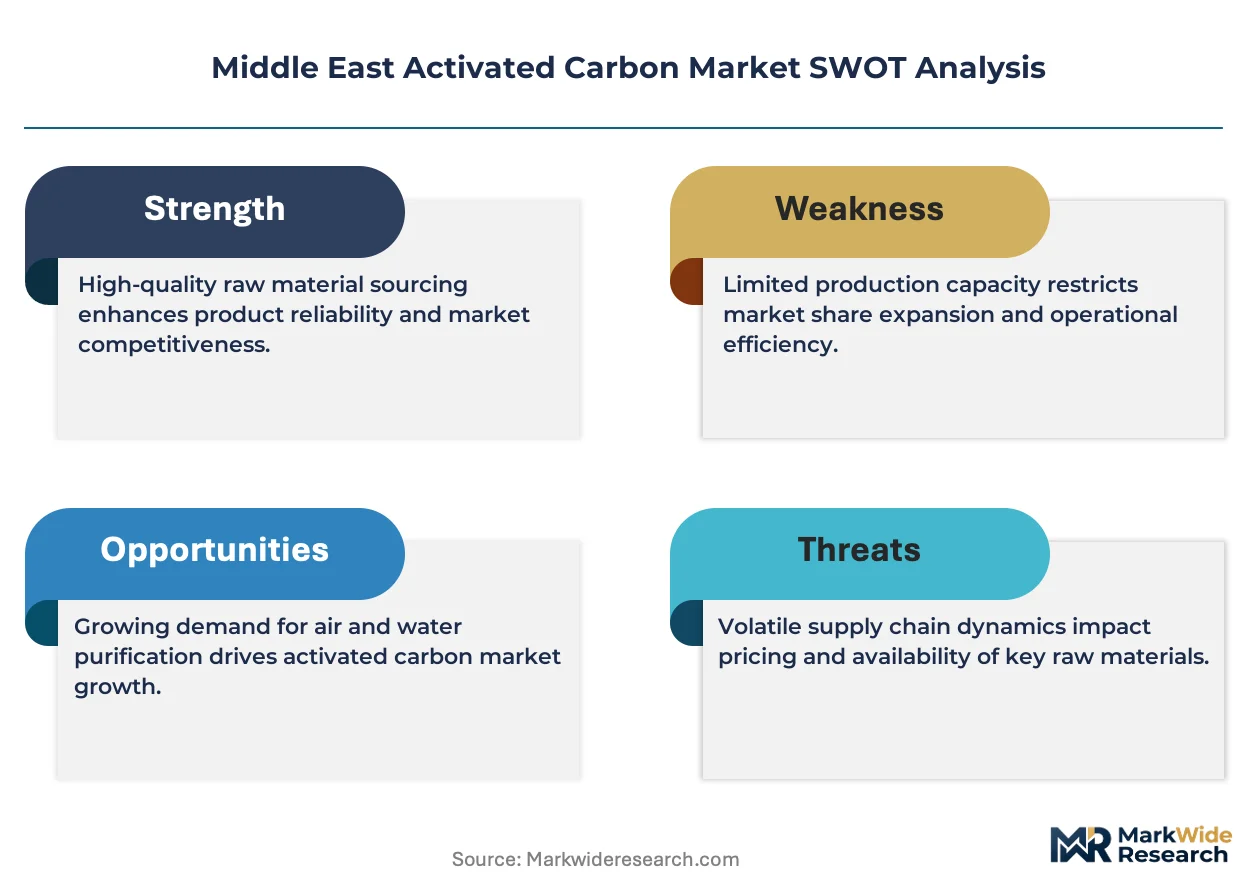
UAE wastewater reuse mandates is broadening the addressable market for activated carbon suppliers across the Gulf Cooperation Council. Chemviron leverages its regional distribution infrastructure to serve desalination plant retrofits in Abu Dhabi and Dubai. JACOBI CARBONS GROUP anchors supply for gold extraction operations in Saudi Arabia's mining belt. Albemarle Corporation specializes in impregnated carbon formulations for mercury control at coal-fired and oil-fired power stations.
Activated carbon comprises a highly porous form of carbon engineered through controlled thermal or chemical activation of carbonaceous feedstocks such as coconut shell, coal, or wood, yielding surface areas exceeding 500 square meters per gram for contaminant adsorption. Its primary industrial purpose centers on removing organic compounds, chlorine, heavy metals, and volatile organic compounds from liquid and gas streams across water treatment, air emission control, and chemical processing applications. Powdered activated carbon dominates municipal water treatment dosing systems due to lower capital requirements and operational flexibility, while granular activated carbon commands premium positioning in fixed-bed industrial filtration where regeneration cycles and longer service life determine total cost of ownership. Extruded activated carbon is gaining traction in air purification deployments across Saudi petrochemical complexes where low pressure drop and high mechanical strength prove critical for continuous operation.
Saudi Arabia's SFDA sets purity benchmarks for food-grade activated carbon used in edible oil and sugar refining across the Kingdom. The UAE's MOHAP enforces drinking water quality protocols that mandate activated carbon filtration for dissolved organic carbon removal in municipal distribution networks. Stakeholders must monitor how Gulf national oil companies integrate carbon capture with existing activated carbon infrastructure for combined pollutant management.
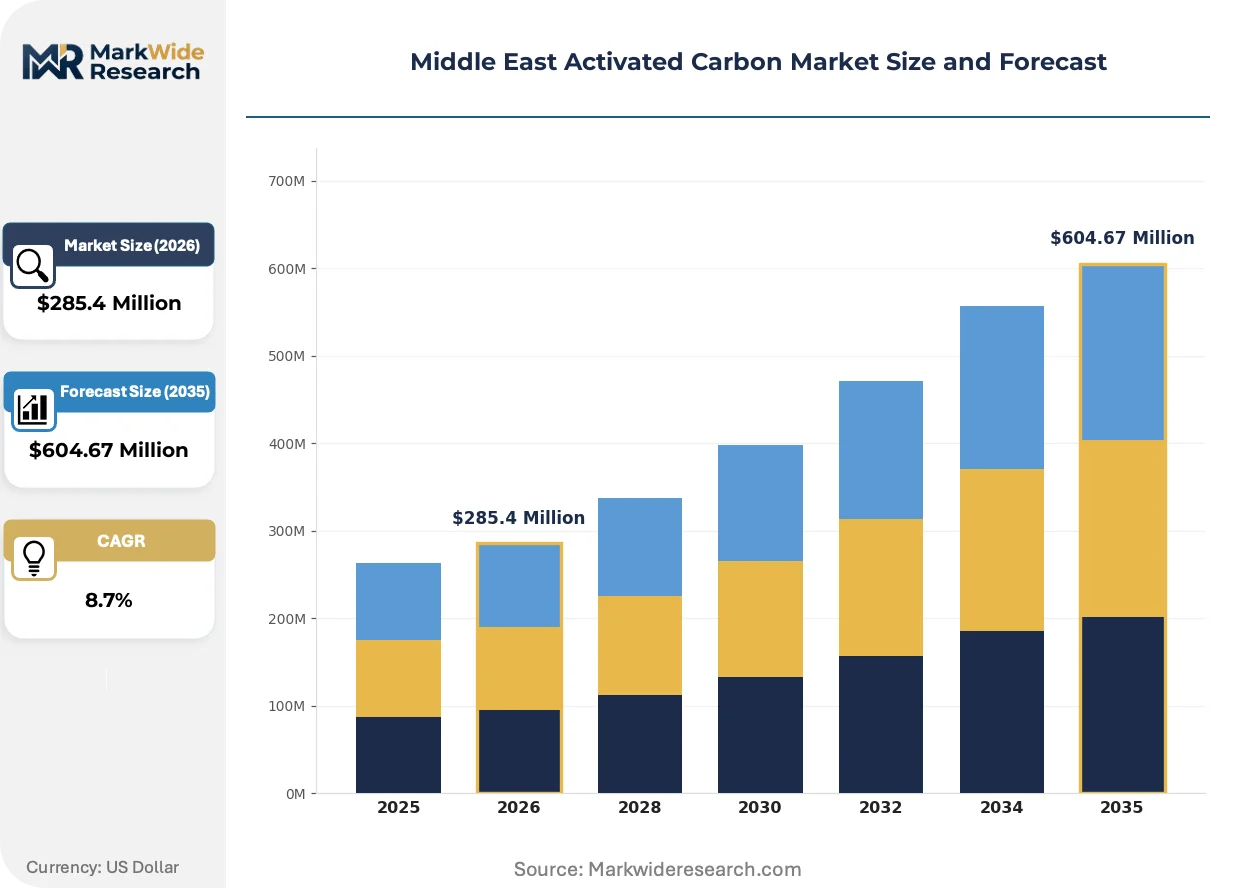
Market Dynamics
Desalination brine management mandates across Gulf Cooperation Council states are forcing activated carbon suppliers to engineer specialized adsorption systems for boron and heavy metal removal, compressing product development cycles and reshaping procurement specifications.
Growth Catalysts
- MOHAP potable water protocols:UAE drinking water quality mandates require dissolved organic carbon removal through activated carbon filtration, driving municipal utility procurement across Dubai and Abu Dhabi distribution networks.
- Petrochemical VOC capture:Saudi Arabia's industrial corridor cities require mercury removal and volatile organic compound capture at refining complexes, sustaining demand for impregnated carbon formulations.
- Gold extraction mining belt:Activated carbon suppliers serve precious metal recovery operations in Saudi Arabia's mining regions, where carbon-in-leach and carbon-in-pulp processes demand high-iodine coconut shell grades.
Market Restraints
- Coconut shell feedstock volatility:Raw material supply concentrates in Southeast Asian producer countries, exposing Middle East carbon manufacturers to shipping cost fluctuations and currency risk.
- SFDA food-grade certification complexity:Saudi Arabia's purity benchmarks for edible oil and sugar refining applications create extended approval timelines that delay product commercialization.
- Thermal regeneration energy intensity:Fixed-bed granular carbon systems require substantial natural gas inputs for reactivation, compressing margins when regional energy prices spike.
Strategic Opportunities
- Qatar industrial wastewater expansion:Petrochemical and fertilizer complexes in Ras Laffan Industrial City present underpenetrated demand for mercury and arsenic removal systems.
- Carbon capture convergence:Gulf national oil companies are evaluating activated carbon pretreatment integration with amine-based carbon capture infrastructure for combined pollutant management.
- Oman mining sector development:Copper and chromite extraction projects in the Sultanate's interior are creating new demand for precious metal recovery carbon grades.
Industry Challenges
- Specialized reactivation technician scarcity:Granular carbon regeneration facilities require skilled operators familiar with rotary kiln temperature profiling and iodine number restoration protocols.
- Desalination plant retrofit coordination:Integrating advanced adsorption systems with existing multi-stage flash and reverse osmosis infrastructure demands precise engineering to avoid pressure drop complications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Activated Carbon Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Activated Carbon, Granular Activated Carbon, Extruded Activated Carbon, Impregnated Activated Carbon Application: Water Treatment, Air Purification, Food & Beverage Processing, Gold Recovery End User: Industrial, Municipal, Residential, Pharmaceutical Technology: Chemical Activation, Physical Activation, Steam Activation, Oxygen Activation |
| Companies Covered | Chemviron, JACOBI CARBONS GROUP, Albemarle Corporation, Advanced Emissions Solutions, Inc., HAYCARB (PVT.) LTD, Cabot Corporation, PURAGEN ACTIVATED CARBONS, Veolia, Calgon Carbon Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Activated Carbon Market Strategic Shifts & Innovations
Extruded activated carbon formats are displacing traditional granular configurations in high-volume air treatment applications, while regulatory pressure on brine discharge quality accelerates specialty carbon formulation development across Gulf water utilities.
Magnetically separable activated carbon is integrating iron oxide nanoparticles into conventional carbon matrices, enabling rapid separation from treated water streams without filtration infrastructure. UAE desalination operators are piloting this technology for boron-selective removal, reducing footprint requirements by eliminating downstream clarification stages. The innovation is compressing capital expenditure thresholds for advanced adsorption retrofits.
SFDA food-grade purity benchmarks are tightening allowable heavy metal content in edible oil refining applications, forcing carbon suppliers to enhance acid-washing protocols and implement batch-level traceability systems. Saudi refineries are responding by consolidating supplier relationships with manufacturers demonstrating consistent pharmaceutical-grade production records.
Buyers across municipal water utilities are consolidating procurement through multi-year framework agreements with technical service bundling, displacing spot purchasing of commodity powdered carbon. Saudi Arabia's National Water Company and Kuwait's Ministry of Electricity and Water are leading this transition, prioritizing suppliers offering guaranteed regeneration services and performance-based dosing optimization.
Middle East Activated Carbon Market Segmentation
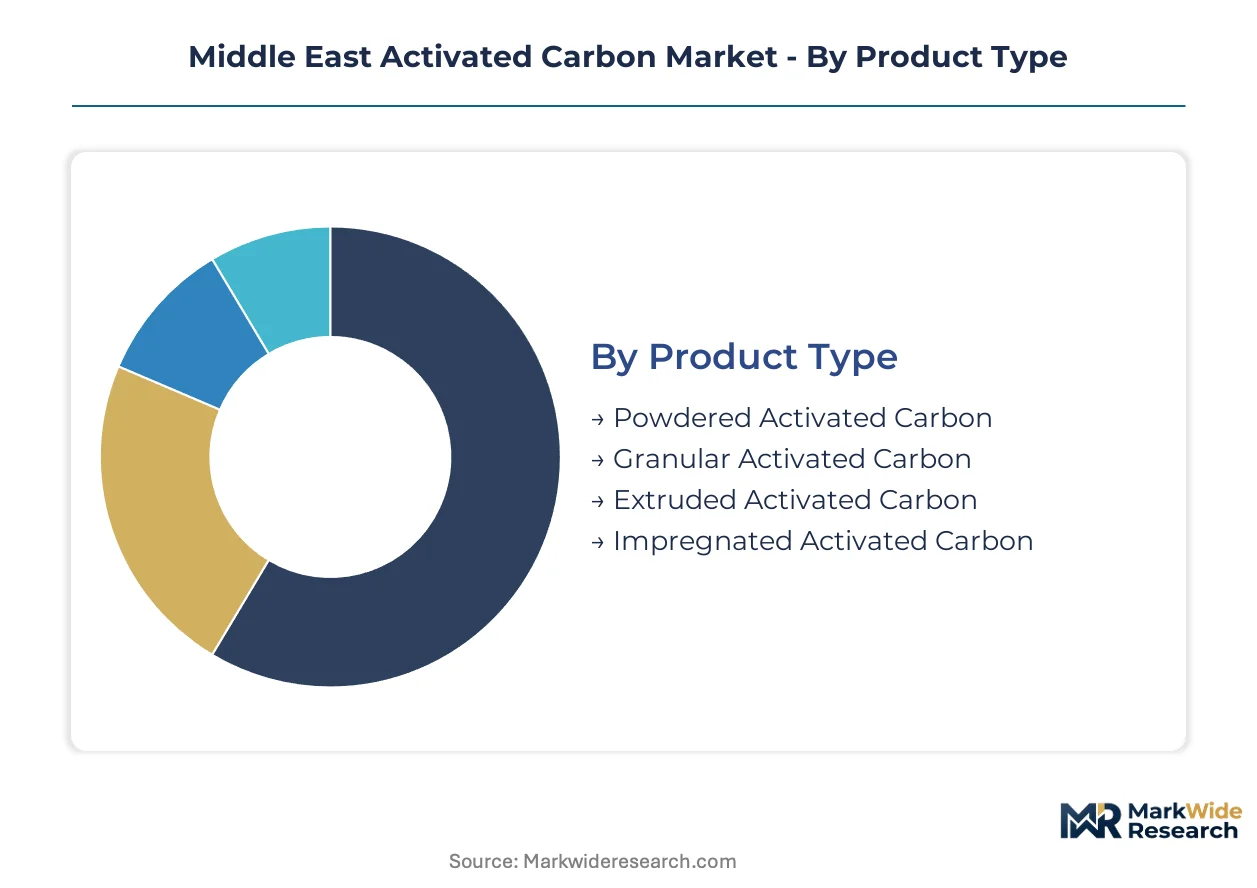
Activated carbon procurement patterns across the Middle East diverge sharply by physical form and end-use specifications. Product type selection directly determines reactivation economics and filtration performance in Gulf desalination and petrochemical applications.
Product Type:
Replacement cycles and upgrade pathways vary dramatically across physical formats, with fixed-bed systems demanding longer asset planning horizons than dosing-based alternatives.
- Granular Activated Carbon:Irregular particle sizing between 0.2 and 5 millimeters delivers optimal packed-bed hydraulics for continuous-flow municipal installations. Saudi Arabia's National Water Company specifies this grade for dissolved organic carbon removal across Riyadh and Jeddah distribution networks, where thermal reactivation infrastructure underpins total cost of ownership calculations.
- Powdered Activated Carbon:Finely milled particles below 0.18 millimeters enable rapid dispersion and high dosing flexibility for seasonal taste-and-odor events. Dubai's DEWA deploys PAC for emergency contaminant response at Al Taweelah desalination complex, though single-use disposal compresses margins versus regenerable alternatives.
- Extruded Activated Carbon:Cylindrical pellets engineered for low pressure drop and high mechanical strength serve continuous air treatment duties. Saudi petrochemical corridors in Jubail and Yanbu specify extruded formats for VOC capture systems where pneumatic conveying durability matters.
- Impregnated Activated Carbon:Surface-modified with sulfur, iodine, or metal oxide compounds for chemisorption of mercury, hydrogen sulfide, or radioactive iodine. Coal-fired power stations across the UAE's Al Dhafra region require impregnated grades for stack gas mercury control compliance.
Granular activated carbon sits at the top of the volume ranking, with extruded activated carbon climbing the fastest as petrochemical air treatment standards tighten.
Application:
Customer procurement sophistication stratifies by contamination complexity, with industrial buyers commanding technical service bundles unavailable to municipal counterparts.
- Water Treatment:Municipal desalination and wastewater reuse systems across the GCC deploy activated carbon for chlorine destruction, organic micropollutant removal, and biological growth suppression. MOHAP protocols in the UAE mandate carbon filtration for potable water distribution, creating recurring demand for high-iodine coconut shell grades.
- Air Purification:Petrochemical complexes, refineries, and power generation facilities utilize carbon adsorption for VOC recovery, odor control, and hazardous air pollutant capture. Saudi Aramco's Jazan refinery expansion incorporates activated carbon pretreatment for sulfur compound management.
- Food & Beverage Processing:Edible oil deodorization and sugar decolorization operations in Saudi Arabia's Central Province require SFDA-certified food-grade carbon with strict heavy metal limits.
- Gold Recovery:Carbon-in-leach and carbon-in-pulp circuits at Saudi Arabian mining operations demand specialized coconut shell grades with superior attrition resistance and gold loading capacity.
Water treatment commands the dominant revenue share, while gold recovery applications expand most quickly alongside Kingdom mining sector development.
End User:
Volume concentration and margin profiles invert across customer categories, with industrial buyers accepting premium pricing for technical performance guarantees.
- Industrial:Petrochemical, refining, and power generation facilities purchase granular and extruded formats under multi-year supply agreements with embedded reactivation services. SABIC affiliate complexes drive specification-setting for mercury removal and solvent recovery applications.
- Municipal:National water utilities procure powdered and granular grades through tender processes prioritizing lowest unit dosing cost. Saudi Arabia's National Water Company and Kuwait's Ministry of Electricity and Water dominate regional tender volume.
- Residential:Point-of-use filtration devices and refrigerator filters represent fragmented, price-sensitive demand concentrated in UAE and Saudi urban retail channels.
- Pharmaceutical:Active pharmaceutical ingredient purification and excipient processing require acid-washed, low-ash carbon grades with batch-level traceability documentation.
Industrial end users generate the highest absolute volume, with pharmaceutical applications gaining share fastest as regional manufacturing capacity expands.
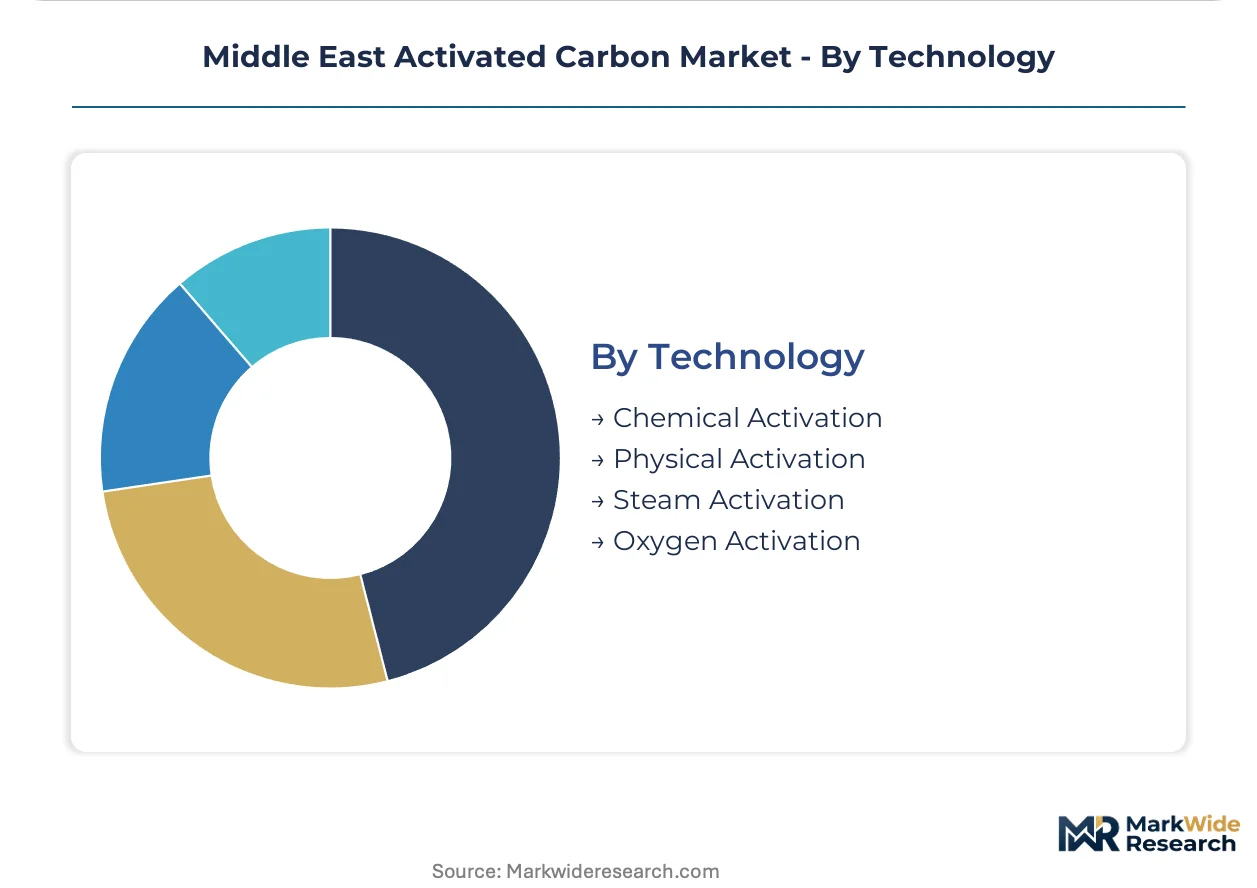
Technology:
Activation method selection determines pore size distribution, surface chemistry, and ultimate adsorption kinetics for target contaminant classes.
- Steam Activation:High-temperature water vapor partial oxidation of carbonized feedstock yields micropore-dominant structures optimal for small-molecule adsorption. Coconut shell steam activation dominates premium water treatment grade production for Gulf municipal utilities.
- Chemical Activation:Phosphoric acid or zinc chloride impregnation followed by controlled thermal processing creates mesopore-rich structures for large-molecule and color-body removal. Wood-based chemical activation serves food processing decolorization requirements.
- Physical Activation:Combined carbonization and controlled oxidation using carbon dioxide or air produces tailored surface area configurations. Coal-based physical activation supplies cost-competitive grades for industrial air treatment with less stringent purity requirements.
- Oxygen Activation:Surface oxidation protocols introduce acidic functional groups enhancing heavy metal cation adsorption capacity. Specialized boron removal applications in UAE desalination brine management pilot this emerging approach.
Steam activation retains the dominant production share, with oxygen activation demonstrating the steepest expansion trajectory as selective ion exchange requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East activated carbon industry traces its commercial scale to desalination infrastructure buildouts during the 1970s oil boom, when Gulf governments imported filtration media for municipal water security. Today national oil companies and mining enterprises anchor regional demand alongside expanding municipal utilities.
Saudi Arabia
Petrochemical complexes in Jubail and Yanbu drive granular carbon procurement for VOC capture and mercury removal systems. SFDA food-grade purity benchmarks govern edible oil refining applications across the Central Province. The Kingdom's mining belt in the west deploys coconut shell grades for gold extraction operations.
United Arab Emirates
MOHAP drinking water protocols mandate activated carbon filtration for dissolved organic carbon removal across Dubai and Abu Dhabi distribution networks. Desalination brine management regulations are accelerating specialty carbon adoption for boron and heavy metal removal. Chemviron maintains regional distribution infrastructure to serve plant retrofits.
Qatar
Ras Laffan Industrial City petrochemical and fertilizer complexes present concentrated demand for mercury and arsenic removal systems. The country's national water utility is expanding wastewater reuse capacity with advanced adsorption pretreatment. Industrial procurement favors multi-year technical service agreements over spot purchasing.
Kuwait
The Ministry of Electricity and Water dominates municipal tender volume for powdered and granular carbon grades. Thermal reactivation infrastructure constraints limit regenerable system adoption despite favorable lifecycle economics. Industrial air treatment applications remain underdeveloped relative to Gulf neighbors.
Oman
Copper and chromite extraction projects in the Sultanate's interior are creating new demand for precious metal recovery carbon grades. The national mining strategy is attracting specialty carbon suppliers to serve carbon-in-leach operations. Port infrastructure at Duqm is reducing import lead times for bulk filtration media.
Middle East Activated Carbon Market Key Industry Players
Premium-margin players sit above commodity-margin players across technical service bundling and reactivation capability. The vendor base spans multinational chemical conglomerates with integrated carbon divisions alongside specialized regional distributors. Three archetypes dominate: integrated carbon manufacturers with captive feedstock sourcing, regional distributors with technical service capabilities, and mining-focused specialists with precious metal recovery expertise. Competitive moves concentrate on multi-year framework agreements with embedded regeneration services and capacity expansion adjacent to Gulf industrial clusters.
Within the integrated manufacturer tier, Cabot Corporation and Calgon Carbon Corporation occupy positions as scale-driven suppliers with global production footprints. Among regional service providers, Chemviron exemplifies the technical bundling archetype through its distribution infrastructure serving UAE desalination retrofits. JACOBI CARBONS GROUP represents the mining specialization vector with supply relationships in Saudi Arabia's extraction belt.
| Leading Market Players |
|---|
| Chemviron |
| JACOBI CARBONS GROUP |
| Albemarle Corporation |
| Advanced Emissions Solutions, Inc. |
| HAYCARB (PVT.) LTD |
| Cabot Corporation |
| PURAGEN ACTIVATED CARBONS |
| Veolia |
| Calgon Carbon Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between SFDA food-grade carbon and commodity industrial grades manifests in both pricing premiums and supply chain complexity across the Middle East. Premium formulations command extended approval timelines and dedicated acid-washing protocols, while commodity grades flow through distributor networks with minimal technical service bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Middle East activated carbon procurement, with differentiation anchored in iodine number performance and reactivation service inclusion. SFDA-certified food-grade carbon carries substantial premiums over industrial air treatment grades due to batch-level traceability requirements. Pricing pressure stems from coconut shell feedstock volatility in Southeast Asian source markets, compressing margins for non-integrated suppliers. Municipal utilities exhibit highest price sensitivity through tender-based spot purchasing, while petrochemical buyers accept premium positioning for guaranteed regeneration cycles.
Supply Chain Analysis
Freight cost exposure dominates Middle East activated carbon economics, with container shipping rates from Sri Lankan and Indonesian processing centers feeding directly into landed cost calculations. Raw material sourcing concentrates in Sri Lanka, Indonesia, and the Philippines for coconut shell grades, while coal-based activation draws from Chinese and Australian bituminous feedstocks. Single-source vulnerability in Southeast Asian shell carbon production creates structural risk during monsoon disruptions. Distribution runs through Chemviron's Jebel Ali hub and direct mill relationships serving Saudi mining and UAE desalination clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East activated carbon market functions as a stable compounder, with desalination infrastructure mandates across Gulf Cooperation Council states ensuring recurring demand through municipal utility procurement cycles.
For Market Incumbents: Deploy captive reactivation infrastructure as the primary defensive lever against margin compression from energy price spikes. Expand technical service bundling into multi-year framework agreements with Saudi Arabia's National Water Company and Kuwait's Ministry of Electricity and Water to lock out spot-market competitors. Counter coconut shell feedstock volatility through backward integration into Southeast Asian carbonization partnerships or long-term offtake contracts with named suppliers. For New Entrants and Emerging Players: Magnetically separable carbon technology offers a technology-first wedge into UAE desalination brine management retrofits, where boron-selective removal commands premium positioning without requiring established regeneration service networks. Target Qatar's Ras Laffan Industrial City for mercury and arsenic removal systems, where petrochemical procurement favors technical performance over incumbent relationships. Lead with pilot-scale demonstrations at Duqm port facilities to establish Omani mining sector credibility before scaling. For Investors and Strategic Acquirers: Asymmetric upside sits with regional distributors possessing embedded technical service capabilities and existing reactivation infrastructure. Long-term viability rests on desalination capacity expansion and mining sector development across the GCC acquisition window. Target acquisition archetype: mid-scale distributors with Chemviron-like UAE footprint and untapped Saudi mining relationships. Watch for SFDA food-grade certification timeline acceleration as inflection signal for premium grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reactivation Infrastructure Expansion | Captive thermal regeneration capacity at Jubail Industrial City locks in SABIC affiliate contracts through lifecycle cost advantages. |
| Specialty Carbon Formulation Development | Boron-selective grades for UAE desalination brine management open premium pricing tiers beyond commodity water treatment. |
| Multi-Year Framework Agreements | Technical service bundling with Saudi National Water Company displaces spot purchasing and secures volume visibility. |
| Backward Integration into Feedstock | Direct carbonization partnerships in Sri Lanka and Indonesia hedge against shipping cost volatility and currency exposure. |
| Magnetic Separation Technology Licensing | Iron oxide nanoparticle integration enables rapid UAE pilot conversions and reduces competitor retrofit timelines. |
Research Approach
Coverage spans Saudi Arabia, UAE, Qatar, Kuwait, and Oman, with primary inputs from each market's desalination operators, petrochemical procurement leads, and mining sector technical directors. The study combines structured interviews with plant managers at National Water Company facilities, procurement officers at SABIC affiliate complexes, and gold extraction process engineers in the Kingdom's western mining belt. Secondary validation draws from GCC customs trade data, MOHAP drinking water quality filings, SFDA food-grade certification registries, and SEC disclosures from listed carbon manufacturers. Bottom-up demand modeling triangulates against top-down industrial capacity assessments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models granular, powdered, extruded, and impregnated carbon formats against water treatment, air purification, food processing, and gold recovery applications. Steam, chemical, physical, and oxygen activation technologies are disaggregated by pore structure performance. CAGRs derive from regression analysis of historical desalination capacity additions, petrochemical expansion pipelines, and mining sector investment flows. Industry-specific forecast inputs include MOHAP protocol implementation timelines and SFDA certification approval velocity.
The model holds under stable GCC desalination investment and continued petrochemical capacity expansion; deviation in coconut shell feedstock availability or shipping route disruptions would shift volume and value trajectories. Forecasts reflect assumptions regarding regulatory enforcement consistency and industrial energy pricing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Metal Heat Treatment Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
High Shear Mixer Market