
 Global Industrial Fastener Seal Market | 2026-2036
Global Industrial Fastener Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Fastener Seal Market Outlook
Advanced polymer formulation is tilting fastener seal architectures toward perfluoroelastomer and high-performance hydrogenated nitrile compounds that withstand extended temperature cycling. Parker Hannifin Corp. leverages its Fluorocarbon division to anchor aerospace hydraulic sealing contracts across North American defense programs. Freudenberg FST GmbH sustains manufacturing scale through captive rubber compounding facilities in Weinheim, Germany. ERIKS N.V. competes by controlling specialized distribution channels for MRO procurement across Benelux industrial clusters.
Industrial fastener seals are precision-engineered closure devices that integrate mechanical fastening with elastomeric or metallic sealing elements to prevent fluid or gas leakage under pressure, temperature, and vibration loads; typical specifications include Shore A hardness ratings from 70 to 90, tensile strength exceeding 15 MPa, and compliance with ASTM D2000 or SAE AMS standards for material classification. Sealing washers and O-rings dominate current procurement volumes due to standardized dimensions and broad interchangeability across automotive and construction equipment fleets. Gaskets represent the fastest-growing product category as turbocharged engines and hydrogen fuel systems demand multi-layer steel-elastomer laminates with compressed thickness recovery below 15 percent. Composite materials are displacing conventional nitrile rubber in aerospace applications where weight reduction targets intersect with FAA fire-resistance requirements.
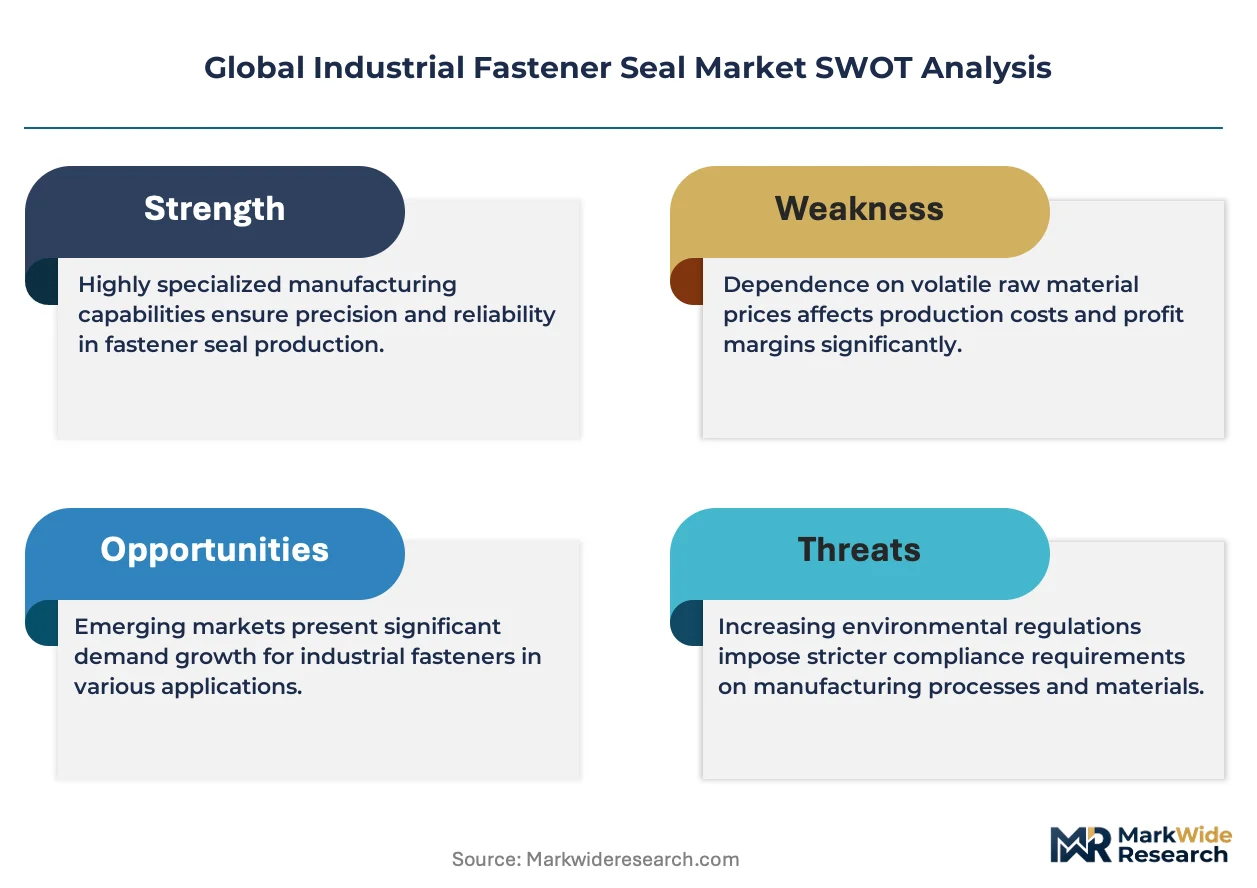
EPA emissions regulations and REACH substance restrictions are forcing reformulation of legacy seal compounds containing per- and polyfluoroalkyl substances, while ISO 3601 tolerancing standards govern O-ring interchangeability for multinational OEM supply chains. The EU F-Gas Regulation and California Air Resources Board protocols are converging on low-global-warming-potential sealing solutions for climate-controlled industrial equipment. Stakeholders must monitor polymer substitution timelines and pre-qualify alternative elastomers before existing compound grades lose regulatory authorization.
Market Dynamics
REACH substance restrictions and EPA emissions protocols are forcing compound reformulation across the fastener seal supply chain, compressing qualification timelines while aerospace OEMs accelerate procurement for hydrogen propulsion architectures.
Growth Catalysts
- Aerospace Propulsion Modernization:Next-generation hydrogen fuel systems and turbocharged engines demand multi-layer steel-elastomer laminates with compressed thickness recovery below 15 percent.
- REACH Compliance Deadlines:European compound manufacturers are pre-qualifying alternative elastomers before legacy fluorocarbon grades lose regulatory authorization.
- Stuttgart-Wolfsburg Corridor Concentration:Germany's automotive supplier cluster is consolidating procurement for sealing washers and O-rings across electrified powertrain programs.
Market Restraints
- Fluorocarbon Feedstock Volatility:Per- and polyfluoroalkyl substance phase-outs are disrupting raw material availability for high-temperature elastomer formulations.
- Captive Rubber Compounding Concentration:European supply depends heavily on Weinheim, Germany manufacturing scale for specialized hydrogenated nitrile production.
- ISO 3601 Tolerancing Rigidity:Multinational OEM supply chains face interchangeability constraints that limit rapid compound substitution.
Strategic Opportunities
- India PLI Scheme Alignment:Automotive component incentives are attracting fastener seal localization for domestic commercial vehicle and tractor manufacturing.
- Hydrogen Infrastructure Buildout:Fuel cell sealing applications represent white space for perfluoroelastomer architectures in high-pressure gas containment.
- Benelux MRO Channel Control:Specialized distribution networks for maintenance-repair-operations procurement remain underconsolidated across industrial clusters.
Industry Challenges
- FAA Fire-Resistance Certification Timelines:Composite material approvals for weight-reduction targets in aerospace applications extend qualification cycles by 18-24 months.
- Polymer Substitution Technical Debt:Legacy nitrile rubber system integration with new hydrogenated nitrile compounds creates performance validation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Fastener Seal Market |
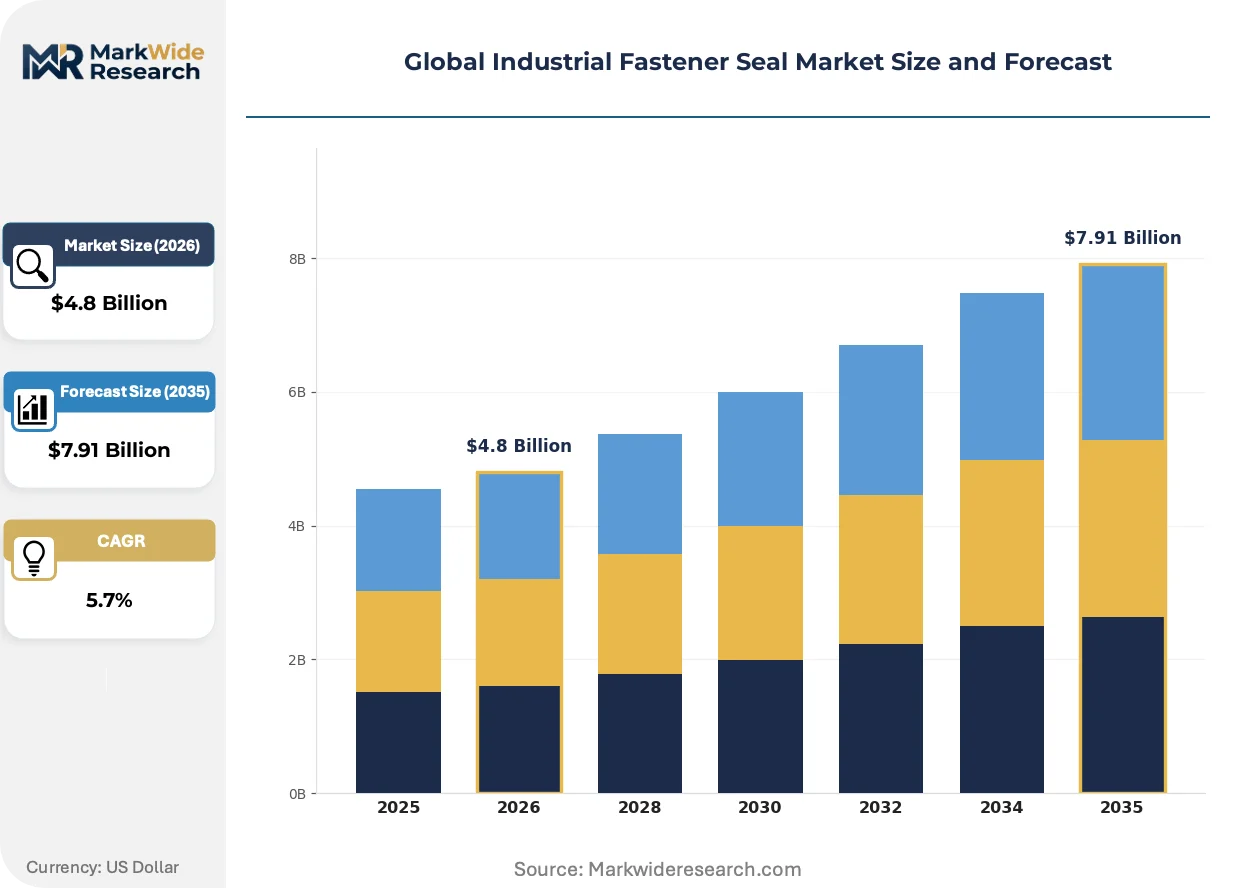
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealing Washers, O-Rings, Gaskets, Bolts Material: Rubber, Metal, Plastic, Composite Application: Aerospace, Automotive, Construction, Electronics End User: Manufacturers, OEMs, Maintenance Providers, Distributors |
| Companies Covered | AB SKF, EnPro Industries Inc., ERIKS N.V., Freudenberg FST GmbH, Parker Hannifin Corp., The Timken Co., All Seals Inc., LSP Holding LTD, Marco Rubber and Plastics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Fastener Seal Market Strategic Shifts
Material science advances are collapsing the boundary between metallic and elastomeric sealing elements, while regulatory convergence on low-global-warming-potential compounds accelerates formulation turnover.
Multi-layer steel-elastomer laminates are hybridizing traditional gasket architectures by embedding compressed thickness recovery mechanisms within rigid substrate geometries. Turbocharged engine manufacturers in Germany and Japan are adopting these structures for thermal cycling endurance above 200°C. The technology is hybridizing procurement specifications across automotive and aerospace verticals, compressing supplier qualification from material-grade to system-level validation.
California Air Resources Board protocols are converging with EU F-Gas Regulation on climate-controlled industrial equipment sealing standards. This regulatory alignment forces compound manufacturers to maintain parallel certification tracks for transatlantic market access. Hydrocarbon refrigerant systems and heat pump compressors represent the most affected product categories, with suppliers accelerating HFO-compatible elastomer development.
Buyer concentration among tier-one automotive suppliers is compressing switching cycles for fastener seal procurement. Long-term framework agreements with captive compounding facilities are displacing spot-market purchasing for high-performance grades. Stuttgart's automotive supplier corridor exhibits the most visible consolidation, with OEMs bundling hydraulic and pneumatic sealing contracts under single-source arrangements.
Global Industrial Fastener Seal Market Segmentation
Fastener seal procurement patterns diverge sharply across product architectures, material grades, and end-use specifications. Aerospace OEMs demand FAA-certified compounds while automotive suppliers prioritize ISO 3601 interchangeability for high-volume fleet maintenance.
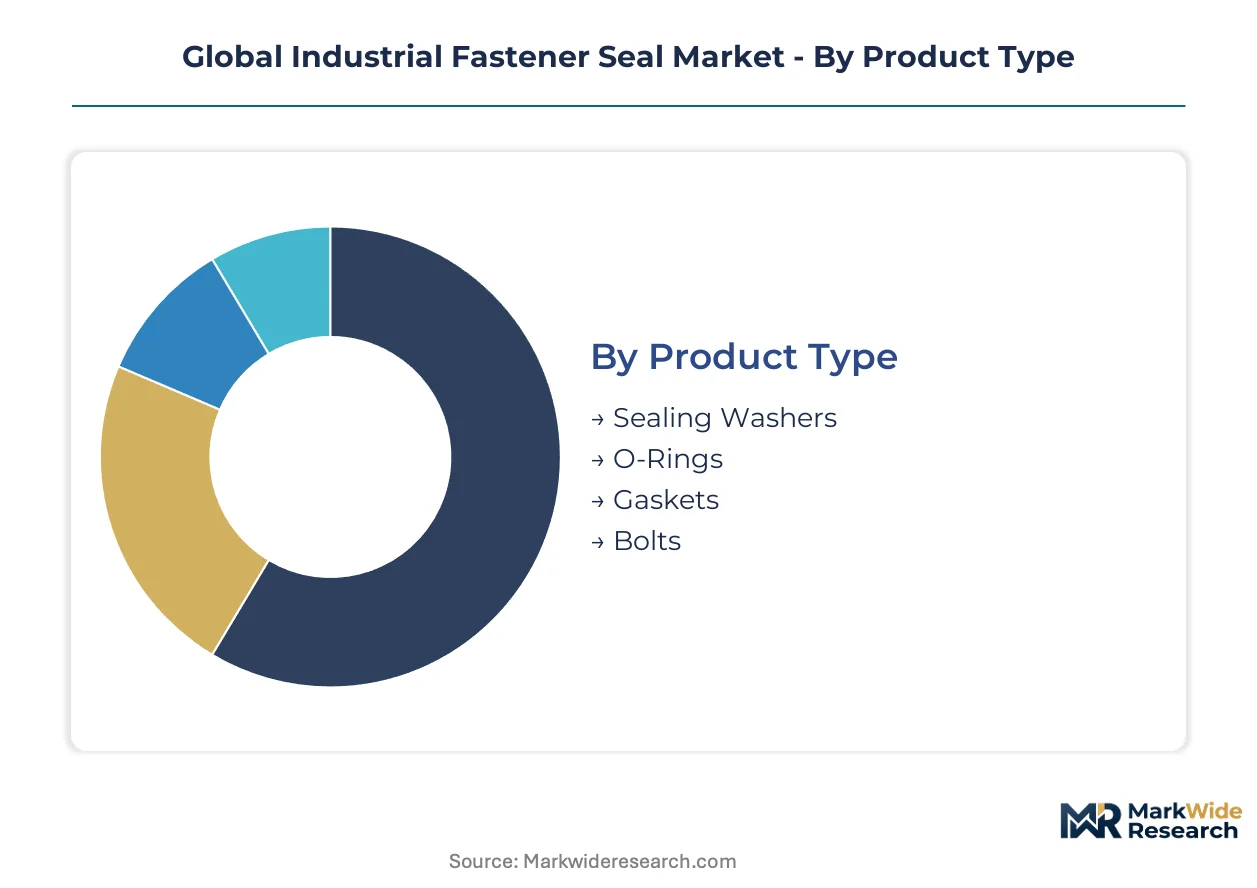
Product Type:
Use-case spectrum spans standardized closure devices for mass-market equipment through precision-engineered laminates for hydrogen containment systems.
- Sealing Washers:Metallic or elastomer-backed discs integrate mechanical load distribution with compression-set resistance for bolted joints. Stuttgart's automotive supplier corridor concentrates procurement for electrified powertrain programs requiring thermal cycling endurance above 150°C.
- O-Rings:Toroidal elastomer seals achieve fluid containment through radial compression in gland grooves; standardized AS568 and ISO 3601 dimensions dominate construction equipment and hydraulic machinery fleets across North American and Asian manufacturing bases.
- Gaskets:Multi-layer steel-elastomer laminates with compressed thickness recovery below 15 percent serve turbocharged engines and hydrogen fuel systems.
- Bolts:Threaded fasteners with integral sealing elements address high-pressure gas containment in specialized process equipment.
The dominant share belongs to Sealing Washers, while Gaskets is closing the gap fastest.
Material:
Cost tier stratification separates commodity compounds from perfluoroelastomer grades commanding 8-12x price multiples for aerospace applications.
- Rubber:Nitrile, hydrogenated nitrile, and fluorocarbon elastomers deliver Shore A hardness ratings from 70 to 90 with tensile strength exceeding 15 MPa; REACH compliance deadlines are forcing European compound manufacturers to pre-qualify alternatives before legacy fluorocarbon grades lose regulatory authorization.
- Metal:Stainless steel and alloy substrates provide rigid sealing surfaces with fire-resistance certification for FAA-regulated applications.
- Plastic:Thermoplastic elastomers and engineered polymers address chemical resistance requirements in semiconductor process equipment.
- Composite:Hybrid metal-elastomer architectures displace conventional nitrile rubber where weight reduction targets intersect with extended temperature cycling demands.
Rubber commands volume leadership, though Composite is expanding most quickly in aerospace procurement.
Application:
Customer type differentiation separates specification-driven OEM engineering from price-sensitive MRO procurement channels.
- Aerospace:Hydrogen propulsion architectures and next-generation fuel systems demand multi-layer laminates with compressed thickness recovery below 15 percent; FAA fire-resistance certification timelines extend qualification cycles by 18-24 months for composite material approvals.
- Automotive:Turbocharged engine manufacturers in Germany and Japan adopt steel-elastomer hybrid structures for thermal cycling endurance above 200°C.
- Construction:Heavy equipment fleets prioritize standardized O-ring interchangeability across hydraulic and pneumatic systems.
- Electronics:Miniaturized sealing elements address ingress protection ratings for climate-controlled industrial equipment under EU F-Gas Regulation and California Air Resources Board protocols.
Automotive retains the largest procurement volume, while Aerospace is gaining share fastest.
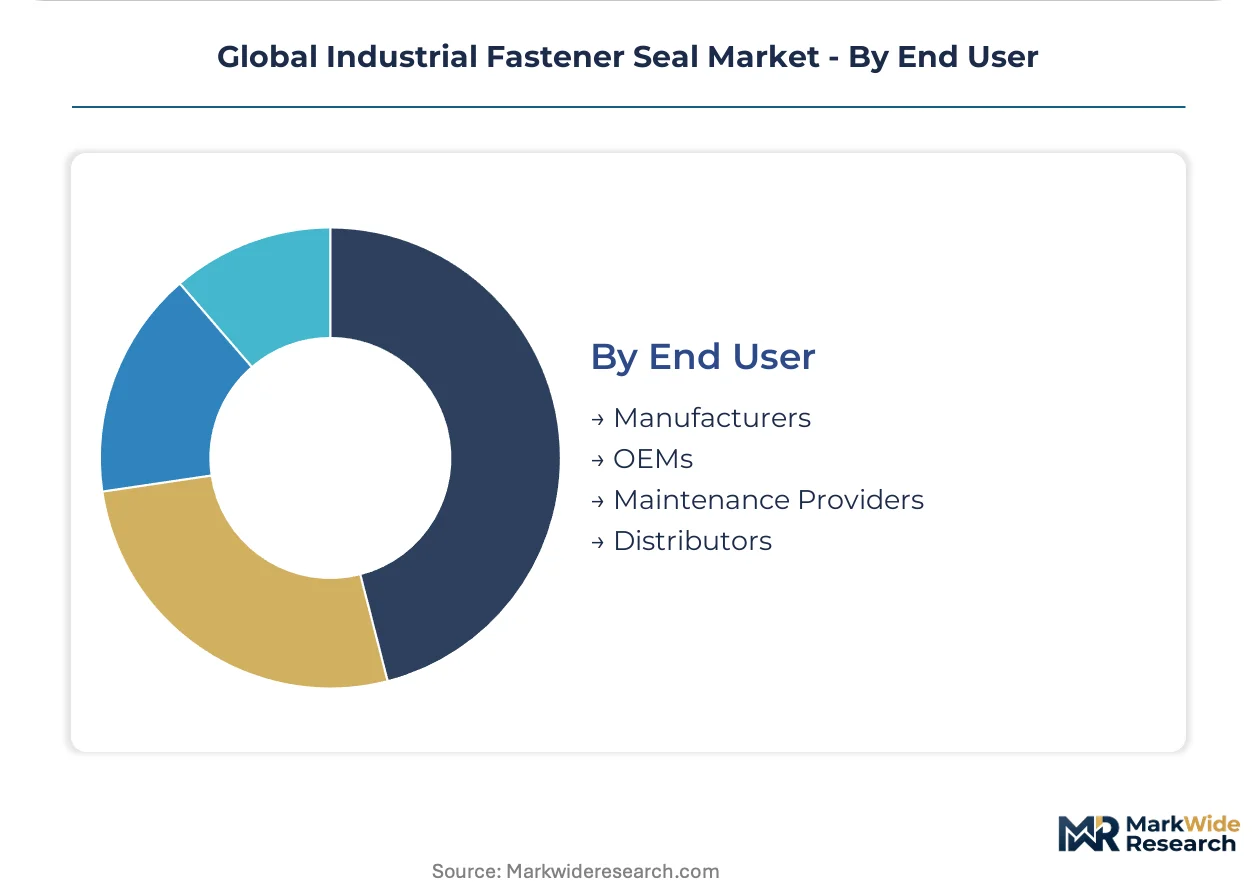
End User:
Supply concentration varies from captive rubber compounding facilities serving single-source framework agreements to fragmented distributor networks across Benelux industrial clusters.
- Manufacturers:Tier-one automotive suppliers in Germany's Stuttgart-Wolfsburg corridor consolidate procurement through long-term agreements with captive compounding facilities.
- OEMs:Original equipment manufacturers bundle hydraulic and pneumatic sealing contracts under single-source arrangements for electrified powertrain programs.
- Maintenance Providers:MRO procurement concentrates through specialized distribution channels controlled by ERIKS N.V. across Benelux industrial clusters.
- Distributors:Spot-market purchasing persists for commodity grades while high-performance compounds shift to direct mill relationships.
Manufacturers hold the dominant procurement position, while Maintenance Providers are consolidating fastest through channel specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fastener seal exports flow predominantly into French aerospace assembly plants and Italian automotive powertrain facilities, establishing a Rhine-Alpine manufacturing corridor that channels specialized elastomer compounds across Western European industrial networks.
United States
Defense procurement programs at Boeing and Lockheed Martin drive demand for FAA-certified composite seals in hydrogen propulsion architectures. EPA emissions protocols force compound reformulation timelines for fluorocarbon elastomers used in climate-controlled industrial equipment. Wichita's aviation manufacturing cluster concentrates MRO procurement through specialized distributor networks serving North American fleet maintenance.
Germany
Stuttgart-Wolfsburg automotive suppliers consolidate procurement for electrified powertrain sealing washers requiring thermal cycling endurance above 150°C. REACH substance restrictions compel pre-qualification of hydrogenated nitrile alternatives before legacy fluorocarbon grades lose authorization. Weinheim's captive rubber compounding facilities anchor European supply for high-performance elastomer production.
Japan
Turbocharged engine manufacturers adopt multi-layer steel-elastomer laminates with compressed thickness recovery below 15 percent for thermal endurance above 200°C. METI industrial standards govern material specifications for semiconductor process equipment sealing. Nagoya's automotive supplier corridor channels procurement through long-term framework agreements with domestic compound manufacturers.
China
Commercial vehicle and tractor manufacturing expansion under domestic stimulus programs attracts localization of sealing washer production for hydraulic systems. GB standards and MIIT regulations shape material certification requirements for industrial machinery exports. Yangtze River Delta industrial zones concentrate spot-market purchasing for commodity-grade O-rings serving construction equipment fleets.
India
Automotive component incentives under the PLI scheme draw fastener seal manufacturing investment for domestic commercial vehicle production. BIS standards govern interchangeability specifications for standardized O-ring dimensions in hydraulic machinery. Tamil Nadu's automotive supplier belt exhibits fastest procurement consolidation through direct mill relationships displacing distributor channels.
Global Industrial Fastener Seal Market Competitive Environment
On the supply side, the industry is tiered between integrated elastomer compounders with captive manufacturing and specialized distributors controlling MRO procurement channels. German and Japanese automotive corridors favor long-term framework agreements with single-source suppliers, while North American defense programs require FAA-certified compounders with established aerospace track records. Three archetypes dominate: integrated material-compounding manufacturers, specialized sealing distributors with regional channel control, and precision-engineering specialists serving specification-driven OEMs. Competitive moves center on backward integration into rubber compounding capacity and geographic expansion through distributor acquisition.
Among integrated compounders, Freudenberg FST GmbH exemplifies the captive manufacturing archetype through Weinheim-based production scale, while Parker Hannifin Corp. anchors the aerospace-defense procurement vector across North American programs. ERIKS N.V. occupies a distinct position controlling specialized distribution channels for MRO procurement across Benelux industrial clusters. These three represent the structural poles around which mid-cap specialists and regional fabricators organize competitive positioning.
| Leading Market Players |
|---|
| AB SKF |
| EnPro Industries Inc. |
| ERIKS N.V. |
| Freudenberg FST GmbH |
| Parker Hannifin Corp. |
| The Timken Co. |
| All Seals Inc. |
| LSP Holding LTD |
| Marco Rubber and Plastics LLC |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Weinheim's hydrogenated nitrile compounding facilities is tightening supplier discipline and amplifying pricing leverage for specialized elastomer grades across European automotive corridors.
Pricing Analysis
Next-generation perfluoroelastomer compounds command 8-12x multiples over legacy nitrile rubber formulations, while current-generation hydrogenated nitrile occupies a mid-tier position. Three-tier pricing structure across premium aerospace-certified, standard automotive-grade, and economy construction-equipment tiers separates procurement contracts by certification burden and volume scale. Cost compression in commodity O-ring segments is intensifying because spot-market purchasing persists for standardized AS568 dimensions. Tier-one automotive suppliers in Stuttgart exhibit the lowest price sensitivity due to long-term framework agreements, while construction equipment fleet operators in North American distributor channels face acute margin pressure.
Supply Chain Analysis
Export control regimes restricting fluoropolymer precursor flows are forcing compound manufacturers to qualify alternative feedstock pathways for high-temperature elastomer production. Geographic supply concentration centers on Germany for captive rubber compounding, Japan for precision steel-elastomer laminates, and China for commodity sealing washer fabrication. Raw material dependencies draw from fluorocarbon elastomer feedstocks, specialty steel substrates, and hydrogenated nitrile polymer resins. Single-source vulnerability runs through Weinheim's concentrated production scale for aerospace-grade compounds. Distribution runs through specialized MRO channels controlled by Benelux industrial cluster distributors alongside direct mill relationships for high-performance automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against polymer substitution threats as REACH substance restrictions and EPA emissions protocols accelerate compound reformulation timelines.
For Market Incumbents: Harden regulatory compliance capabilities by pre-qualifying alternative elastomer grades before legacy fluorocarbon authorizations expire. Deepen backward integration into rubber compounding capacity in Germany's automotive corridor to secure captive supply of hydrogenated nitrile for electrified powertrain programs. Lock in long-term framework agreements with Stuttgart-Wolfsburg OEMs to displace spot-market competitors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-aligned automotive component manufacturing by localizing sealing washer production for commercial vehicle and tractor OEMs. Target hydrogen infrastructure buildout applications where perfluoroelastomer architectures for high-pressure gas containment remain underpenetrated. Pursue direct mill relationships with Tamil Nadu automotive suppliers to bypass consolidated distributor channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized MRO distributors controlling Benelux industrial cluster procurement channels. Long-term viability over the next decade rests on exposure to aerospace hydrogen propulsion architectures and automotive electrification sealing demand. Monitor FAA fire-resistance certification timeline acceleration as an inflection signal for composite material approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive production of hydrogenated nitrile in Weinheim secures supply continuity for Stuttgart OEM contracts. |
| Long-term Supply Agreement | Framework contracts with tier-one automotive suppliers compress switching cycles and displace spot-market purchasing. |
| Regulatory Pre-qualification Investment | Alternative elastomer validation before REACH fluorocarbon deadlines preserves aerospace and automotive authorization. |
| Geographic Manufacturing Footprint | Localization in India's PLI scheme corridors captures commercial vehicle and tractor demand growth. |
| Joint Venture | Partnerships with hydrogen infrastructure developers open white-space for perfluoroelastomer high-pressure sealing applications. |
Study Parameters
Initial hypotheses were tested against primary input from OEM procurement directors, tier-one automotive supplier engineering leads, MRO channel managers, and rubber compounding technical directors and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance directors at aerospace fleet operators and aftermarket service heads at construction equipment dealers. Secondary sources included customs and trade data for elastomer compound flows, SEC 10-K filings for integrated seal manufacturers, and ASTM D2000 material specification databases. Bottom-up volume modeling across product types and materials was triangulated against top-down demand aggregation from end-use industries.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material grade tier, end-use industry vertical, and regional manufacturing cluster concentration. CAGRs were derived from installed base expansion rates, content-per-vehicle trajectories in automotive applications, and fleet renewal cycles in aerospace MRO. Industry-specific forecast inputs incorporated REACH substance restriction phase-out schedules and FAA composite material certification pipeline data.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, commercial aircraft delivery rates, or construction equipment capital expenditure would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory authorization timelines and polymer substitution technical readiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Brushes Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Magnet Rings Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Foam Insulation Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Catalyst Bins Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Precipitated Silica Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Noise Reduction Plastic Gear Market